
 Flue Gas Desulfurization Systems Market | 2026-2036
Flue Gas Desulfurization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flue Gas Desulfurization Systems Market Intelligence
Aftermarket service revenue is narrowing toward predictive maintenance contracts and reagent supply agreements as original equipment margins compress. Mitsubishi Heavy Industries leverages its installed base across Japanese and Southeast Asian power plants to sustain long-term service income. Babcock & Wilcox Enterprises anchors North American retrofit demand through specialized boiler integration capabilities. Siemens Energy AG competes on digital twin integration for scrubber optimization, differentiating its offering from commodity hardware suppliers.
Flue gas desulfurization systems chemically remove sulfur dioxide from exhaust streams of fossil-fuel combustion and industrial processes, typically achieving removal efficiencies above 95 percent through limestone-gypsum wet scrubbing or dry sorbent injection at operating temperatures between 120 and 180 degrees Celsius. Wet scrubber installations dominate current procurement for power generation end users due to proven reliability and byproduct gypsum recovery economics, while semi-dry scrubber technology is gaining traction in cement production where water availability constraints limit full wet systems. Retrofit installation demand outpaces new build activity across mature markets as existing coal and industrial boiler fleets face accelerated compliance deadlines.
The US EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act that mandate continuous SO2 monitoring and minimum removal efficiencies for utility boilers, while China's MEE implements ultra-low emission thresholds requiring wet scrubber upgrades at provincial power clusters. India's CEA has notified revised emission norms for thermal power plants with compliance timelines that drive sorbent injection and wet scrubber procurement across the National Capital Region and western coal belt. Stakeholders must monitor regulatory enforcement consistency in emerging economies where delayed implementation creates demand volatility and technology selection uncertainty.
Market Dynamics
Retrofit installation demand for wet scrubber systems is compressing project timelines as coal-fired utilities face accelerated compliance deadlines across multiple jurisdictions simultaneously.
Growth Catalysts
- China's MEE ultra-low emission standards:Mandated wet scrubber upgrades at provincial power clusters in Shandong and Shanxi provinces drive concentrated procurement demand from aging coal boiler fleets.
- Limestone-gypsum wet scrubbing:Proven removal efficiencies above 95 percent and viable byproduct recovery economics sustain technology preference among power generation end users.
- India's CEA revised emission norms:Compliance timelines for thermal power plants accelerate sorbent injection and wet scrubber deployment across the National Capital Region and western coal belt.
Market Restraints
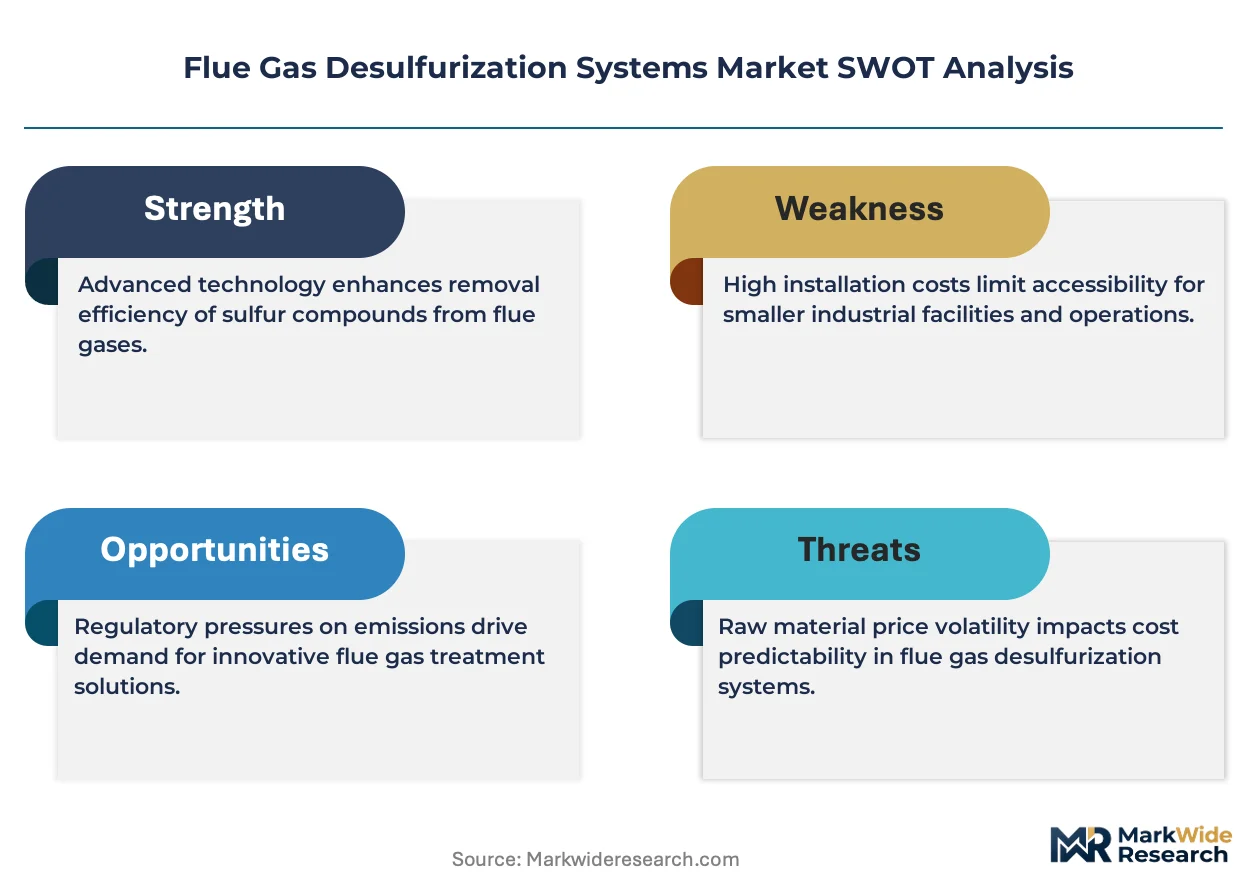
- Limestone reagent price volatility:Input cost fluctuations for calcium carbonate sorbents compress operating margins for continuous scrubber operations.
- Water availability constraints:Full wet scrubber systems face technical limitation in arid regions and cement production facilities where semi-dry alternatives dominate.
- Delayed regulatory enforcement:Inconsistent implementation timelines in emerging economies create demand volatility and technology selection uncertainty for project developers.
Strategic Opportunities
- Digital twin integration:Convergence of scrubber optimization software with predictive maintenance platforms creates differentiation from commodity hardware suppliers.
- Aftermarket service unbundling:Predictive maintenance contracts and reagent supply agreements offer recurring revenue streams as original equipment margins compress.
- Semi-dry scrubber adoption:Water-scarce cement production facilities in the Middle East and North Africa present underpenetrated application expansion potential.
Industry Challenges
- Specialized welding and corrosion engineering talent:Scarcity of technicians qualified for alloy scrubber vessel fabrication and weld inspection extends project commissioning timelines.
- Legacy boiler integration complexity:Retrofit projects require customized ductwork modifications and fan capacity upgrades that escalate engineering change orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flue Gas Desulfurization Systems Market |
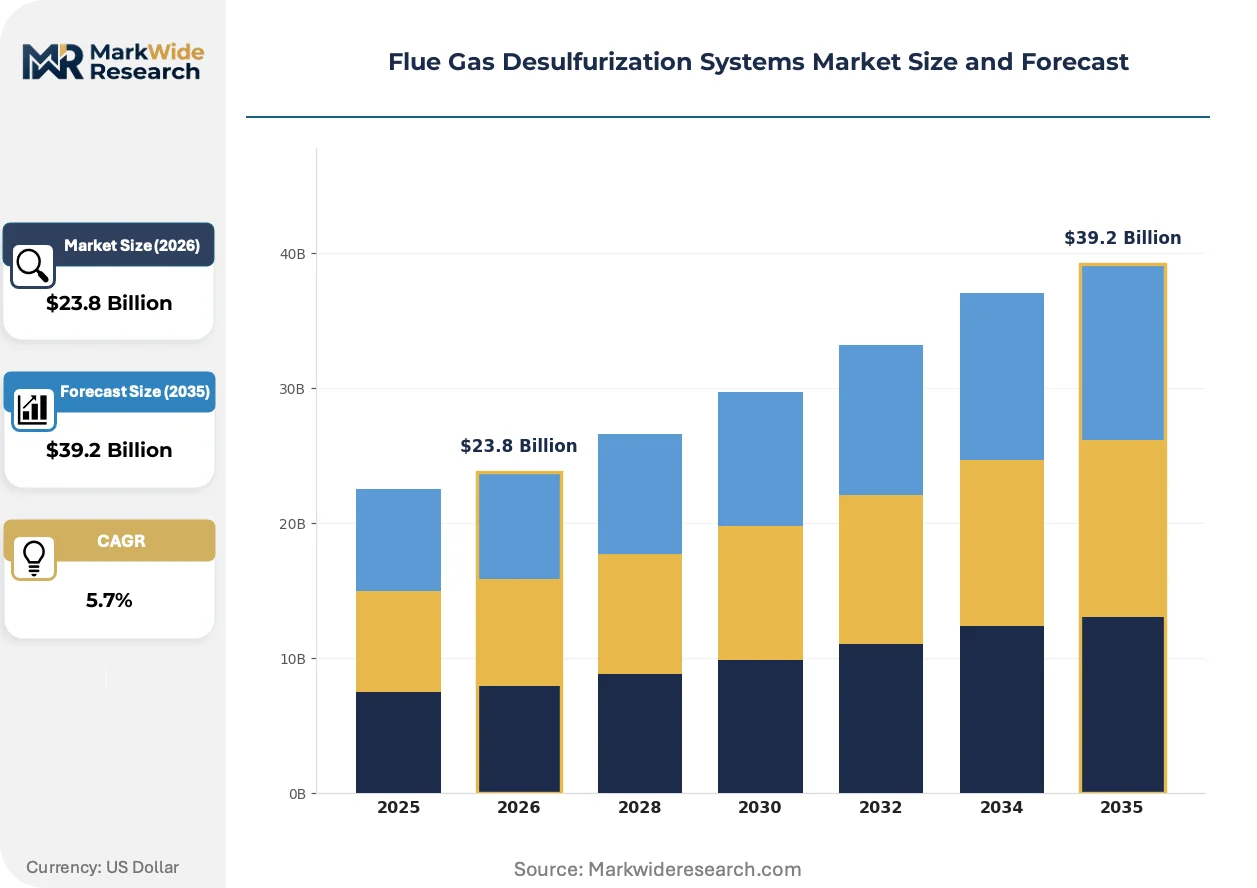
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Wet Scrubber, Dry Scrubber, Semi-Dry Scrubber, Sorbent Injection Installation Type: New Installation, Retrofit Installation, Modular Installation, Integrated Installation End User: Power Generation, Cement Production, Chemical Processing, Paper Manufacturing Technology: Alkali Scrubbing, Calcium Sorbent, Magnesium Oxide, Amine Gas Treatment |
| Companies Covered | Mitsubishi Heavy Industries, GE Vernova, Babcock & Wilcox Enterprises, ANDRITZ AG, Siemens Energy AG, Valmet Oyj, GEA Group Aktiengesellschaft, Thermax Ltd, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flue Gas Desulfurization Systems Market Strategic Shifts & Innovations
Digital instrumentation and advanced process control are transforming scrubber operations from reactive compliance tools into optimized industrial assets with measurable performance transparency.
Artificial intelligence-based flue gas monitoring is virtualizing traditional manual stack testing and laboratory analysis workflows. Cement producers and power utilities are adopting continuous emissions monitoring systems with machine learning anomaly detection at accelerating rates. This technology is virtualizing the role of third-party environmental compliance auditors and compressing reporting latency from weeks to minutes.
The US EPA Maximum Achievable Control Technology standards under the Clean Air Act mandate continuous SO2 monitoring and minimum removal efficiencies for utility boilers. Industrial operators must install and maintain certified continuous emissions monitoring systems with documented quality assurance protocols. Coal-dependent utilities in the Ohio River Valley and Southwest are responding by consolidating scrubber maintenance contracts with specialized service providers.
Power generation procurement departments are unbundling long-term service agreements into discrete predictive maintenance and reagent supply contracts. This behavior shift disrupts traditional bundled OEM service models and transfers operational risk to specialized chemical suppliers. The pattern is most visible across Japanese and Southeast Asian power plant fleets where Mitsubishi Heavy Industries leverages installed base relationships to sustain aftermarket revenue.
Flue Gas Desulfurization Systems Market Segmentation
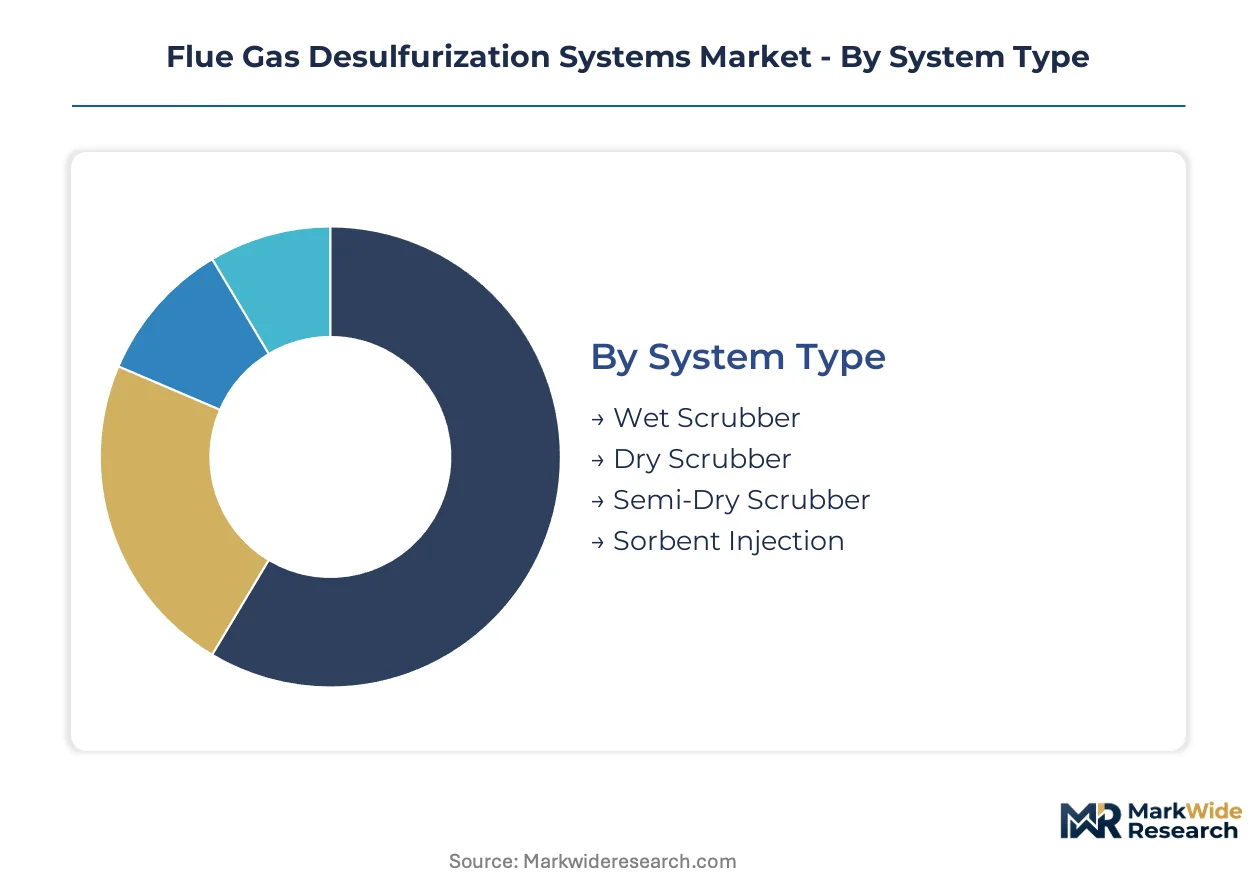
Segmentation in flue gas desulfurization systems reveals how technology maturity, regulatory pressure, and industrial application diversity create distinct procurement patterns across the value chain. Understanding these divides helps suppliers align engineering resources with the specific compliance timelines and operational constraints driving each category.
System Type:
Mature wet scrubber technology dominates procurement volumes while emerging semi-dry systems capture water-constrained applications.
- Wet Scrubber:Limestone-gypsum systems achieve removal efficiencies above 95 percent through aqueous chemical absorption at 120-180 degrees Celsius. Power generation utilities across China's Shandong and Shanxi provinces prioritize these installations for ultra-low emission compliance at aging coal clusters.
- Semi-Dry Scrubber:Spray-dryer absorbers inject lime slurry into hot flue gas, producing a dry waste product without wastewater discharge. Cement producers in water-scarce regions of the Middle East and North Africa are expanding procurement where full wet systems face technical limitations.
- Dry Scrubber:Dry sorbent injection systems deploy powdered activated carbon or hydrated lime directly into ductwork. Chemical processing facilities with intermittent SO2 loads favor these for lower capital intensity.
- Sorbent Injection:In-duct injection of sodium-based or calcium-based reagents offers rapid deployment for smaller boilers. India's western coal belt utilities deploy these for interim compliance ahead of full scrubber retrofits.
Wet scrubber systems handle the majority of throughput; semi-dry scrubber technology is expanding most quickly in water-constrained industrial corridors.
Installation Type:
Cost tier stratification separates turnkey new builds from engineered retrofits with complex legacy integration requirements.
- Retrofit Installation:Customized ductwork modifications and fan capacity upgrades integrate scrubber vessels with existing boiler architectures. North American utilities in the Ohio River Valley concentrate procurement here as EPA compliance deadlines accelerate.
- New Installation:Greenfield projects specify optimized scrubber-boiler configurations from initial design. Greenfield coal capacity in Southeast Asia drives concentrated demand for integrated system packages.
- Modular Installation:Pre-fabricated skid-mounted scrubber units reduce field construction duration. Smaller industrial boilers in India's National Capital Region adopt these for rapid deployment timelines.
- Integrated Installation:Combined procurement of scrubber systems with particulate control and NOx reduction equipment. Japanese power utilities favor this approach for streamlined vendor accountability.
Retrofit installation commands the dominant project pipeline; modular systems are climbing the fastest as compressed compliance windows favor rapid deployment.
End User:
Application diversity spans continuous-load power generation to batch-process industrial operations with variable emission profiles.
- Power Generation:Coal-fired and oil-fired utility boilers operate continuous flue gas streams requiring 95+ percent SO2 removal. Asia-Pacific utilities anchor procurement demand as regional emission standards tighten.
- Cement Production:Kiln exhaust gases contain SO2 from sulfur-bearing raw materials and fuels. Facilities across water-scarce regions prioritize semi-dry scrubber adoption over wet systems.
- Chemical Processing:Sulfuric acid plants and refinery operations generate concentrated SO2 streams amenable to recovery rather than disposal. Amine-based treatment systems find application here for acid regeneration.
- Paper Manufacturing:Recovery boiler exhaust contains dilute SO2 alongside particulate and reduced sulfur compounds. Kraft mill operators deploy alkali scrubbing to capture sulfur for pulping chemical recycle.
Power generation handles the majority of installed capacity; cement production is gaining share fastest as clinker capacity expansion intersects with tightening emission norms.
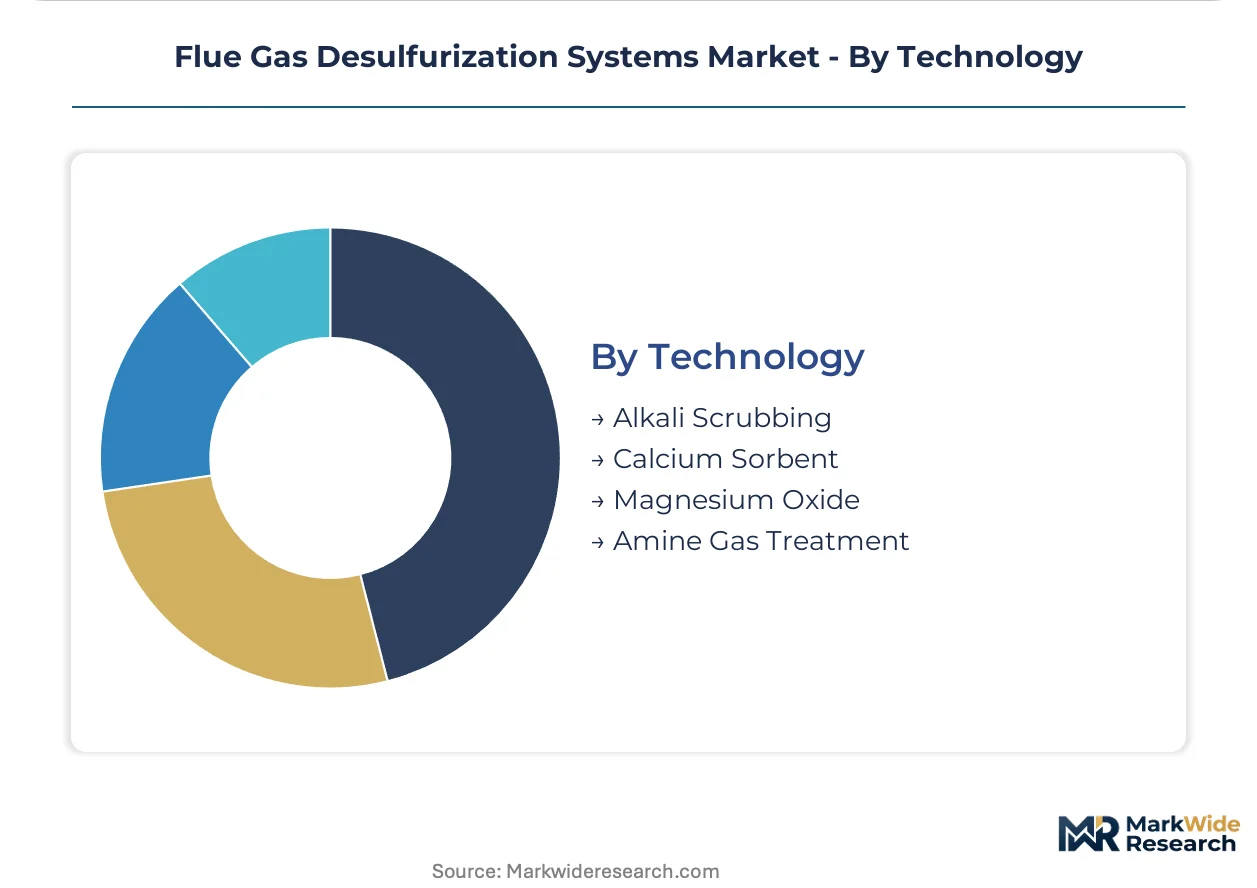
Technology:
Volume concentration sits with calcium-based sorbents while margin opportunity concentrates in specialized amine treatment for chemical recovery applications.
- Calcium Sorbent:Limestone and lime-based reagents react with SO2 to produce calcium sulfite or sulfate byproducts. Gypsum recovery economics sustain preference across Chinese and Indian utility procurement.
- Alkali Scrubbing:Sodium hydroxide or sodium carbonate solutions achieve high removal efficiency without solid byproduct handling. Paper manufacturing recovery boilers deploy these for integrated sulfur cycle closure.
- Magnesium Oxide:Regenerable scrubbing produces concentrated SO2 for sulfuric acid manufacture. Chemical processing facilities with acid product demand favor this technology for operational cost recovery.
- Amine Gas Treatment:Selective absorption enables SO2 concentration for subsequent conversion or sequestration. Refinery and petrochemical operators pilot these systems for carbon capture co-benefits.
Calcium sorbent technology anchors the majority of operating capacity; amine gas treatment is expanding most quickly in chemical processing applications seeking recovery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. China's power utilities prioritize wet scrubber retrofits for ultra-low emission compliance, while water-scarce cement producers in the Middle East gravitate toward semi-dry alternatives. India's compressed compliance timelines favor modular rapid-deployment systems over engineered turnkey installations.
China
Coal-fired capacity concentration in Shandong and Shanxi provinces drives concentrated wet scrubber procurement demand. The MEE mandates ultra-low emission standards for industrial boilers, accelerating retrofit timelines at aging provincial power clusters. Utilities in these provinces face 2025-2027 compliance windows that compress vendor selection and commissioning schedules.
United States
Ohio River Valley utilities consolidate scrubber maintenance contracts with specialized service providers under EPA Maximum Achievable Control Technology standards. The Clean Air Act mandates continuous SO2 monitoring with documented quality assurance protocols. Coal-dependent operators in the Southwest respond by unbundling long-term service agreements into discrete predictive maintenance and reagent supply contracts.
India
Thermal power plants across the National Capital Region and western coal belt deploy sorbent injection systems for interim compliance ahead of full scrubber retrofits. The CEA has notified revised emission norms with specific compliance timelines. Smaller industrial boilers in Delhi-NCR adopt modular skid-mounted scrubber units for rapid deployment against compressed regulatory deadlines.
Japan
Power utilities favor integrated procurement of scrubber systems with particulate control and NOx reduction equipment for streamlined vendor accountability. METI oversees industrial emission standards that sustain technology upgrade cycles. Mitsubishi Heavy Industries leverages installed base relationships across Japanese and Southeast Asian power plant fleets to sustain aftermarket service revenue.
Germany
Chemical processing facilities with sulfuric acid production deploy amine-based treatment systems for acid regeneration and operational cost recovery. The EU Industrial Emissions Directive enforces best available technique requirements across large combustion plants. Industrial operators in the Rhine-Ruhr chemical corridor pilot regenerable scrubbing technologies for concentrated SO2 stream handling.
Flue Gas Desulfurization Systems Market Key Industry Players
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies across three tiers: integrated technology providers with digital twin capabilities, boiler specialists with legacy integration expertise, and regional fabricators serving modular installation demand. Consolidation pressure intensifies as original equipment margins compress and aftermarket service contracts become the primary revenue anchor. Dominant competitive moves include predictive maintenance platform development and reagent supply chain integration.
Among diversified Japanese industrial groups, Mitsubishi Heavy Industries and Kawasaki Heavy Industries occupy positions within the integrated technology tier, leveraging power plant installed bases across Asia-Pacific markets. Babcock & Wilcox Enterprises exemplifies the boiler-specialist archetype with concentrated North American retrofit demand. Siemens Energy AG represents the digital convergence vector, competing on scrubber optimization software rather than commodity hardware supply.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| GE Vernova |
| Babcock & Wilcox Enterprises |
| ANDRITZ AG |
| Siemens Energy AG |
| Valmet Oyj |
| GEA Group Aktiengesellschaft |
| Thermax Ltd |
| Kawasaki Heavy Industries |
| Others |
Cost & Logistics Intelligence
Limestone reagent price volatility compresses operating margins across continuous scrubber operations while simultaneously determining the spread between premium turnkey installations and economy modular systems. This input cost instability forces procurement departments toward long-term offtake agreements that reshape supplier relationships and inventory strategies across the value chain.
Pricing Analysis
Long-term offtake contracts dominate procurement for calcium carbonate sorbents, insulating continuous operations from spot market swings. Three-tier pricing structure across premium, standard, and economy levels separates integrated digital-twin systems from commodity hardware and skid-mounted modular units. Cost compression in the economy tier is intensifying because regional fabricators compete aggressively for India's compressed compliance deadlines. Cement producers in water-scarce regions exhibit highest price sensitivity due to intermittent utilization rates, while Chinese provincial utilities under MEE mandates show lowest sensitivity given compliance-driven procurement urgency.
Supply Chain Analysis
Contract manufacturing concentration for alloy scrubber vessels sits with specialized fabrication shops in Germany, Japan, and South Korea, where corrosion engineering expertise anchors production. Raw material flows draw from limestone quarries in Vietnam and India, nickel-alloy plate from European mills, and specialized welding consumables from Japanese suppliers. Single-source vulnerability concentrates in high-nickel alloy supply for absorber vessel fabrication, where qualified foundry capacity remains constrained. Distribution runs through EPC contractors and specialized environmental engineering firms that bundle scrubber procurement with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flue gas desulfurization systems occupy an early-cycle expansion phase as ultra-low emission standards proliferate beyond China into India and Southeast Asia, with regulatory tailwinds accelerating retrofit demand faster than new-build coal capacity deployment.
For Market Incumbents: Insulate service revenue streams by unbundling predictive maintenance contracts from equipment sales before margin compression accelerates. Capture backward integration into limestone reagent supply to secure input cost visibility for captive scrubber operations. Cement the installed base advantage through digital twin platform stickiness that raises switching costs for utility procurement departments. For New Entrants and Emerging Players: Build out semi-dry scrubber specialization targeting Middle East and North Africa cement corridors where water scarcity blocks incumbent wet-system dominance. Penetrate India's modular installation segment through rapid-deployment skid-mounted units that exploit compressed CEA compliance timelines. Lead with reagent supply agreements rather than capital equipment to bypass incumbent relationships and establish operational presence. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors aftermarket service platforms over pure equipment manufacturers. Five-to-ten year viability rests on recurring revenue durability as original equipment margins compress toward commodity levels. Target acquisition archetypes combine predictive maintenance software capabilities with regional reagent distribution networks. Monitor enforcement consistency at India's CEA and China's MEE as the critical inflection signal—delayed implementation would stall procurement velocity and strand capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Digital twin integration at Siemens Energy AG differentiates service offerings from commodity hardware suppliers. |
| Reagent Supply Chain Integration | Backward integration into limestone procurement secures margin visibility for continuous scrubber operations. |
| Semi-Dry Scrubber Capacity Expansion | Water-scarce cement production in the Middle East drives fastest-growing technology adoption corridor. |
| Modular Skid-Mounted System Launch | Compressed CEA compliance timelines in India's National Capital Region favor rapid-deployment procurement. |
| Regional Fabrication Joint Venture | Localized alloy vessel production reduces logistics exposure and accelerates commissioning schedules. |
Research Approach
A spread of perspectives from utility planning officers, EPC contractors, scrubber maintenance directors, and reagent procurement managers converged on the working assumptions that frame this analysis. Primary fieldwork combined structured interviews across Asia-Pacific power generation fleets with secondary validation from EPA enforcement databases, MEE emission standard filings, CEA compliance notifications, and customs trade data for limestone and alloy plate imports. Bottom-up project pipeline analysis triangulated against top-down capacity installation estimates to anchor volume forecasts.
Demand-supply balance modeling tracked retrofit installation backlogs against qualified fabrication capacity across Germany, Japan, and South Korea. Segmentation dimensions span system type, installation complexity, end-use industry, and technology chemistry, with regional regulatory enforcement tiers as an additional industry-specific dimension. CAGRs were derived from regression analysis of historical procurement patterns against compliance deadline clustering. Forecast inputs incorporated limestone price volatility indices and welding technician availability metrics as industry-specific variables.
Sensitivities concentrate around regulatory enforcement delays in emerging economies and limestone reagent cost spikes that could compress project economics. Forecasts reflect documented assumptions regarding MEE and CEA implementation consistency. Quarterly review of provincial compliance deadline adherence and alloy plate order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Scrubber System Market