
 Global Flue Gas Desulphurization Market | 2026-2036
Global Flue Gas Desulphurization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flue Gas Desulphurization Market Foresight
The EU Industrial Emissions Directive is pivoting European coal and lignite operators toward regenerable sorbent upgrades and semi-dry retrofit configurations. Fujian Longking dominates wet scrubbing supply chains across Chinese provincial power grids. Doosan Lentjes anchors engineering procurement for utility-scale FGD retrofits in Southeast Asian markets. Mitsubishi Heavy Industries specializes in high-sulfur fuel applications for metallurgical clients.
Flue gas desulphurization removes sulfur dioxide from combustion exhaust through chemical absorption, oxidation, or solid-gas reaction, typically achieving outlet concentrations below 35 mg per standard cubic meter in wet limestone systems. Wet scrubbing occupies the largest installed base due to proven reliability in high-sulfur coal applications, though regenerable sorbent configurations are gaining traction where gypsum disposal constraints apply. Retrofit projects command premium engineering margins compared with new plant installations, particularly in markets with aging thermal fleets and limited greenfield power demand.
The EPA enforces Mercury and Air Toxics Standards that tighten SO₂ limits across US coal-fired units, while China's MEE implements ultra-low emission thresholds for existing power generators. India's CEA mandates FGD installation timelines for thermal plants exceeding 500 MW capacity. Stakeholders must track enforcement consistency in emerging markets and sorbent chemistry advances that reduce wastewater generation.
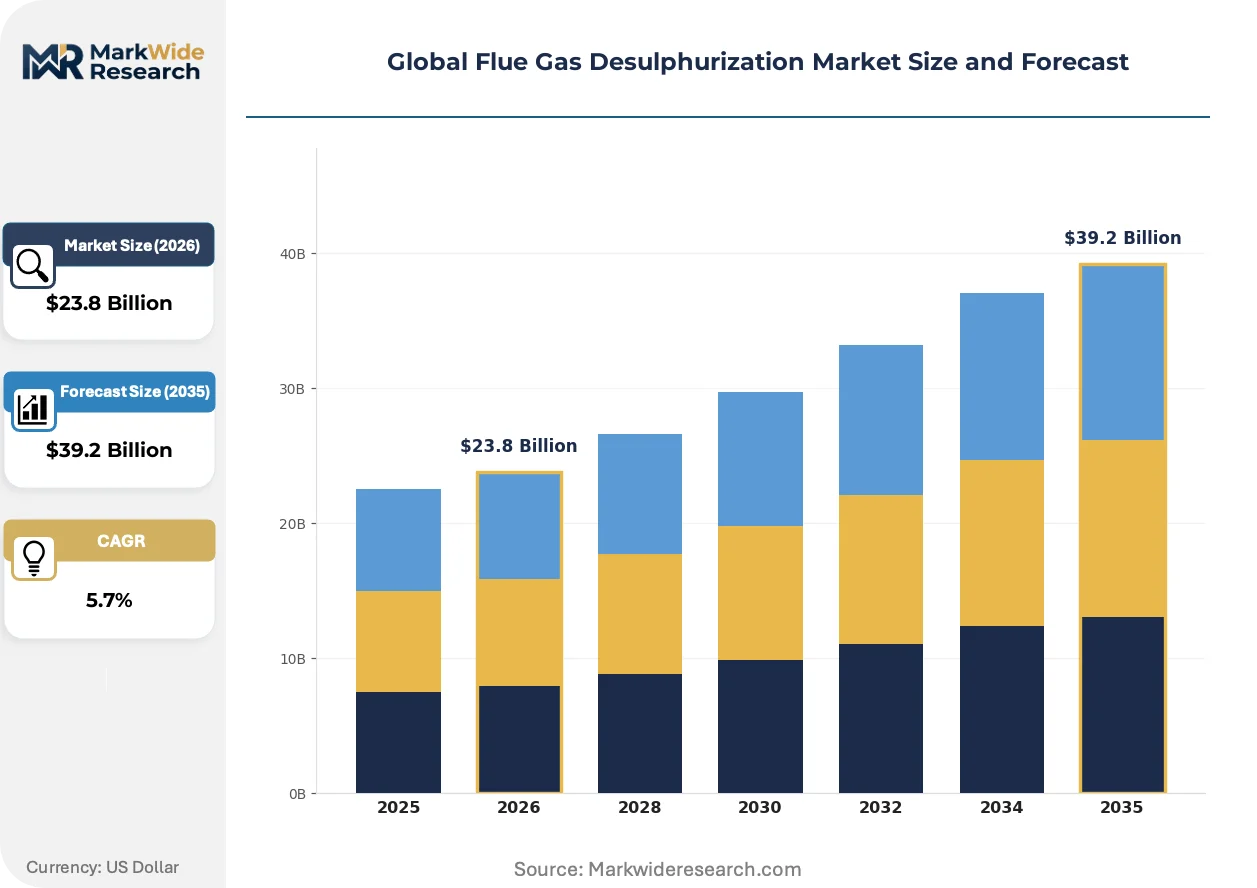
Market Dynamics
Retrofit mandates across aging coal fleets are compressing project timelines and elevating engineering premiums, as operators face simultaneous pressure from emission enforcement and plant retirement economics.
Growth Catalysts
- China's ultra-low emission standards:MEE enforcement drives wet scrubbing upgrades across provincial power grids, forcing continuous operation of existing FGD assets rather than plant closure.
- Indian thermal fleet mandates:CEA installation timelines for units exceeding 500 MW create immediate retrofit demand across state-owned and private generators.
- Regenerable sorbent chemistry:Advances in sodium-based absorption enable gypsum-free operation where landfill constraints block conventional limestone systems.
Market Restraints
- Limestone supply concentration:High-purity reagent sourcing clusters in specific mining districts, exposing scrubbing operations to localized price volatility and transport bottlenecks.
- Wastewater treatment burden:Wet scrubbing generates chloride-laden effluent requiring tertiary treatment, adding opex layers that erode project returns in water-stressed regions.
- Competing plant retirement:Accelerated coal phase-out policies in Germany and the United Kingdom strand FGD investments before depreciation cycles complete.
Strategic Opportunities
- Indonesian IPP expansion:Independent power producers building subcritical units face domestic emission rules creating first-mover FGD installation demand outside China and India.
- Industrial boiler segments:Cement kilns and smelters in Turkey and Vietnam face emerging SO₂ limits, extending FGD addressable market beyond power generation.
- Digital twin integration:Predictive maintenance platforms reduce reagent consumption and unplanned outages, opening recurring software revenue streams for system integrators.
Industry Challenges
- Corrosion engineering expertise:Wet scrubbing environments demand specialized alloy specification and welding protocols, constraining qualified EPC contractor availability.
- Legacy control system interfacing:Retrofit projects must integrate modern DCS architectures with decades-old plant automation, extending commissioning schedules and acceptance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flue Gas Desulphurization Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wet Scrubbing, Dry Scrubbing, Semi-Dry Scrubbing, Regenerable Sorbent, Activated Carbon Injection End User: Power Plants, Cement Manufacturing, Metallurgical Plants, Waste Incineration Facilities, Chemical Processing Units Application: Electricity Generation, Industrial Process Emission Control, Waste Treatment, Metal Smelting, Chemical Production Installation Type: New Plants, Retrofit Projects, Modular Installations, Mobile Units |
| Companies Covered | Fujian Longking Co. Ltd, Doosan Lentjes, Mitsubishi Heavy Industries, Ducon Technologies, Thermax Ltd, GE Vernova, Andritz AG, Hamon Corporation, Babcock & Wilcox Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flue Gas Desulphurization Market Shifts & Advancements
Active technology convergence between emission control and digital optimization is redefining FGD system architecture, moving hardware suppliers toward performance-guarantee contracting and remote operations support.
Advanced oxidation processes for simultaneous mercury and SO₂ capture are integrating into single-vessel scrubbing configurations, reducing footprint and capital intensity for metallurgical clients. Copper smelters in Chile and zinc refineries in Australia adopt these hybrid systems to consolidate multi-pollutant compliance. The technology is integrating previously separate wastewater treatment stages, compressing total installed cost for brownfield sites.
REACH authorization requirements for chromium-based alloys are forcing European operators toward duplex stainless specifications in scrubber vessel construction. Fabricators face extended lead times for certified materials, pushing project schedules into regulatory deadline windows. German lignite operators respond with modular pre-fabrication strategies to compress field installation duration.
Power procurement authorities in Southeast Asia now embed FGD performance guarantees into long-term offtake agreements, transferring operational risk to technology suppliers. Independent engineers in Thailand and Vietnam enforce liquidated damages clauses tied to continuous emission monitoring data. This contractual evolution concentrates supplier selection on demonstrated operating experience rather than equipment cost alone.
Global Flue Gas Desulphurization Market Segmentation
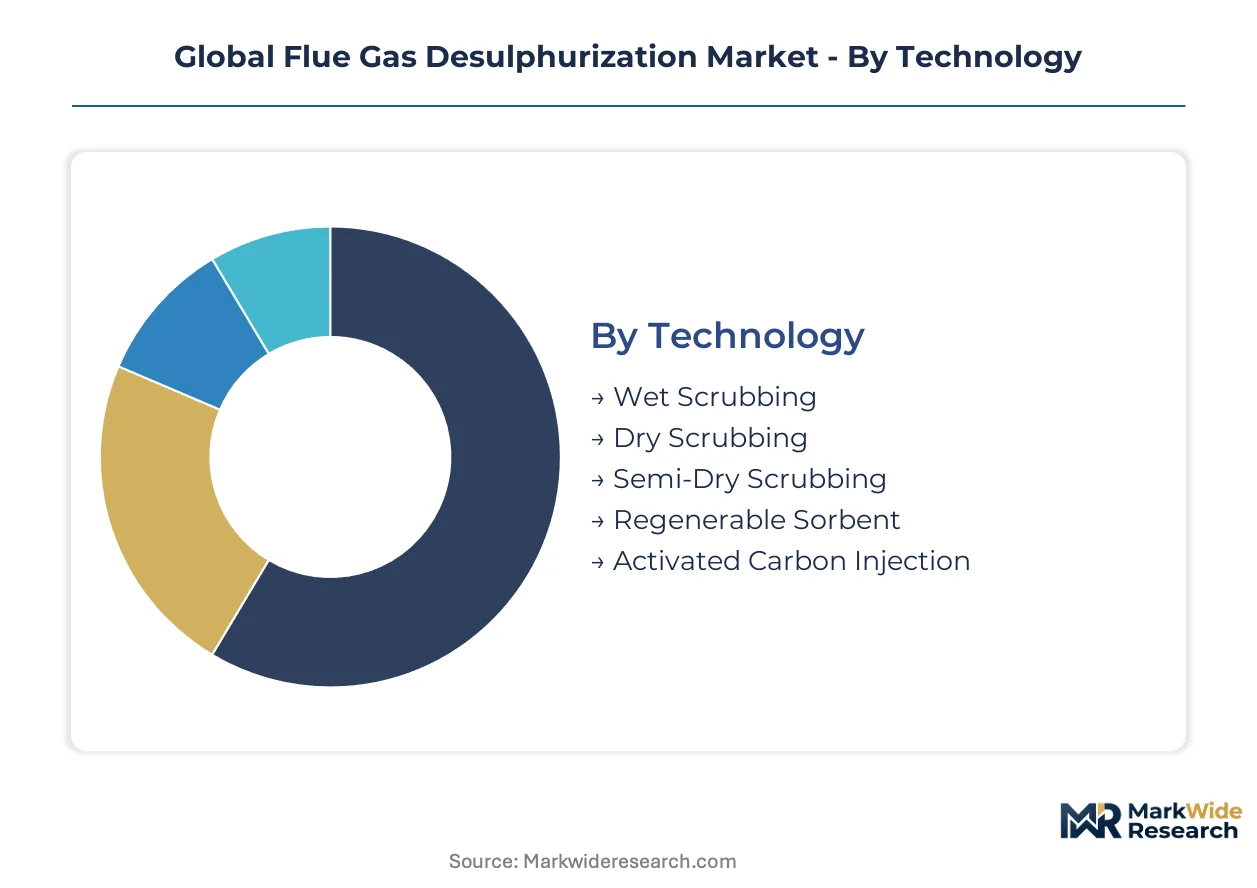
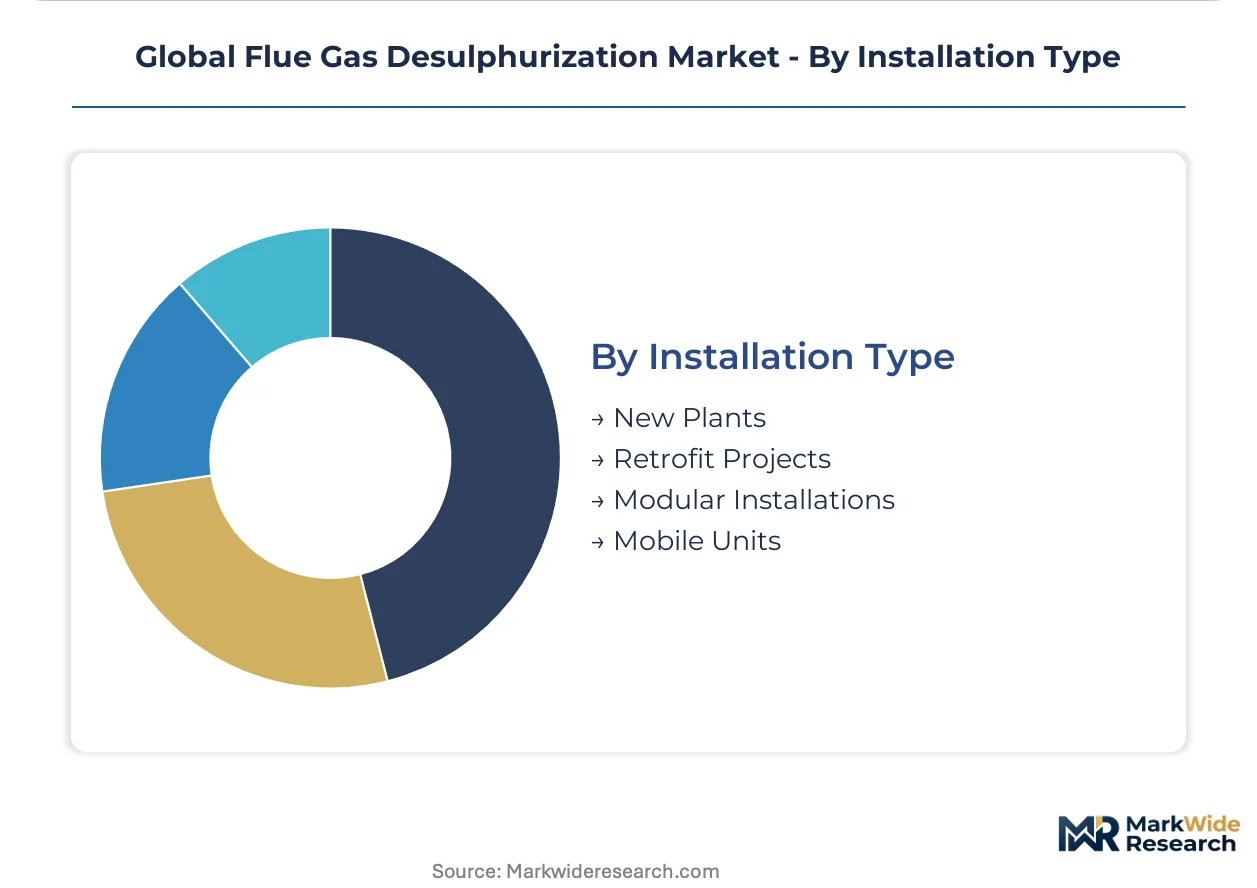
Technology selection in flue gas desulphurization hinges on fuel sulfur content, water availability, and byproduct disposal economics. Installation type determines project margin structure, with retrofits commanding engineering premiums against standardized greenfield deployments.
Technology:
Certification burdens cluster around wet scrubbing systems requiring EPA Best Available Control Technology approval and China's MEE ultra-low emission verification, while regenerable sorbent configurations face ECHA REACH compliance for sodium-based reagent handling.
- Wet Scrubbing:Limestone-gypsum systems achieve outlet concentrations below 35 mg per standard cubic meter through single-loop or dual-loop absorber configurations. Demand concentrates in Indian and Chinese coal retrofits where high-sulfur fuel necessitates proven reliability and continuous operation mandates prevent plant closure.
- Regenerable Sorbent:Sodium-based absorption enables gypsum-free operation with thermal reactivation of spent sorbent, eliminating landfill constraints that block conventional limestone systems in European and Japanese markets. German lignite operators and Japanese coastal plants adopt these configurations where wastewater discharge faces strict regulatory limits.
- Dry Scrubbing:Spray-dryer absorbers inject lime slurry into hot flue gas, producing dry powder byproduct for landfill or construction filler.
- Semi-Dry Scrubbing:Circulating fluidized bed reactors combine dry reagent injection with humidification, occupying middle ground on capital intensity.
- Activated Carbon Injection:Powdered sorbent injection targets mercury co-capture alongside SO₂ reduction in metallurgical applications.
Leading the category by volume: Wet Scrubbing. Growing fastest: Regenerable Sorbent.
End User:
Cost tier stratification separates utility-scale power plants with multi-million dollar scrubber investments from industrial boiler operators seeking compact, skid-mounted solutions.
- Power Plants:Coal-fired and lignite-fired thermal units above 500 MW capacity dominate installed base, with wet limestone systems representing standard configuration. Indian state-owned generators and Chinese provincial grids drive retrofit timelines under CEA and MEE mandates.
- Metallurgical Plants:Copper smelters in Chile and zinc refineries in Australia deploy hybrid scrubbing-oxidation systems for simultaneous SO₂ and mercury capture, consolidating multi-pollutant compliance into single-vessel configurations.
- Cement Manufacturing:Preheater tower integration and kiln bypass gas treatment create specialized sizing requirements.
- Waste Incineration Facilities:Acid gas scrubbing for municipal solid waste plants combines SO₂ removal with HCl neutralization.
- Chemical Processing Units:Sulfuric acid plants and refinery fluid catalytic crackers require tailored corrosion-resistant alloys.
Dominant by capital deployment: Power Plants. Expanding most quickly: Metallurgical Plants.
Application:
Customer type differentiation separates continuous-duty electricity generators from batch-process industrial operators with intermittent emission profiles.
- Electricity Generation:Baseload coal and lignite plants require 8,000+ annual operating hours with guaranteed availability clauses, driving predictive maintenance contracts and digital twin integration. Southeast Asian independent power producers embed FGD performance guarantees into long-term offtake agreements.
- Metal Smelting:Non-ferrous pyrometallurgical operations generate high-strength SO₂ streams exceeding 50,000 ppm, demanding specialized high-sulfur fuel scrubbing expertise and duplex stainless construction.
- Industrial Process Emission Control:Boiler and kiln applications across diverse manufacturing sectors.
- Waste Treatment:Incineration flue gas cleaning with multi-pollutant focus.
- Chemical Production:Tail gas treatment for sulfur recovery and acid manufacturing.
Highest revenue concentration: Electricity Generation. Steepest expansion trajectory: Metal Smelting.
Installation Type:
Supply concentration in qualified EPC contractors shapes project economics, with corrosion engineering expertise and legacy control system interfacing capability limiting viable bidders.
- Retrofit Projects:Brownfield installations integrate modern distributed control systems with decades-old plant automation, extending commissioning schedules and elevating acceptance risk. German lignite operators and Indian state generators compress timelines through modular pre-fabrication to meet regulatory deadlines.
- New Plants:Greenfield installations allow optimized layout and standardized equipment specifications.
- Modular Installations:Pre-fabricated skid packages reduce field construction duration.
- Mobile Units:Temporary scrubbing for emergency compliance or pilot testing.
Greatest margin capture: Retrofit Projects. Fastest volume growth: New Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors wet scrubbing retrofit activity, with Shanghai and Jiangsu province power clusters driving limestone-gypsum system upgrades under enforcement timelines.
China
Provincial grids in Shandong and Shanxi retrofit wet scrubbers to meet MEE ultra-low emission deadlines. The Ministry of Ecology and Environment mandates continuous FGD operation rather than plant closure. Zhejiang coastal plants adopt regenerable sorbent configurations where wastewater discharge faces strict limits.
India
State-owned NTPC units and private generators in Maharashtra and Gujarat compress installation schedules for units exceeding 500 MW. The Central Electricity Authority mandates fixed timelines for FGD commissioning. Tamil Nadu thermal clusters face limestone supply bottlenecks from distant mining districts.
Germany
Rhineland lignite operators deploy modular pre-fabrication to meet EU Industrial Emissions Directive deadlines before accelerated phase-out policies strand investments. ECHA REACH authorization requirements for chromium-based alloys force duplex stainless specifications. Saxony-Anhalt plants face compressed depreciation cycles against retirement economics.
United States
Ohio River Valley coal units retrofit wet scrubbing to comply with EPA Mercury and Air Toxics Standards SO₂ limits. Texas ERCOT generators balance FGD upgrade costs against plant retirement decisions. Powder River Basin operators in Wyoming face reagent transport economics from distant limestone sources.
Indonesia
Independent power producers in Java and Sumatra install first-mover FGD systems for subcritical units under domestic emission rules. Jakarta procurement authorities embed performance guarantees into long-term offtake agreements. Sulawesi nickel smelters create emerging demand for high-sulfur fuel scrubbing expertise.
Global Flue Gas Desulphurization Market Competitive Landscape
The competitive structure tilts toward integrated engineering-procurement contractors with corrosion metallurgy expertise. Wet scrubbing system supply concentrates among Asian fabricators with domestic coal fleet relationships, while European specialists anchor regenerable sorbent configurations. Three archetypes dominate: utility-scale EPC integrators, regional equipment fabricators, and industrial process specialists. Consolidation pressure favors technology licensing partnerships over vertical asset acquisition, particularly for legacy control system interfacing capabilities.
Among Asia-Pacific-based engineering groups, Fujian Longking Co. Ltd and Doosan Lentjes exemplify the utility-scale EPC archetype with established coal fleet relationships. Mitsubishi Heavy Industries occupies a position within the industrial process specialist tier, reflecting metallurgical application heritage. These three anchors demonstrate how geographic clustering around domestic coal upgrade cycles shapes competitive positioning without requiring global scale parity.
| Leading Market Players |
|---|
| Fujian Longking Co. Ltd |
| Doosan Lentjes |
| Mitsubishi Heavy Industries |
| Ducon Technologies |
| Thermax Ltd |
| GE Vernova |
| Andritz AG |
| Hamon Corporation |
| Babcock & Wilcox Enterprises |
| Others |
Supply & Pricing Matrix
Retrofit project mandates from India's CEA and China's MEE are compressing engineering timelines and forcing procurement officers to accept premium pricing for qualified EPC contractors with corrosion metallurgy expertise, shifting supplier selection criteria from equipment cost toward demonstrated operating experience and performance guarantee capacity.
Pricing Analysis
Performance-guarantee contracting anchors pricing structures across utility-scale FGD deployments, with Southeast Asian independent power producers embedding liquidated damages clauses tied to continuous emission monitoring data into long-term offtake agreements. Price differentiation separates premium-tier integrators with modular pre-fabrication capabilities from standard-tier fabricators facing extended lead times for ECHA REACH-compliant duplex stainless materials. Cost compression in mid-market limestone-gypsum systems is intensifying because qualified welding protocol specialists remain scarce against compressed regulatory deadlines. State-owned generators in India exhibit highest price sensitivity due to fixed CEA-mandated commissioning windows, while German lignite operators facing accelerated phase-out economics demonstrate lowest sensitivity to upfront capital outlays.
Supply Chain Analysis
EPA Best Available Control Technology certification and China's MEE ultra-low emission verification gate supplier participation, with qualified EPC contractors clustering in China, Germany, and South Korea where wet scrubbing fabrication infrastructure and corrosion engineering training programs concentrate. High-purity limestone reagent sourcing draws from specific mining districts in India and Vietnam, exposing scrubbing operations to localized transport bottlenecks. Single-source vulnerability pervades certified alloy supply for duplex stainless scrubber vessels under ECHA REACH chromium restrictions. Distribution runs through utility procurement departments and independent power producer engineering teams rather than open equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated engineering-procurement contractors with legacy control system interfacing capabilities, as compressed retrofit timelines strand pure equipment fabricators lacking commissioning expertise and performance guarantee balance sheets.
For Market Incumbents: Deepen backward integration into certified duplex stainless supply chains to compress lead times for ECHA REACH-compliant materials and defend margin position against modular pre-fabrication specialists. Acquire legacy DCS interfacing capabilities through technology licensing partnerships rather than asset-heavy vertical integration, as plant automation integration expertise becomes the scarcest constraint in retrofit project execution. For New Entrants and Emerging Players: Digital twin platforms for predictive FGD maintenance represent a technology-first wedge into recurring software revenue streams, penetrating the white-space between hardware suppliers and plant operators seeking reagent consumption optimization. Target Indonesian independent power producers building subcritical units under domestic emission rules, where first-mover FGD installation demand lacks established supplier relationships and performance guarantee contracting expertise remains underdeveloped. For Investors and Strategic Acquirers: The window for entry favors mid-cap EPC integrators with demonstrated MEE and CEA retrofit completion records and existing corrosion metallurgy certification pipelines. Long-term viability over the next decade hinges on regulatory enforcement consistency in emerging markets rather than greenfield power demand recovery. Watch for inflection signals in Indonesian nickel smelter emission rule enforcement, which would extend addressable market beyond power generation into high-sulfur fuel metallurgical applications.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Pre-fabrication Deployment | German lignite operators compress field installation duration to meet EU Industrial Emissions Directive deadlines. |
| Regenerable Sorbent Chemistry Licensing | Sodium-based absorption technology enables gypsum-free operation where ECHA REACH wastewater constraints block conventional systems. |
| Digital Twin Platform Integration | Predictive maintenance contracts reduce unplanned outages for NTPC units operating under CEA-mandated continuous FGD operation. |
| Corrosion Metallurgy Certification Investment | Duplex stainless specifications satisfy ECHA REACH authorization requirements for scrubber vessel construction. |
| Performance Guarantee Contracting | Thai and Vietnamese independent engineers enforce liquidated damages clauses tied to continuous emission monitoring data. |
Research Methodology
Independent corroboration across EPC contractor project databases, MEE enforcement disclosure filings, and CEA installation timeline records underwrites the qualitative findings, combining primary interviews with utility procurement officers, plant engineering directors, and corrosion metallurgy specialists against secondary validation through EPA MATS compliance data, EU ETS installation records, and customs trade statistics for limestone reagent flows. Bottom-up project pipeline aggregation triangulates against top-down regulatory mandate quantification.
Comparable-period anchoring to historical retrofit completion rates and greenfield commissioning schedules shapes the projection horizon, with segmentation modeling across wet scrubbing, regenerable sorbent, dry scrubbing, and semi-dry configurations, further disaggregated by power plant, metallurgical, cement, and waste incineration end-use categories. CAGRs derive from installed base depreciation cycles intersecting with enforcement deadline clustering, incorporating fuel sulfur content trajectories and wastewater discharge limit tightening as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced coal phase-out policy accelerations, breakthrough sorbent chemistry advances eliminating limestone dependency, and geopolitical disruptions to certified alloy supply chains. Forecasts reflect documented assumptions regarding MEE and CEA enforcement consistency. A model refresh is warranted upon material change in Indonesian domestic emission rule implementation timelines or nickel smelter FGD mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market