
 Global Portable Emissions Measurement Systems (PEMS) Market | 2026-2036
Global Portable Emissions Measurement Systems (PEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Emissions Measurement Systems (PEMS) Market Outlook
The EU Green Deal is repositioning PEMS from niche R&D equipment to mandatory compliance infrastructure across European vehicle certification workflows. Horiba leverages its spectroscopy heritage to dominate high-precision regulatory testing contracts. AVL LIST anchors its position through integrated powertrain validation ecosystems that bundle PEMS with dynamometer services. Sensors Inc. specializes in compact, battery-powered architectures suited to mobile fleet auditing applications.
Portable Emissions Measurement Systems are self-contained analyzers that quantify exhaust constituents—NOx, CO, CO2, THC, and particulate matter—using non-dispersive infrared, chemiluminescence, or flame ionization detection methods, typically at sampling frequencies exceeding one Hertz to capture transient emission events during real-world driving. Their primary purpose is to verify that vehicles meet emission limits under actual operating conditions rather than laboratory cycles. Non-dispersive infrared platforms occupy the largest installed base due to proven reliability and lower maintenance overhead, though wireless and real-time monitoring configurations are gaining traction where fleet operators prioritize immediate data transmission over laboratory-grade precision. Research institutions represent a concentrated margin pool because their procurement cycles favor multi-analyzer configurations with extended service agreements.
EPA, EMA, and the California Air Resources Board shape PEMS demand through divergent real-driving emissions test protocols that force manufacturers to maintain multi-jurisdictional certification capabilities. REACH and RoHS frameworks additionally constrain sensor material selection and electronics supply chains, particularly for infrared source elements and lithium battery packs. Stakeholders must monitor regulatory harmonization negotiations between the EPA and European Commission, as aligned test cycles would reshape R&D allocation and product platform strategies.
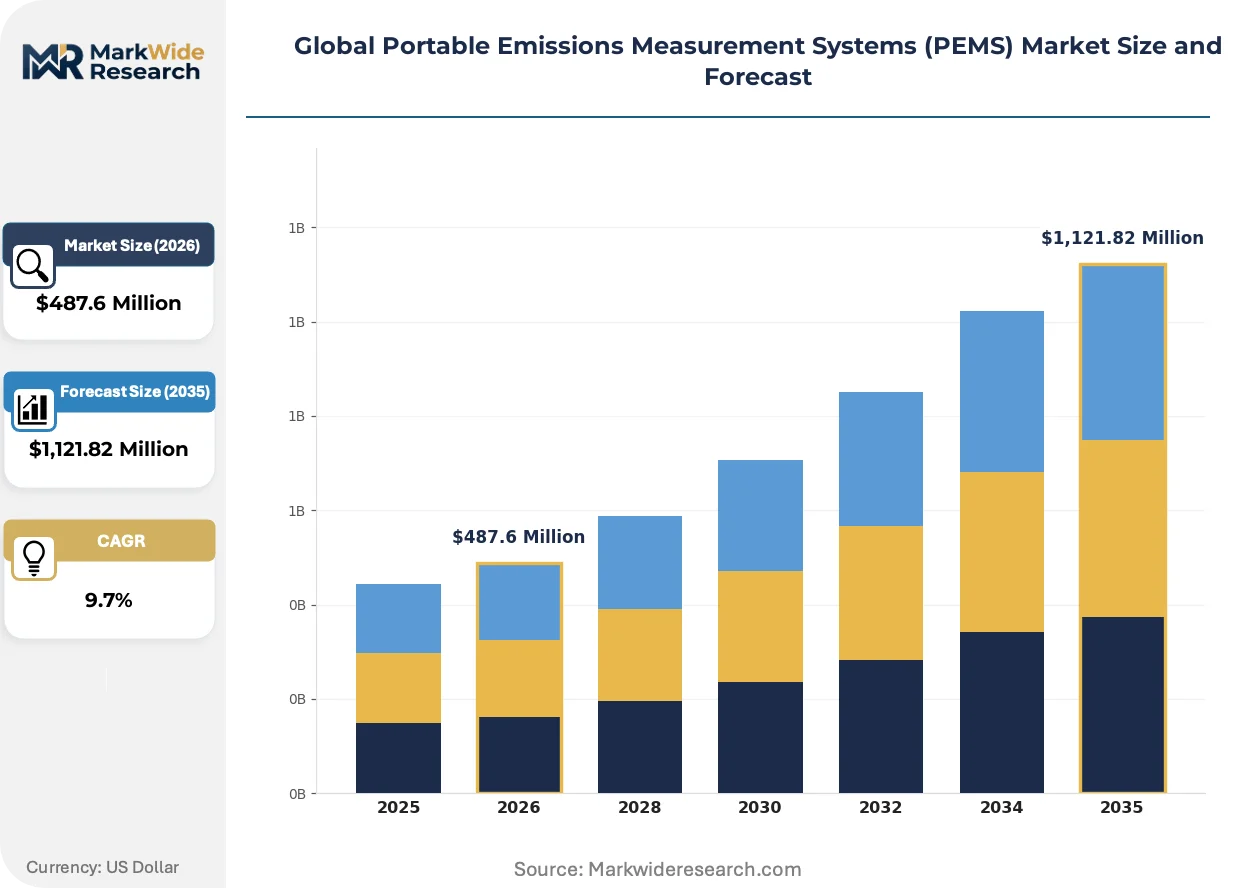
Market Dynamics
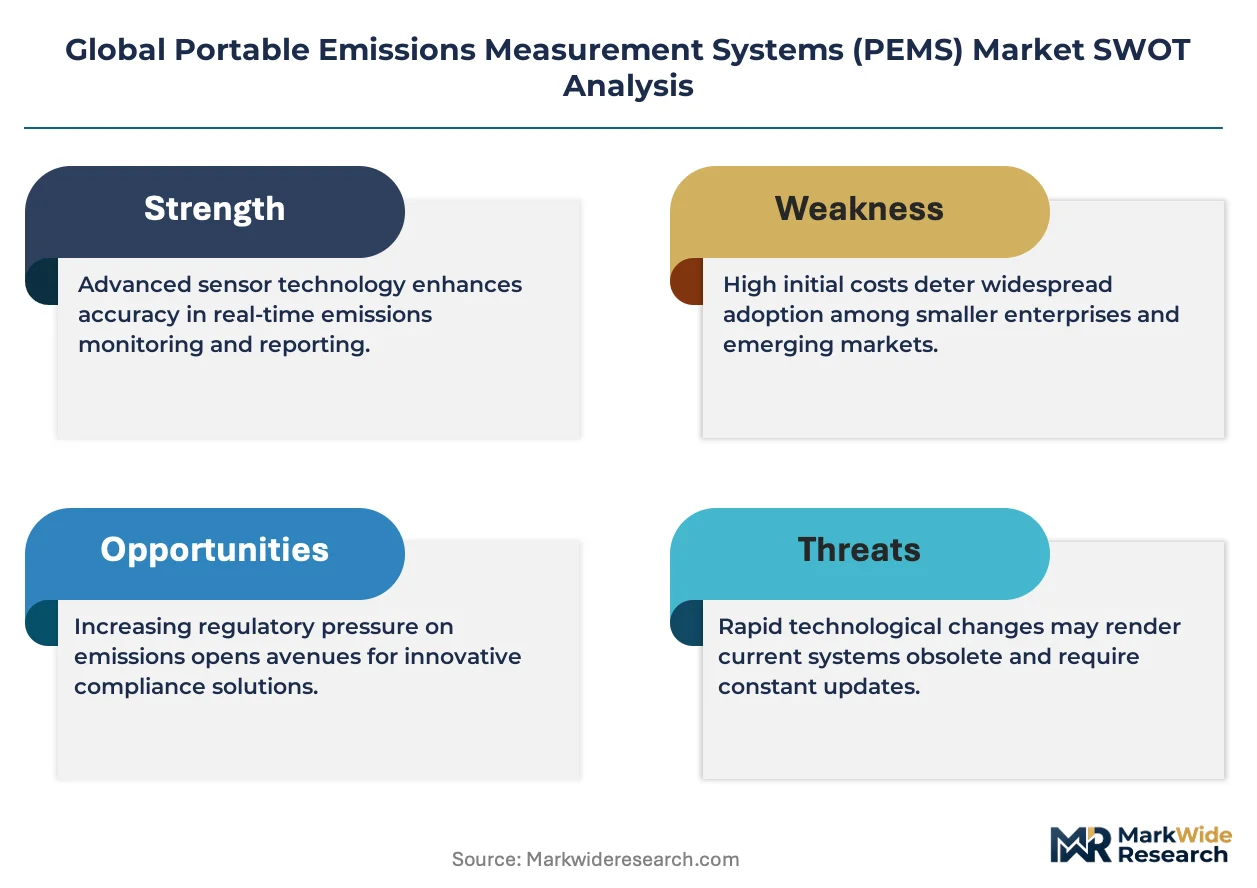
The EPA's real-driving emissions verification mandate and the European Commission's Euro 7 rollout are compressing hardware replacement cycles and forcing multi-jurisdictional certification capabilities among PEMS manufacturers. This regulatory divergence creates structural pressure on R&D allocation and product platform strategies.
Growth Catalysts
- Euro 7 Protocol Expansion:The European Commission's tightened NOx and particulate matter limits for commercial vehicles mandate PEMS deployment across certification workflows, converting laboratory-centric testing infrastructure to mobile verification systems.
- Heavy-Duty Fleet Electrification Auditing:Fleet operators in Germany and California require PEMS to baseline combustion emissions before hybrid conversion, creating sustained demand for portable analyzers that quantify real-world exhaust profiles.
- Non-Dispersive Infrared Reliability:Proven lower maintenance overhead and sampling frequency stability above one Hertz position NDIR platforms as the default choice for regulatory enforcement agencies prioritizing operational uptime over cutting-edge precision.
Market Restraints
- Lithium Battery Supply Concentration:REACH and RoHS constraints on sensor materials and battery packs limit supplier flexibility, with lithium cell sourcing concentrated among East Asian manufacturers creating input cost volatility.
- Multi-Jurisdictional Certification Burden:Divergent EPA, EMA, and California Air Resources Board test protocols force PEMS vendors to maintain parallel hardware configurations, elevating fixed compliance costs without volume scaling benefits.
- Laboratory Dynamometer Substitution:Integrated powertrain validation ecosystems that bundle stationary testing with PEMS services threaten standalone portable analyzer demand among research institutions with captive testing facilities.
Strategic Opportunities
- India Emissions Enforcement Infrastructure:The Central Pollution Control Board's expanding real-driving test requirements for commercial vehicles in Delhi and Mumbai create first-mover advantages for PEMS vendors establishing local calibration and service networks.
- Wireless Real-Time Monitoring Convergence:Battery-powered architectures with immediate data transmission capabilities are penetrating fleet auditing applications where operators prioritize operational visibility over laboratory-grade measurement precision.
- EU Green Deal Compliance Services:Mandatory PEMS integration into European vehicle certification workflows positions service-extended analyzer configurations as recurring revenue platforms beyond one-time hardware sales.
Industry Challenges
- Spectroscopy Calibration Expertise Gap:Shortages of technicians proficient in chemiluminescence and flame ionization detection maintenance constrain service network expansion and extend equipment downtime for remote fleet operators.
- Legacy Analyzer Integration Complexity:Retrofitting existing laboratory information management systems to ingest one-Hertz PEMS data streams requires custom middleware development, delaying deployment timelines for institutional buyers with entrenched software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Emissions Measurement Systems (PEMS) Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,121.82 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dispersive Infrared, Chemiluminescence, Flame Ionization, Gas Chromatography End User: Automotive OEMs, Environmental Agencies, Research Institutions, Industrial Users Technology: Battery-Powered, Wireless, Hybrid, Real-Time Monitoring Application: Regulatory Compliance, Research & Development, Fleet Management, Emissions Testing |
| Companies Covered | TÜV Hessen, Testo, Horiba, ZUMBACH, AVL LIST, Emissions Analytics, SGS, Sensors Inc., DEKRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Emissions Measurement Systems (PEMS) Market Strategic Shifts
Sensor miniaturization and wireless telemetry are compressing form factors while expanding deployment scenarios beyond controlled laboratory environments. These hardware shifts intersect with regulatory mandates to reposition PEMS from research equipment to operational compliance infrastructure.
Quantum cascade laser technology is integrating into mid-infrared detection modules for selective NOx and ammonia measurement with reduced cross-sensitivity to water vapor. Powertrain validation laboratories in Japan and Germany are adopting these platforms to capture transient emission events during cold-start sequences. This precision upgrade is integrating spectroscopic capabilities previously confined to stationary analyzers into battery-portable architectures, collapsing the performance gap between mobile and fixed-site equipment.
The EU Green Deal's vehicle certification workflow mandates are binding PEMS deployment to type-approval processes across member states. Industrial consequence includes mandatory third-party verification of real-driving emissions before market entry, elevating analyzer uptime and traceability requirements. Commercial vehicle segments serving cross-border logistics routes face the steepest compliance burden, driving demand for multi-gas configurations certified under both REACH material constraints and CE marking protocols.
Fleet procurement patterns are fragmenting from centralized capital expenditure toward distributed operational leasing of calibrated analyzer pools. Third-party environmental auditing firms in the United States are displacing in-house testing departments as the primary PEMS acquisition channel, unbundling hardware ownership from measurement service delivery. California's heavy-duty vehicle inspection and maintenance program exhibits this shift most visibly, with independent testing contractors capturing growing shares of regulatory verification volume from captive fleet laboratories.
Global Portable Emissions Measurement Systems (PEMS) Market Segmentation
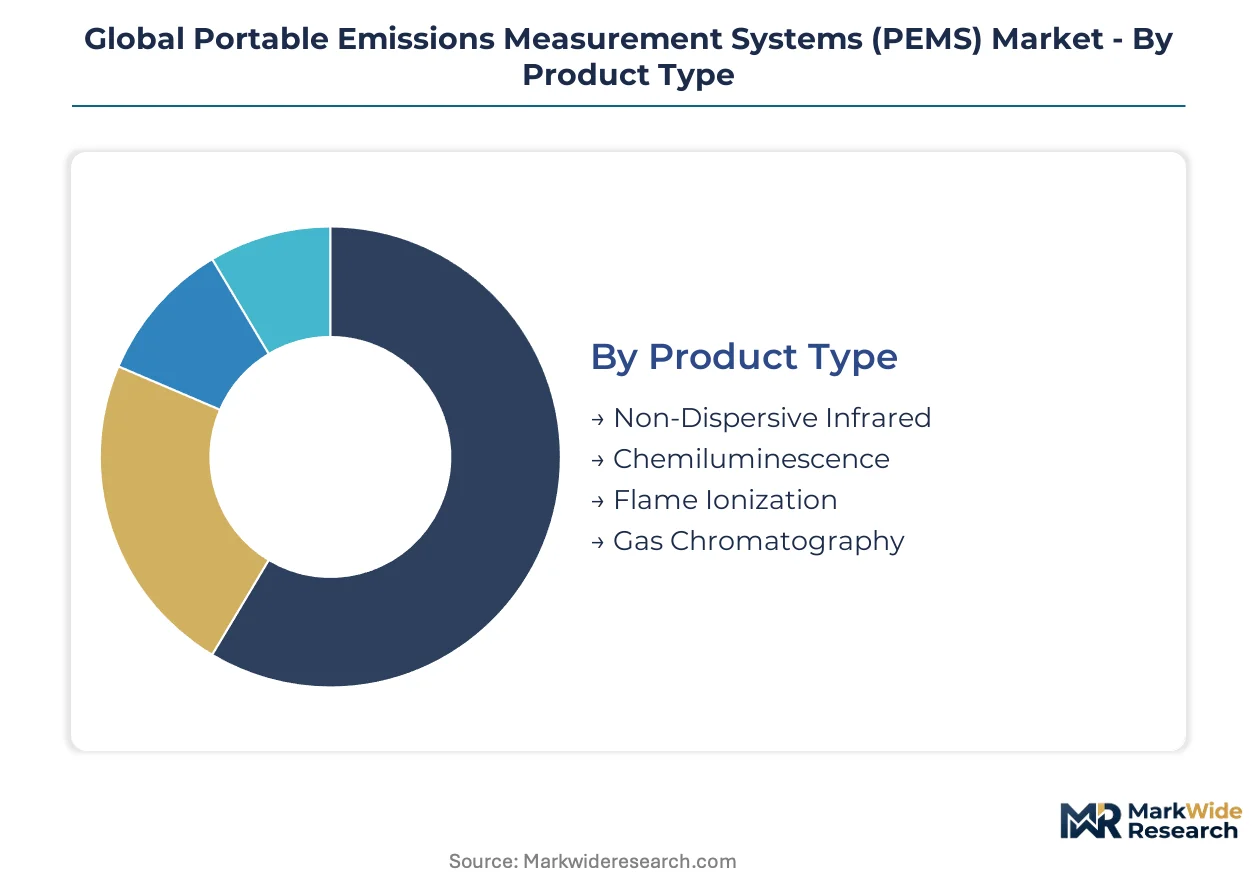
PEMS segmentation reveals how detection physics, deployment architecture, and regulatory use cases create distinct margin pools. Vendors configure platform variants around specific compliance workflows rather than pursuing universal hardware designs.
Product Type:
Detection method determines sampling frequency, cross-sensitivity profiles, and maintenance cadence across regulatory jurisdictions.
- Non-Dispersive Infrared:Measures CO and CO2 through selective absorption at characteristic wavelengths using solid-state optical benches. EPA and KBA enforcement fleets in the United States and Germany specify NDIR cores for their mean-time-between-failure advantages and reduced consumable dependence. Mature deployment sits with stationary-adjacent verification protocols. Newer deployment is concentrated in battery-portable fleet auditing configurations.
- Chemiluminescence:Quantifies NOx via reaction with ozone to produce light emission proportional to nitrogen oxide concentration. Euro 7 type-approval laboratories in Stuttgart and Turin require chemiluminescence for its parts-per-billion resolution during cold-start transient capture.
- Flame Ionization:Detects total hydrocarbons through combustion-induced ion current measurement. California Air Resources Board heavy-duty programs specify FID for methane-non-methane speciation requirements.
- Gas Chromatography:Separates exhaust constituents by retention time for speciated organic compound identification. Research institutions deploy GC-PEMS hybrids for non-regulatory characterization studies.
NDIR platforms anchor commercial volume. Chemiluminescence commands premium positioning in European certification workflows.
End User:
Procurement authority and technical staffing depth shape analyzer specification and service contract structures.
- Automotive OEMs:Internal powertrain validation groups at manufacturers in Japan and Germany purchase multi-analyzer racks for pre-homologation screening. These buyers negotiate extended calibration service agreements to maintain traceability chains. Mature deployment sits with integrated dynamometer facilities. Newer deployment is concentrated in on-road validation fleets for real-driving emissions correlation.
- Environmental Agencies:National regulators including EPA and state-level California Air Resources Board operate mobile enforcement units requiring ruggedized, standardized configurations.
- Research Institutions:University laboratories and national research centers procure configurable platforms with open data architectures for method development.
- Industrial Users:Mining and construction equipment operators in Australia and Canada deploy PEMS for site-specific emissions inventorying under non-road mobile machinery regulations.
Environmental agencies drive standardization. Industrial users are expanding most quickly as non-road regulatory scope widens.
Technology:
Power and telemetry architecture determines deployment flexibility versus measurement fidelity tradeoffs.
- Battery-Powered:Lithium-ion architectures enable installation on vehicles lacking auxiliary power takeoffs. Fleet auditors in Delhi and São Paulo favor these for roadside interception capabilities without generator deployment.
- Wireless:Cellular or satellite telemetry transmits encrypted data streams to cloud validation platforms. California fleet operators prioritize wireless for real-time compliance dashboard integration.
- Hybrid:Combines battery mobility with laboratory-grade sensor conditioning through onboard power management. German technical inspection associations specify hybrid architectures for their TÜV-branded verification services.
- Real-Time Monitoring:Edge computing platforms process emission events locally with sub-second latency. Mining operators in Western Australia deploy these for ventilation-triggered equipment shutdown protocols.
Hybrid systems dominate European certification. Wireless configurations are gaining share fastest in North American fleet management.
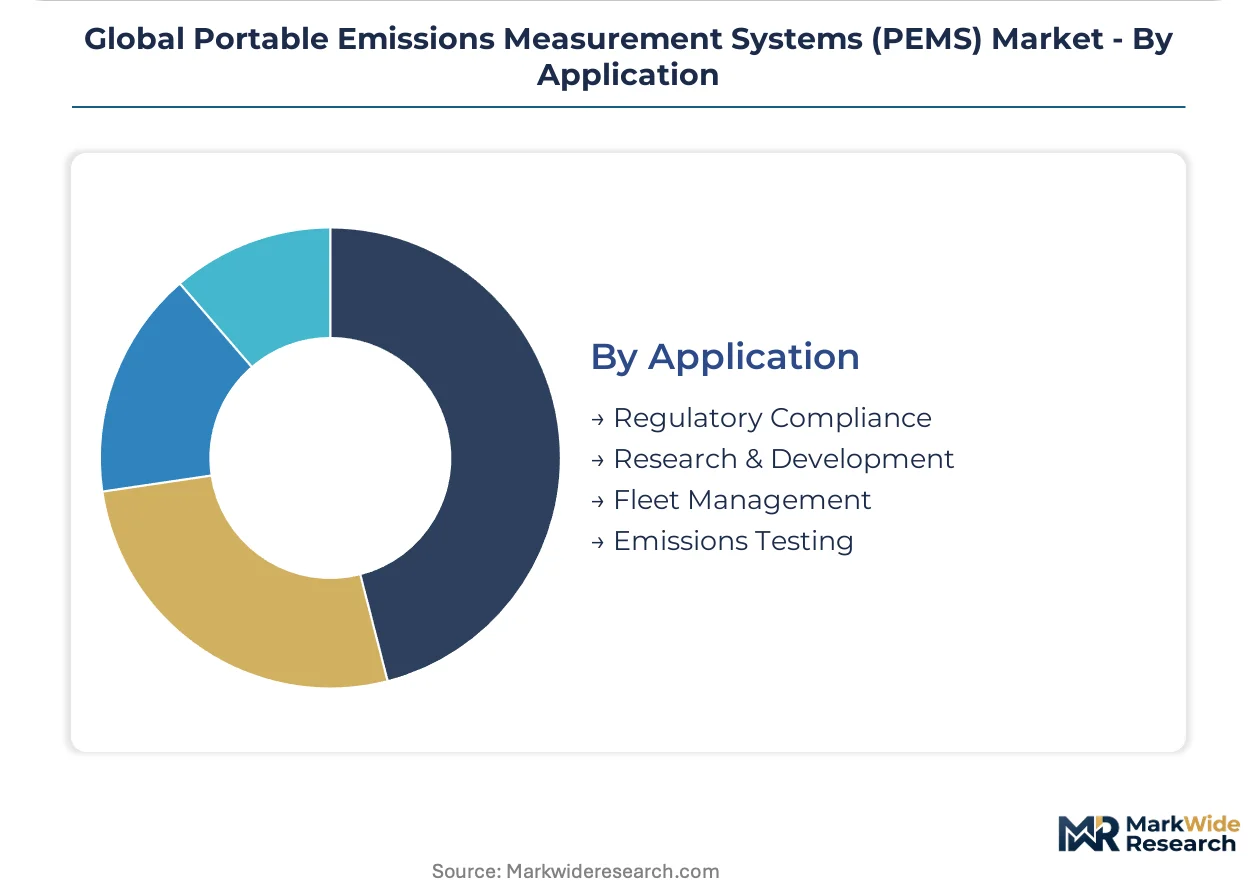
Application:
Use case dictates sampling protocol rigor, data retention requirements, and third-party witnessing needs.
- Regulatory Compliance:Mandated verification for type-approval or in-service conformity testing under EPA, Euro 7, or Japan's Ministry of Land, Infrastructure, Transport and Tourism protocols. These applications require accredited calibration chains and witnessed test procedures.
- Research & Development:Powertrain engineering groups employ PEMS for calibration optimization and aftertreatment strategy validation without formal homologation constraints.
- Fleet Management:Logistics operators baseline vehicle emissions before hybrid conversion or monitor degradation to trigger maintenance interventions.
- Emissions Testing:Independent laboratories offer for-hire verification services to vehicle importers and small manufacturers lacking captive testing infrastructure.
Regulatory compliance commands highest specification tiers. Fleet management is expanding most quickly as electrification auditing requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European PEMS demand through its dense concentration of powertrain engineering centers and KBA regulatory testing facilities. Fleet operators in Germany's automotive corridor deploy portable analyzers for Euro 7 pre-homologation screening. California's heavy-duty vehicle inspection infrastructure generates parallel demand volumes across the Pacific.
United States
EPA enforcement fleets and California Air Resources Board mobile units drive standardized hardware procurement. The federal real-driving emissions verification mandate compresses replacement cycles among commercial vehicle testers. Detroit's powertrain validation clusters anchor OEM pre-certification demand.
Germany
KBA type-approval protocols and TÜV technical inspection networks mandate multi-analyzer configurations. Euro 7 implementation converts laboratory-centric infrastructure to mobile verification systems. Stuttgart and Munich engineering corridors concentrate OEM validation spending.
Japan
Ministry of Land, Infrastructure, Transport and Tourism protocols shape analyzer specifications for domestic manufacturers. METI-funded electrification auditing programs baseline combustion emissions before hybrid conversion. Nagoya's automotive supplier belt deploys battery-portable architectures for on-road validation.
India
Central Pollution Control Board enforcement in Delhi and Mumbai creates first-mover opportunities for calibrated analyzer networks. Real-driving test requirements for commercial vehicles expand beyond laboratory infrastructure constraints. Pune's automotive manufacturing corridor attracts PEMS service providers establishing regional calibration hubs.
China
MEE enforcement of China VI standards drives fleet auditing demand in Beijing and Shanghai port logistics corridors. Dual carbon goals accelerate baseline emissions quantification before electrification retrofits. Shenzhen's equipment manufacturing base supports domestic analyzer assembly.
Global Portable Emissions Measurement Systems (PEMS) Market Competitive Environment
The competitive structure tilts toward diversified instrumentation conglomerates with spectroscopy heritage. Three to four integrated validation service providers anchor regulatory testing contracts across Europe and North America. Specialist vendors occupy fleet auditing niches with compact, battery-powered architectures. Dominant competitive moves include strategic partnerships between analyzer manufacturers and third-party testing contractors, plus geographic expansion of calibration service networks into emerging enforcement markets.
Within the diversified instrumentation tier, Horiba and AVL LIST exemplify integrated powertrain validation ecosystems that bundle portable analyzers with dynamometer services. Sensors Inc. occupies a specialist position among compact architecture vendors serving mobile fleet auditing applications. TÜV Hessen and DEKRA represent the service-provider archetype, leveraging established technical inspection infrastructure to displace standalone hardware procurement.
| Leading Market Players |
|---|
| TÜV Hessen |
| Testo |
| Horiba |
| ZUMBACH |
| AVL LIST |
| Emissions Analytics |
| SGS |
| Sensors Inc. |
| DEKRA |
| Others |
Value Chain & Pricing Dynamics
Certification-grade tier divergence between Euro 7 type-approval systems and fleet-auditing portable units manifests in both pricing premiums and supply chain configurations. REACH-compliant sensor sourcing and lithium battery qualification create cost ladders that separate KBA-accredited laboratories from roadside enforcement operators in Delhi and São Paulo.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for regulatory enforcement agencies operating EPA and KBA mobile units. Three-tier pricing structure across premium chemiluminescence, standard NDIR, and economy battery-portable tiers reflects calibration traceability depth and service bundling. Cost compression in economy tiers intensifies because East Asian battery cell sourcing faces RoHS material constraints. Fleet auditing contractors in California exhibit highest price sensitivity; German TÜV technical inspection networks show lowest sensitivity due to mandatory compliance pass-through.
Supply Chain Analysis
Single-source vulnerability sits with lithium-ion cell manufacturing concentrated in China, South Korea, and Japan. Infrared source elements, chemiluminescence ozone generators, and flame ionization detector hydrogen supplies draw from German and Japanese precision component specialists. Tariff exposure on battery packs and sensor electronics creates margin volatility for battery-powered architecture vendors. Distribution runs through third-party environmental auditing firms displacing direct OEM sales in North American fleet management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 implementation has converted PEMS from discretionary R&D equipment to mandatory compliance infrastructure, erecting calibration expertise and certification network barriers that protect established players.
For Market Incumbents: Extend calibration service network density into India's Central Pollution Control Board enforcement corridors before local competitors establish traceability infrastructure. Acquire battery-portable architecture specialists to defend against fleet-auditing contractors displacing integrated validation ecosystems. Deepen backward integration into lithium battery pack assembly to offset East Asian cell sourcing volatility.
For New Entrants and Emerging Players: Begin with wireless real-time monitoring configurations targeting California heavy-duty fleet operators prioritizing operational dashboards over laboratory precision. India's real-driving test expansion for commercial vehicles represents the most penetrable geography. Partner with third-party testing contractors as channel anchor rather than competing for direct OEM procurement.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-architecture specialists given EU Green Deal workflow mandates converting laboratory infrastructure to mobile verification. Long-term viability hinges on service revenue attachment rates exceeding hardware depreciation cycles. Watch EPA-European Commission regulatory harmonization negotiations as inflection signal for R&D allocation efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Establishes recurring revenue moats in Euro 7 and EPA enforcement corridors. |
| Wireless Telemetry Integration | Captures California fleet operator demand for real-time compliance dashboards. |
| Battery Architecture Miniaturization | Enables Delhi roadside interception without generator deployment constraints. |
| Service Contract Bundling | Converts one-time hardware sales to recurring revenue under EU Green Deal mandates. |
| Quantum Cascade Laser Adoption | Collapses performance gap between mobile and stationary NOx measurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with powertrain validation engineers, environmental agency enforcement officers, fleet procurement managers, and third-party testing contractors combined with EPA enforcement budget disclosures, KBA type-approval databases, and EU Green Deal implementation timelines. Bottom-up unit demand estimates triangulated against top-down regulatory mandate scaling across the analysis window.
Segment-level modeling addressed detection method, power architecture, end-user procurement authority, and application rigor across the projection horizon. CAGRs derived from regulatory implementation schedules, hardware replacement cycle compression, and fleet electrification auditing proliferation. India emissions enforcement infrastructure buildout and wireless telemetry adoption curves served as industry-specific forecast inputs.
Regulatory harmonization delays, lithium battery supply disruptions, and spectroscopy technician shortages are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding Euro 7 implementation pacing and EPA real-driving emissions verification scope expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market