
 Canada Oil and Gas Upstream Market | 2026-2036
Canada Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Oil and Gas Upstream Market Outlook
API-grade specification upgrades across the Western Canadian Sedimentary Basin is redrawing procurement standards for domestic refiners. Cenovus Energy leverages its integrated oil sands and refining footprint to sustain heavy crude throughput advantages. Canadian Natural Resources Limited anchors the largest conventional heavy oil production base in the country. Tourmaline Oil Corp. dominates the Montney and Deep Basin fairways through pure-play natural gas scale.
Canada oil and gas upstream encompasses exploration, drilling, and production of hydrocarbons from subsurface reservoirs, with API gravity specifications ranging from heavy sour crude below 22 degrees to light sweet grades above 35 degrees, serving refineries and export-dependent markets. Seismic surveys and horizontal drilling together account for the dominant exploration and completion methodology across unconventional tight oil and gas plays. Enhanced oil recovery and digital oilfield technologies are capturing expanding capital allocation as producers target declining base production and operational cost compression. Crude oil and natural gas segments split the value pool, with condensates and NGLs growing fastest as petrochemical feedstock demand intensifies.
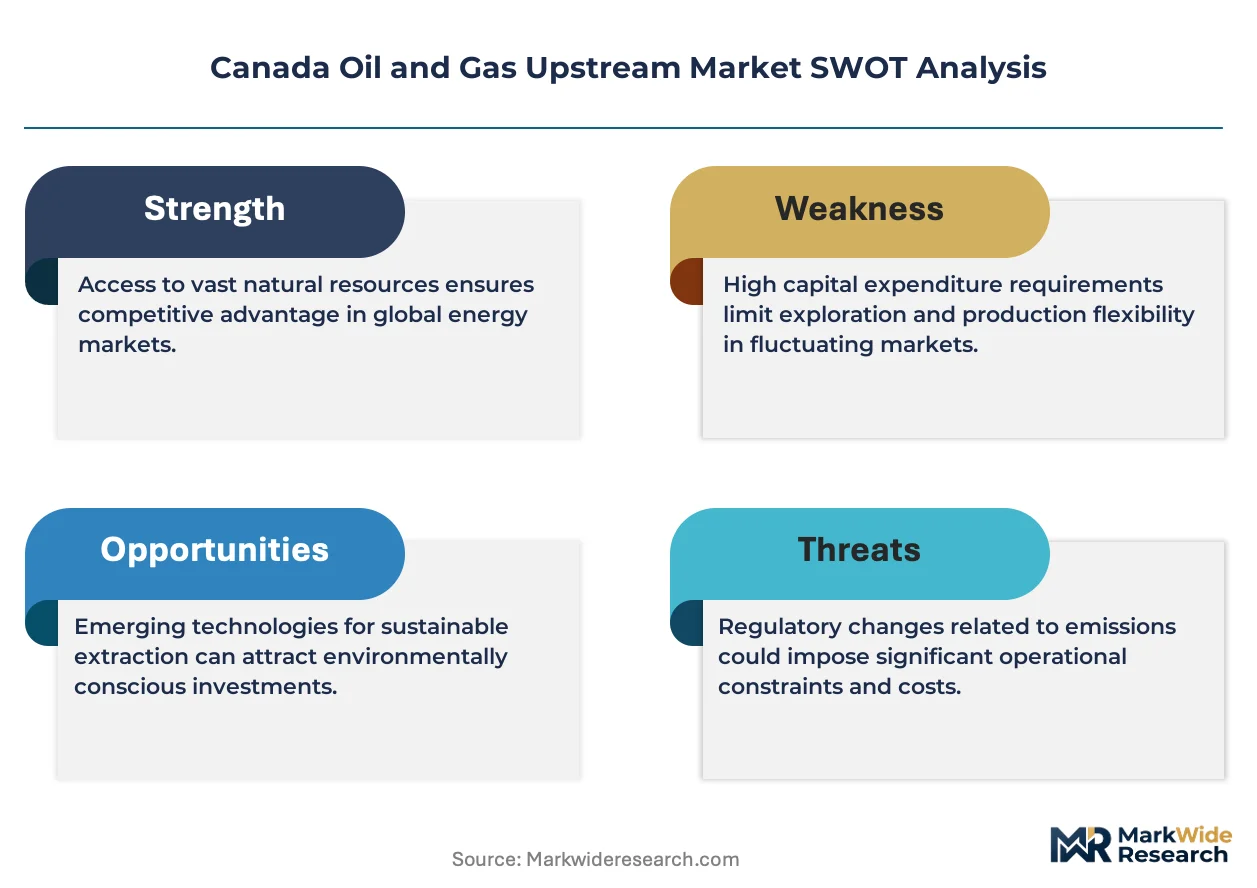
Health Canada and PMRA oversee environmental and health standards affecting upstream chemical use, while provincial regulators in Alberta and British Columbia administer methane reduction mandates and water licensing frameworks that directly shape drilling permit timelines. The federal Impact Assessment Act creates additional approval layers for major projects crossing provincial boundaries or triggering national significance thresholds. Stakeholders must weigh carbon intensity benchmarking against access to tidewater export capacity when allocating capital across the sedimentary basin.
Market Dynamics
Federal methane regulations and provincial carbon pricing frameworks are compressing operating margins across the Western Canadian Sedimentary Basin, forcing producers to reallocate capital toward emissions abatement technologies and low-carbon intensity projects.
Growth Catalysts
- Alberta oil sands corridor concentration:Integrated producers leverage existing steam-assisted gravity drainage infrastructure to sustain heavy crude output without greenfield development timelines.
- Montney tight gas formation scale:British Columbia's Montney and Deep Basin fairways anchor North American LNG feedstock supply as Pacific Basin offtake contracts expand.
- Digital oilfield deployment:Real-time reservoir monitoring and predictive maintenance systems compress operating costs across declining base production assets.
Market Restraints
- Tidewater export capacity constraint:Pipeline egress limitations to British Columbia and US Gulf Coast markets force price discounts on Western Canadian Select crude versus WTI benchmarks.
- Carbon price trajectory:Federal fuel charge escalation and provincial output-based pricing systems compound cost structures for high-carbon intensity oil sands operations.
- Drilling permit timeline extension:Impact Assessment Act review layers and provincial water licensing frameworks stretch project approval cycles for multi-well pad developments.
Strategic Opportunities
- Carbon capture utilization and storage:Alberta's carbon sequestration hub designation and federal investment tax credits position oil sands facilities for blue hydrogen and enhanced oil recovery integration.
- Petrochemical feedstock pivot:Condensate and NGL production from Montney liquids-rich gas streams supplies Alberta's Heartland Petrochemical Complex and export markets.
- Indigenous partnership structures:Equity participation and revenue-sharing agreements with First Nations and Métis communities accelerate project social license and regulatory certainty.
Industry Challenges
- Specialized drilling talent scarcity:Horizontal multi-stage fracturing expertise and directional drilling competency gaps constrain rig fleet utilization rates across unconventional plays.
- Legacy facility methane detection:Fugitive emissions monitoring and pneumatic device retrofitting requirements strain maintenance budgets and field crew deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Oil and Gas Upstream Market |
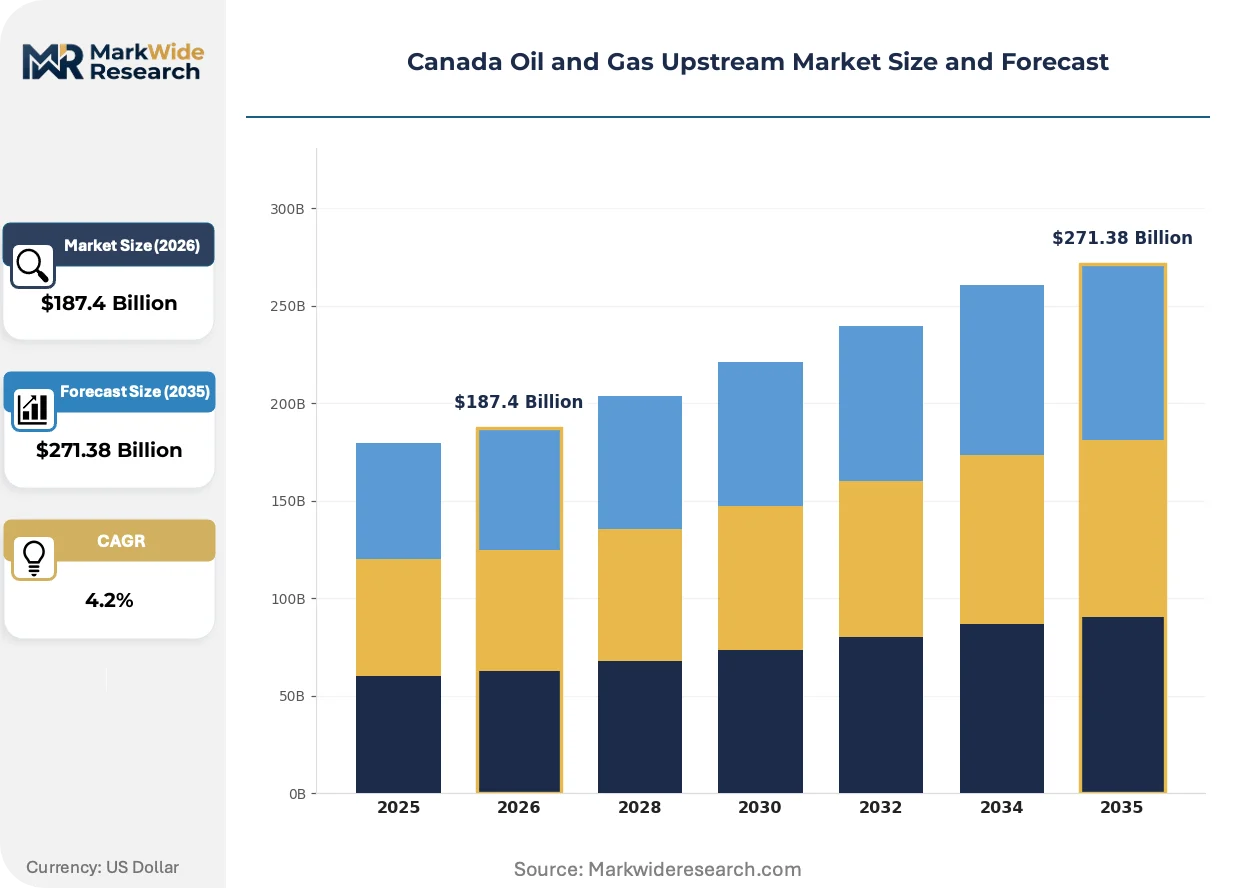
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Condensates, NGLs Exploration Technique: Seismic Surveys, Drilling, Geological Analysis, Remote Sensing Technology: Enhanced Oil Recovery, Hydraulic Fracturing, Horizontal Drilling, Digital Oilfield End User: Refineries, Petrochemical Plants, Export Markets, Power Generation |
| Companies Covered | Cenovus Energy Inc., TotalEnergies SE, Canadian Natural Resources Limited, Chevron Corporation, Exxon Mobil Corporation, Tourmaline Oil Corp., ConocoPhillips, Shell plc, ARC Resources Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Oil and Gas Upstream Market Strategic Shifts
Upstream technology deployment is pivoting from volume-maximizing extraction methods toward emissions-intensity reduction and operational automation, reshaping capital allocation and vendor selection criteria across the sedimentary basin.
Pad-drilling and walking-rig systems are supplanting single-well development economics across Montney and Duvernay tight oil formations. Producers deploy multi-well pad configurations with batch-completion sequences to compress surface disturbance footprints and drilling cycle times. This concentration is enabling continuous operations logistics and shared infrastructure amortization across extended lateral lengths.
Health Canada and PMRA oversight of chemical disclosure requirements for hydraulic fracturing fluids is tightening formulation transparency mandates. Provincial regulators in Alberta and British Columbia now require pre-approval of additive chemistries before well stimulation permits issue. Service companies are reformulating friction reducers and biocides to meet biodegradability thresholds while preserving downhole performance specifications.
Integrated producers are consolidating procurement authority under centralized supply chain functions, displacing field-level discretionary purchasing for drilling and completions materials. Category management teams now negotiate multi-year tubular and proppant agreements directly with manufacturers, bypassing traditional distributor networks. This concentration is most visible across Alberta's oil sands operators and large Montney gas producers seeking volume-scale pricing and inventory pooling advantages.
Canada Oil and Gas Upstream Market Segmentation
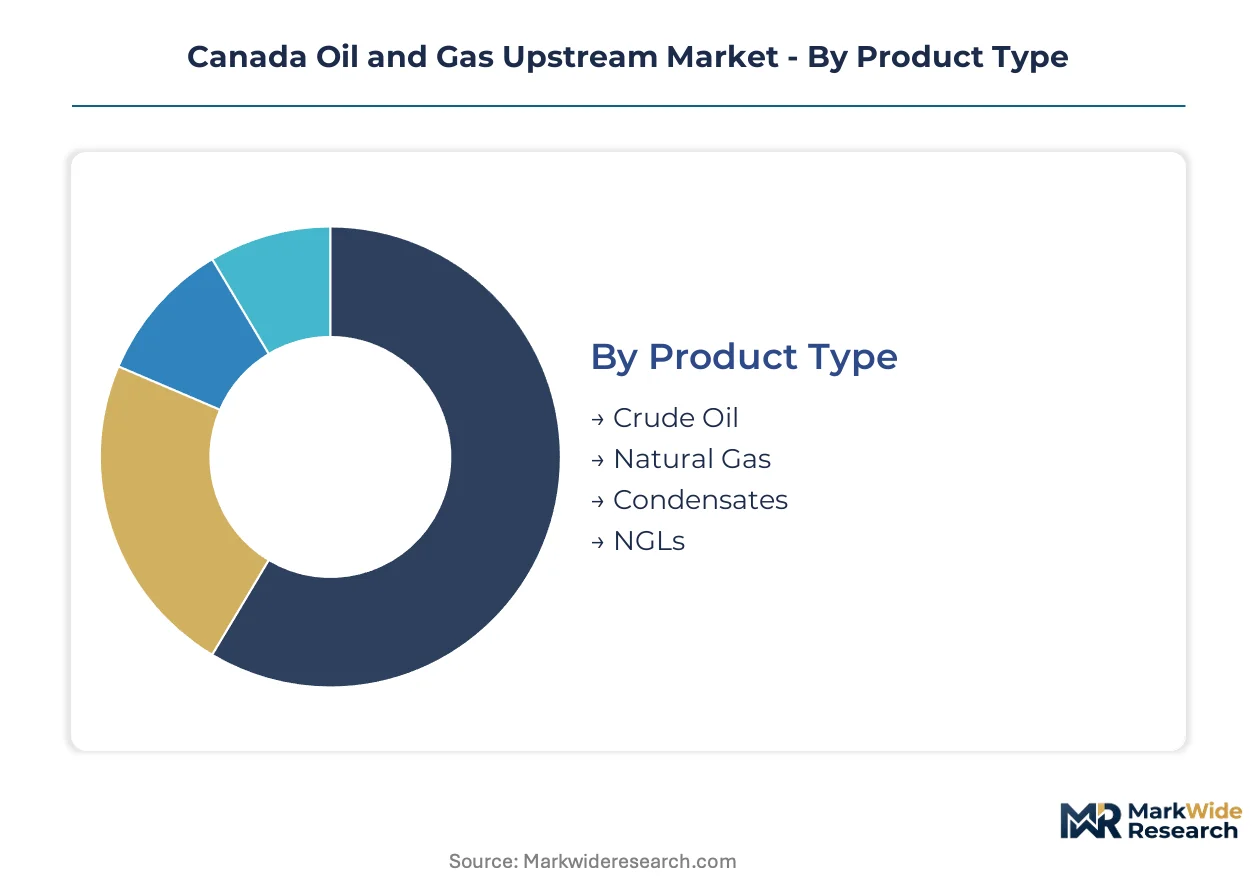
Upstream segmentation in Canada reflects divergent capital intensity profiles and regulatory exposure across hydrocarbon types and extraction methodologies. Producers allocate capital based on carbon intensity benchmarking, tidewater access economics, and integration with downstream refining and petrochemical infrastructure.
Product Type:
Substitution pressure from renewable power and biofuels concentrates most intensely on light sweet crude streams, while heavy sour grades retain captive demand from complex refiners lacking alternative feedstock sources.
- Crude Oil:Western Canadian Select and synthetic grades from oil sands operations dominate volume. Alberta's oil sands corridor concentrates heavy crude production for integrated refinery networks and US Gulf Coast exporters facing constrained pipeline egress.
- Natural Gas:Montney and Deep Basin tight gas formations supply North American LNG export terminals and Alberta power generation. British Columbia's Montney fairway anchors feedstock contracts for Pacific Basin offtake as global LNG demand displaces coal-fired power.
- Condensates:Ultra-light hydrocarbon streams from liquids-rich Montney wells dilute heavy crude for pipeline transport and supply Alberta's Heartland Petrochemical Complex.
- NGLs:Ethane, propane, and butane fractions from gas processing plants feed domestic petrochemical crackers and US export markets.
Crude oil anchors the volume base while natural gas gains share at the steepest rate as LNG export capacity expands.
Exploration Technique:
Cost tier differentiation separates capital-intensive seismic programs from rapid-deployment remote sensing, with budget-constrained operators prioritizing lower-cost methods in mature basin areas.
- Seismic Surveys:3D and 4D seismic acquisition maps subsurface reservoirs across the Western Canadian Sedimentary Basin. Alberta operators deploy dense seismic grids to optimize horizontal well placement in unconventional tight oil formations.
- Drilling:Exploration and appraisal wells prove reserves in frontier acreage and step-out locations. Northern Alberta and British Columbia foothills drilling targets conventional structural traps bypassed by earlier development waves.
- Geological Analysis:Core sampling and petrophysical interpretation calibrate reservoir models. Regional geological surveys from provincial energy regulators provide public data packages reducing exploration risk in underexplored sub-basins.
- Remote Sensing:Satellite imagery and aerial magnetometry screen large acreage blocks for surface seeps and structural anomalies. Early-stage reconnaissance in remote Canadian Arctic and offshore frontier basins leverages spectral imaging to prioritize ground surveys.
Seismic surveys retain the largest share of exploration capital while remote sensing climbs fastest as operators screen frontier acreage at lower cost.
Technology:
Application focus distinguishes mature basin technologies targeting base production decline from frontier methods unlocking unconventional resources.
- Enhanced Oil Recovery:Steam-assisted gravity drainage and carbon dioxide injection sustain output from aging oil sands and conventional pools. Alberta's carbon sequestration hub designation positions CO2-EOR projects for federal investment tax credit support.
- Hydraulic Fracturing:Multi-stage slickwater and hybrid gel fracs complete horizontal wells in Montney and Duvernay tight formations. Health Canada and PMRA chemical disclosure mandates drive service company reformulation of friction reducers and biocides.
- Horizontal Drilling:Extended-reach laterals maximize reservoir contact per surface location. Walking-rig systems and pad-drilling configurations compress cycle times across multi-well developments in British Columbia's gas fairways.
- Digital Oilfield:Real-time reservoir monitoring and predictive maintenance systems reduce operating costs. Integrated producers deploy edge computing and IoT sensors across remote well pads to automate production optimization.
Hydraulic fracturing commands the largest installed base while digital oilfield expands most quickly as labor scarcity drives automation investment.
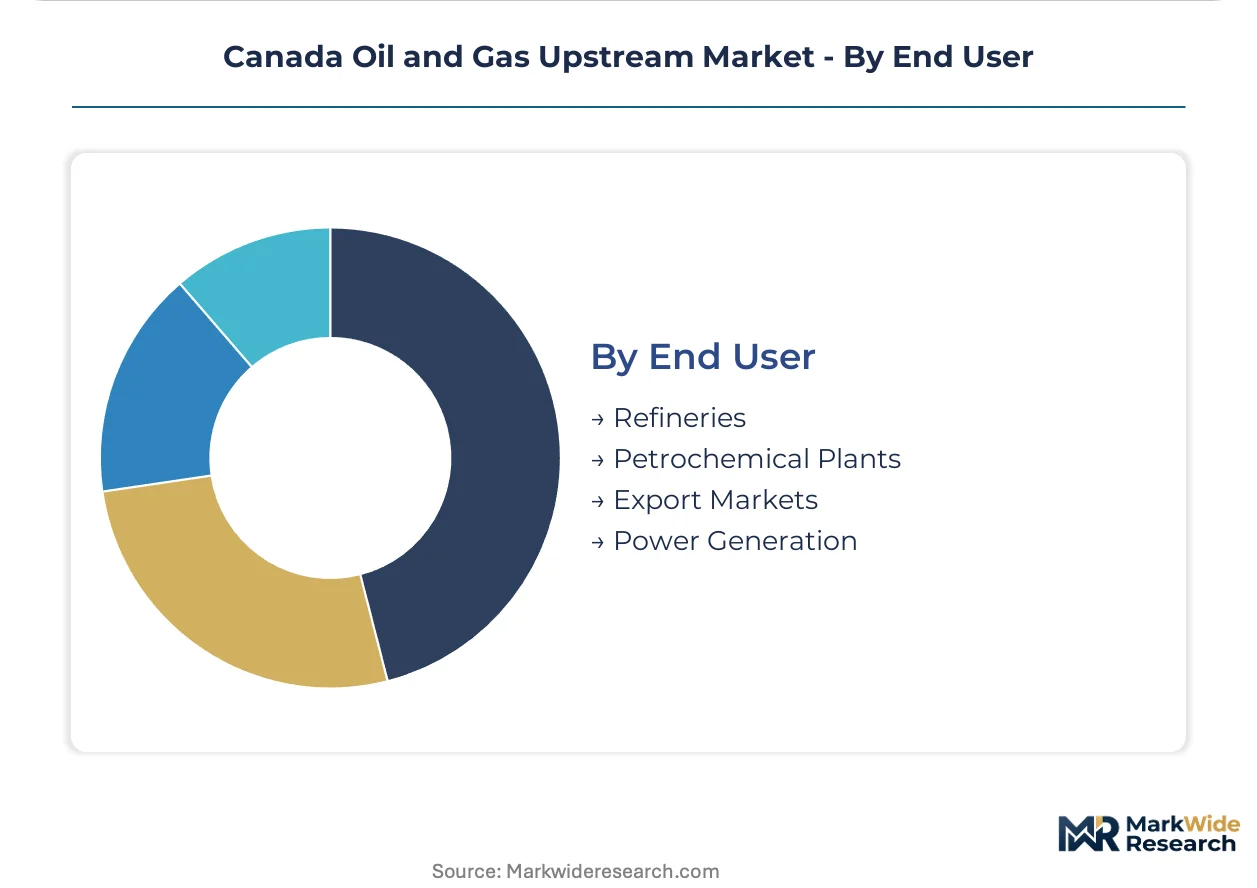
End User:
Customer type segmentation reveals diverging carbon intensity requirements and pricing power across domestic processing and export channels.
- Refineries:Complex coking and hydrocracking units in Alberta, Ontario, and US Midwest process heavy sour Canadian crude. Cenovus Energy and Canadian Natural Resources Limited anchor long-term supply contracts with integrated refining networks.
- Petrochemical Plants:Alberta's Heartland Petrochemical Complex and US Gulf Coast crackers consume condensate and NGL feedstocks. Montney liquids-rich gas production supplies regional ethane and propane demand as petrochemical capacity expands.
- Export Markets:Pipeline deliveries to US Midwest and Gulf Coast refiners, plus rail and marine volumes to Asia-Pacific buyers. Tidewater capacity constraints force Western Canadian Select discounts versus WTI benchmarks.
- Power Generation:Alberta and Saskatchewan gas-fired plants burn Montney and Deep Basin production. Coal phase-out regulations accelerate gas demand from provincial utilities seeking lower-carbon baseload supply.
Refineries absorb the largest volume share while petrochemical plants capture the steepest demand trajectory as downstream integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian crude flows primarily to US Midwest and Gulf Coast refineries via pipeline networks, while Montney gas supplies Pacific Basin LNG terminals through British Columbia export infrastructure. Provincial regulatory frameworks and carbon pricing systems create divergent operating economics across sedimentary basin sub-regions.
Alberta
Oil sands steam-assisted gravity drainage operations and conventional heavy oil pools sustain the province's production base. Alberta Energy Regulator administers methane reduction mandates and water licensing frameworks that shape multi-well pad approval timelines. The Athabasca oil sands corridor around Fort McMurray concentrates integrated producer operations and carbon capture hub development.
British Columbia
Montney tight gas formations supply feedstock for Pacific Northwest LNG export terminals and Alberta power generation markets. BC Oil and Gas Commission enforces drilling permit conditions and hydraulic fracturing fluid disclosure requirements under provincial environmental statutes. The Peace River regional district anchors horizontal multi-stage fracturing operations and liquids-rich gas processing infrastructure.
Saskatchewan
Conventional heavy oil thermal recovery projects and CO2-enhanced oil recovery operations target declining legacy pools. Saskatchewan Ministry of Energy and Resources oversees production facility inspections and pipeline integrity programs. The Lloydminster heavy oil belt straddling the Alberta border maintains thermal cyclic steam stimulation activity.
Manitoba
Light oil production from the Williston Basin extension supplies US Midwest refineries through pipeline interconnects. Manitoba Sustainable Development issues well licenses under provincial oil and gas regulations aligned with federal environmental assessment thresholds. The southwest corner around Virden and Waskada contains the province's primary drilling activity.
Canada Oil and Gas Upstream Market Competitive Environment
Listed leaders compete with private specialists across capital allocation and emissions intensity dimensions. The market structure concentrates around integrated oil sands operators and large-scale Montney gas producers, with mid-tier conventional players occupying niche positions. Strategic archetypes include vertically integrated heavy crude refiners, pure-play tight gas specialists, and international majors with Canadian subsidiary operations. Dominant competitive moves encompass carbon capture infrastructure partnerships and Indigenous equity participation structures.
Within the integrated heavy crude tier, Cenovus Energy Inc. and Canadian Natural Resources Limited exemplify operators leveraging oil sands and refining footprints to manage throughput economics. Tourmaline Oil Corp. occupies a position among pure-play Montney gas specialists scaling liquids-rich production for petrochemical and LNG export markets.
| Leading Market Players |
|---|
| Cenovus Energy Inc. |
| TotalEnergies SE |
| Canadian Natural Resources Limited |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Tourmaline Oil Corp. |
| ConocoPhillips |
| Shell plc |
| ARC Resources Ltd. |
| Others |
Value Chain & Pricing Dynamics
Health Canada and PMRA chemical disclosure mandates gate both service company qualification and price differentiation for hydraulic fracturing fluids, compressing margins for non-compliant suppliers while rewarding reformulation investments with contract premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across tubular goods and proppant categories. Price differentiation rests on volume scale and API certification grade, with integrated producers capturing lowest-unit-cost positions through multi-year manufacturer agreements. Cost compression in standard-grade proppants is intensifying because category management teams bypass distributor networks. Small conventional operators exhibit highest price sensitivity due to limited storage capacity and fragmented purchasing authority.
Supply Chain Analysis
Inventory pooling and extended lead times for specialized alloy tubulars constrain drilling program flexibility across Montney and oil sands developments. Manufacturing concentrates in the United States, China, and domestic Canadian facilities for drilling consumables. Raw material dependencies include high-grade steel alloys, ceramic proppants, and specialized chemical friction reducers. Single-source vulnerability runs through Chinese ceramic proppant suppliers facing export licensing variability. Distribution runs through centralized supply chain functions displacing field-level discretionary purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital oilfield service layers expand faster than hardware deployment, creating attach-rate opportunities for predictive maintenance and reservoir optimization software recurring revenue streams.
For Market Incumbents: Fortify emissions monitoring technology integration to defend against carbon intensity benchmarking requirements tightening across Alberta and British Columbia. Deepen backward integration into carbon capture infrastructure through Alberta's sequestration hub designation. Expand Indigenous partnership equity structures to accelerate social license timelines for multi-well pad approvals.
For New Entrants and Emerging Players: Aftermarket digital twin and edge computing deployment for legacy well pads represents the most penetrable service gap where incumbents under-serve declining base production assets. Target Saskatchewan thermal recovery operators seeking automation retrofit solutions without greenfield capital commitments. Lead with subscription-based reservoir monitoring platforms to bypass upfront hardware procurement barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Montney tight gas developments as pad-drilling efficiencies compress per-well surface infrastructure requirements. Long-term viability favors pure-play gas producers with secured Pacific Basin LNG offtake positioning. Acquisition target archetype: mid-scale Montney operators with undeveloped liquids-rich inventory and existing First Nations partnership frameworks. Watch federal fuel charge escalation trajectory as inflection indicator for oil sands versus gas-weighted portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Hub Integration | Alberta's sequestration designation positions oil sands facilities for federal investment tax credit capture and blue hydrogen feedstock supply. |
| Indigenous Equity Partnership | Revenue-sharing agreements with First Nations and Métis communities compress regulatory approval timelines and secure social license. |
| Digital Oilfield Platform Deployment | Predictive maintenance and real-time reservoir monitoring systems reduce labor dependency across remote well pad operations. |
| Montney LNG Feedstock Contracting | Pacific Basin offtake agreements anchor production economics for British Columbia liquids-rich gas developments. |
| Petrochemical Feedstock Pivot | Condensate and NGL supply contracts to Alberta's Heartland Petrochemical Complex diversify revenue beyond pipeline-export dependence. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with upstream operations executives, drilling contractors, provincial regulator policy leads, and carbon capture project developers; and secondary validation through Alberta Energy Regulator production databases, BC Oil and Gas Commission permit filings, federal Impact Assessment Act project registers, and Canadian Association of Petroleum Producers capital expenditure surveys. Bottom-up well count and production volume estimates triangulated against top-down provincial reserve assessments and infrastructure capacity utilization rates.
Across the projection horizon, the analytical framework modeled hydrocarbon type, extraction methodology, carbon intensity tier, and end-use customer segment dimensions. CAGRs derived from historical production growth rates, capital allocation patterns, and regulatory compliance cost trajectories. Forecast inputs incorporated steam-assisted gravity drainage efficiency curves, Montney well productivity decline rates, and LNG export terminal commissioning timelines.
Forecasts assume regulatory continuity in federal methane regulations and provincial carbon pricing frameworks; material policy shifts including accelerated fuel charge escalation or tightened water licensing thresholds would require re-modeling. Outputs reflect assumptions about tidewater export capacity expansion and Indigenous consultation process standardization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Small Scale LNG (SSLNG) Market