
 Scrubber Market | 2026-2036
Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Scrubber Market Outlook
Modular scrubber packaging is decoupling hardware from installation services, letting buyers source components and engineering separately. Alfa Laval leverages its marine aftermarket network to capture retrofit cycles. Wärtsilä anchors its position through integrated vessel optimization platforms. Babcock & Wilcox Enterprises specializes in utility-scale dry scrubber arrays for coal-fired plants.
Scrubbers are gas-liquid or gas-solid contact systems that remove particulates, acid gases, or volatile organic compounds from industrial exhaust streams, typically operating at pressure drops between 2 and 20 inches of water column and achieving removal efficiencies above 95 percent for sulfur oxides. Wet scrubbers dominate marine and chemical processing applications where high humidity tolerance matters, while dry scrubbers lead in power generation settings with water scarcity constraints. Packaged systems command premium pricing in pharmaceutical cleanroom applications, whereas modular solutions gain traction in oil and gas field deployments requiring rapid redeployment.
The International Maritime Organization enforces sulfur content limits that directly mandate scrubber installations on ocean-going vessels, while EPA standards under the Clean Air Act drive utility and industrial compliance spending in the United States. REACH and the EU Industrial Emissions Directive impose chemical safety and emissions performance thresholds that shape scrubber material selection and operating permits across European manufacturing. Stakeholders must weigh capex-heavy full-system contracts against modular procurement models as regulatory stringency diverges across flag states and industrial zones.
Market Dynamics
The scrubber market pivots on a fundamental structural tension: marine operators face simultaneous pressure from IMO sulfur enforcement and rising dry-docking costs, forcing compressed retrofit windows and supplier consolidation around integrated platform providers.
Growth Catalysts
- IMO 2020 Sulfur Cap Enforcement:Ocean-going vessels sailing under flags of Panama, Liberia, and Marshall Islands must install exhaust gas cleaning systems or switch to compliant fuels, creating installed-base demand across 60,000+ eligible ships.
- EU F-Gas Regulation Phase-Down:Industrial refrigeration and air conditioning OEMs in Germany, France, and Italy are retrofitting production lines with acid gas scrubbers to handle transitional refrigerant chemistries.
- Chemical Processing Cluster Expansion:Petrochemical complexes along the US Gulf Coast and China's eastern seaboard are adding wet scrubber trains to handle higher-sulfur feedstock flexibility.
Market Restraints
- Specialized Alloy Cost Volatility:Super-duplex stainless steel and titanium plate prices for marine scrubber internals swing with nickel and molybdenum commodity markets, compressing fabricator margins on fixed-price contracts.
- Shipyard Capacity Concentration:Retrofit installation slots cluster in Chinese yards around Shanghai and Guangzhou, creating 12-18 month backlogs that delay hardware revenue recognition.
- Open-Loop Scrubber Bans:Port authorities in Belgium, Germany, and parts of China prohibit discharge of washwater effluent, forcing expensive closed-loop system upgrades or fuel switching that undermines scrubber ROI.
Strategic Opportunities
- India Port Infrastructure Buildout:Jawaharlal Nehru Port Trust and Mundra Port are expanding container handling capacity, creating first-mover advantage for scrubber OEMs establishing local service depots.
- Carbon Capture Integration:Post-combustion amine scrubbing for cement and steel plants is converging with traditional SOx scrubber footprints, enabling combined EPC contracts for emissions stack retrofits.
- US Inflation Reduction Act Credits:Section 45Q carbon capture incentives are extending to industrial CO2 scrubbing installations, qualifying equipment for investment tax credits that improve project economics.
Industry Challenges
- Marine Surveyor Certification Bottlenecks:Flag state inspectors for Bahamas, Malta, and Cyprus lack sufficient trained personnel to clear scrubber installation certificates, extending vessel downtime.
- Legacy Control System Integration:Vessels with 1990s-era engine management platforms require custom PLC bridging to connect modern scrubber monitoring to ship-wide alarm networks.
- Washwater Treatment Chemistry Expertise:Operators struggle to source chemists familiar with buffering agent optimization for varying seawater alkalinity across trading routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scrubber Market |
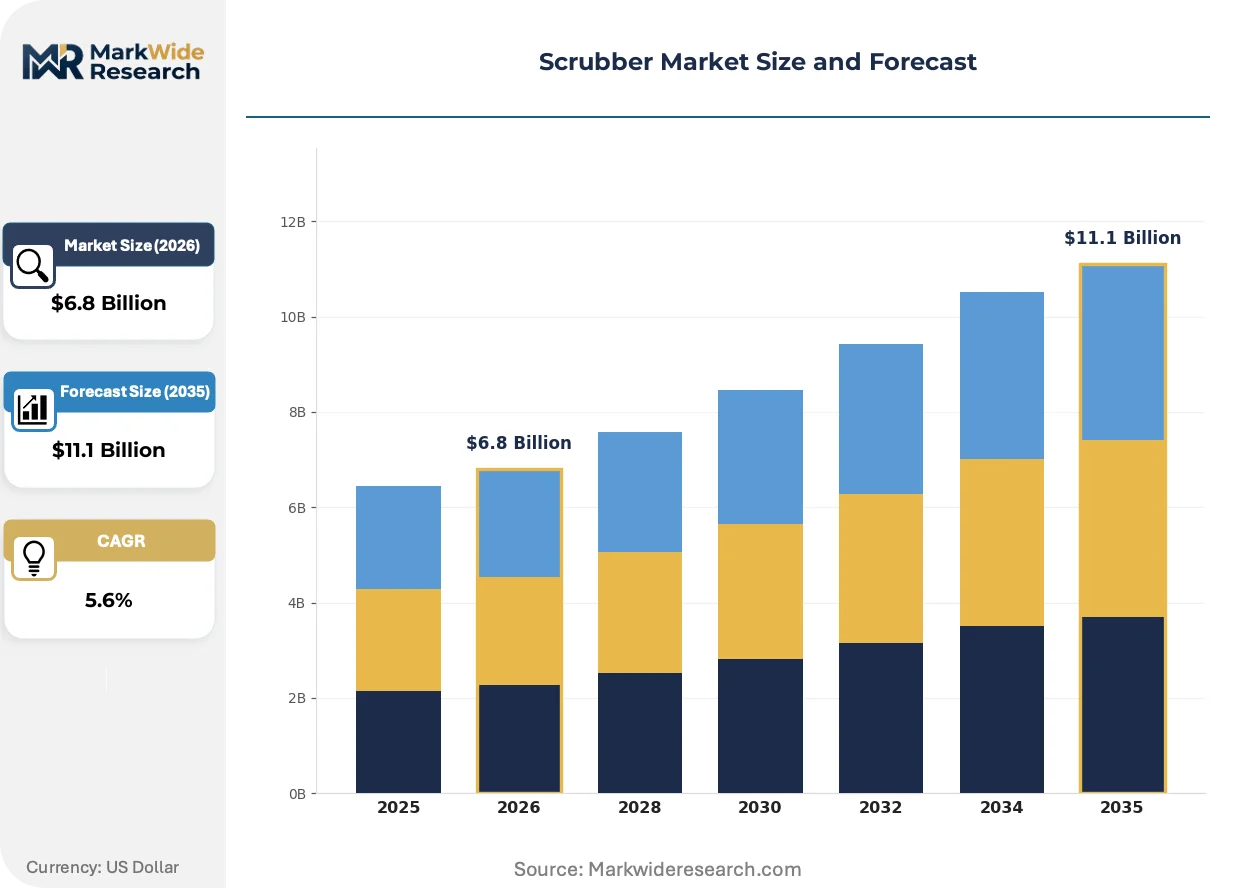
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Scrubbers, Dry Scrubbers, Electrostatic Precipitators, Carbon Adsorbers Application: Industrial Processes, Power Generation, Wastewater Treatment, Air Pollution Control Technology: Packaged Systems, Modular Solutions, Advanced Oxidation, Bioreactors End User: Manufacturing, Oil & Gas, Pharmaceuticals, Chemical Processing |
| Companies Covered | Alfa Laval, Wärtsilä, Babcock & Wilcox Enterprises, CECO Environmental, Yara Marine Technologies, DuPont, GEA Group, Fuji Electric, Nederman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scrubber Market Strategic Shifts
Scrubber technology is converging with adjacent emissions control systems, compressing the traditional separation between sulfur, particulate, and carbon capture hardware into unified stack solutions.
Hybrid scrubber architectures is unifying wet and dry contact stages within single vessel footprints. Marine operators on Asia-Europe routes are specifying these configurations to handle both high-sulfur residual fuels and variable port-state discharge rules. The technology is unifying what were separate EPC contracts into integrated performance guarantees covering SOx, particulate, and washwater effluent compliance.
REACH Annex XVII restrictions on nickel compound emissions are tightening material specifications for scrubber internals used in European chemical plants. German TÜV and DEKRA certification bodies are now requiring extended leach testing for alloy selections in food-contact pharmaceutical applications. Specialty chemical manufacturers in the Netherlands and Switzerland are accelerating replacement schedules for legacy packed-bed designs that cannot meet the revised migration limits.
Buyers are unbundling hardware procurement from installation and commissioning services. Large container lines with in-house technical teams are sourcing scrubber modules directly from fabricators in South Korea and China, then contracting local shipyards for fit-out only. This pattern is most pronounced among Singapore-flagged operators with established engineering departments, who are compressing supplier margins and forcing OEMs toward pure equipment sales or long-term service agreements.
Scrubber Market Segmentation
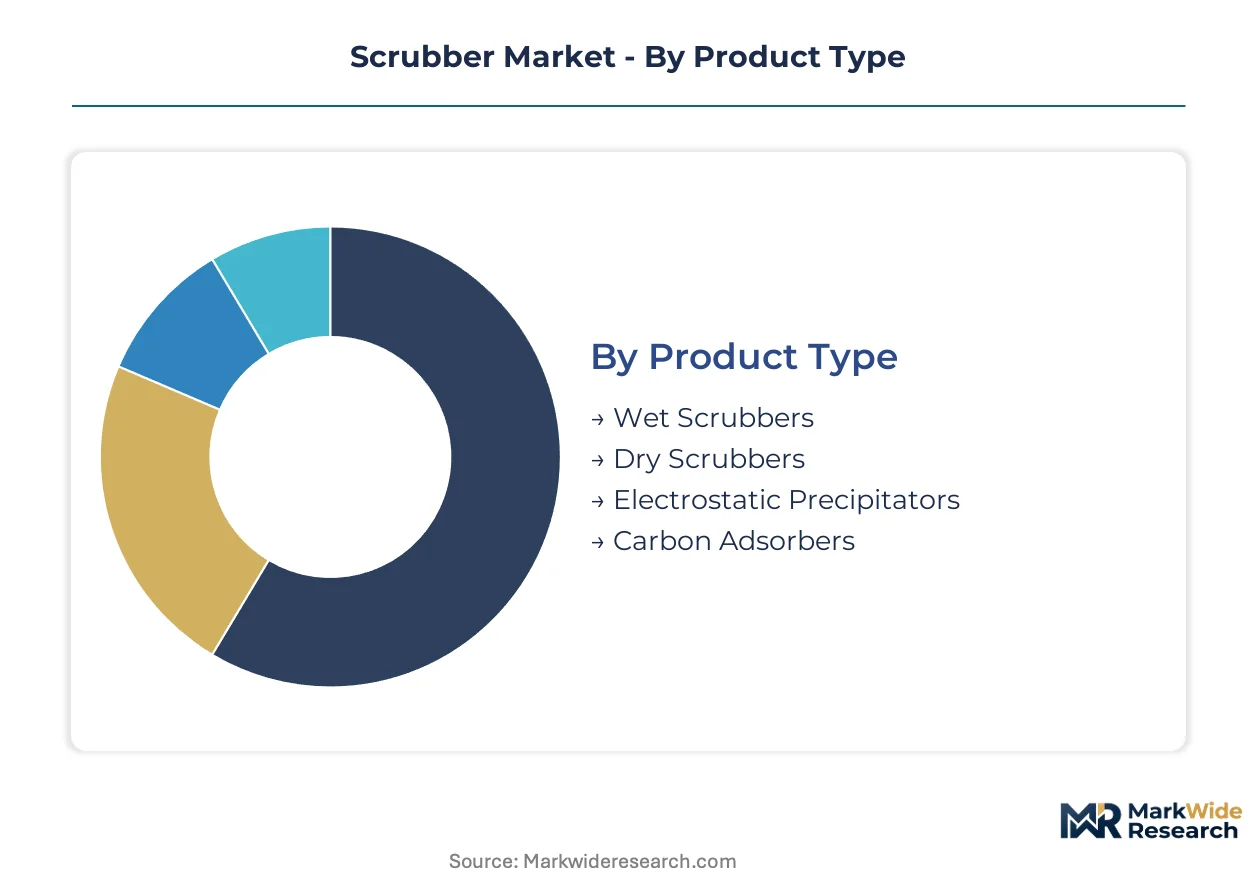
Scrubber procurement patterns diverge sharply across technology architectures and end-use constraints. Buyers in marine and chemical sectors prioritize different performance trade-offs than utility operators, fragmenting vendor strategies across these axes.
Product Type:
Technology selection hinges on effluent chemistry, water availability, and regulatory discharge permissions.
- Wet Scrubbers:Gas-liquid contact systems using aqueous reagents to absorb acid gases and particulates. Shipyards in South Korea and China specify these for open-loop marine retrofits where port discharge rules permit washwater release. IMO sulfur enforcement compresses installation timelines for this segment.
- Dry Scrubbers:Gas-solid reaction systems employing lime or sodium-based sorbents without liquid effluent. Power plants in water-stressed regions of Spain and Australia deploy these to eliminate wastewater handling. Fixed-bed designs dominate coal-fired retrofit contracts.
- Electrostatic Precipitators:High-voltage ionization systems capturing sub-micron particulates in cement and steel flue streams.
- Carbon Adsorbers:Activated carbon beds targeting volatile organic compounds and mercury in specialty chemical production.
Wet scrubbers lead on scale; dry scrubbers lead on momentum in water-constrained geographies.
Application:
End-use contexts impose distinct operating regimes, from continuous baseload duty to batch pharmaceutical campaigns.
- Industrial Processes:Scrubber trains handling variable load profiles in petrochemical crackers and smelters. German chemical complexes along the Rhine corridor are expanding wet scrubber capacity to process higher-sulfur feedstocks under EU Industrial Emissions Directive limits.
- Power Generation:Utility-scale arrays managing steady-state flue volumes from coal and biomass combustion. Dry scrubber deployments concentrate in US Midwest plants facing EPA Mercury and Air Toxics Standards compliance deadlines.
- Wastewater Treatment:Odor control and biogas purification systems at municipal anaerobic digesters.
- Air Pollution Control:Standalone installations for incinerator and coating operation exhaust streams.
Power generation leads on scale; industrial processes lead on momentum with feedstock flexibility investments.
Technology:
System packaging determines procurement flexibility and total installed cost structures.
- Packaged Systems:Factory-assembled skid-mounted units with integrated controls and instrumentation. Pharmaceutical cleanrooms in Switzerland and Singapore specify these for rapid qualification under TÜV and HSA guidelines. Premium pricing reflects documentation and validation burdens.
- Modular Solutions:Component-based architectures permitting field assembly and future expansion. Oil and gas operators in the US Permian Basin favor these for redeployment across wellpad locations. Fabricators in Houston and Dubai maintain rental fleets for short-cycle projects.
- Advanced Oxidation:UV-ozone and photocatalytic systems destroying refractory organics in semiconductor effluent.
- Bioreactors:Microbial degradation systems for biodegradable volatile compounds in food processing.
Packaged systems lead on scale; modular solutions lead on momentum with unbundled procurement trends.
End User:
Industry-specific emissions profiles and regulatory exposure shape scrubber specification priorities.
- Manufacturing:Metal finishing, electronics assembly, and automotive coating operations generating acid mist and solvent vapors. Japanese automotive suppliers in Aichi Prefecture are retrofitting chromium plating lines with dedicated scrubber ventilation under METI air quality mandates.
- Oil & Gas:Refinery sulfur recovery units and offshore platform flare gas treatment. Saudi Aramco's Jazan complex represents a concentrated demand node for high-capacity wet scrubber trains.
- Pharmaceuticals:Solvent recovery and containment systems for potent compound manufacturing.
- Chemical Processing:Chlor-alkali and fertilizer production with halogen acid handling requirements.
Oil and gas leads on scale; pharmaceuticals lead on momentum with containment technology upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scrubber technology first achieved industrial scale in German chemical corridors during the 1970s, when BASF and Bayer installed pioneering wet scrubber trains along the Rhine. That engineering heritage now diffuses across three continents through licensing, joint ventures, and supplier migration.
China
Shipyards in Shanghai and Guangzhou dominate marine scrubber retrofit installation, handling over 60 percent of global vessel upgrades. The Ministry of Ecology and Environment enforces increasingly stringent port emissions standards that parallel IMO sulfur caps. Dalian and Qingdao chemical complexes are adding wet scrubber capacity to process higher-sulfur crude slates from Russian and Middle Eastern sources.
Germany
Rhine corridor chemical plants under the EU Industrial Emissions Directive are replacing legacy packed-bed scrubbers with closed-loop systems. TÜV and DEKRA certification bodies now mandate extended alloy leach testing for food-contact pharmaceutical applications. BASF's Ludwigshafen complex represents Europe's largest concentrated demand node for scrubber replacement cycles.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries integrate scrubber modules into newbuild vessel specifications at Ulsan and Geoje shipyards. The Korean Register of Shipping accelerated type-approval timelines for hybrid scrubber configurations. Busan port authority mandates closed-loop operation within harbor limits, forcing technology upgrades on retrofitted fleets.
United States
Gulf Coast petrochemical complexes from Corpus Christi to Lake Charles are expanding wet scrubber trains for Permian Basin feedstock flexibility. EPA Mercury and Air Toxics Standards drive dry scrubber deployments at Midwest coal plants facing compliance deadlines. Section 45Q carbon capture incentives under the Inflation Reduction Act now extend to industrial CO2 scrubbing installations.
India
Jawaharlal Nehru Port Trust and Mundra Port container expansion creates first-mover opportunity for scrubber OEMs establishing local service depots. Central Pollution Control Board norms for port emissions are tightening toward IMO-equivalent standards. Reliance Industries' Jamnagar refinery complex represents the largest single-site demand for sulfur recovery scrubber capacity in South Asia.
Scrubber Market Competitive Environment
The competitive structure tilts toward integrated platform providers with marine aftermarket networks. Three to five engineering conglomerates anchor the premium tier through vessel optimization software and long-term service agreements. Mid-tier fabricators compete on modular component sourcing and rapid field assembly. Dominant competitive moves include geographic expansion through local service depot establishment and technology licensing for hybrid wet-dry architectures.
Among Nordic marine specialists, Alfa Laval and Wärtsilä occupy positions defined by aftermarket density and integrated vessel platforms respectively. Babcock & Wilcox Enterprises anchors the utility-scale dry scrubber segment with coal-fired plant retrofit expertise. These three exemplify how engineering heritage and regulatory timing shape competitive positioning across marine and stationary source applications.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| Babcock & Wilcox Enterprises |
| CECO Environmental |
| Yara Marine Technologies |
| DuPont |
| GEA Group |
| Fuji Electric |
| Nederman |
| Others |
Value Chain & Pricing Dynamics
Marine welding specialists concentrated in South Korean shipyards at Ulsan and Geoje command wage premiums that compress margins on fixed-price scrubber contracts, widening spreads between premium turnkey packages and economy modular kits sourced from Chinese fabricators.
Pricing Analysis
Project-based EPC contracting dominates marine retrofits, with pricing stratifying across premium, standard, and economy tiers based on certification grade and after-sales bundling. TÜV and Korean Register of Shipping certification tiers separate premium offerings from uncertified economy alternatives. Cost compression in the economy tier is intensifying because container lines with in-house engineering teams unbundle hardware from installation services. Singapore-flagged operators with established technical departments exhibit lowest price sensitivity; smaller Greek and Cypriot operators dependent on external project management show highest sensitivity.
Supply Chain Analysis
Refurbishment flows for marine scrubber internals cycle through service depots in Singapore, Rotterdam, and Dubai before re-entering regional retrofit programs. Manufacturing concentration rests on South Korea, China, and Germany for specialized alloy fabrication and control system assembly. Super-duplex stainless steel and titanium plate feed from nickel and molybdenum commodity markets; PLC and sensor packages draw from German and Japanese automation suppliers. Single-source vulnerability concentrates in Chinese shipyard installation slots around Shanghai and Guangzhou. Distribution runs through OEM-direct channels for premium tier, regional fabricator networks for standard tier, and equipment rental fleets for economy tier oil and gas field deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scrubber market margins expand through chemist workforce scarcity in washwater treatment optimization, forcing buyers toward premium service contracts that embed technical labor costs.
For Market Incumbents: Lock in long-term service agreements with Singapore-flagged container lines before in-house engineering teams mature their direct sourcing capabilities. Deepen backward integration into super-duplex alloy fabrication through captive supply agreements with South Korean foundries to offset nickel price volatility. Priority lever: hybrid wet-dry scrubber certification investment to capture Busan and Rotterdam port authority mandates. For New Entrants and Emerging Players: Direct-to-shipowner digital platforms bypass incumbent distributor networks for modular component sales. Target Indian port infrastructure buildout at Jawaharlal Nehru Port Trust and Mundra Port where local service depot presence remains underdeveloped. White-space angles: closed-loop system upgrades for open-loop scrubber fleets facing Belgian and German port bans; rental fleet models for Permian Basin oil and gas redeployment cycles. For Investors and Strategic Acquirers: Marine engineering conglomerates with vessel optimization software platforms are the most active acquirer in this space, consolidating aftermarket service density. Five-to-ten year viability hinges on carbon capture integration convergence with traditional SOx scrubber footprints. Acquisition target archetype: regional fabricators with Korean Register of Shipping or TÜV certification credentials and established shipyard relationships. Signal to monitor: EPA Section 45Q credit rulemaking for industrial CO2 scrubbing eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Scrubber Certification Investment | Korean Register of Shipping accelerated timelines capture Busan port closed-loop mandates. |
| Backward Integration into Alloy Fabrication | Captive super-duplex supply from Ulsan foundries insulates against nickel commodity swings. |
| Local Service Depot Establishment | Jawaharlal Nehru Port Trust expansion creates first-mover advantage in Indian retrofit cycles. |
| Carbon Capture Integration Development | Combined EPC contracts for SOx and CO2 stack retrofits access IRA Section 45Q incentives. |
| Direct Digital Platform Launch | Shipowner-direct modular sales compress incumbent distributor margins on standard-tier hardware. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged marine engineering directors at container lines, shipyard procurement managers at Hyundai Heavy Industries and Shanghai Waigaoqiao, scrubber OEM aftermarket heads, and classification society surveyors at Lloyd's Register and Bureau Veritas. Secondary validation drew from IMO circulars on sulfur cap enforcement, EU Industrial Emissions Directive implementation guidance, EPA MATS compliance databases, and customs trade data on scrubber component shipments. Bottom-up vessel-by-vessel retrofit demand modeling triangulated against top-down shipyard capacity and alloy consumption estimates.
Historical reference periods anchored the projection framework through scrubber installation cycle analysis and regulatory phase-in timing across the analysis window. Segmentation dimensions modeled include wet versus dry technology architecture, marine versus stationary source application, packaged versus modular system packaging, and IMO flag state regulatory cluster. CAGRs derived from shipyard slot availability constraints, alloy price trajectory assumptions, and port authority discharge rule adoption curves. Industry-specific inputs incorporated marine dry-docking schedule density and EU F-Gas Regulation phase-down timelines for industrial refrigeration retrofit demand.
The model assumes a particular technology adoption path; alternative pathways for amine-based carbon capture scrubbing would alter the outlook for combined SOx and CO2 system demand. Forecasts reflect assumptions on shipyard capacity expansion rates, flag state inspector certification throughput, and nickel alloy price stabilization. Practitioners should monitor EPA Section 45Q rulemaking developments, Belgian and German port authority open-loop ban enforcement patterns, and Chinese Ministry of Ecology and Environment port emissions standard tightening for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Scrubber System Market