
 Flue Gas Analyzers Market | 2026-2036
Flue Gas Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Flue Gas Analyzers Market Analysis
The flue gas analyzer market is recalibrating around a widening split between premium multi-gas systems with laser-based detection and commodity electrochemical units serving basic compliance needs. ABB leverages its integrated automation platform to bundle analyzers with distributed control systems for power utility clients. Testo sustains dominance in the portable segment through channel density across European HVAC service networks. Siemens anchors its position in stationary installations via long-term service contracts with German industrial manufacturing sites.
Flue gas analyzers are precision instruments that measure combustion byproducts including oxygen, carbon monoxide, nitrogen oxides, and sulfur dioxide using electrochemical cells, infrared absorption, or tunable diode laser spectroscopy with detection thresholds reaching parts-per-billion sensitivity. Their primary purpose is optimizing fuel-air ratios for thermal efficiency while verifying compliance with legally mandated emission limits. Portable analyzers command the highest replacement frequency due to sensor degradation in field conditions, whereas laser technology segments extract premium pricing from continuous emission monitoring systems at waste incineration facilities. Electrochemical sensors remain the volume workhorse for combustion efficiency applications in smaller industrial boilers where capital constraints limit technology upgrades.
The EPA enforces Maximum Achievable Control Technology standards that mandate continuous emission monitoring systems at major power plants, directly shaping analyzer specification requirements and recertification cycles. The EU's Industrial Emissions Directive and F-Gas Regulation impose parallel obligations across member states, with Germany's Federal Emission Control Act adding national calibration protocols that vendors must satisfy for market access. Stakeholders should monitor evolving methane slip regulations for gas turbines, as emerging measurement protocols could displace incumbent infrared platforms with more sensitive laser absorption systems in utility procurement decisions.
Market Dynamics
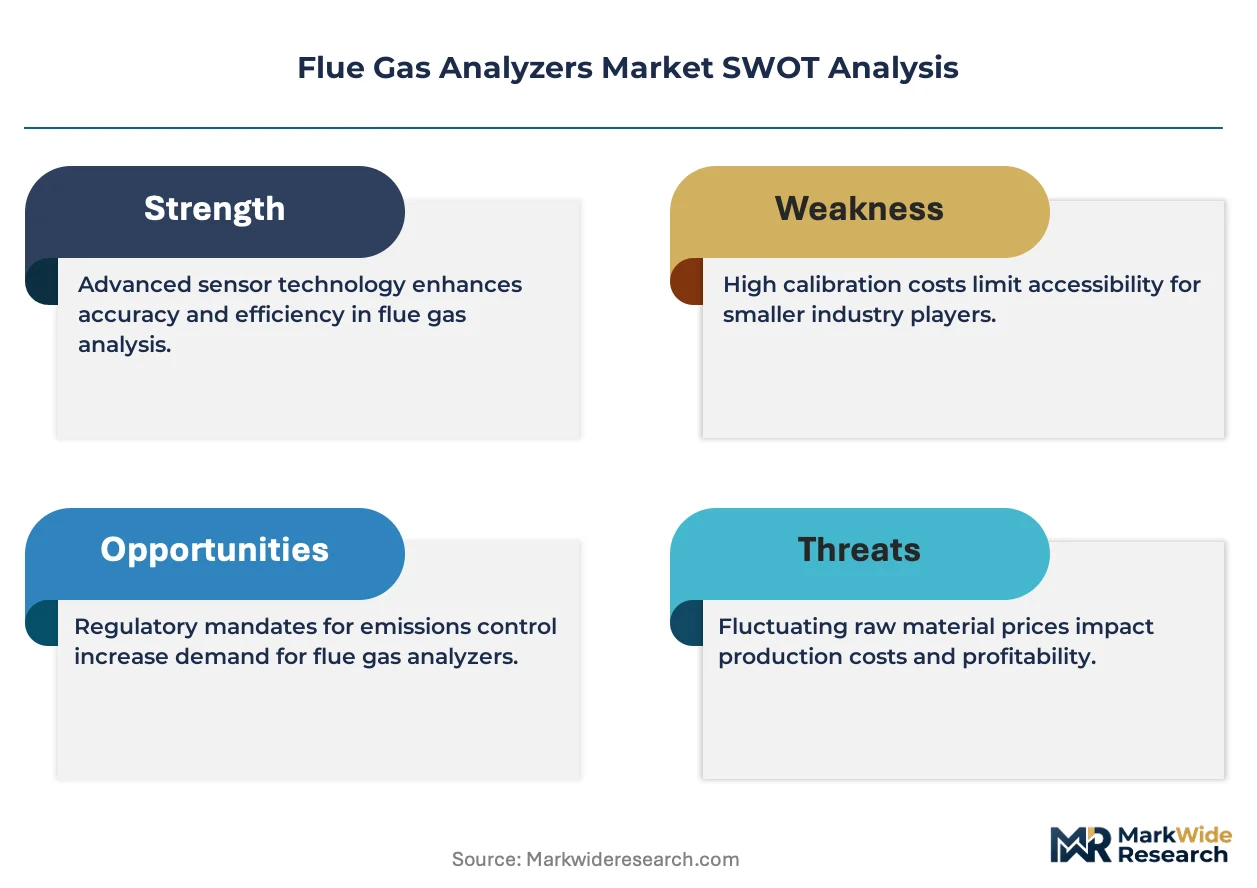
The flue gas analyzer market is splitting sharply between premium laser-based multi-gas systems and commodity electrochemical units, driven by divergent compliance requirements across power generation and industrial boiler segments.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:These mandates force continuous emission monitoring system installations at major US power plants, creating sustained replacement cycles for certified analyzer hardware.
- Coal-to-gas plant conversions:Germany's Federal Emission Control Act drives analyzer upgrades as utilities retrofit combustion systems for natural gas, requiring new multi-gas measurement protocols.
- Tunable diode laser spectroscopy:This detection technology enables parts-per-billion sensitivity for mercury and ammonia tracking, opening utility procurement for advanced stationary installations.
Market Restraints
- Electrochemical sensor degradation:Portable analyzers require 12-18 month replacement cycles in field conditions, creating lifecycle cost barriers for small industrial boiler operators.
- Calibration infrastructure concentration:Germany hosts the majority of EU-certified reference gas facilities, forcing non-German vendors to absorb cross-border logistics for compliance verification.
- Infrared platform obsolescence risk:Emerging methane slip measurement protocols for gas turbines threaten displacement of incumbent non-dispersive infrared systems before depreciation cycles complete.
Strategic Opportunities
- Waste incineration facility expansion:Continuous emission monitoring mandates in EU member states create demand for laser absorption systems at municipal waste-to-energy plants.
- HVAC service network channel penetration:Portable analyzer vendors can expand through technician certification programs tied to combustion efficiency auditing requirements.
- EU F-Gas Regulation alignment:Analyzer manufacturers integrating refrigerant leak detection capabilities access cross-selling opportunities into building automation procurement.
Industry Challenges
- TDLAS technician scarcity:Tunable diode laser spectroscopy maintenance requires specialized optical alignment skills that field service networks struggle to recruit.
- Legacy DCS integration friction:Analyzer vendors face extended commissioning timelines when connecting new hardware to aging distributed control systems at industrial manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flue Gas Analyzers Market |
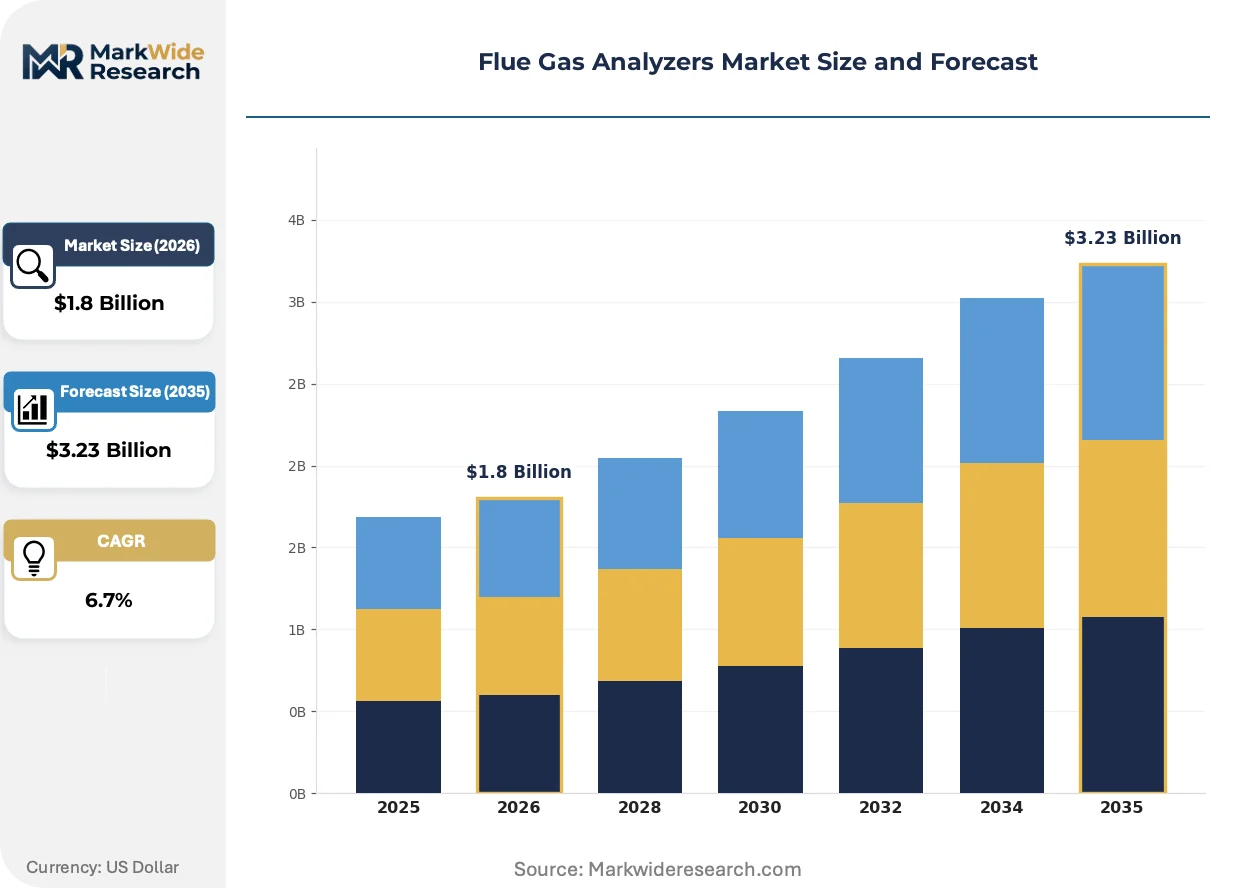
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, Fixed Analyzers, Multi-Gas Analyzers Technology: Infrared Technology, Electrochemical Sensors, Paramagnetic Technology, Laser Technology End User: Power Plants, Industrial Manufacturing, Waste Incineration, Research Laboratories Application: Emission Monitoring, Combustion Efficiency, Regulatory Compliance, Indoor Air Quality |
| Companies Covered | Teledyne Analytical Instruments, Testo, Emerson Electric Co., Nova Analytical Systems, Siemens, ABB, Horiba, Sick AG, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flue Gas Analyzers Market Emerging Trajectories
Analyzer technology is pivoting from discrete measurement instruments toward integrated emission data platforms, compressing the boundary between hardware vendors and industrial software providers.
Laser absorption spectroscopy is converging with cloud-based emission reporting platforms, enabling real-time data transmission directly to regulatory submission portals. Waste incineration operators in the Netherlands and Denmark are piloting these integrated systems to automate compliance documentation. This convergence is compressing the traditional separation between analyzer hardware procurement and industrial IT infrastructure decisions.
The EU's Industrial Emissions Directive is tightening continuous monitoring requirements for nitrogen oxides and sulfur dioxide at medium combustion plants. Germany's Federal Emission Control Act adds national calibration protocols that foreign vendors must satisfy for market access. Power utilities across Bavaria and North Rhine-Westphalia are accelerating analyzer replacement cycles to meet 2025 recertification deadlines.
Service contract unbundling is fragmenting the stationary analyzer market, with industrial buyers separating hardware procurement from multi-year maintenance agreements. German chemical manufacturers are driving this shift, negotiating direct sensor replacement schedules rather than comprehensive vendor-managed service. This pattern is most visible in the Rhine-Ruhr industrial cluster, where procurement teams prioritize operational expenditure flexibility over capital bundling.
Flue Gas Analyzers Market Segmentation
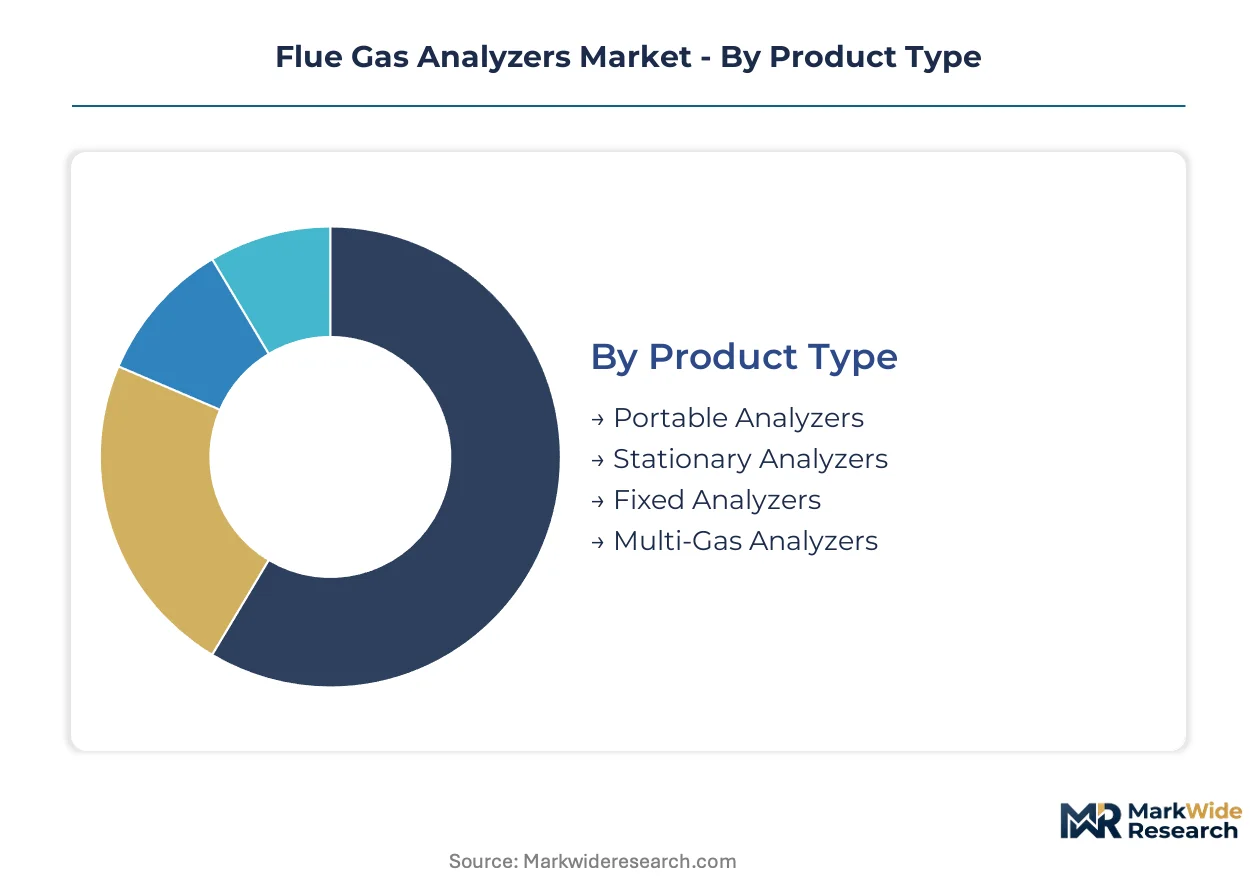
Segmentation in flue gas analyzers reflects divergent procurement logics across compliance-driven utilities and efficiency-focused industrial operators. Technology choices cascade through product form factors, end-use specifications, and application workflows with limited substitutability between tiers.
Product Type:
Supply concentration tilts toward stationary systems as German utilities and EU waste incineration operators consolidate procurement around certified continuous monitoring platforms.
- Portable Analyzers:Handheld units with electrochemical sensor arrays dominate HVAC service technician toolkits across European maintenance networks. Replacement cycles compress to 12-18 months in high-humidity field conditions, creating recurring revenue concentration for sensor suppliers.
- Stationary Analyzers:Rack-mounted continuous emission monitoring systems anchor utility procurement at coal-to-gas conversion sites in North Rhine-Westphalia. Long-term service contracts with calibration obligations lock in vendor relationships across depreciation cycles.
- Fixed Analyzers:Wall-mounted installations serve medium combustion plants under tightening EU Industrial Emissions Directive thresholds.
- Multi-Gas Analyzers:Configurable platforms integrating multiple detection technologies command premium positioning at waste-to-energy facilities.
Today's leader: Stationary Analyzers. Tomorrow's challenger: Multi-Gas Analyzers.
Technology:
Cost tier stratification separates premium laser platforms from volume electrochemical deployments, with mid-range infrared facing displacement risk from emerging methane slip protocols.
- Infrared Technology:Non-dispersive infrared absorption serves established nitrogen oxides and sulfur dioxide measurement at legacy power installations. Dutch and Danish waste incineration pilots are testing cloud-integrated variants for automated regulatory submission.
- Electrochemical Sensors:Solid-state cells measuring oxygen, carbon monoxide, and nitrogen oxides remain the volume workhorse for combustion efficiency applications. Capital constraints at smaller industrial boilers in Germany's Mittelstand sector sustain demand despite shorter operational lifespans.
- Paramagnetic Technology:Oxygen-specific measurement using magnetic susceptibility differentials occupies niche calibration reference roles.
- Laser Technology:Tunable diode laser spectroscopy enables parts-per-billion mercury and ammonia detection at utility scale.
Laser Technology is climbing the fastest. Electrochemical Sensors retain volume dominance.
End User:
Application intensity varies sharply across end users, with power generation demanding continuous monitoring density while research laboratories prioritize analytical precision over uptime metrics.
- Power Plants:EPA Maximum Achievable Control Technology standards mandate certified analyzer installations at major US facilities. German utilities in Bavaria face 2025 recertification deadlines under Federal Emission Control Act protocols.
- Industrial Manufacturing:Chemical producers in the Rhine-Ruhr cluster are unbundling service contracts, negotiating direct sensor replacement schedules rather than comprehensive vendor-managed maintenance.
- Waste Incineration:Municipal waste-to-energy expansion across EU member states drives laser absorption system procurement.
- Research Laboratories:Academic and institutional users require trace-level detection capabilities for method development and calibration standard production.
Power Plants anchor current procurement volume. Waste Incineration shows steepest expansion trajectory.
Application:
Customer type bifurcation separates regulatory compliance buyers with mandated specification requirements from efficiency optimizers with discretionary upgrade timelines.
- Emission Monitoring:Continuous data streams for regulatory submission portals dominate utility procurement specifications. Real-time transmission requirements are compressing hardware and software procurement decisions.
- Combustion Efficiency:Fuel-air ratio optimization drives portable analyzer deployment across commercial and industrial boiler service networks. Technician certification programs tied to auditing requirements channel purchasing decisions.
- Regulatory Compliance:Periodic verification and documentation workflows sustain replacement cycles for certified reference equipment.
- Indoor Air Quality:Building automation integration opportunities emerge from EU F-Gas Regulation alignment for refrigerant leak detection crossover.
Emission Monitoring commands specification authority. Combustion Efficiency sustains replacement frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized calibration technicians cluster in Germany's Rhine-Ruhr and Bavaria regions, anchoring European analyzer service capacity. German utilities drive multi-gas system procurement for coal-to-gas conversions. US EPA enforcement creates continuous monitoring demand across Midwest and Southeast power corridors.
United States
Midwest power plant operators deploy continuous emission monitoring systems to satisfy EPA Maximum Achievable Control Technology standards. The agency's Mercury and Air Toxics Standards mandate analyzer recertification cycles at major facilities. Ohio River Valley coal plants accelerate replacement timelines ahead of enforcement deadlines.
Germany
Coal-to-gas conversions in North Rhine-Westphalia require advanced multi-gas measurement protocols for retrofitted combustion systems. The Federal Emission Control Act imposes national calibration standards that foreign vendors must satisfy. Bavarian utilities face 2025 recertification deadlines under tightening state-level protocols.
Netherlands
Waste-to-energy facility expansion drives laser absorption system procurement for municipal incineration operators. The EU Industrial Emissions Directive tightens nitrogen oxides monitoring thresholds for medium combustion plants. Rotterdam industrial clusters pilot cloud-integrated emission reporting platforms for automated regulatory submission.
China
Power sector emission control enforcement expands analyzer deployment at provincial coal plants under MEE supervision. National dual carbon goals accelerate continuous monitoring upgrades for carbon dioxide tracking. Yangtze River Delta manufacturing hubs integrate combustion efficiency auditing into environmental compliance workflows.
India
Central Electricity Authority mandates drive analyzer installation at thermal power stations for particulate matter and sulfur dioxide tracking. National ambient air quality standards tighten enforcement across industrial boiler operations. Gujarat and Maharashtra industrial corridors adopt portable electrochemical units for combustion optimization in small and medium enterprises.
Flue Gas Analyzers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the flue gas analyzer market, creating a tiered structure where integrated automation platforms face modular specialists. The vendor base splits between diversified industrial conglomerates bundling analyzers with control systems and focused instrumentation houses serving discrete compliance niches. Strategic archetypes include full-stack automation integrators, portable device specialists, and laser spectroscopy technology licensors. Competitive moves concentrate on long-term service contract capture and calibration infrastructure control.
Among diversified industrial conglomerates, Siemens and ABB exemplify the integrated platform archetype, anchoring stationary system procurement through bundled distributed control system relationships. Testo occupies a distinct position within the portable segment, representing the channel-density specialist model across European HVAC service networks. Sick AG exemplifies the precision instrumentation house archetype, sitting within the German industrial automation cluster with established calibration protocol compliance.
| Leading Market Players |
|---|
| Teledyne Analytical Instruments |
| Testo |
| Emerson Electric Co. |
| Nova Analytical Systems |
| Siemens |
| ABB |
| Horiba |
| Sick AG |
| AMETEK |
| Others |
Supply Flow & Price Mechanics
German utility procurement teams concentrating demand for coal-to-gas conversion projects enforce bundled service contracts that compress margins for standalone hardware vendors. This buyer concentration anchors a pricing model where long-term calibration obligations and recertification cycles determine total cost of ownership rather than upfront equipment expenditure.
Pricing Analysis
The bundled-versus-unbundled service split is restructuring competitive positioning across stationary system tiers. Three-tier pricing structure across premium laser platforms, mid-range infrared systems, and economy electrochemical units separates vendors by detection sensitivity and calibration protocol compliance. Price differentiation rests on certification grade under Germany's Federal Emission Control Act and after-sales service density in the Rhine-Ruhr industrial cluster. Cost compression in the electrochemical segment is intensifying because portable analyzer replacement cycles compress under field humidity stress. Small industrial boiler operators in Germany's Mittelstand sector exhibit highest price sensitivity, while waste incineration utilities in the Netherlands and Denmark absorb premium positioning for mercury detection capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Germany's concentration of EU-certified reference gas facilities for calibration verification. Manufacturing draws from Germany, the United States, and Japan for precision optical components, electrochemical sensor cells, and tunable diode laser assemblies. Raw material dependencies include rare-earth elements for laser diodes, specialized ceramics for sensor housings, and high-purity reference gases for calibration standards. Tariff exposure on Chinese-sourced electronic subassemblies threatens cost stability for mid-tier vendors. Distribution runs through authorized service networks with technician certification requirements, locking out direct channel approaches for compliance-critical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flue gas analyzer market functions as a stable compounder where regulatory recertification cycles generate predictable replacement revenue regardless of macroeconomic volatility. EPA and EU enforcement timelines create annuity-like demand visibility for vendors with certified calibration infrastructure.
For Market Incumbents: To counter service contract unbundling by German chemical manufacturers in the Rhine-Ruhr cluster, deepen calibration protocol exclusivity through Federal Emission Control Act accreditation investments and acquire regional service providers to restore bundled offering control.
For New Entrants and Emerging Players: Enter via cloud-integrated emission reporting platforms for Dutch and Danish waste incineration pilots, targeting the white-space between hardware procurement and industrial IT infrastructure decisions with software-first positioning and regulatory submission automation capabilities.
For Investors and Strategic Acquirers: Industrial automation conglomerates with distributed control system platforms are the most active acquirer in this space, seeking analyzer technology to complete emission monitoring stacks. Over a multi-year holding period, target precision instrumentation houses with established German calibration compliance and laser spectroscopy IP. Monitor methane slip measurement protocol finalization for gas turbines as the inflection signal that would accelerate displacement of incumbent infrared platforms and trigger consolidation among technology-orphaned vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Spectroscopy Technology Licensing | Tunable diode laser spectroscopy IP unlocks parts-per-billion mercury detection contracts at EU waste-to-energy facilities. |
| Calibration Infrastructure Acquisition | Control of Germany's reference gas facilities creates compliance bottlenecks that foreign competitors cannot bypass. |
| Cloud Platform Integration | Real-time emission data transmission to EPA and EU regulatory portals compresses hardware-software procurement decisions. |
| Technician Certification Program Expansion | HVAC service network density in European maintenance channels secures portable analyzer replacement cycle capture. |
| Multi-Gas System Portfolio Extension | Configurable platforms address coal-to-gas conversion demand in North Rhine-Westphalia utility procurement. |
Methodological Framework
Bottom-up power plant and industrial manufacturing modeling reconciled against top-down analyzer vendor shipment tracking forms the analytical core of this study. Primary interviews with utility environmental compliance officers, HVAC service network managers, calibration facility technicians, and industrial procurement directors combined with secondary validation against EPA enforcement databases, EU Industrial Emissions Directive implementation reports, and German Federal Emission Control Act accreditation records. Top-down trade data and bottom-up installation tracking were cross-referenced to reconcile volume estimates.
Input-output matrix framing maps detection technology adoption curves against regulatory deadline schedules across the projection horizon. Segmentation dimensions modeled include product form factor, detection technology tier, end-use vertical, and application workflow with regional regulatory cluster overlays. CAGRs were derived from fitted adoption curves rather than linear extrapolation, incorporating coal-to-gas conversion timelines in Germany and EPA recertification cycle phasing as industry-specific forecast inputs.
Inputs from EPA enforcement databases and EU member state implementation reports were available through the study window; gaps in real-time utility procurement pipeline visibility introduce uncertainty bands around near-term replacement cycle timing. Forecasts reflect documented assumptions regarding regulatory deadline adherence and technology transition rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Ozone Generator Market