
 Manufacturing Scale Electrostatic Precipitator Market | 2026-2036
Manufacturing Scale Electrostatic Precipitator Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Scale Electrostatic Precipitator Market Insights
Market Context
Cement production is realigning toward wet electrostatic precipitator systems as kiln operators face stricter mercury and fine particulate standards. ANDRITZ GROUP leverages its Austrian engineering base to dominate European retrofit contracts for dry-to-wet conversions. Babcock & Wilcox sustains technology leadership in high-voltage transformer design for North American power generation clients. Thermax anchors Indian market presence through localized manufacturing of pulse-jet configurations for steel mills.
Technical Definition and Segment Structure
A manufacturing scale electrostatic precipitator is an industrial gas-cleaning device that applies high-voltage corona discharge—typically 30 to 100 kilovolts—to ionize particulate matter in exhaust streams, collecting charged particles on grounded electrode surfaces for removal as dry dust or liquid slurry. Dry electrostatic precipitator systems occupy the largest installed base globally due to decades of deployment in coal-fired power generation, though wet electrostatic precipitator configurations represent the fastest-growing product category as chemical processing and food processing facilities adopt them for sticky or hygroscopic particulate capture. Pulse-jet electrostatic precipitator technology concentrates margin pools in specialized steel manufacturing applications requiring intermittent high-energy cleaning cycles.
Regulatory Environment and Outlook
The US EPA Mercury and Air Toxics Standards and the EU Industrial Emissions Directive enforce continuous particulate monitoring thresholds that directly determine ESP specification requirements for power generation and cement production facilities. China's MEE enforces ultra-low emission standards below 10 milligrams per cubic meter for steel manufacturing, while India's CEA mandates electrostatic precipitator upgrades for thermal plants exceeding 25-year operational life. Stakeholders must monitor evolving electrode material standards and corona discharge efficiency benchmarks as regulatory agencies tighten verification protocols for hybrid system performance claims.
Market Dynamics
The migration from dry to wet electrostatic precipitator configurations is compressing retrofit timelines across cement and steel sectors as mercury emission thresholds tighten. Equipment suppliers face compressed delivery schedules while balancing electrode material sourcing constraints.
Growth Catalysts
- China's MEE ultra-low emission mandate:Steel manufacturers in Hebei and Jiangsu provinces must achieve below 10 milligrams per cubic meter particulate discharge, forcing wholesale system replacements.
- Wet ESP technology maturation:Sticky particulate capture capabilities now extend to food processing and chemical manufacturing, opening adjacent industrial verticals previously served by baghouse alternatives.
- India's PLI scheme for clean technology:Domestic manufacturing incentives are accelerating localized production of pulse-jet configurations, reducing import dependence for steel mill operators.
Market Restraints
- High-voltage transformer supply concentration:Specialty transformer winding capacity clusters in Germany and Japan, creating 18-24 month order backlogs for large-scale installations.
- Corona electrode material cost volatility:Tungsten and titanium alloy prices fluctuate with rare earth export quotas, directly impacting system pricing stability.
- Baghouse technology substitution in sub-50 MW applications:Lower capital requirements and simpler maintenance protocols attract biomass and small industrial boiler operators.
Strategic Opportunities
- Hybrid dry-wet system integration:Cement kilns in Vietnam and Indonesia present untapped demand for sequential particulate and acid gas capture configurations.
- Digital twin predictive maintenance:Real-time corona discharge monitoring combined with machine learning algorithms enables outcome-based service contracting.
- EU Carbon Border Adjustment Mechanism:Importing steel and cement producers face embedded emissions scrutiny, creating pull for verified ESP performance documentation.
Industry Challenges
- Corona discharge optimization expertise scarcity:Field engineers capable of tuning 100 kilovolt systems across varying particulate loads command premium compensation, constraining deployment velocity.
- Legacy control system integration complexity:Pre-2010 installations rely on proprietary PLC architectures that resist modern SCADA connectivity without substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Scale Electrostatic Precipitator Market |
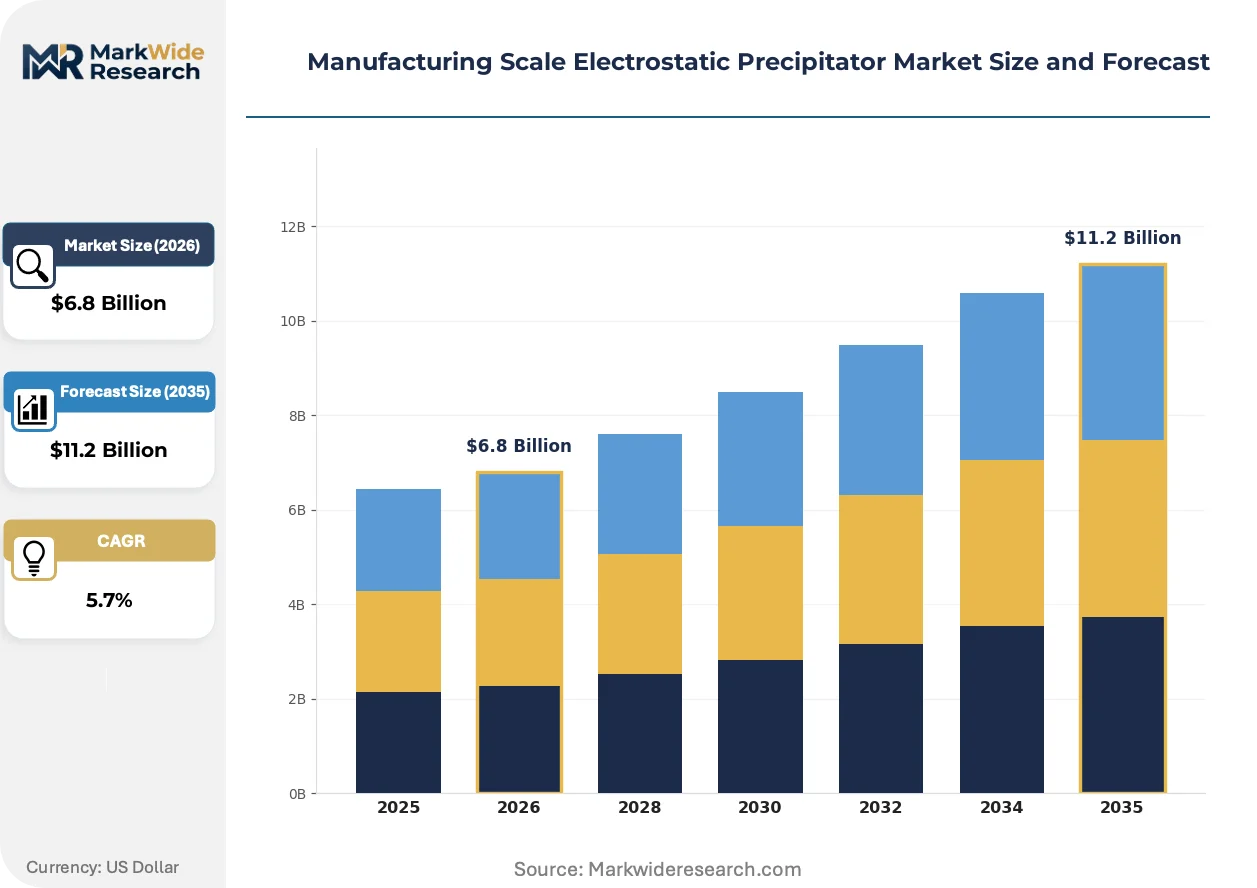
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Electrostatic Precipitator, Wet Electrostatic Precipitator, Hybrid Electrostatic Precipitator, Pulse-Jet Electrostatic Precipitator Technology: Corona Discharge, High Voltage Transformer, Electrodes Configuration, Dust Collection Method Application: Power Generation, Cement Production, Steel Manufacturing, Chemical Processing, Food Processing End User: Heavy Industries, Metal Fabrication Plants, Pulp & Paper Mills, Textile Manufacturers |
| Companies Covered | ANDRITZ GROUP, Babcock & Wilcox, Thermax, GEA Group, Mitsubishi Heavy Industries, FLSmidth, Siemens, Fujian Longking, Balcke-Dürr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Scale Electrostatic Precipitator Market Trends and Innovations
Pulse-jet cleaning cycles are compressing maintenance windows while electrode material science extends operational lifespans. Three converging developments are restructuring competitive positioning across wet, dry, and hybrid system categories.
Advanced ceramic composite electrodes are electrifying corona discharge efficiency in high-temperature exhaust streams above 400 degrees Celsius. Cement kiln operators in China and Turkey are adopting these configurations to reduce rapping energy consumption. The technology is electrifying margin structures for retrofit specialists capable of delivering temperature-resistant installations without structural housing modifications.
The EU Industrial Emissions Directive's 2025 review cycle is tightening continuous monitoring verification protocols for particulate measurement systems. Cement and waste-to-energy facilities must demonstrate correlation between stack monitors and ESP performance parameters. German and Polish operators are accelerating procurement of integrated sensor packages to preempt enforcement actions.
Steel manufacturers are consolidating maintenance contracts under single-source performance guarantees that bundle electrode replacement, transformer servicing, and emissions compliance verification. Japanese and South Korean mill operators pioneered these arrangements; Indian producers are now adopting similar structures. Channel intermediaries lacking technical service capabilities face displacement as OEMs deepen direct field engineering presence.
Manufacturing Scale Electrostatic Precipitator Market Segmentation
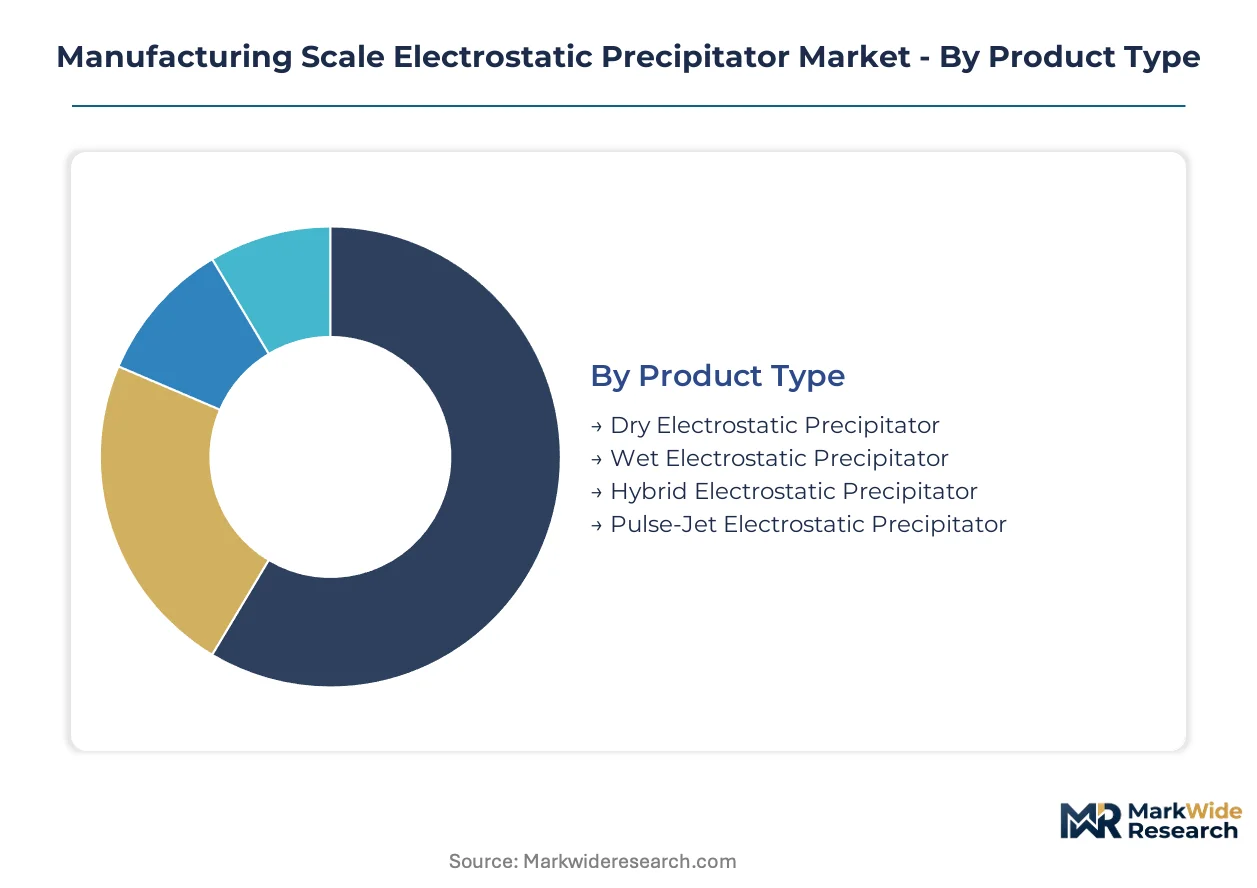
Electrostatic precipitator procurement patterns diverge sharply across operational scale, particulate chemistry, and regulatory exposure. Buyers select configurations based on exhaust temperature profiles, moisture content, and compliance verification requirements rather than capital cost alone.
Product Type:
Buyers differentiate primarily by particulate physical state and cleaning cycle requirements.
- Dry Electrostatic Precipitator:Operates through mechanical rappers that dislodge dry dust from collecting plates into hoppers. Coal-fired power plants in Poland and the Czech Republic sustain replacement demand as aging installations face EU Industrial Emissions Directive enforcement.
- Wet Electrostatic Precipitator:Uses liquid irrigation to continuously wash electrodes, capturing sticky or hygroscopic particulates that resist dry removal. Cement kilns in Turkey and Vietnam are adopting these systems to meet mercury emission thresholds without downstream scrubber additions.
- Hybrid Electrostatic Precipitator:Combines dry pre-collection stages with wet polishing sections for sequential particulate and acid gas capture. Steel manufacturers in Hebei province deploy these configurations to achieve China's MEE ultra-low emission mandates below 10 milligrams per cubic meter.
- Pulse-Jet Electrostatic Precipitator:Delivers intermittent high-energy cleaning cycles through compressed air bursts, suited to steel manufacturing applications with variable particulate loading. Indian steel mills under the PLI scheme for clean technology are localizing production of these configurations.
Volume sits with dry systems; growth tilts toward wet configurations.
Technology:
Technology selection hinges on voltage stability requirements and electrode maintenance accessibility.
- Corona Discharge:Ionizes particulate matter through 30-100 kilovolt discharge between wire electrodes and grounded collecting surfaces. German engineering specialists dominate high-efficiency corona optimization for cement retrofit contracts.
- High Voltage Transformer:Converts grid power to the elevated potentials required for sustained corona formation. Supply concentrates in Germany and Japan, creating 18-24 month order backlogs for large-scale installations.
- Electrodes Configuration:Encompasses wire-plate, wire-pipe, and rigid electrode geometries tailored to exhaust stream characteristics. Advanced ceramic composite electrodes are extending operational temperatures above 400 degrees Celsius for kiln applications.
- Dust Collection Method:Governs particulate removal through mechanical rappers, liquid slurry, or pneumatic conveyance. Wet slurry systems demand corrosion-resistant alloys that fluctuate with tungsten and titanium pricing.
Transformer design commands premium margins; electrode material science drives differentiation.
Application:
Application segmentation reflects emission threshold stringency and particulate toxicity.
- Power Generation:Coal and biomass combustion facilities deploy large-scale dry systems with continuous monitoring integration. US EPA Mercury and Air Toxics Standards enforce upgrade timelines for plants exceeding 25-year operational life.
- Cement Production:Kiln exhaust streams require wet or hybrid configurations for mercury and fine particulate capture. Chinese producers face MEE enforcement of ultra-low standards that force wholesale system replacements.
- Steel Manufacturing:Sinter plants and electric arc furnaces generate high-temperature, metal-laden exhaust demanding pulse-jet or hybrid systems. Japanese and South Korean operators pioneered performance-guaranteed maintenance contracts now spreading to India.
- Chemical Processing:Sticky organic particulates and acid mists necessitate wet electrode irrigation. Food processing facilities are adopting wet ESP technology for hygroscopic particulate capture previously served by baghouse alternatives.
- Food Processing:Handles oil-laden exhaust from frying and roasting operations where particulate agglomeration resists dry removal. Wet configurations are gaining share in this adjacent vertical as technology matures.
Steel and cement concentrate procurement volume; food processing represents the steepest expansion trajectory.
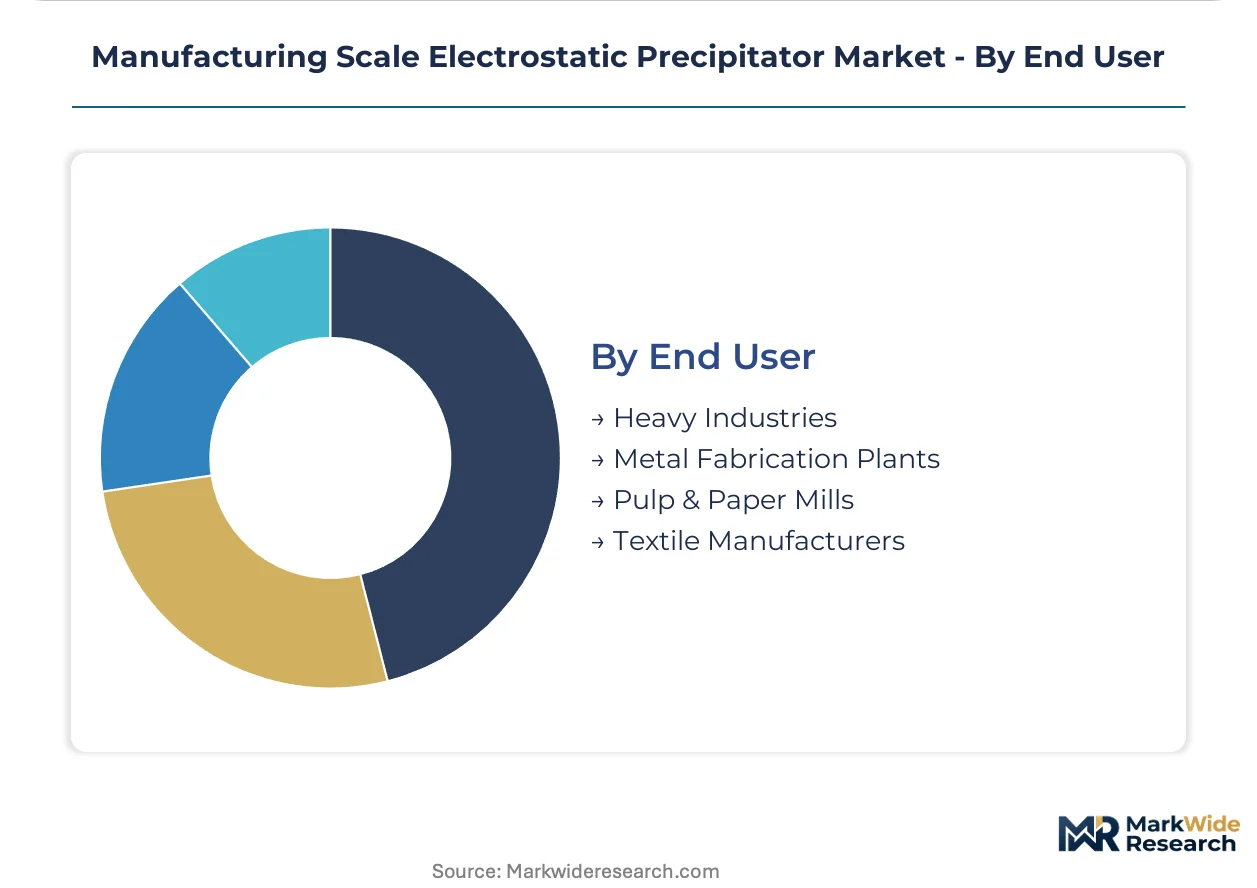
End User:
End user categories separate by operational scale and in-house technical capability.
- Heavy Industries:Integrated steel and cement producers with dedicated environmental engineering staff favor complex hybrid systems with predictive maintenance integration.
- Metal Fabrication Plants:Smaller-scale welding and cutting operations with intermittent exhaust loads prioritize compact pulse-jet configurations and outsourced service contracts.
- Pulp & Paper Mills:Recovery boiler exhaust streams combine particulate and odorous compound challenges, driving demand for wet ESP with acid gas polishing stages.
- Textile Manufacturers:Fiber and finishing operations generate fine lint and chemical particulates requiring specialized electrode spacing to prevent bridging.
Heavy industries anchor system complexity; metal fabrication plants drive standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of manufacturing scale electrostatic precipitator systems consumed across East Asian industrial clusters, while demand concentrates in steel manufacturing and cement production corridors spanning Hebei province, the Yangtze River Delta, and India's western industrial belt.
China
Hebei and Jiangsu provinces drive procurement volume as steel manufacturers confront MEE ultra-low emission mandates below 10 milligrams per cubic meter. The dual carbon goals accelerate localized production capacity for wet and hybrid configurations. Tangshan and Xuzhou industrial clusters anchor system deployment for sinter plants and electric arc furnaces.
India
Steel mills in Maharashtra and Gujarat expand pulse-jet configuration procurement under the PLI scheme for clean technology manufacturing. CEA mandates force electrostatic precipitator upgrades for thermal plants exceeding 25-year operational life. The Delhi-Mumbai Industrial Corridor concentrates demand from integrated steel producers seeking performance-guaranteed maintenance contracts.
Japan
Kansai and Chubu regions sustain replacement demand for high-voltage transformer systems in aging coal-fired infrastructure. METI efficiency standards push cement producers toward wet configuration retrofits. Osaka and Nagoya industrial zones pioneer bundled service contracts now spreading to South Korean and Indian operators.
Germany
Polish and Czech coal plants sustain European retrofit demand through ANDRITZ GROUP's Austrian engineering base for dry-to-wet conversions. The EU Industrial Emissions Directive enforces continuous particulate monitoring thresholds that determine ESP specifications. Ruhr Valley cement producers accelerate procurement of integrated sensor packages ahead of 2025 verification protocol tightening.
United States
Midwestern power generation facilities face EPA Mercury and Air Toxics Standards enforcement timelines forcing system replacements. High-voltage transformer supply concentration in Germany and Japan creates 18-24 month order backlogs for large-scale installations. Ohio River Valley coal plants concentrate procurement of continuous monitoring integration packages.
Manufacturing Scale Electrostatic Precipitator Market Competitive Landscape
Top-tier vendors anchor technology leadership in high-voltage transformer design and wet system engineering, while mid-tier fabricators compete on delivery speed and localized service presence. The vendor base stratifies across three archetypes: integrated engineering conglomerates with full-system capabilities, specialized precipitator manufacturers focused on electrode configurations, and regional fabricators serving maintenance-heavy replacement cycles. Capacity expansion and strategic technology licensing represent the dominant competitive moves as suppliers confront compressed retrofit timelines.
Within the integrated engineering tier, ANDRITZ GROUP and Babcock & Wilcox occupy positions exemplifying divergent geographic anchoring—ANDRITZ leveraging its Austrian base for European retrofit dominance, Babcock & Wilcox representing North American high-voltage specialization. Thermax anchors the regional fabricator archetype through Indian market presence. These three exemplify how competitive positioning stratifies across engineering depth, geographic concentration, and service bundling capabilities rather than scale alone.
| Leading Market Players |
|---|
| ANDRITZ GROUP |
| Babcock & Wilcox |
| Thermax |
| GEA Group |
| Mitsubishi Heavy Industries |
| FLSmidth |
| Siemens |
| Fujian Longking |
| Balcke-Dürr |
| Others |
Pricing and Supply Chain Analysis
Captive transformer production in Germany and Japan anchors supply-side pricing power for high-voltage system suppliers, while electrode material sourcing from Chinese rare earth processors creates asymmetric cost exposure across wet and dry configuration tiers. This integration pattern concentrates margin defense capability among vendors with in-house winding capacity, forcing regional fabricators toward service-based differentiation.
Pricing Analysis
Premium pricing attaches to sub-12-month delivery commitments for large-scale installations, while spot inventory of standard electrode configurations trades at contracted discounts. Project-based contracting dominates, with price differentiation resting on transformer origin and ceramic electrode certification grade. Pricing pressure intensifies in the dry system retrofit tier as Polish and Czech coal plants compress procurement timelines. Heavy industries demonstrate lowest price sensitivity due to compliance failure costs, while metal fabrication plants prioritize capital efficiency over performance guarantees.
Supply Chain Analysis
Specialized corona discharge engineers in Germany and Japan constrain expansion velocity for high-efficiency system output. Manufacturing concentrates in China, Germany, and Japan, with raw material dependencies on tungsten alloys, titanium electrodes, and high-grade transformer copper. Single-source vulnerability concentrates in Japanese transformer winding capacity. Distribution runs through OEM direct sales for large installations and regional service intermediaries for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where China's MEE ultra-low emission mandates erect regulatory moats favoring certified system suppliers with proven sub-10 milligrams per cubic meter performance documentation.
For Market Incumbents: Lock in electrode material supply through long-term offtake agreements with Chinese rare earth processors before export quota tightening. Expand captive transformer winding capacity in India under PLI scheme incentives to deflect German-Japanese supply bottlenecks. Baghouse technology substitution in sub-50 MW biomass applications threatens the dry system replacement tier; defend through bundled digital twin predictive maintenance contracts that shift buyer value perception from capital cost to outcome assurance. For New Entrants and Emerging Players: India's CEA mandates for thermal plant upgrades open a window for pulse-jet configuration localization under clean technology manufacturing incentives. Target Maharashtra and Gujarat steel corridors where performance-guaranteed maintenance contracts are displacing channel intermediaries. Vietnam and Indonesia cement kilns present white-space demand for hybrid dry-wet systems without entrenched incumbent relationships. Establish technical service partnerships with regional fabricators lacking field engineering depth rather than competing on system specification. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated engineering conglomerates seeking wet system capabilities and Asian market presence. Five-to-ten year viability favors vendors with demonstrated EU Industrial Emissions Directive compliance documentation and installed base in China's Hebei province. Monitor electrode material cost volatility indices as inflection indicator for margin compression timing across the competitive tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Materials | Tungsten and titanium alloy supply control insulates margin from Chinese rare earth export quota volatility. |
| Digital Twin Predictive Maintenance Platform | Real-time corona discharge monitoring enables outcome-based contracting with Indian steel mills under PLI scheme. |
| Localized Manufacturing in India | Domestic pulse-jet production reduces import dependence and captures CEA-mandated thermal plant upgrade cycles. |
| Hybrid System Technology Licensing | Cement kiln operators in Vietnam and Indonesia seek sequential particulate and acid gas capture without proprietary development. |
| Performance-Guaranteed Service Contracts | Japanese and South Korean steel mill maintenance consolidation models transfer to Indian producers seeking compliance assurance. |
Research Methodology
Multi-period observation of MEE enforcement actions, CEA upgrade mandates, and EU Industrial Emissions Directive verification protocol developments anchored the trend analysis, supplemented by interviews with plant engineers at steel and cement facilities, procurement leads at integrated heavy industrial operators, aftermarket service directors at regional fabricators, and regulatory compliance officers at environmental agencies. Secondary validation drew from EPA enforcement databases, EU ETS emissions trading records, Chinese customs trade data for electrode material flows, and SEC filings of publicly traded engineering conglomerates. Bottom-up installation tracking across Hebei province, Maharashtra-Gujarat corridor, and Ohio River Valley coal plants triangulated against top-down market sizing from equipment supplier revenue disclosures.
Input-output matrices modeled particulate discharge volumes against configuration-specific capture efficiency curves across the projection horizon. Segmentation dimensions spanned product type, technology tier, application vertical, and end-user operational scale. CAGRs derived from regression analysis of historic procurement cycles against regulatory deadline clustering. Industry-specific forecast inputs incorporated transformer order backlog durations and ceramic electrode temperature tolerance adoption rates in Chinese cement kiln retrofits.
Caveats apply where MEE enforcement intensity fluctuations or EU Industrial Emissions Directive 2025 review cycle outcomes could materially shift the outlook. Forecasts rest on assumptions of sustained rare earth export quota stability and continued high-voltage transformer supply concentration in Germany and Japan. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Bin Vent Filter Market