
 Saudi Arabia Prefabricated Building and Structural Steel Market | 2026-2036
Saudi Arabia Prefabricated Building and Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Prefabricated Building and Structural Steel Market Intelligence
Saudi Arabia is fragmenting its prefabricated building capacity across Jubail, Rabigh, and Dammam industrial clusters to shorten project lead times for NEOM and Red Sea developments. Zamil Steel leverages integrated coil-to-building production to dominate commercial and industrial contracts. Al Jazera Factory For Engineering Construction Co. Ltd. anchors its position through specialized heavy-gauge structural fabrication for petrochemical clients. Saudi Building Systems Mfg Co. differentiates via turnkey design-build capabilities that reduce on-site labor dependency.
Prefabricated building and structural steel encompasses factory-manufactured structural assemblies using hot-rolled or cold-formed steel sections, welded or bolted connections, and corrosion-resistant coatings engineered for rapid site erection. These systems serve primary functions spanning commercial framing, industrial warehousing, residential modular units, and infrastructure support structures requiring seismic and wind-load compliance. Pre-engineered structures lead volume allocation due to standardized portal frame designs that compress engineering cycles for repeat industrial clients. Modular buildings represent the fastest-expanding category as hospitality and healthcare developers adopt volumetric construction for speed-to-market advantages. Steel frames command concentrated margin pools in complex multi-story commercial projects where engineering intensity elevates pricing power.
SFDA material certification protocols, Saudi Building Code seismic provisions, and SASO quality conformity assessments collectively shape product specifications and market access thresholds for domestic and imported structural components. The Saudi Standards, Metrology and Quality Organization enforces mandatory compliance for steel grades, welding procedures, and fire-resistance ratings that directly influence procurement decisions across government and private developments. Stakeholders must monitor evolving localization requirements under the National Industrial Development Center as domestic content mandates reshape supplier qualification criteria and contract eligibility.
Market Dynamics
Vision 2030 megaprojects are compressing traditional construction timelines, forcing a structural shift toward factory-based fabrication methods that reduce on-site labor dependency and accelerate project delivery across NEOM, Red Sea, and Qiddiya developments.
Growth Catalysts
- SFDA Material Certification Alignment:Unified steel grade and welding procedure standards under SASO quality conformity assessments are streamlining supplier qualification, reducing procurement friction for government contractors bidding on giga-project packages.
- Industrial Zone Clustering:Concentrated fabrication capacity in Jubail, Rabigh, and Dammam is shortening logistics lead times for petrochemical and logistics warehouse developers operating along the Eastern Province corridor.
- Volumetric Construction Methods:Modular building systems are displacing conventional stick-built approaches in hospitality and healthcare verticals where speed-to-market determines project financing viability.
Market Restraints
- Hot-Rolled Coil Price Volatility:Input cost swings tied to regional steel billet supply disruptions compress margin predictability for fabricators locked into fixed-price EPC contracts.
- Specialized Welder Shortage:Limited domestic certification capacity for structural steel welding procedures under Saudi Building Code seismic provisions constrains production throughput at peak demand periods.
- Concrete-Steel Hybrid Substitution:Cast-in-place reinforced concrete retains cost advantages in low-rise residential segments, limiting addressable market expansion for pure steel framing solutions.
Strategic Opportunities
- NEOM Linear City Infrastructure:The 170-kilometer urban corridor requires unprecedented volumes of modular residential and commercial units, creating captive demand for prefabrication specialists with design-build capabilities.
- Saudi Green Building Forum Incentives:Energy efficiency certification pathways for steel-intensive construction are unlocking preferential financing terms for developers meeting thermal performance thresholds.
- BIM-to-Fabrication Integration:Convergence of building information modeling with CNC plasma cutting and robotic welding is compressing engineering-to-production cycles for complex multi-story commercial frames.
Industry Challenges
- SFDA Certification Timeline Compression:Extended material testing and documentation requirements for imported structural components delay project mobilization, particularly for European and Asian suppliers unfamiliar with SASO conformity pathways.
- Seismic Design Expertise Scarcity:Limited domestic engineering capacity for high-load wind and seismic calculations under Saudi Building Code Chapter 15 forces reliance on expatriate specialists, inflating pre-construction costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Prefabricated Building and Structural Steel Market |
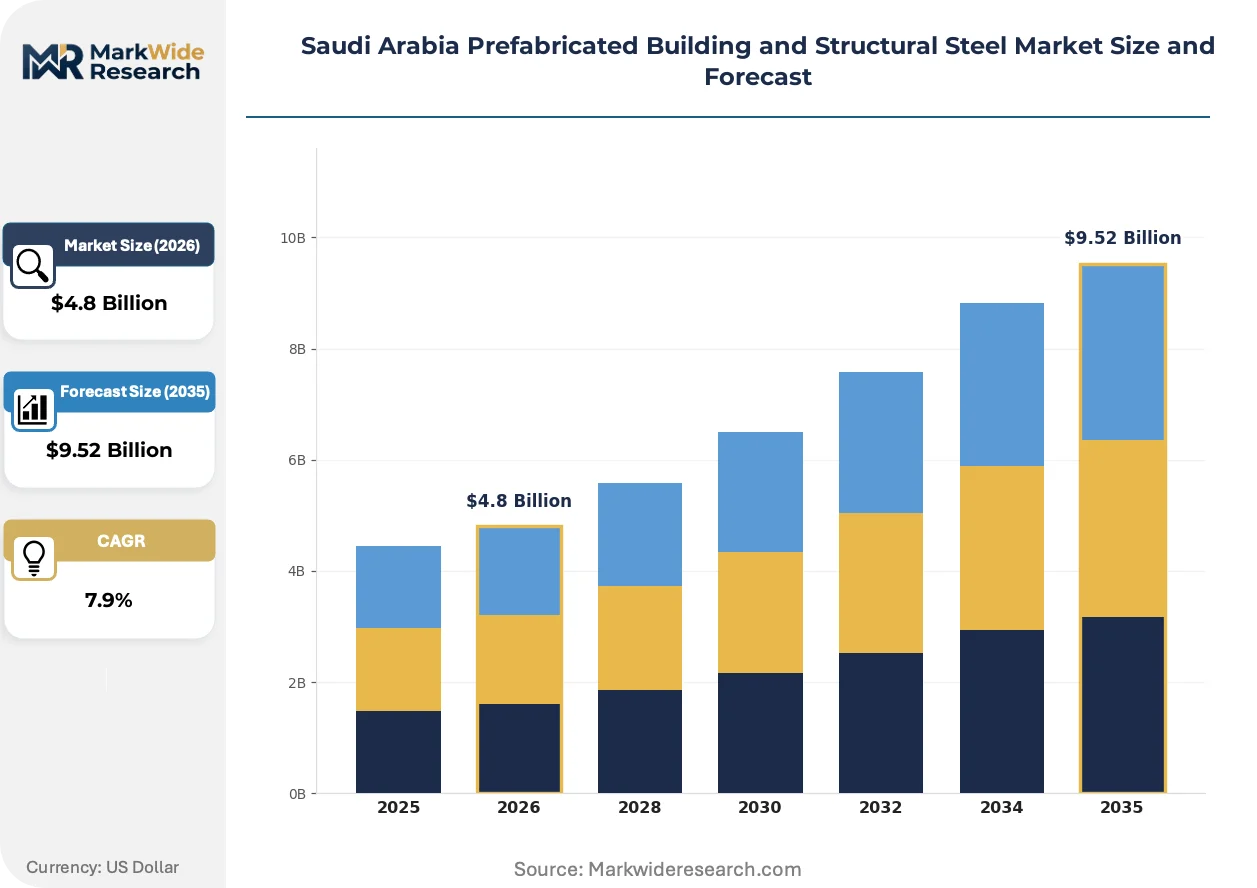
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Steel Frames, Pre-engineered Structures, Insulated Panels End User: Construction Companies, Government Projects, Residential Developers, Industrial Facilities Installation Type: On-site Assembly, Off-site Construction, Hybrid Methods, Turnkey Solutions Material Type: Structural Steel, Concrete, Wood, Composite Materials |
| Companies Covered | Zamil Steel, Al Jazera Factory For Engineering Construction Co. Ltd., Saudi Building Systems Mfg Co., Alabniah, Saudi Company for Prefabricated Buildings LLC, Red Sea Housing Services, United Company for Caravans and Prefab Houses, Eastern Precast Concrete, Kirby Building Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Prefabricated Building and Structural Steel Market Strategic Shifts & Innovations
Digital fabrication workflows and regulatory tightening are converging to redefine competitive advantage in Saudi structural steel, rewarding suppliers who integrate design intelligence with manufacturing precision.
Building information modeling is hybridizing with automated nesting algorithms and robotic welding stations to compress material waste ratios while accelerating shop drawing approval cycles. Industrial warehouse developers in Ras Al-Khair and Jazan Economic City are adopting these integrated workflows to meet aggressive handover schedules. The technology is hybridizing traditional steel fabrication with data-driven quality assurance, enabling real-time defect detection that reduces rework costs and SASO compliance rejection rates.
Saudi Building Code seismic provisions and SFDA-aligned fire-resistance rating mandates are elevating engineering documentation requirements for multi-story commercial structures. These regulations are forcing fabricators to invest in third-party testing partnerships and in-house structural calculation capabilities to maintain bid eligibility for government megaprojects. Complex portal frame and moment-resisting connections in Riyadh's central business district expansion are most affected, with developers prioritizing pre-qualified suppliers over lowest-bid procurement.
Asset ownership models are displacing traditional lump-sum EPC contracting as hospitality and healthcare operators seek operational flexibility. Build-to-suit lease structures with embedded maintenance obligations are emerging as the preferred transaction format for Red Sea tourism developers and Ministry of Health hospital expansions. This shift is most visible in the Western Province, where international hospitality brands demand turnkey delivery with performance guarantees spanning structural integrity and thermal envelope efficiency.
Saudi Arabia Prefabricated Building and Structural Steel Market Segmentation
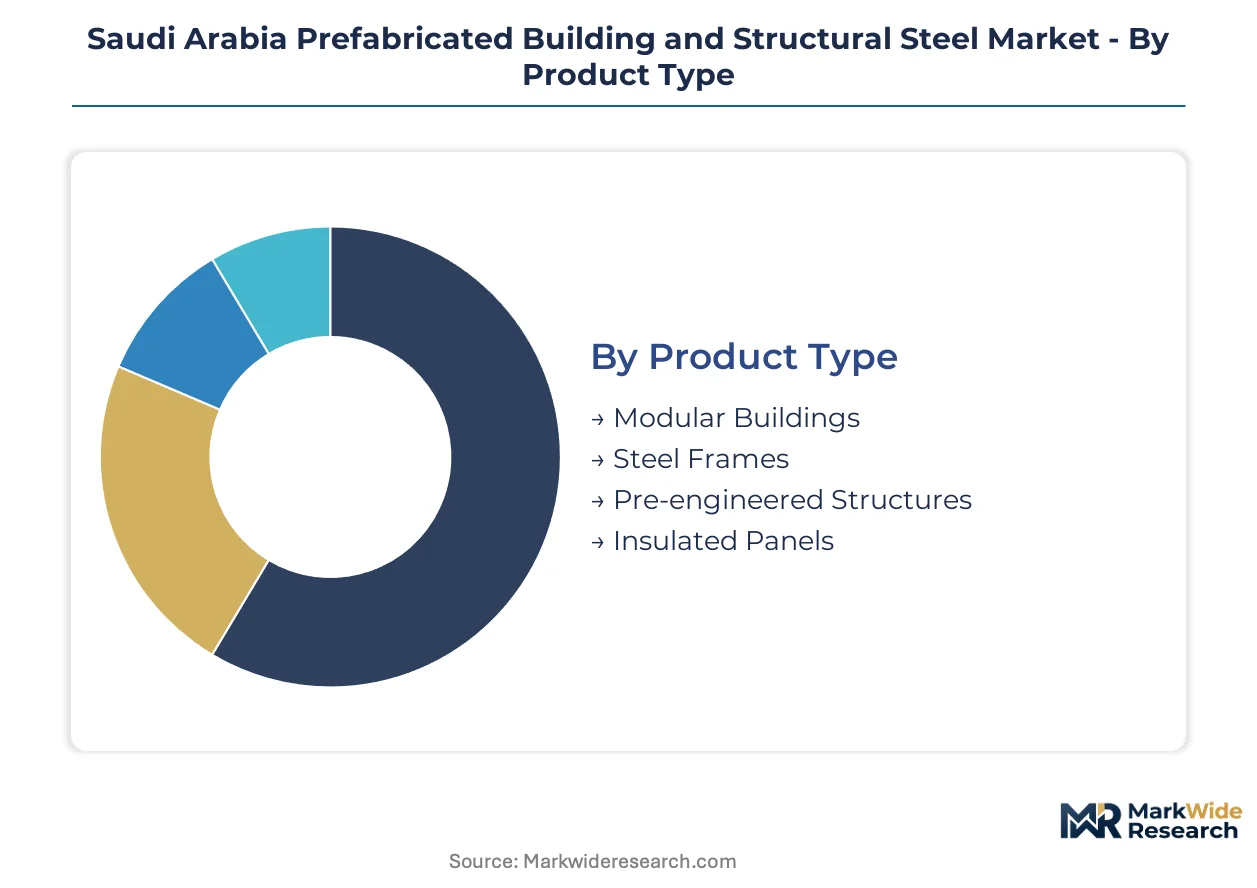
Segmentation in Saudi Arabia's prefabricated building market reveals how product specifications, procurement channels, and installation methods align with Vision 2030 delivery pressures. Distinct buyer behaviors across government megaprojects, industrial zones, and residential developments create specialized demand pockets requiring tailored fabrication and logistics strategies.
Product Type:
Product diversity spans permanent modular structures through engineered structural systems, each serving distinct project velocity and durability requirements across NEOM, Red Sea, and Eastern Province developments.
- Modular Buildings:Factory-produced volumetric units with integrated MEP and finishing enable hotel and healthcare developers to compress handover schedules. Red Sea tourism operators and Ministry of Health hospital expansions are driving specification intensity for fire-rated, thermally efficient modules that meet SFDA material certification and Saudi Building Code seismic provisions.
- Pre-engineered Structures:Standardized portal frame designs with optimized hot-rolled steel sections dominate logistics warehouse and petrochemical facility procurement in Jubail and Ras Al-Khair industrial zones. Repeatable engineering cycles and minimal site welding reduce labor dependency for EPC contractors facing aggressive timeline compression.
- Steel Frames:Multi-story commercial framing with moment-resisting connections serves Riyadh central business district expansion. Complex engineering documentation requirements elevate supplier qualification thresholds.
- Insulated Panels:Sandwich panel systems with PUR or mineral wool cores address thermal envelope efficiency mandates under Saudi Green Building Forum pathways. Cold storage and food processing facilities anchor demand.
Established volume favors pre-engineered structures; emerging adoption favors modular buildings.
End User:
Customer archetypes range from state-backed megaproject developers to private industrial operators, each imposing distinct contract structures, certification requirements, and payment risk profiles on fabrication suppliers.
- Construction Companies:EPC contractors bidding on NEOM and Qiddiya packages require design-build partners with SASO pre-qualification and integrated BIM-to-fabrication capabilities. Turnkey procurement with fixed-price risk transfer dominates commercial framing contracts.
- Government Projects:Direct state procurement through Ministry of Housing and Ministry of Health mandates domestic content compliance and extended warranty terms. SFDA material certification and third-party testing documentation are non-negotiable bid requirements.
- Residential Developers:Private developers in Riyadh and Jeddah prioritize cost predictability over speed, sustaining demand for standardized pre-engineered solutions in mid-rise housing.
- Industrial Facilities:Petrochemical and logistics operators in Dammam and Yanbu specify heavy-gauge structural fabrication with corrosion-resistant coatings for aggressive operating environments.
Contract concentration favors government projects; margin expansion favors construction companies with design-build integration.
Installation Type:
Installation methodology determines labor allocation between factory and site, with implications for project risk, schedule certainty, and regulatory compliance burden across Saudi Arabia's constrained skilled workforce environment.
- Turnkey Solutions:Single-contractor responsibility for design, fabrication, transport, and erection eliminates interface risk for hospitality developers seeking performance guarantees. Red Sea tourism projects increasingly specify this format.
- Off-site Construction:Factory-controlled production of 80-90% complete volumetric units minimizes on-site labor and weather exposure. Healthcare developers value infection-control advantages of controlled manufacturing environments.
- Hybrid Methods:Combination of pre-fabricated structural frames with site-cast concrete cores optimizes cost in mid-rise commercial projects where pure steel framing faces concrete substitution pressure.
- On-site Assembly:Conventional bolt-up erection of pre-cut components persists in remote locations where module transport economics deteriorate.
Risk transfer preferences favor turnkey solutions; cost optimization favors hybrid methods.
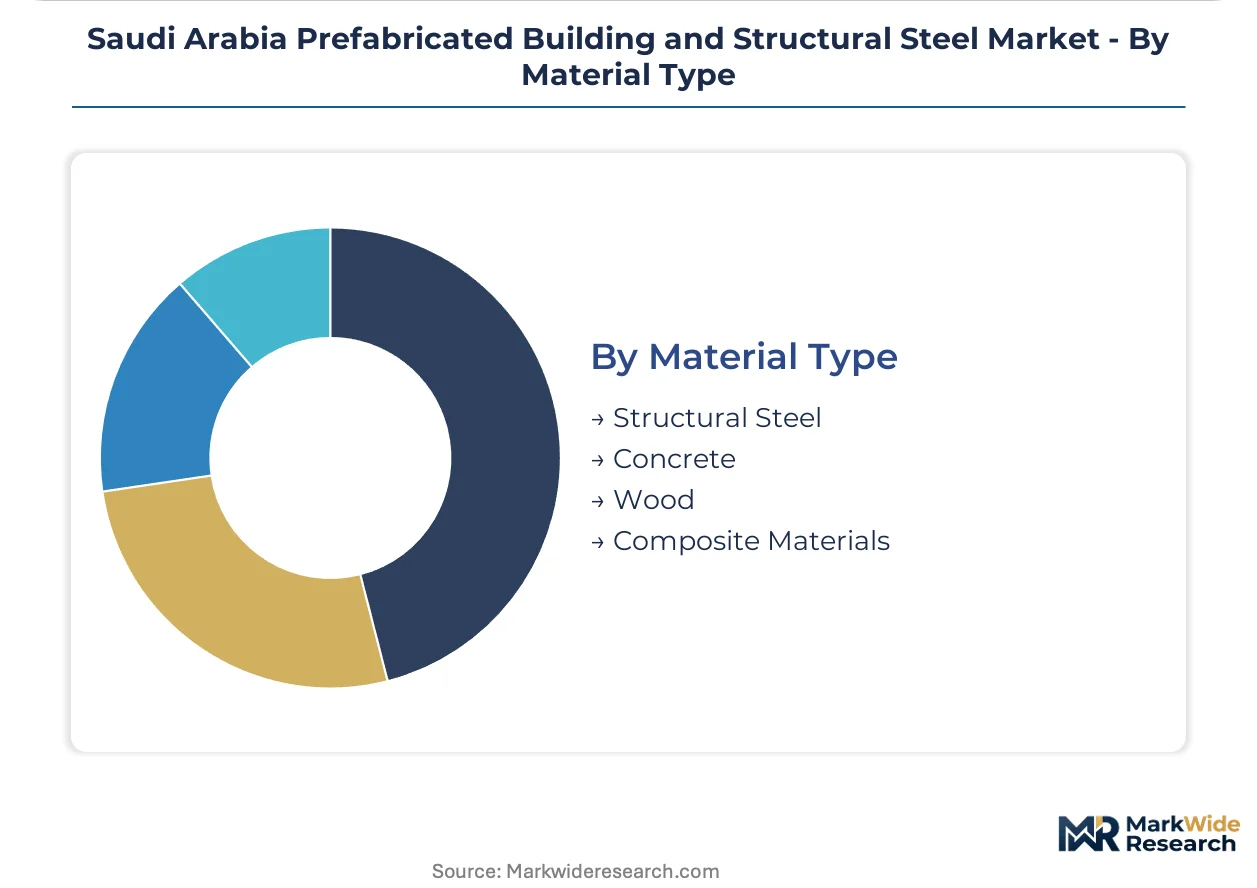
Material Type:
Material selection balances structural performance, code compliance, and supply chain security within Saudi Arabia's import-dependent steel market and emerging localization mandates.
- Structural Steel:Hot-rolled and cold-formed sections with SASO-grade certification form the dominant structural medium for commercial and industrial applications. Jubail and Rabigh industrial clusters provide domestic coil supply for integrated fabricators.
- Composite Materials:Fiber-reinforced polymer and steel-concrete hybrid systems address corrosion challenges in coastal and petrochemical environments. Niche adoption in specialized infrastructure.
- Concrete:Cast-in-place reinforced concrete retains cost advantage in low-rise residential segments, constraining pure steel framing addressable market.
- Wood:Engineered timber and cross-laminated lumber face climate durability and code acceptance barriers, limiting penetration to temporary and low-rise applications.
Structural dominance favors steel; specialized performance favors composites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity clusters along Saudi Arabia's industrial corridor to minimize logistics friction for Vision 2030 megaprojects. The Eastern Province anchors heavy-gauge structural production, while Riyadh concentrates commercial framing and modular assembly operations.
Eastern Province
Jubail and Dammam industrial zones host integrated steel coil-to-building facilities serving petrochemical and logistics warehouse developers. SFDA material certification requirements and SASO quality conformity assessments shape procurement protocols for state-backed infrastructure. Ras Al-Khair and Yanbu fabrication clusters are expanding robotic welding capacity to meet aggressive handover schedules for Red Sea tourism support facilities.
Riyadh
The central business district expansion drives demand for multi-story commercial steel frames with moment-resisting connections. Ministry of Housing mandates and Saudi Building Code seismic provisions elevate engineering documentation requirements for government contractors. Industrial city developments on the capital's periphery are attracting modular building specialists with turnkey design-build capabilities.
Western Region
Jeddah and Makkah construction activity concentrates on hospitality and healthcare modular units for religious tourism infrastructure. Red Sea Project developers specify volumetric construction methods to compress speed-to-market timelines. King Abdullah Economic City is emerging as a secondary fabrication hub with port access for imported structural components.
NEOM Northwest
The linear city corridor requires unprecedented volumes of factory-manufactured residential and commercial modules. NEOM's procurement frameworks prioritize suppliers with integrated BIM-to-fabrication workflows and domestic content compliance. Specialized fabrication zones within the development boundary are planned to eliminate transport logistics for the 170-kilometer urban strip.
Saudi Arabia Prefabricated Building and Structural Steel Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on material supply and specialized fabrication. The Saudi market exhibits tiered concentration with a handful of integrated producers dominating government megaproject contracts while mid-scale fabricators compete for private industrial work. Three archetypes define competitive positioning: coil-integrated steel producers with captive raw material supply, design-build specialists offering turnkey project delivery, and regional fabricators focused on heavy-gauge petrochemical structures. Capacity expansion and strategic partnerships with international engineering firms represent the dominant competitive moves as localization requirements tighten.
Among Saudi-based integrated producers, Zamil Steel, Al Jazera Factory For Engineering Construction Co. Ltd., and Saudi Building Systems Mfg Co. occupy positions across the value chain. Zamil Steel exemplifies the coil-integrated archetype with upstream control over hot-rolled supply. Al Jazera Factory represents specialized heavy-gauge fabrication capabilities for aggressive industrial environments. Saudi Building Systems anchors the design-build tier with turnkey delivery models that reduce client-side project management burden. These three entities collectively illustrate how domestic market leaders are aligning vertical integration depth with Vision 2030 procurement preferences.
| Leading Market Players |
|---|
| Zamil Steel |
| Al Jazera Factory For Engineering Construction Co. Ltd. |
| Saudi Building Systems Mfg Co. |
| Alabniah |
| Saudi Company for Prefabricated Buildings LLC |
| Red Sea Housing Services |
| United Company for Caravans and Prefab Houses |
| Eastern Precast Concrete |
| Kirby Building Systems |
| Others |
Cost & Logistics Intelligence
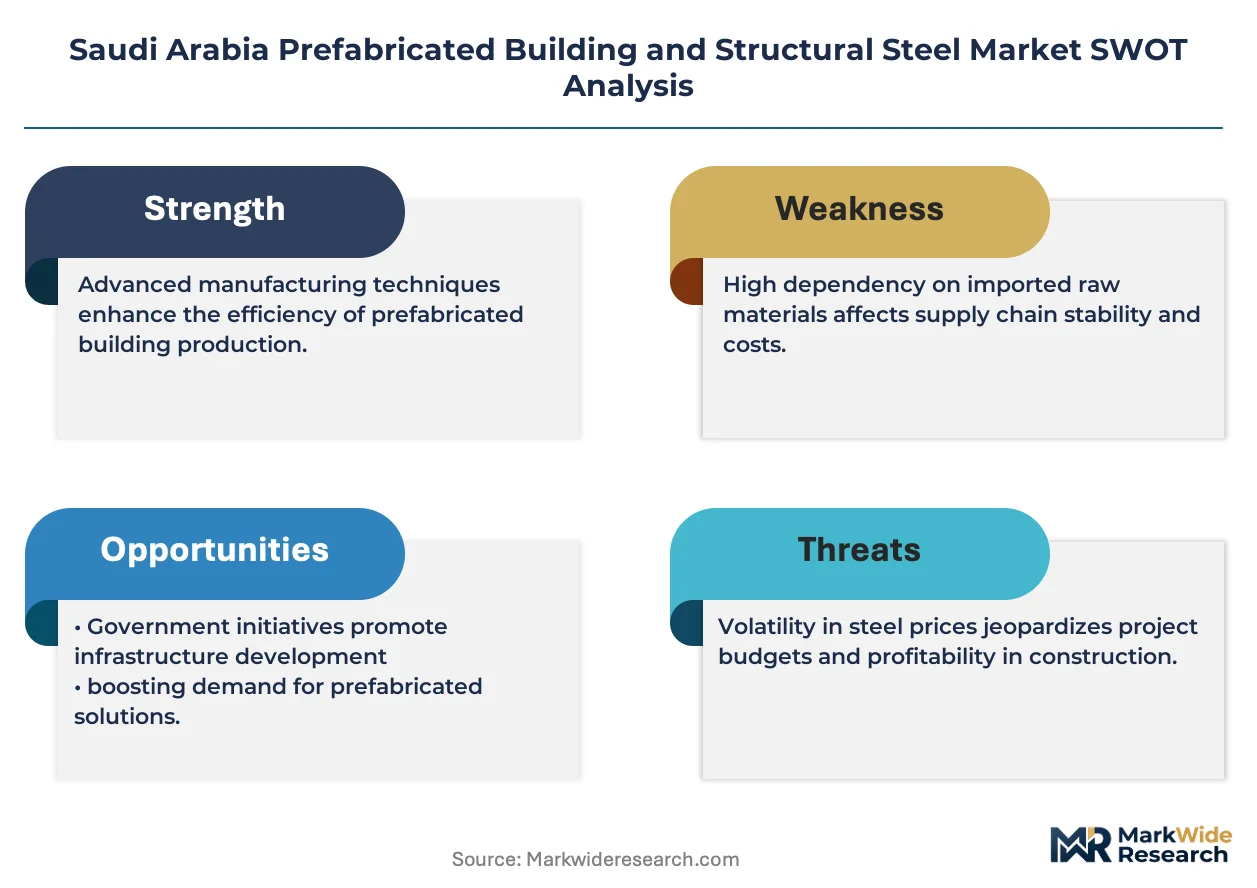
Hot-rolled coil price volatility determines both margin compression patterns and supplier consolidation trajectories across Saudi Arabia's prefabricated building sector. Fabricators locked into fixed-price EPC contracts face asymmetric exposure to regional steel billet supply disruptions, forcing tiered procurement strategies that separate integrated coil-to-building producers from import-dependent competitors.
Pricing Analysis
SASO quality conformity assessments dictate the pricing tier structure across Saudi Arabia's structural steel market. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified fabricators with in-house testing capabilities from traders sourcing uncertified Asian imports. Cost compression in the economy tier is intensifying because Ministry of Housing contractors are consolidating purchase volumes toward pre-qualified suppliers. Government megaproject developers exhibit lowest price sensitivity due to speed-to-market premiums, while private residential developers anchor the most price-sensitive segment.
Supply Chain Analysis
Zamil Steel, Al Jazera Factory, and Saudi Building Systems hold concentrated fabrication capacity across Jubail, Rabigh, and Dammam industrial clusters. Domestic supply draws from integrated hot-rolled coil production at Jubail steel complexes, supplemented by imported billet from Turkey, India, and China. Single-source vulnerability concentrates in specialized welding consumables and seismic-grade connection hardware. Distribution runs through EPC contractor procurement offices with direct-to-site logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Concrete-steel hybrid substitution threatens pure steel framing incumbents in low-rise residential segments, requiring defensive repositioning toward high-engineering commercial and industrial applications where material performance advantages are defensible.
For Market Incumbents: Entrench position through backward integration into hot-rolled coil supply and captive SFDA certification laboratories that accelerate project mobilization timelines. Zamil Steel's coil-to-building model demonstrates how upstream control over raw material insulates margin predictability against regional billet price swings. Al Jazera Factory's heavy-gauge specialization for petrochemical environments shows how technical differentiation defends against concrete substitution in aggressive operating conditions.
For New Entrants and Emerging Players: Western Province hospitality modular construction represents the most penetrable white-space opportunity, where Red Sea tourism developers prioritize speed-to-market over established supplier relationships. King Abdullah Economic City's port infrastructure enables imported component assembly with lower domestic content thresholds than NEOM-bound competitors. A build-to-suit lease structuring capability unlocks financing-aligned procurement decisions among international hospitality brands.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors design-build specialists with BIM-to-fabrication integration. Long-term viability hinges on exposure to Vision 2030 megaproject pipelines rather than cyclical private residential construction. Acquisition targets should demonstrate Saudi Building Code Chapter 15 seismic calculation capabilities and established third-party testing partnerships. Quarterly review of Ministry of Housing procurement award patterns and NEOM contractor pre-qualification lists is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil Supply | Zamil Steel's captive steel production eliminates import dependency and stabilizes input cost exposure for government contracts. |
| SFDA Certification Laboratory Investment | In-house material testing capabilities compress project mobilization timelines and unlock bid eligibility for Ministry of Health hospital expansions. |
| BIM-to-Fabrication Workflow Implementation | Robotic welding stations integrated with building information modeling reduce engineering-to-production cycles for Riyadh commercial frame contracts. |
| Build-to-Suit Lease Structure Development | Performance-guaranteed delivery models align with Red Sea tourism developer financing requirements and operational flexibility demands. |
| Heavy-Gauge Corrosion-Resistant Specialization | Al Jazera Factory's petrochemical-focused fabrication commands margin premiums in Yanbu and Ras Al-Khair industrial zones. |
Research Approach
The analysis maps pre-engineered structures, modular buildings, steel frames, and insulated panels, each validated through EPC contractor procurement directors, structural engineering consultants, Ministry of Housing program managers, and SFDA certification officers. Primary fieldwork combined with secondary validation draws from SASO conformity assessment databases, Saudi Building Code technical committees, industrial zone development authority filings, and customs import records for structural steel components. Bottom-up project pipeline aggregation triangulates against top-down construction spending forecasts.
Assumptions held fixed include Vision 2030 megaproject commitment levels, SFDA certification timeline structures, and prevailing Saudi Building Code seismic provisions. Variables tested across the analysis window encompass hot-rolled coil price trajectory, domestic welding certification capacity expansion, and concrete-steel hybrid substitution elasticity in residential segments. Segmentation modeling incorporated product type, end-user archetype, installation methodology, and material composition. CAGRs derive from weighted project award probability assessments and historical construction completion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish or Chinese fabricators with SASO pre-qualification would shift pricing and share outcomes. Quarterly review of Ministry of Housing procurement award patterns, NEOM contractor announcements, and Jubail steel complex production disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Timber Frame Construction Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Steel Beam Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Girder Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Bridge Construction Market