
 GCC Prefabricated Building and Structural Steel Market | 2026-2036
GCC Prefabricated Building and Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Prefabricated Building and Structural Steel Market Intelligence
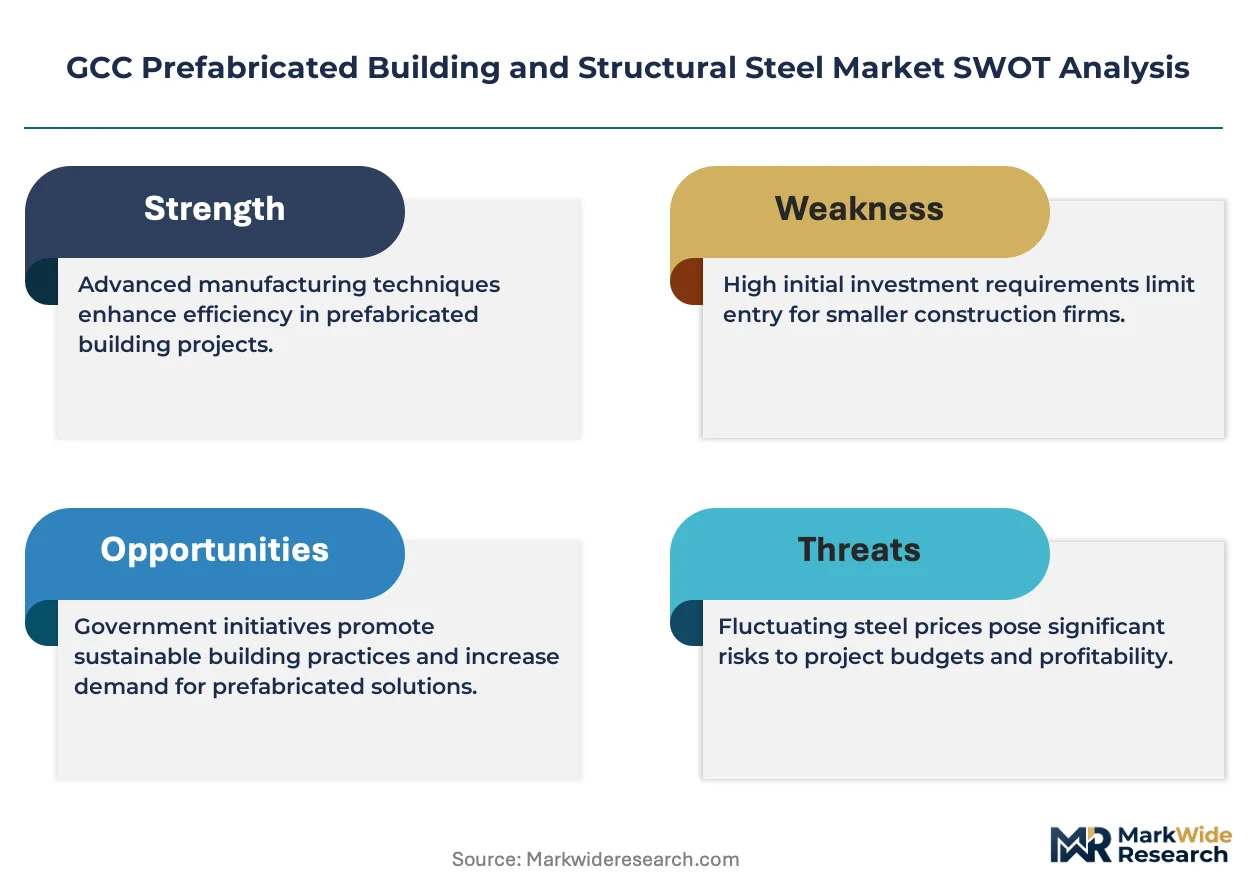
Saudi Arabia's giga-project pipeline is broadening the addressable market for prefabricated structural systems. Zamil Steel leverages its integrated manufacturing footprint across Dammam and Jubail to anchor regional supply. Emirates Steel Arkan sustains feedstock dominance through its captive steelmaking capacity in Abu Dhabi. Mabani Steel LLC differentiates via specialized coating and corrosion-protection capabilities suited to coastal and desert environments.
Prefabricated building and structural steel encompasses factory-manufactured load-bearing assemblies produced through automated cutting, welding, and surface-treatment processes, then transported for bolted or welded site erection. Pre-engineered structures lead volume throughput due to standardized portal-frame designs that compress project schedules for warehouses and logistics facilities. Modular buildings represent the fastest-expanding category as hospitality and healthcare buyers prioritize repeatable room-unit production with integrated MEP. Steel frames command durable margin pools in high-rise commercial towers where engineering complexity and code compliance create specialist barriers.
The Saudi Building Code and UAE's Al Sa'fat green building framework mandate seismic resilience and energy-efficiency thresholds that favor engineered steel over conventional concrete. MOHAP's federal construction safety protocols in the UAE require traceable welding certifications and third-party inspection regimens, effectively filtering out informal fabricators. Saudi Standards, Metrology and Quality Organization technical regulations for structural steel imports impose mill-certificate documentation that reshapes procurement patterns toward approved regional mills. Stakeholders must monitor how evolving Gulf national content requirements recalibrate supplier qualification criteria across upcoming project tenders.
Market Dynamics
Saudi Arabia's giga-project corridor is compressing construction timelines and forcing procurement toward factory-fabricated structural systems that bypass traditional cast-in-place bottlenecks. This demand concentration is restructuring supplier qualification criteria across the GCC.
Growth Catalysts
- NEOM and Red Sea mega-developments:Saudi Arabia's sovereign-backed projects specify pre-engineered steel for logistics hubs and worker accommodation, creating guaranteed offtake for regional fabricators.
- Al Sa'fat green building mandates:The UAE's energy-efficiency framework rewards off-site construction with faster permitting, tilting developer calculus toward modular steel solutions.
- Hot-rolled coil localization:Emirates Steel Arkan's captive steelmaking in Abu Dhabi secures feedstock supply for downstream prefabricators, insulating the value chain from import volatility.
Market Restraints
- Scrap price volatility:Structural steel producers face margin compression when Turkish scrap export prices spike, as GCC mills remain net importers of ferrous raw material.
- Jeddah-Dammam supply corridor dominance:Fabrication capacity clusters along Saudi Arabia's eastern seaboard, exposing projects in Kuwait and Oman to extended logistics lead times and transport cost premiums.
- Concrete substitution in low-rise residential:Block-and-plaster construction retains cost advantages for Saudi housing ministry projects under SAR 500,000 unit-price thresholds, capping steel penetration.
Strategic Opportunities
- Kuwait's Silk City and Boubyan Island:Planned free-zone developments lack established local fabrication infrastructure, creating first-mover openings for Saudi and UAE suppliers with mobile production units.
- Healthcare modularization:MOHAP's hospital expansion program favors repeatable patient-room modules with integrated MEP, opening a specialized vertical beyond standard warehouse frames.
- BIM-to-fabrication workflow convergence:Integration of building information modeling with CNC cutting lines is compressing engineering-to-production cycles, rewarding early technology adopters with tender advantages.
Industry Challenges
- Welding certification bottlenecks:Saudi Standards, Metrology and Quality Organization traceability requirements for structural joints outpace vocational training output, constraining qualified technician supply.
- Site-to-factory coordination complexity:Just-in-time delivery of large steel assemblies demands real-time logistics synchronization that many GCC contractors lack, causing erection delays and demurrage costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Prefabricated Building and Structural Steel Market |
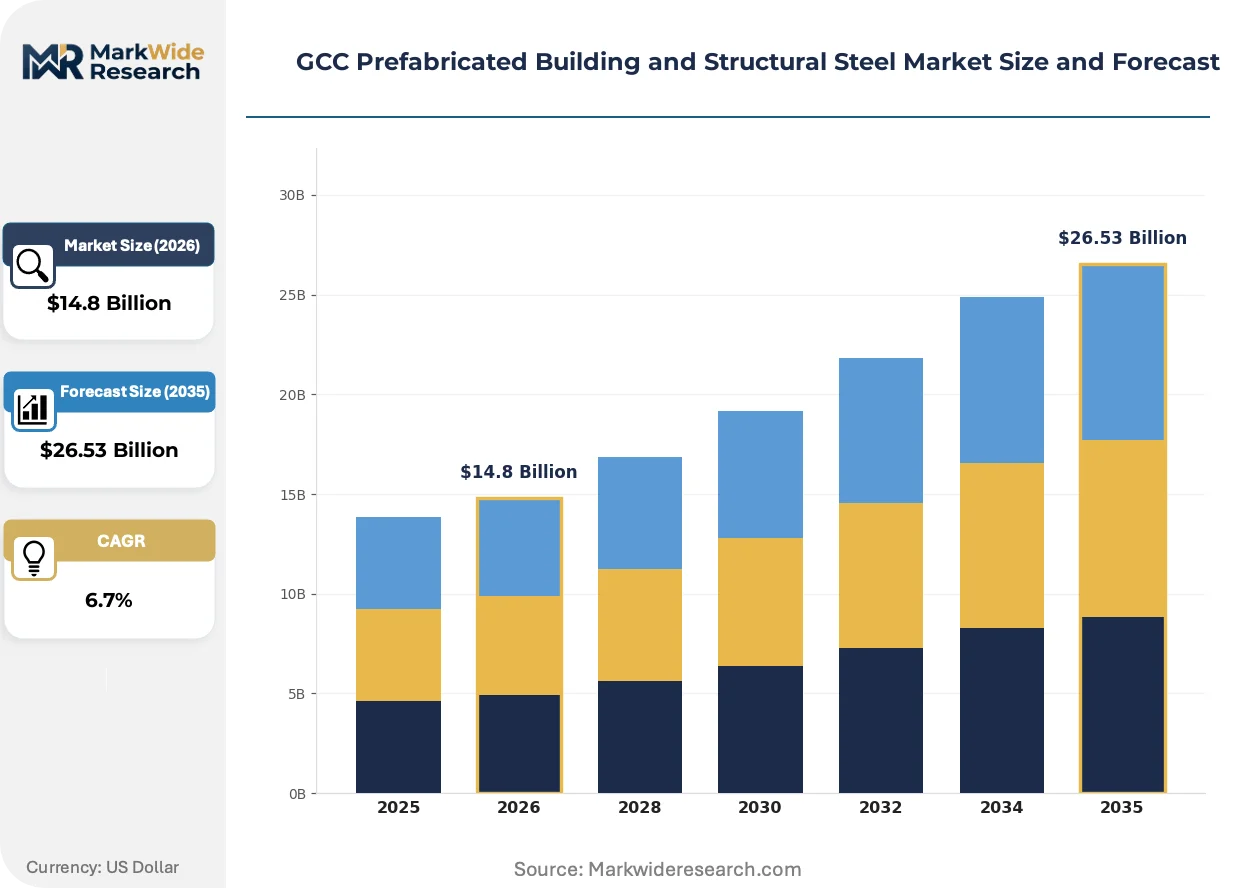
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Pre-Engineered Structures, Steel Frames, Composite Panels End User: Construction Sector, Industrial Facilities, Commercial Buildings, Residential Developments Installation Type: On-Site Assembly, Off-Site Fabrication, Hybrid Systems, Fully Modular Solutions Structural Component: Beams, Columns, Trusses, Decking |
| Companies Covered | Arabian International Company for Steel Structures, Mabani Steel LLC, Zamil Steel, Eversendai Engineering LLC, Al Shahin Company for Metal Industries, Emirates Steel Arkan, Al Yamamah Steel Industries Co., Techno Steel Construction LLC, Hidada Ltd Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Prefabricated Building and Structural Steel Market Strategic Shifts & Innovations
Digital fabrication workflows and regulatory tightening are converging to separate capital-intensive, certified producers from informal competitors across the GCC structural steel value chain.
Automated plasma cutting coupled with robotic welding is electrifying production economics for complex truss geometries. Saudi giga-project engineers now specify these assemblies for airport terminals and exhibition halls. The technology compresses fabrication labor content by half, enabling Dammam-based suppliers to bid competitively on contracts historically awarded to East Asian exporters.
SFDA's alignment with Saudi Building Code seismic provisions is mandating performance-based design submissions for structural steel above four stories. Engineering consultancies in Riyadh must now retain specialized structural steel designers, a capability previously concentrated among multinational firms. Local fabricators lacking in-house engineering partnerships face exclusion from commercial tower tenders.
Developer procurement teams are consolidating vendor panels to reduce qualification overhead on repetitive project types. Warehouse and logistics facility buyers in Dubai now maintain approved supplier lists of three to four pre-engineered building specialists, displacing the prior open-tender norm. This concentration is most visible among UAE-based retail and e-commerce fulfillment developers with standardized building footprints across multiple emirates.
GCC Prefabricated Building and Structural Steel Market Segmentation
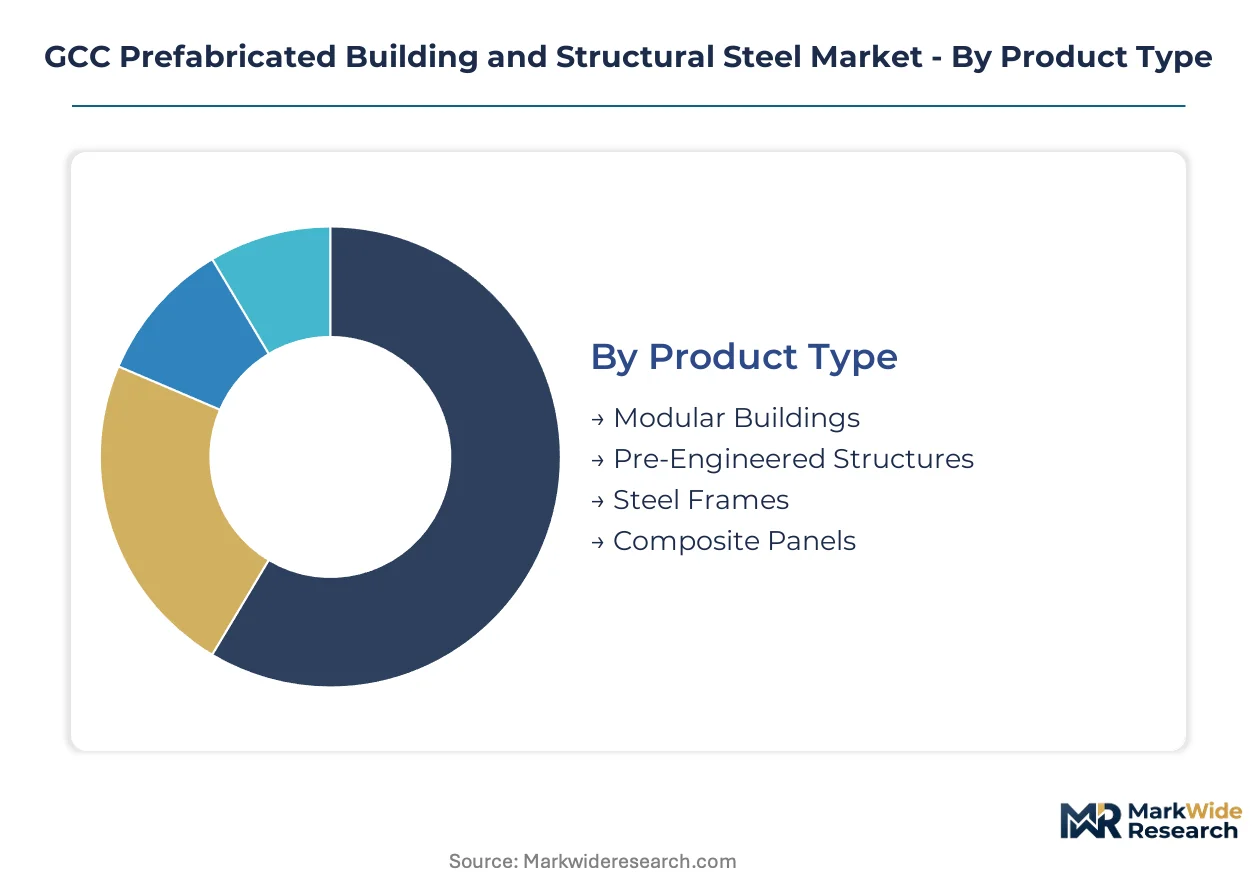
Segmentation in the GCC prefabricated building and structural steel market reveals how procurement priorities diverge across project scales, regulatory exposure, and logistics constraints. Buyers optimize for speed, certification depth, or total installed cost depending on end-use requirements.
Product Type:
Cost tier separates buyers seeking standardized warehouse solutions from those requiring architecturally complex commercial envelopes.
- Pre-Engineered Structures:Factory-built portal-frame systems with standardized connection details dominate logistics and industrial procurement. NEOM's warehouse clusters and Red Sea Project supply hubs specify these systems to compress foundation-to-handover schedules. Saudi Arabia's giga-project corridor absorbs the highest regional volumes.
- Modular Buildings:Volumetric room units with integrated MEP and interior finishes ship as complete assemblies. MOHAP's hospital expansion program in the UAE and Saudi healthcare ministry projects drive demand for repeatable patient-room production. This category expands most quickly as hospitality and education buyers adopt volumetric construction.
- Steel Frames:Custom-fabricated skeletal systems for mid-to-high-rise commercial towers require project-specific engineering. Dubai's commercial tower pipeline and Riyadh's financial district developments sustain specialist fabricator margins.
- Composite Panels:Insulated steel-faced sandwich systems deliver thermal performance for controlled-environment facilities. Cold-chain logistics developers in Jeddah and Dammam specify these for pharmaceutical and food distribution centers.
Volume sits with Pre-Engineered Structures; growth tilts toward Modular Buildings.
End User:
Application type determines engineering complexity, with industrial buyers prioritizing speed and commercial buyers demanding aesthetic customization.
- Industrial Facilities:Warehouses, manufacturing plants, and energy infrastructure dominate steel tonnage. Saudi Aramco's supply chain requirements and ADNOC's fabrication specifications filter supplier qualification. This segment anchors regional mill output.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures require seismic engineering and facade integration. Dubai's Al Sa'fat green building compliance adds energy-performance layers to steel specification.
- Construction Sector:General contractors and project developers purchasing structural systems for third-party deployment. Saudi giga-project delivery companies consolidate procurement across multiple EPC partners.
- Residential Developments:Low-to-mid-rise housing and worker accommodation units. Saudi housing ministry projects under cost thresholds retain concrete construction, capping steel penetration in this vertical.
Industrial Facilities command the largest share; Commercial Buildings gain fastest as urban density rises.
Installation Type:
Supply chain configuration separates buyers with established site logistics from those seeking factory-controlled quality assurance.
- Off-Site Fabrication:Complete structural assemblies produced in controlled factory conditions with certified welding and surface treatment. Emirates Steel Arkan's downstream partners and Zamil Steel's Dammam facilities supply giga-project demand. This method dominates quality-sensitive commercial and industrial applications.
- Hybrid Systems:Partial prefabrication combining factory-built primary frames with site-installed secondary elements. Kuwait's emerging project pipeline and Oman's infrastructure builds favor this approach to balance speed with local content requirements.
- Fully Modular Solutions:Volumetric units delivered as complete building sections. Healthcare and education buyers in the UAE and Saudi Arabia specify these for speed-to-occupancy.
- On-Site Assembly:Component-based erection from loose steel sections. Remains prevalent for small-scale projects and remote sites beyond efficient factory delivery radius.
Off-Site Fabrication holds volume leadership; Fully Modular Solutions accelerate fastest in healthcare verticals.
Structural Component:
Margin concentration varies by fabrication complexity, with engineered assemblies capturing premium pricing over commodity sections.
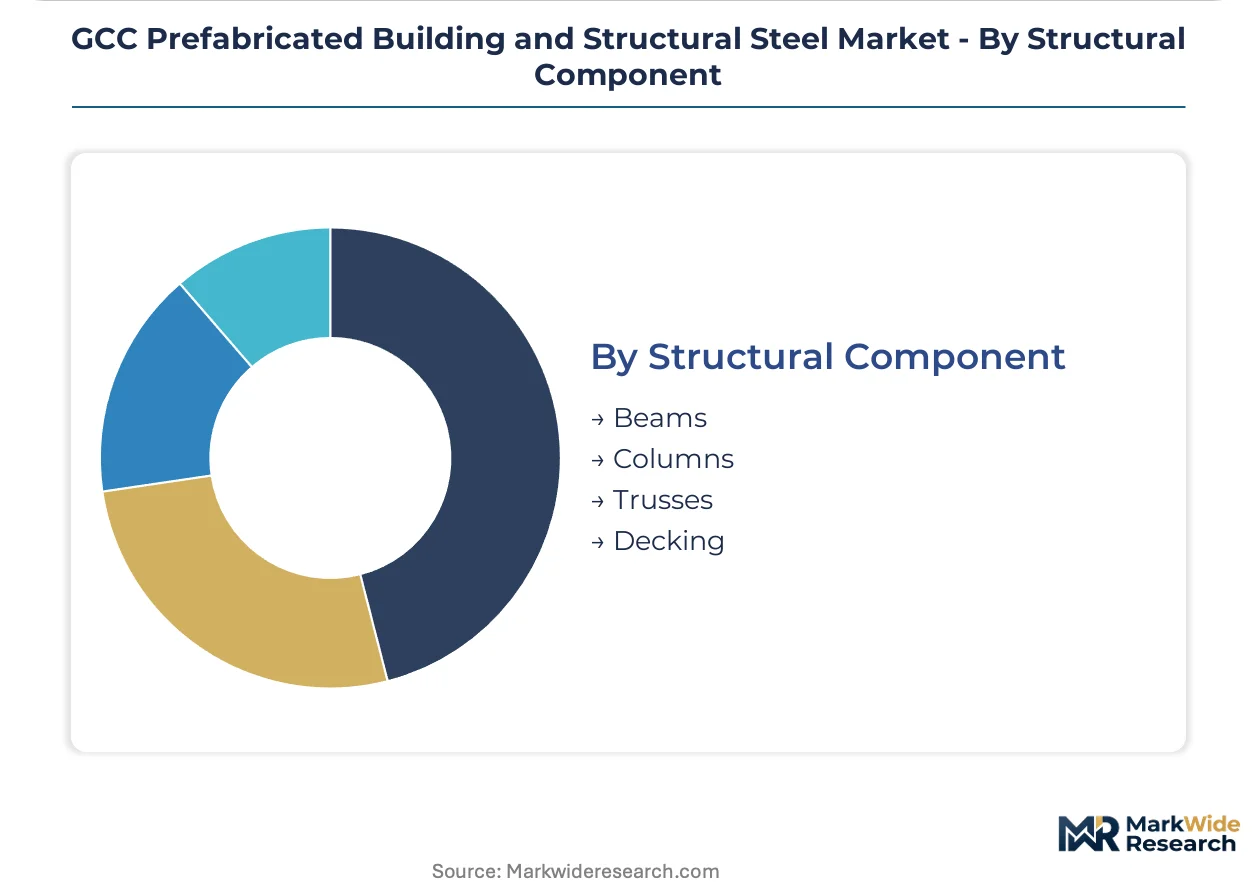
- Beams:Primary horizontal load-bearing members in I-section or fabricated box configurations. Hot-rolled sections from Emirates Steel Arkan and Saudi Arabian mills feed downstream fabricators. Standard profiles dominate warehouse construction.
- Columns:Vertical compression members ranging from rolled sections to built-up fabricated assemblies. High-rise commercial towers in Dubai and Riyadh specify heavy fabricated columns for load concentration.
- Trusses:Triangulated open-web assemblies for long-span roofs and atrium structures. Robotic welding adoption in Dammam-based facilities compresses production economics for complex geometries.
- Decking:Profiled steel sheeting for composite floor slabs and roof diaphragms. Standardized roll-forming equipment produces high volumes for repetitive project types.
Beams and Columns together anchor volume; Trusses expand fastest as airport and exhibition hall specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive hot-rolled coil capacity in Abu Dhabi and Dammam anchors fabrication economics across the Arabian Peninsula. Mill-certificate traceability requirements from Saudi Standards, Metrology and Quality Organization and MOHAP welding protocols reshape procurement toward approved regional suppliers.
Saudi Arabia
NEOM's linear city and Red Sea Project logistics hubs compress construction schedules toward pre-engineered portal frames. The Saudi Building Code mandates seismic resilience thresholds above four stories, filtering fabricator qualification. Dammam and Jubail industrial zones concentrate Zamil Steel's integrated manufacturing footprint.
United Arab Emirates
Al Sa'fat green building regulations reward off-site construction with accelerated permitting for energy-efficient envelopes. MOHAP's federal safety protocols require traceable welding certifications for hospital expansions. Dubai's commercial tower pipeline and Abu Dhabi's downstream steelmaking sustain Emirates Steel Arkan's feedstock dominance.
Kuwait
Silk City and Boubyan Island free-zone developments lack established local fabrication infrastructure. The country's national building regulator imposes structural import documentation similar to Saudi technical regulations. Northern Gulf project sites face extended logistics lead times from Dammam-based suppliers.
Qatar
World Cup legacy infrastructure and North Field expansion sustain industrial steel demand. The national standards body enforces Gulf Standardization Organization conformity marks on structural imports. Doha-based contractors consolidate procurement through pre-qualified vendor panels.
Oman
Duqm Special Economic Zone and port infrastructure projects favor hybrid prefabrication approaches. The Ministry of Commerce, Industry and Investment Promotion monitors national content requirements in public tenders. Sohar's industrial port attracts Saudi and UAE fabricators with mobile production units.
GCC Prefabricated Building and Structural Steel Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized coating and modular healthcare applications. The market structures around three tiers: integrated steelmakers with captive feedstock, dedicated fabricators with certified welding capacity, and project-specific modular specialists. Dominant competitive moves include geographic expansion into Kuwait and Oman, plus BIM-to-fabrication workflow licensing.
Among Saudi-based fabricators, Zamil Steel and Mabani Steel LLC exemplify the scale-driven and specialization archetypes respectively. Emirates Steel Arkan anchors the integrated mill tier through Abu Dhabi-based steelmaking. Arabian International Company for Steel Structures occupies a position within the certified fabrication segment serving commercial tower demand.
| Leading Market Players |
|---|
| Arabian International Company for Steel Structures |
| Mabani Steel LLC |
| Zamil Steel |
| Eversendai Engineering LLC |
| Al Shahin Company for Metal Industries |
| Emirates Steel Arkan |
| Al Yamamah Steel Industries Co. |
| Techno Steel Construction LLC |
| Hidada Ltd Company |
| Others |
Cost & Logistics Intelligence
Saudi giga-project procurement offices concentrate buying power across NEOM and Red Sea developments, forcing tiered pricing structures that unbundle engineering services from raw material supply. Contractors purchasing pre-engineered steel frames face project-based quotations where welding certification depth and BIM integration capabilities determine final award pricing.
Pricing Analysis
Warranty and surface-treatment bundling separates premium fabricators from commodity suppliers across the GCC structural steel market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by welding traceability grade and seismic engineering certification. Cost compression in the economy tier is intensifying because Turkish scrap export volatility feeds into GCC mill feedstock pricing. Industrial warehouse buyers exhibit highest price sensitivity due to standardized portal-frame specifications, while healthcare modular contractors prioritize speed-to-occupancy over unit cost.
Supply Chain Analysis
Saudi and UAE national content mandates are reshaping sourcing patterns toward domestic fabrication capacity and approved regional mill certificates. Hot-rolled coil supply draws from Emirates Steel Arkan's Abu Dhabi complex, Saudi Arabian mills, and limited Omani production. Feedstock dependency rests on ferrous scrap imports, alloy additives, and protective coating chemicals. Single-source vulnerability concentrates in the Jeddah-Dammam corridor where Zamil Steel and integrated fabricators dominate. Distribution runs through project-specific logistics contracts with just-in-time delivery obligations to giga-project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC prefabricated building and structural steel market functions as a vertical-integration race where captive hot-rolled coil supply determines fabricator margin sustainability. Players securing upstream steelmaking capacity or downstream installation capabilities capture pricing power across project tenders.
For Market Incumbents: Hedge against Turkish scrap price volatility through long-term offtake agreements with Emirates Steel Arkan and Saudi Arabian mills. Deepen captive coating and corrosion-protection capabilities to defend margin position against Mabani Steel LLC's specialized coastal-environment offerings. Certification investment in Saudi Standards, Metrology and Quality Organization traceability protocols filters out informal competitors.
For New Entrants and Emerging Players: Kuwaiti healthcare ministry procurement teams represent an underserved buyer archetype with limited local fabrication infrastructure and growing hospital expansion budgets. Mobile production units positioned at Silk City and Boubyan Island sites capture first-mover advantage before Saudi and UAE incumbents establish permanent capacity. Go-to-market positioning through MOHAP-aligned welding certification accelerates vendor panel qualification.
For Investors and Strategic Acquirers: The window for entry favors modular healthcare specialists with integrated MEP engineering partnerships and existing MOHAP safety protocol compliance. Long-term viability hinges on technology licensing for BIM-to-fabrication workflow integration rather than pure capacity plays. Watch for Saudi national content requirement tightening as the inflection signal that reshapes supplier qualification criteria across upcoming tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil | Emirates Steel Arkan's captive steelmaking insulates downstream fabricators from scrap import volatility. |
| BIM-to-Fabrication Workflow Licensing | CNC cutting line integration compresses engineering-to-production cycles for Dammam-based suppliers bidding on complex truss geometries. |
| Mobile Production Unit Deployment | Kuwait's Silk City and Oman's Duqm SEZ lack established fabrication infrastructure, creating geographic expansion openings. |
| Specialized Coating Capability Investment | Mabani Steel LLC's corrosion-protection expertise commands premium positioning for coastal and desert environment specifications. |
| Healthcare Modular Certification Pathway | MOHAP's hospital expansion program favors repeatable patient-room modules with integrated MEP and traceable welding documentation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this GCC prefabricated building and structural steel market analysis. Primary interviews with procurement directors at Saudi giga-project delivery companies, welding certification officers, EPC contractor fabrication managers, and Emirates Steel Arkan distribution leads combined with Saudi Standards, Metrology and Quality Organization technical regulations, MOHAP safety protocols, and GCC customs import documentation. Bottom-up project pipeline aggregation and top-down steel consumption estimates were triangulated to validate volume assumptions.
Data-stream reconciliation across pre-engineered structures, modular buildings, steel frames, and composite panel segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, installation method, and structural component complexity. CAGRs were derived from project-level procurement timing and steel intensity coefficients applied to announced giga-project development schedules. Forecast inputs incorporated Saudi Building Code seismic provision adoption curves and Al Sa'fat green building compliance timelines.
Revisions become necessary when Saudi national content requirements tighten beyond current thresholds or when Turkish scrap export restrictions disrupt GCC mill feedstock economics. Forecasts reflect assumptions about giga-project execution pacing and welding technician training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Girder Market
Structural Construction
H Beam Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Steel Beam Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Global Rebar Splice Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market