
 Vietnam Structural Steel Fabrication Market | 2026-2036
Vietnam Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Structural Steel Fabrication Market Analytics
The Vietnam structural steel fabrication sector is pivoting on a widening gap between premium engineered systems and commodity-grade fabrication. ATAD Steel Structure Corporation leverages its integrated design-build model to capture complex industrial projects requiring seismic compliance. Hoa Phat Group anchors the mid-market through captive hot-rolled coil supply and domestic mill scale. Zamil Steel Buildings Vietnam Company Limited differentiates via pre-engineered building systems optimized for warehouse and logistics clients.
Structural steel fabrication encompasses the cutting, welding, machining, and assembly of hot-rolled or welded sections into load-bearing frameworks for buildings, bridges, and industrial facilities, with typical yield strengths ranging from 235 MPa to 355 MPa per Vietnamese TCVN standards. Beams and columns constitute the dominant product category, reflecting sustained investment in commercial and industrial vertical construction across southern Vietnam. CNC Machining and Plasma Cutting represent the fastest-expanding technology segments as fabricators automate to meet tighter dimensional tolerances and accelerate project delivery timelines.
Vietnam's Ministry of Construction and the Directorate for Standards, Metrology and Quality enforce TCVN structural codes and fire-resistance ratings that directly shape material specifications and fabrication certifications for high-rise and public infrastructure projects. The country's national construction regulator also mandates third-party inspection for welded joints in seismic zones, creating compliance barriers for uncertified workshops. Stakeholders must monitor evolving green building criteria and potential carbon-border adjustments affecting imported steel inputs.
Market Dynamics
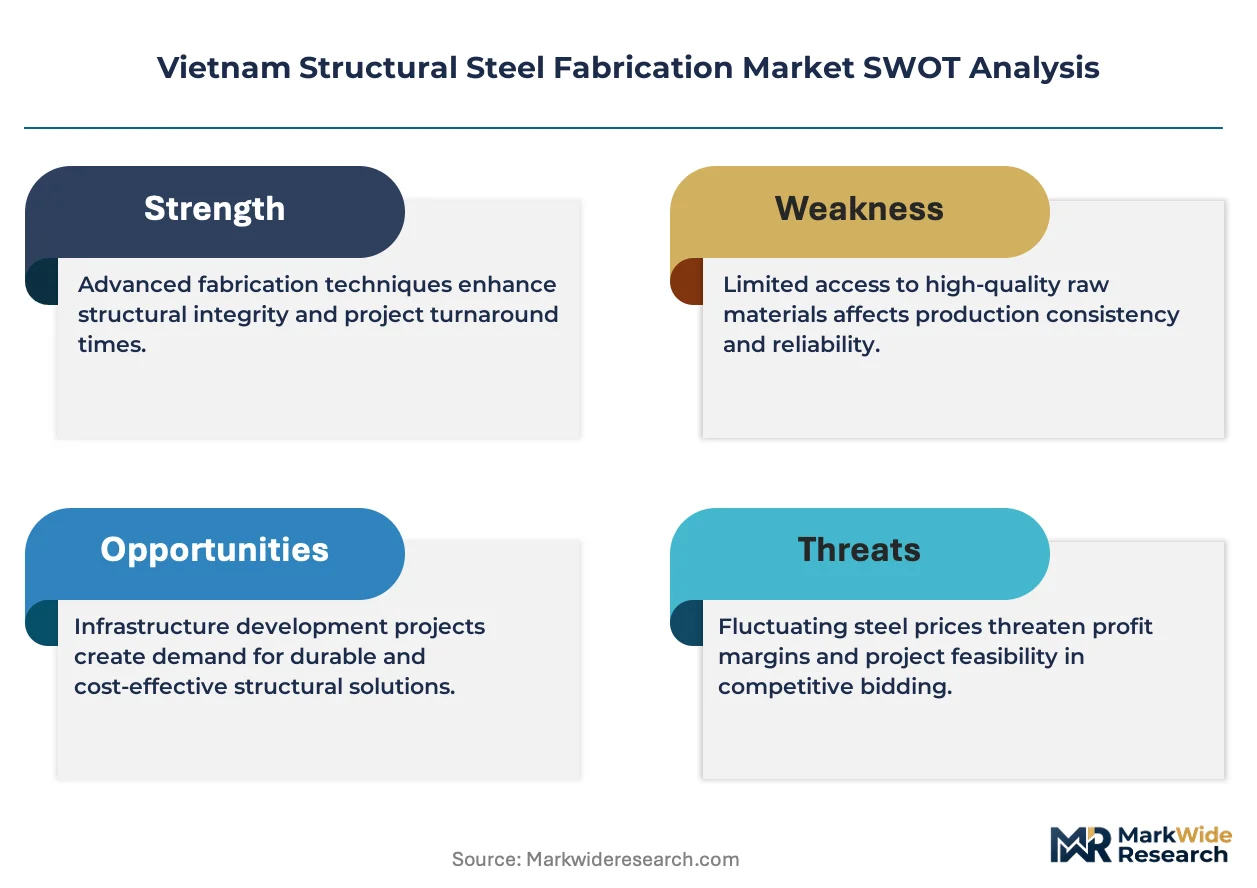
Vietnam's structural steel fabrication sector is bifurcating between automated, certified fabricators serving seismic-grade high-rises and informal workshops supplying commodity warehouse frames. This divergence is compressing margins at the mid-tier while rewarding capital-intensive players with design-build capabilities and captive steel supply.
Growth Catalysts
- Fire-safety mandate escalation:The Ministry of Construction's tightened standards for buildings above twelve stories are disqualifying uncertified fabricators from premium commercial projects. Developers now specify TCVN-compliant seismic detailing as a baseline requirement.
- Industrial corridor expansion:Binh Duong province's logistics hub development is generating sustained demand for pre-engineered warehouse frameworks. Foreign manufacturers relocating from China require rapid-build steel facilities with shorter construction cycles than concrete alternatives.
- Seismic resilience preference:Moment-resisting steel frames are displacing reinforced concrete in Ho Chi Minh City's high-rise market due to superior ductility during earthquakes. Structural engineers increasingly specify steel for buildings exceeding twenty stories.
Market Restraints
- Hot-rolled coil import dependency:Vietnamese fabricators rely on imported HRC from China and South Korea, exposing margins to currency volatility and regional supply disruptions. Domestic flat-rolled capacity at Hoa Phat Dung Quat cannot fully substitute for specialized grades.
- Welding certification scarcity:The Directorate for Standards, Metrology and Quality mandates third-party inspection for seismic-zone welded joints. Certified welding inspectors are concentrated in Ho Chi Minh City, creating bottlenecks for provincial fabricators.
- Concrete substitution persistence:Cost-sensitive residential developers in secondary cities continue specifying reinforced concrete frames for mid-rise buildings. Steel's speed advantage is undervalued where labor costs remain low and project timelines are flexible.
Strategic Opportunities
- Central Highlands logistics penetration:Dak Lak and Gia Lai provinces lack established structural steel supply chains despite accelerating agro-industrial investment. First-mover fabricators can anchor regional distribution networks before competition intensifies.
- Green building certification alignment:Vietnam's pending adoption of LEED and LOTUS criteria for public projects will favor steel's recyclability and lighter embodied carbon versus concrete. Fabricators with environmental product declarations can differentiate in government tenders.
- BIM-to-fabrication integration:Converting building information models directly into CNC machine instructions is compressing rework rates and accelerating delivery timelines. Early adopters are securing design-build contracts with foreign engineering firms.
Industry Challenges
- Skilled welder attrition:Vietnam's vocational training pipeline produces insufficient certified welders for TCVN seismic compliance. Fabricators compete with shipbuilding and offshore oil for experienced tradespeople, driving wage inflation.
- Automation capex recovery:Plasma cutting and robotic welding systems require substantial upfront investment with payback periods exceeding three years. Mid-tier workshops face credit constraints for equipment upgrades.
- Multi-standard certification burden:Export-oriented fabricators must simultaneously maintain TCVN, AWS D1.1, and Eurocode compliance. Audit costs and documentation complexity strain quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Structural Steel Fabrication Market |
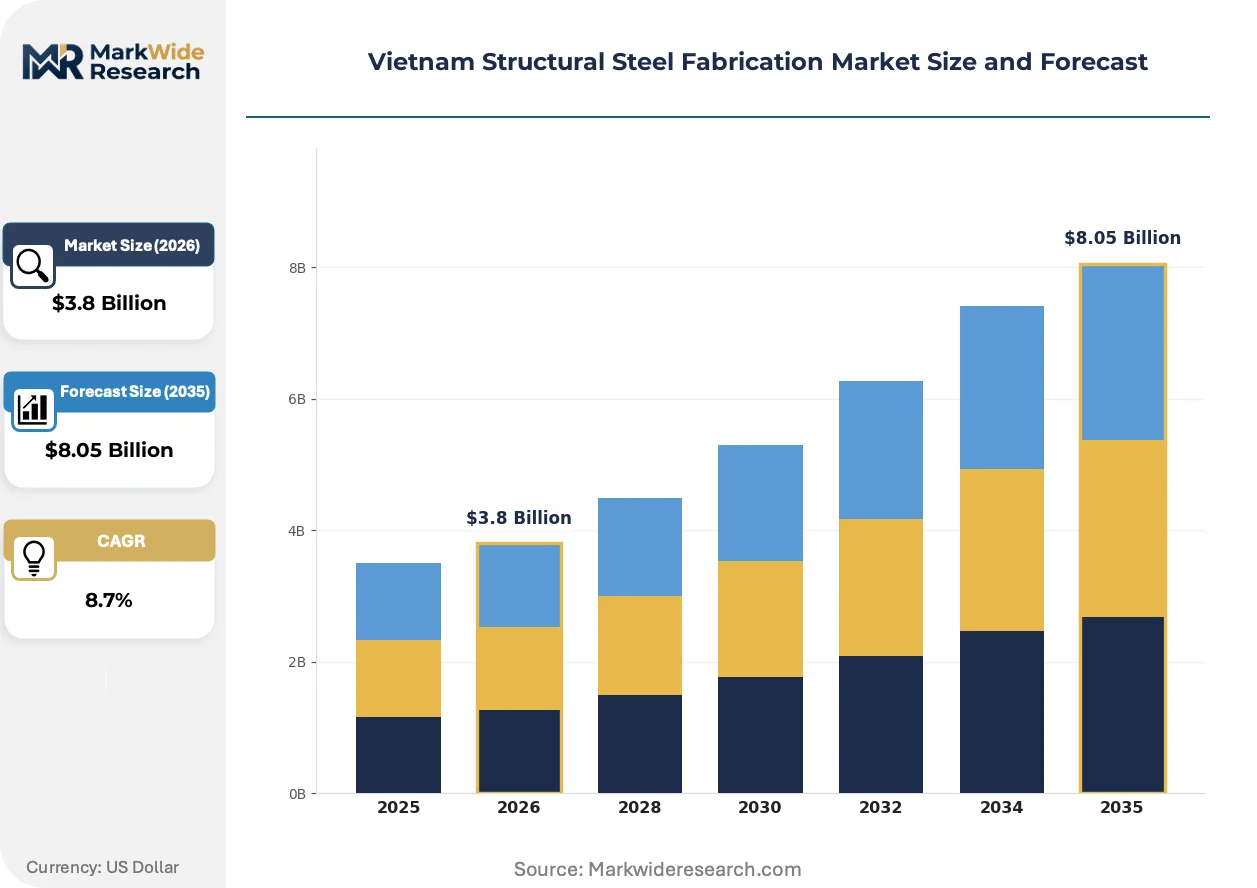
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Columns, Plates, Trusses Technology: Mig Welding, Tig Welding, Plasma Cutting, CNC Machining End User: Construction, Manufacturing, Infrastructure, Oil & Gas Application: Residential, Commercial, Industrial, Composite Structures |
| Companies Covered | ATAD Steel Structure Corporation, Zamil Steel Buildings Vietnam Company Limited, Hoa Phat Group, Viet Y Steel, Nam Kim Steel, Formosa Ha Tinh Steel, PEB Steel, Newinds Corporation Vietnam, Hoa Sen Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Structural Steel Fabrication Market Evolving Landscape
Fabrication technology, regulatory enforcement, and procurement sophistication are converging to reshape competitive positioning in Vietnam's structural steel sector. These forces favor capital-intensive operators while marginalizing traditional craft-based workshops.
CNC plasma cutting systems with integrated nesting software are automating material optimization and reducing scrap rates below three percent. Large commercial contractors in Ho Chi Minh City now mandate dimensional tolerances of plus-or-minus two millimeters, achievable only through automated processing. This capability gap is automating the exclusion of manual cutting shops from premium project bidding.
Vietnam's Ministry of Construction is tightening enforcement of TCVN 2737 seismic design codes through mandatory peer review for structures exceeding twelve stories. The regulation requires documented weld procedures and inspector qualifications that many provincial workshops cannot satisfy. High-rise developers are responding by consolidating supplier lists to pre-qualified fabricators with certified quality management systems.
Design-build contracting is displacing traditional bid-build procurement in industrial and logistics construction. Foreign manufacturing tenants prefer single-source accountability for structural performance and schedule certainty. This preference shift is most visible in Binh Duong province, where warehouse developers now award turnkey steel packages to integrated fabricators rather than managing separate design and construction contracts.
Vietnam Structural Steel Fabrication Market Segmentation
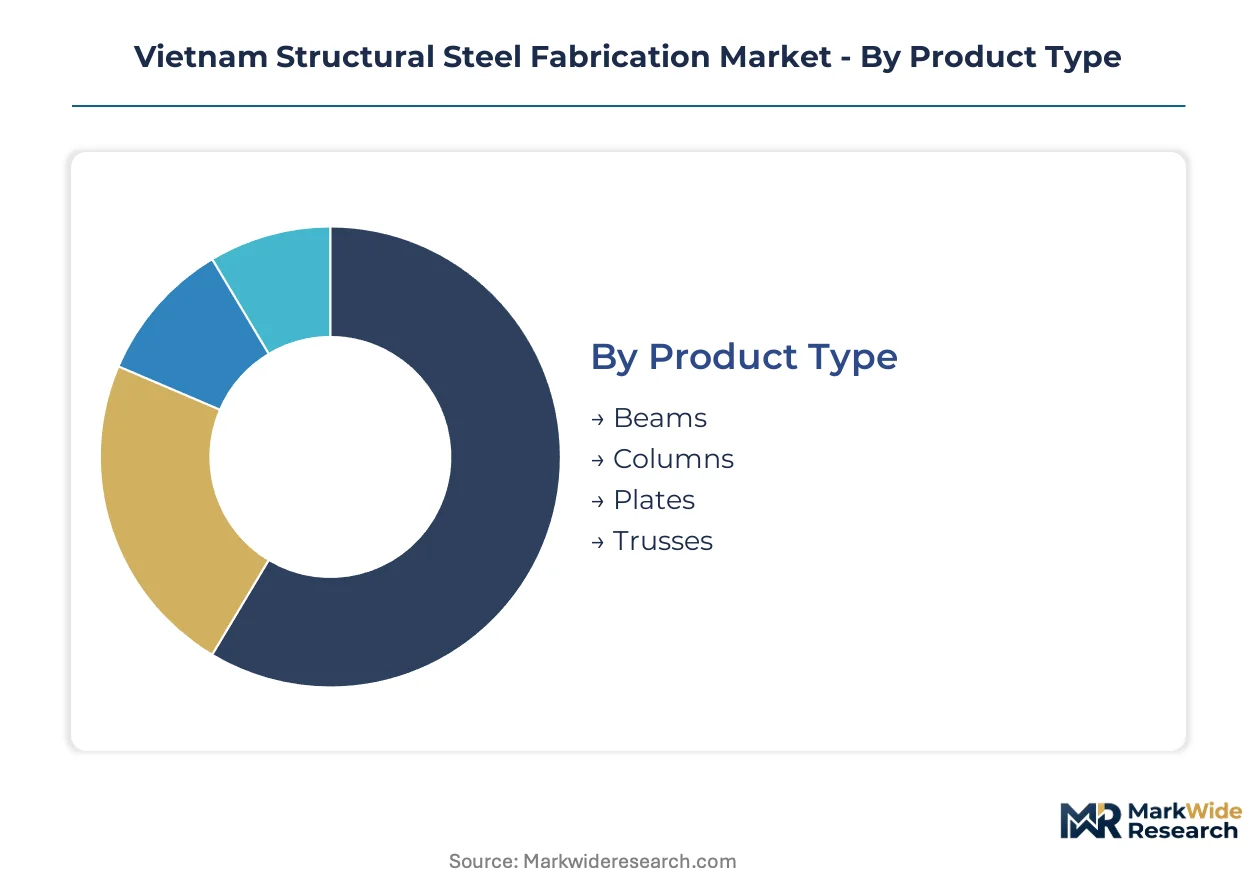
Segmentation in Vietnam's structural steel fabrication market reveals divergent capability requirements across product complexity and end-use criticality. Fabricators must align equipment investments and certification portfolios with specific segment demands to avoid capability mismatches.
Product Type:
Customization intensity varies sharply across this category, from standardized rolled sections to project-specific engineered assemblies.
- Beams:Hot-rolled I-sections and welded plate girders with yield strengths of 235-355 MPa per TCVN standards constitute the volume anchor. Ho Chi Minh City high-rise developers specify moment-resisting beam-column connections with documented weld procedures for seismic compliance.
- Columns:Box sections and built-up H-columns deliver axial load capacity for commercial towers exceeding twenty stories. Binh Duong industrial corridor demand concentrates in rigid-frame warehouse columns requiring rapid field bolting.
- Plates:Flame-cut base plates and gusset plates for connection detailing.
- Trusses:Roof framing systems for long-span industrial buildings.
Most installed capacity flows through Beams. Expansion is steepest in Columns.
Technology:
Automation depth separates premium fabricators from commodity suppliers in this category.
- CNC Machining:Computer-numerical control drilling and milling systems achieve plus-or-minus two-millimeter tolerances mandated by large Ho Chi Minh City contractors. Automated nesting software reduces scrap rates below three percent, compressing material costs for competitive bidding.
- Plasma Cutting:High-definition plasma systems with integrated CAD/CAM interfaces process plate thicknesses up to fifty millimeters for heavy industrial applications. The technology is displacing oxy-fuel cutting in Binh Duong workshops serving foreign manufacturing relocations from China.
- Mig Welding:Gas metal arc welding for high-deposition production joints.
- Tig Welding:Gas tungsten arc welding for precision aesthetic and root passes.
Most installed capacity flows through Mig Welding. CNC Machining is climbing the fastest.
End User:
Contracting sophistication and technical specification rigor vary substantially across buyer categories.
- Construction:Commercial high-rise and industrial building contractors dominate procurement volume. Fire-safety mandates from Vietnam's Ministry of Construction for structures above twelve stories restrict supplier qualification to certified fabricators with third-party weld inspection capabilities.
- Manufacturing:Foreign-owned electronics and automotive assembly plants require rapid-build steel facilities with single-source design-build accountability. Binh Duong province logistics hub development sustains demand for pre-engineered building systems with compressed construction cycles.
- Infrastructure:Bridge and public works projects with government tender requirements.
- Oil & Gas:Offshore platform and petrochemical structural modules.
Most installed capacity flows through Construction. Manufacturing is gaining share fastest.
Application:
Performance requirements and regulatory exposure create distinct margin profiles across use cases.
- Commercial:Office towers and retail complexes in Ho Chi Minh City drive specification of seismic-grade moment frames with TCVN 2737 compliance. Developers consolidate supplier lists to pre-qualified fabricators with certified quality management systems, excluding provincial workshops.
- Industrial:Warehouse and factory structures prioritize speed and cost over architectural refinement. Pre-engineered building systems from integrated design-build specialists capture dominant share in Binh Duong province.
- Residential:Mid-rise apartment buildings in secondary cities where concrete substitution persists.
- Composite Structures:Steel-concrete hybrid systems for enhanced stiffness.
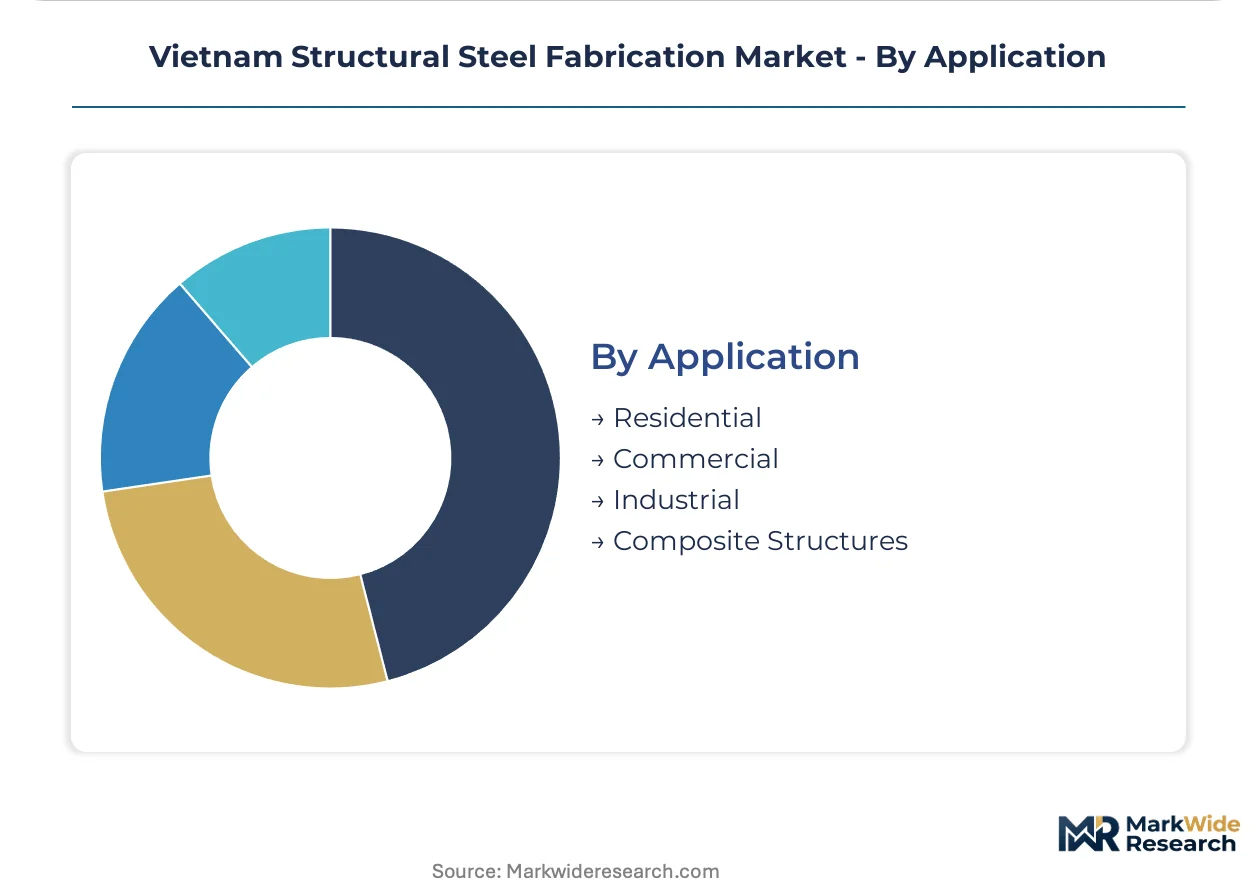
Most installed capacity flows through Industrial. Commercial shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders and structural engineers cluster disproportionately in Ho Chi Minh City and its industrial periphery, creating a talent moat that shapes competitive geography across Vietnam's fabrication sector.
Southern Region
Ho Chi Minh City high-rise developers specify moment-resisting steel frames for towers exceeding twenty stories. Vietnam's Ministry of Construction mandates third-party weld inspection for seismic-zone projects, restricting qualified supplier pools. Binh Duong province anchors pre-engineered warehouse demand as foreign manufacturers relocate from China.
Central Region
Da Nang's logistics corridor generates emerging demand for rapid-build industrial facilities. The Directorate for Standards, Metrology and Quality extends TCVN compliance requirements to central provinces, elevating certification barriers. Quang Nam industrial zones attract electronics manufacturers requiring turnkey steel packages.
Northern Region
Hanoi commercial construction favors concrete frames for cost-sensitive mid-rise buildings. The Ministry of Construction's fire-safety mandates apply less stringently outside seismic priority zones. Hai Phong port infrastructure sustains steel import throughput for redistributed southern fabrication.
Central Highlands
Dak Lak and Gia Lai provinces lack established structural steel supply chains despite accelerating agro-industrial investment. Provincial regulators adopt TCVN codes with enforcement lags. First-mover fabricators can anchor regional distribution networks before competition intensifies.
Mekong Delta
Can Tho logistics hub development creates nascent demand for warehouse frameworks. Flood-resilient elevated steel structures attract climate-adaptive design specifications. Local fabricators remain uncertified for seismic-grade commercial projects, importing from Ho Chi Minh City suppliers.
Vietnam Structural Steel Fabrication Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Vietnam's bifurcated fabrication sector. Automated, certified workshops serving seismic-grade high-rises command premium pricing while informal commodity suppliers compress margins at the mid-tier. Three archetypes dominate: integrated steel mill-fabricators with captive raw material supply, design-build specialists capturing turnkey industrial contracts, and regional workshops serving undifferentiated warehouse demand. Capacity expansion and certification acquisition constitute the dominant competitive moves as players reposition for tightened regulatory enforcement.
Among Vietnam-based fabricators, ATAD Steel Structure Corporation, Hoa Phat Group, and Zamil Steel Buildings Vietnam Company Limited exemplify contrasting strategic positions within this tiered structure. ATAD occupies a position as an integrated design-build specialist. Hoa Phat anchors the mid-market through upstream control over hot-rolled coil supply. Zamil represents the pre-engineered building systems archetype optimized for logistics and warehouse deployment.
| Leading Market Players |
|---|
| ATAD Steel Structure Corporation |
| Zamil Steel Buildings Vietnam Company Limited |
| Hoa Phat Group |
| Viet Y Steel |
| Nam Kim Steel |
| Formosa Ha Tinh Steel |
| PEB Steel |
| Newinds Corporation Vietnam |
| Hoa Sen Group |
| Others |
Value Network & Pricing Analysis
CNC plasma cutting adoption among Ho Chi Minh City fabricators compresses per-unit processing costs while concentrating premium capacity in certified workshops. This technology shift simultaneously widens the bid spread between automated seismic-grade suppliers and manual commodity shops across Vietnam's southern industrial corridor.
Pricing Analysis
Design-build bundling versus component-only supply splits the market into two pricing regimes. Three-tier pricing structure across premium certified, mid-market compliant, and economy-grade levels reflects TCVN seismic certification status and third-party weld inspection coverage. Cost compression in the mid-tier intensifies because Hoa Phat's captive hot-rolled coil supply undercuts import-dependent competitors. Foreign manufacturing tenants relocating to Binh Duong show least price sensitivity, prioritizing schedule certainty over unit cost.
Supply Chain Analysis
Vietnam's domestic-content preferences for public infrastructure projects reshape sourcing patterns toward local TCVN-certified mills. Raw material flows draw from China, South Korea, and Japan for specialized high-strength grades that Hoa Phat Dung Quat cannot yet substitute. Single-source vulnerability concentrates in imported hot-rolled coil exposed to currency volatility and regional supply disruptions. Distribution runs through Ho Chi Minh City-based fabricators with certified quality management systems serving Binh Duong industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's structural steel fabrication market functions as a regulatory compounder where TCVN 2737 seismic code enforcement for buildings above twelve stories continuously upgrades demand specifications.
For Market Incumbents: Deepen captive hot-rolled coil supply through upstream capacity expansion at Dung Quat or backward integration into specialized grade imports. Defend against Zamil Steel's pre-engineered building systems by embedding BIM-to-fabrication workflows that compress design-build delivery timelines for Binh Duong logistics developers. For New Entrants and Emerging Players: Begin with uncertified provincial workshops in Dak Lak and Gia Lai provinces where agro-industrial investment outpaces structural steel supply chain development. Target rapid-build warehouse frameworks for foreign agricultural processors requiring climate-adaptive elevated structures. Lead with TCVN certification acquisition to bridge toward seismic-grade commercial eligibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fabricators squeezed between Hoa Phat's raw material dominance and ATAD's design-build integration. Long-term viability favors operators with demonstrated TCVN compliance and CNC automation deployed across the projection horizon. Monitor Ministry of Construction fire-safety mandate expansion beyond twelve-story thresholds as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| TCVN Certification Acquisition | Unlocks bidding eligibility for Ho Chi Minh City high-rise projects above twelve stories. |
| CNC Plasma Cutting Deployment | Achieves plus-or-minus two-millimeter tolerances mandated by large commercial contractors. |
| Backward Integration into HRC Supply | Reduces exposure to China and South Korea import volatility for specialized grades. |
| BIM-to-Fabrication Integration | Compresses rework rates and accelerates design-build contract capture from foreign engineering firms. |
| Central Highlands Distribution Network | Anchors regional supply position before competition intensifies in Dak Lak and Gia Lai provinces. |
Research Methodology
Direct dialogue with fabrication plant managers, procurement leads at Binh Duong industrial developers, TCVN certification auditors, and structural engineering consultants grounded qualitative findings. Secondary validation drew from Vietnam Ministry of Construction regulatory filings, Directorate for Standards, Metrology and Quality certification databases, customs import records for hot-rolled coil, and Hoa Phat Group production disclosures. Bottom-up capacity assessments and top-down construction spending trajectories were triangulated against project pipeline tracking.
Segmented outputs across product type, technology tier, end-user category, and application use case were generated through the analytical framework. CAGRs were derived from regression analysis against construction permit data and foreign direct investment flows into industrial zones. Modeled inputs included TCVN code enforcement timelines, CNC automation adoption curves, and Binh Duong logistics hub development schedules across the projection horizon.
Caveats apply where Ministry of Construction regulatory delays, hot-rolled coil import disruptions, or certified welder supply constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding TCVN 2737 enforcement consistency and foreign manufacturing relocation velocity from China. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Bridge Construction Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Bridge Bearings Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Steel Beam Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
H Beam Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Girder Market
Structural Construction
Global Rebar Splice Market