
 Glue Laminated Beams Market | 2026-2036
Glue Laminated Beams Market Size, Share, and Industry Trends Forecast 2026-2036
Glue Laminated Beams Market Foresight
Product tier divergence in glue laminated beams is rebalancing as premium custom and curved configurations command specification-driven margins while standard beams face commoditization pressure. Boise Cascade leverages its integrated Pacific Northwest timber base to control raw material flows into structural laminating operations. Binderholz GmbH anchors Central European supply through vertically managed sawmilling and glulam finishing capacity. PFEIFER GROUP specializes in architecturally exposed systems for landmark projects, competing on engineering depth rather than volume scale.
Glue laminated beams consist of kiln-dried lumber laminations bonded with moisture-resistant adhesives under controlled clamping pressure, typically achieving flexural strengths of 24-30 MPa in standard grades for primary structural spans. Standard beams occupy the volume base for residential and routine commercial framing, while curved and box beam configurations capture disproportionate margin pools in sports facilities and cultural centers where visual expressiveness governs selection. Douglas fir and spruce species dominate North American and European supply chains respectively, with species choice tracking regional sawmill availability and design stress requirements.
Building codes incorporating mass timber provisions from the International Code Council in the United States and Eurocode 5 design standards under EOTA technical approvals in Europe are expanding permissible height and span applications for glulam systems. EPA TSCA Title VI formaldehyde emission limits and CE marking under Construction Products Regulation enforce adhesive chemistry and factory production control standards that filter market access. Stakeholders must monitor evolving carbon accounting rules embedded in procurement frameworks, as embodied carbon disclosure shifts from voluntary differentiation to mandatory bid qualification.
Market Dynamics
Mass timber building code amendments and embodied carbon disclosure mandates are compressing specification cycles for engineered wood systems, forcing laminators to certify production under multiple jurisdictional standards simultaneously.
Growth Catalysts
- EU Green Deal procurement criteria:Public tenders above specific thresholds now require whole-life carbon assessments that favor laminated timber over steel and concrete for institutional frameworks.
- Sports facility architecture:Long-span roof structures for arenas and aquatic centers specify curved glulam configurations for their structural efficiency and visual impact.
- Cross-laminated timber integration:Hybrid construction systems combining CLT floor plates with glulam frames simplify erection logistics for mid-rise commercial buildings.
Market Restraints
- Spruce lamstock supply concentration:European laminators depend on Alpine and Nordic sawmill regions where beetle damage and harvesting restrictions constrain kiln-dried input availability.
- Moisture-resistant adhesive cost volatility:Phenol resorcinol formaldehyde and polyurethane formulations track petrochemical feedstock prices that fluctuate with energy market swings.
- Steel-frame substitution in seismic zones:High ductility requirements in earthquake-prone jurisdictions limit glulam penetration for lateral force-resisting systems.
Strategic Opportunities
- Retrofit and adaptive reuse:Historic building renovations in Germany and Austria create demand for custom-curved beams that match existing masonry profiles while upgrading structural capacity.
- Digital fabrication convergence:CNC machining paired with parametric design software enables mass-customization of complex geometries without manual templating overhead.
- US Inflation Reduction Act tax credits:Low-carbon construction incentives embedded in federal procurement guidelines redirect federal building specifications toward certified mass timber.
Industry Challenges
- Structural engineer capacity constraints:Specialized timber design expertise remains concentrated among boutique firms, creating bottlenecks for project documentation and peer review.
- Multi-jurisdictional certification timelines:Securing CCMC listings in Canada, EOTA approvals in Europe, and ICC-ES reports in the United States requires parallel testing programs that extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue Laminated Beams Market |
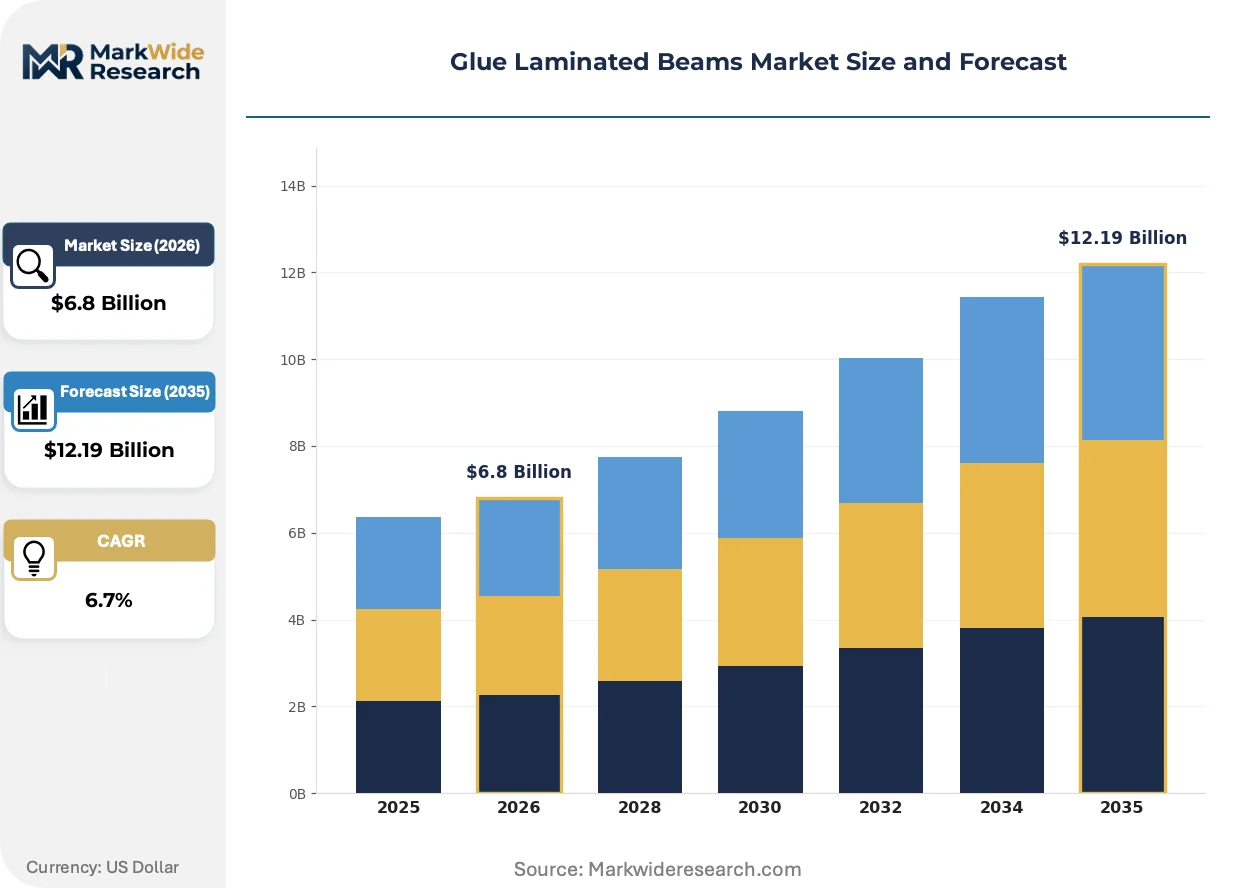
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Beams, Custom Beams, Curved Beams, Box Beams, Tapered Beams Wood Species: Pine, Douglas Fir, Spruce, Hemlock, Redwood, Cedar Application: Residential Construction, Commercial Buildings, Bridges, Sports Facilities, Cultural Centers End User: General Contractors, Structural Engineers, Architects, Fabricators, Building Owners |
| Companies Covered | Mayr-Melnhof Holz Holding AG, Boise Cascade, Binderholz GmbH, Western Forest Products, Stora Enso Oyj, Hasslacher Holding GmbH, Setra Group AB, Canfor, PFEIFER GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue Laminated Beams Market Shifts & Advancements
Computational design tools and automated manufacturing are collapsing the traditional trade-off between custom geometry and production efficiency in structural timber.
Hybrid adhesive systems combining melamine-urea-formaldehyde with polyurethane crosslinkers are unifying the performance characteristics of interior and exterior-grade laminations. Manufacturers in Austria and Germany have adopted these formulations for production runs that serve both protected and exposed applications without line changeovers. This chemistry consolidation is compressing inventory complexity while maintaining the moisture durability required for open-joint façade systems.
EPA TSCA Title VI formaldehyde emission standards and their state-level California Air Resources Board extensions are tightening factory production control requirements for structural wood adhesives. Laminators must maintain third-party certification and quarterly testing protocols that filter smaller producers from institutional supply chains. The compliance burden falls most heavily on curved and architectural beam specialists whose lower volumes spread fixed certification costs across fewer units.
Architects and developers now bundle carbon accounting with structural specifications, requiring Environmental Product Declarations and biogenic carbon calculations at schematic design phases. Engineering firms in Scandinavia and the Pacific Northwest have restructured proposal workflows to front-load embodied carbon analysis alongside structural capacity checks. This behavioral shift compresses the window for material substitution decisions and privileges laminators with verified supply chain transparency.
Glue Laminated Beams Market Segmentation
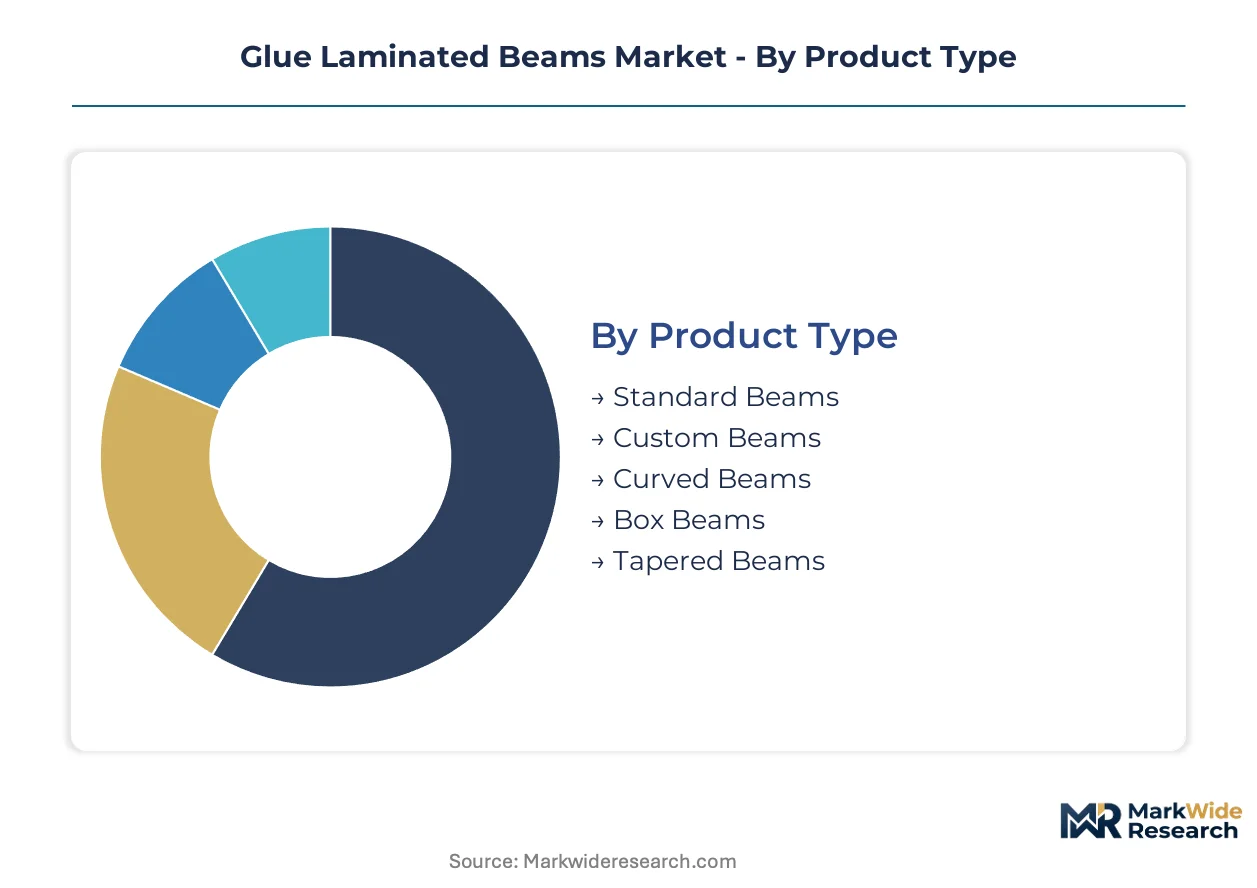
Glue laminated beams fragment across five distinct product configurations, six wood species, and four primary demand channels. Specification complexity rises with architectural exposure requirements, while raw material availability anchors regional supply patterns.
Product Type:
Volume concentrates in standardized straight beams for routine framing, while premium pools concentrate in custom geometries where engineering depth commands specification margins.
- Standard Beams:Straight, parallel-laminar configurations with uniform cross-sections dominate residential and routine commercial procurement. Kiln-dried laminations bonded with phenol resorcinol formaldehyde achieve 24-30 MPa flexural strength for primary spans up to 30 meters in Germany and the United States.
- Curved Beams:Architecturally exposed configurations for sports arenas and aquatic centers require CNC-machined laminations bent under controlled clamping pressure. Visual expressiveness governs selection for long-span roof structures in Austria and Switzerland.
- Custom Beams:Project-specific dimensions and connection details serve adaptive reuse and historic renovation projects. German fabricators specialize in matching existing masonry profiles while upgrading structural capacity.
- Box Beams:Hollow rectangular sections reduce self-weight while maintaining bending stiffness for mid-rise commercial frames. Integration with CLT floor plates simplifies erection logistics in hybrid mass timber systems.
- Tapered Beams:Variable-depth configurations optimize material distribution for cantilevered canopies and entry portals. Pacific Northwest manufacturers leverage Douglas fir availability for exterior-exposed applications.
Today's leader: Standard Beams. Tomorrow's challenger: Curved Beams.
Wood Species:
Regional sawmill availability dictates species selection, with design stress requirements filtering permissible substitutions.
- Douglas Fir:Dense, high-strength laminations from Pacific Northwest timber bases serve heavy commercial and bridge applications. Boise Cascade controls raw material flows into structural laminating operations through integrated ownership.
- Spruce:Alpine and Nordic kiln-dried supply chains anchor Central European glulam production. Beetle damage and harvesting restrictions in Austrian and German forest regions constrain lamstock availability for institutional projects.
- Pine:Southern yellow and European species offer cost-competitive alternatives for protected interior applications. Lower density limits exterior exposure without supplemental preservative treatment.
- Hemlock:Eastern North American availability supports regional residential markets. Lower mechanical properties restrict span capabilities compared to Douglas fir.
- Redwood:Decay-resistant heartwood suits exposed coastal and high-moisture environments. Limited old-growth supply concentrates procurement in premium architectural segments.
- Cedar:Natural durability and dimensional stability serve exterior fascia and screening applications. Western red cedar from British Columbia feeds Pacific Coast custom fabrication.
Supply gravity centers on Spruce and Douglas Fir, with Cedar gaining share fastest in exposed architectural niches.
Application:
Institutional and commercial frameworks drive specification complexity, while residential volume spreads across standardized inventory.
- Commercial Buildings:Mid-rise office and retail frames specify hybrid CLT-glulam systems for speed of erection. US Inflation Reduction Act tax credits redirect federal procurement toward certified mass timber.
- Sports Facilities:Arenas and aquatic centers demand curved and tapered configurations for structural efficiency and visual impact. Long-span roof structures in Germany and Austria showcase architecturally exposed timber.
- Residential Construction:Single-family and multi-family framing consumes standard straight beams through distributor inventory. Cost competition with engineered wood I-joists limits glulam penetration in routine spans.
- Cultural Centers:Museums and performance venues prioritize aesthetic expressiveness in specification decisions. PFEIFER GROUP specializes in landmark projects competing on engineering depth rather than volume scale.
- Bridges:Pedestrian and light vehicular spans exploit high strength-to-weight ratios for accelerated bridge construction. Moisture durability requirements enforce polyurethane adhesive specifications.
Commercial Buildings anchor current procurement volumes. Sports Facilities show the steepest expansion trajectory as EU Green Deal criteria favor low-carbon materials.
End User:
Specification influence fragments across the project delivery chain, with architects and structural engineers filtering product selection before procurement execution.
- Architects:Design-phase specification of exposed timber systems governs product tier selection. Computational design tools and parametric software enable mass-customization of complex geometries.
- Structural Engineers:Capacity verification and connection design create bottlenecks for project documentation. Specialized timber expertise remains concentrated among boutique firms in Scandinavia and the Pacific Northwest.
- General Contractors:Procurement execution and erection sequencing influence adhesive chemistry and prefabrication choices. Multi-jurisdictional certification timelines extend product launch schedules for international projects.
- Fabricators:CNC machining and finishing operations add value through precision cutting and preservative treatment. Austrian and German specialists dominate curved and architectural beam production.
- Building Owners:Whole-life carbon accounting and operational energy performance increasingly filter material selection. Environmental Product Declarations and biogenic carbon calculations now enter schematic design phases.
Architects control specification gates today. Building Owners are consolidating influence fastest through embodied carbon disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized timber engineers and CNC machinists concentrate in Alpine valleys and Pacific Northwest mill towns, anchoring glulam production capacity close to sawmill resources. Their expertise enables curved-beam fabrication for architecturally exposed structures.
Germany
Sports arena construction in Munich and Berlin drives specification of long-span curved configurations. The EU Green Deal procurement criteria mandate whole-life carbon assessments for public tenders above defined thresholds. Baden-Württemberg fabricators supply custom beams matching historic masonry profiles in adaptive reuse projects.
Austria
Alpine tourism infrastructure and cultural center expansions sustain demand for visually expressive timber structures. EOTA technical approvals under Eurocode 5 govern design stress calculations for institutional frameworks. Styrian and Tyrolean laminators integrate vertically from sawmilling through CNC finishing for architectural beam production.
United States
Federal building procurement under the Inflation Reduction Act redirects specifications toward certified mass timber systems. EPA TSCA Title VI formaldehyde emission limits enforce adhesive chemistry standards for structural laminations. Pacific Northwest Douglas fir supply chains feed Boise Cascade's integrated laminating operations in Idaho and Washington.
Canada
Mid-rise commercial hybrid construction combining CLT floor plates with glulam frames accelerates in Vancouver and Toronto. CCMC listings required for national building code compliance filter market access for imported adhesive systems. British Columbia coastal mills supply western red cedar for exterior-exposed architectural applications.
Switzerland
Municipal building codes in Zurich and Geneva favor low-carbon materials for public institutional frameworks. CE marking under Construction Products Regulation enforces factory production control for moisture-resistant adhesive bonds. Alpine fabricators specialize in precision-curved beams for ski resort and wellness center roof structures.
Glue Laminated Beams Market Competitive Landscape
Top-tier vendors anchor premium architectural and curved-beam segments, while volume-scale producers compete on lamstock integration and distributor reach. The vendor base stratifies across three tiers: integrated forest-products conglomerates controlling raw material flows, mid-cap specialists commanding specification-driven margins in custom geometries, and regional laminators serving residential inventory channels. Strategic archetypes include backward-integrated sawmill operators, engineering-heavy architectural beam specialists, and hybrid mass timber system providers. Competitive positioning depends on captive lamstock supply and multi-jurisdictional certification depth.
Among integrated forest-products groups, Boise Cascade and Canfor exemplify backward-integrated structures with captive timber bases feeding structural laminating operations. Binderholz GmbH occupies a position within Central European vertically managed supply chains. PFEIFER GROUP represents the engineering-depth archetype, anchoring specification influence in landmark cultural and sports facility projects where parametric design capabilities govern selection.
| Leading Market Players |
|---|
| Mayr-Melnhof Holz Holding AG |
| Boise Cascade |
| Binderholz GmbH |
| Western Forest Products |
| Stora Enso Oyj |
| Hasslacher Holding GmbH |
| Setra Group AB |
| Canfor |
| PFEIFER GROUP |
| Others |
Supply & Pricing Matrix
Kiln-dried lamstock costs cascade through three pricing tiers as Alpine and Nordic sawmill concentration grants upstream leverage to integrated producers. Phenol resorcinol formaldehyde adhesive formulations track petrochemical volatility, compressing margins for non-integrated laminators serving institutional procurement channels.
Pricing Analysis
Engineering services bundle with physical product for curved and architectural beam configurations, while standard straight beams trade on unbundled per-meter rates. Three-tier pricing structure across premium custom geometries, standard structural grades, and economy residential inventory reflects certification depth and visual grading protocols. Pricing pressure stems from spruce lamstock supply constraints in beetle-damaged Austrian forest regions. Residential distributors exhibit highest price sensitivity, while cultural center developers prioritize embodied carbon credentials over unit cost.
Supply Chain Analysis
Regional distribution centers in Munich, Vienna, and Portland anchor hub-and-spoke patterns for just-in-time delivery to construction sites. Supply concentrates in Germany, Austria, and the United States where vertically integrated sawmill-laminator complexes control lamstock flows. Production draws from Douglas fir in the Pacific Northwest, spruce in Alpine regions, and western red cedar from British Columbia. Single-source vulnerability in moisture-resistant adhesive chemistry exposes laminators to energy market swings. Distribution runs through specialized structural timber distributors with CNC finishing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Glue Laminated Beams Market compounds steadily as EU Green Deal procurement criteria embed low-carbon materials into public tender mandates. Mass timber building code amendments expand addressable span and height applications across institutional frameworks.
For Market Incumbents: Deepen backward integration into kiln-dried lamstock supply through long-term harvesting concessions in beetle-impacted Alpine regions. Secure multi-jurisdictional certification depth under EOTA technical approvals and ICC-ES reports to defend specification influence against emerging hybrid mass timber system providers. For New Entrants and Emerging Players: Launch via digital fabrication partnerships with parametric design studios serving sports facility architects. Target adaptive reuse and historic renovation segments in German cities where custom-curved beam demand outstrips CNC machining capacity. White-space exists in mid-rise commercial hybrid CLT-glulam systems for US federal procurement under Inflation Reduction Act tax credit guidelines. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering-heavy architectural beam specialists lack captive lamstock supply and face spreading fixed certification costs across low volumes. Five-to-ten year viability favors vertically integrated Central European laminators with Eurocode 5 design approval depth. Monitor carbon accounting rulemaking in procurement frameworks as the inflection signal for mandatory bid qualification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lamstock Supply | Secures kiln-dried spruce and Douglas fir flows against Alpine beetle damage and Nordic harvesting restrictions. |
| Multi-Jurisdictional Certification Investment | Unlocks institutional procurement in Germany, Austria, and US federal frameworks under divergent building codes. |
| CNC Machining and Digital Fabrication Partnership | Enables mass-customization of curved geometries for sports arena and cultural center specifications. |
| Environmental Product Declaration Verification | Qualifies laminators for EU Green Deal tenders requiring whole-life carbon assessments. |
| Hybrid Mass Timber System Development | Integrates glulam frames with CLT floor plates for accelerated erection in mid-rise commercial construction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with structural engineers, architects, glulam fabricators, and procurement officers at general contractors with secondary validation. Secondary sources included Eurocode 5 technical documentation, EPA TSCA Title VI certification registries, EOTA approval databases, and national building code amendment records. Bottom-up volume modeling across product configurations, wood species, and application channels triangulated against top-down construction spending forecasts.
Comparable historical reference periods anchored the projection horizon to observed adoption curves for mass timber building code amendments and embodied carbon disclosure mandate implementation. Segmentation dimensions modeled included beam geometry tier, wood species, application channel, and end-user specification influence. CAGRs derived from elasticity-adjusted demand curves incorporating lamstock supply constraints and adhesive cost volatility. Forecast inputs incorporated EU Green Deal procurement threshold evolution and US federal mass timber procurement guidelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated beetle infestation expansion in Alpine spruce forests or abrupt petrochemical price spikes affecting phenol resorcinol formaldehyde chemistry. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Sandwich Plate System Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Timber Frame Construction Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
H Beam Market
Structural Construction
Bridge Bearings Market
Structural Construction
Steel Beam Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market