
 Prefabricated Steel Bridge Market | 2026-2036
Prefabricated Steel Bridge Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Steel Bridge Market Insights
Weathering steel is consolidating share against conventional painted carbon grades in highway bridge applications, cutting lifecycle maintenance costs by eliminating repainting cycles. High Steel Structures leverages captive fabrication capacity in Pennsylvania to anchor supply for northeastern state DOT contracts. Acrow Bridge competes through standardized modular panel systems that compress field assembly to days rather than months. China Railway Group dominates domestic procurement through integrated design-build capabilities spanning structural steel and alloy grades.
Prefabricated steel bridge denotes structural spans fabricated off-site to precise dimensional tolerances, then transported and erected using high-strength bolted or welded connections, typically employing ASTM A709 Grade 50W or equivalent weathering compositions with yield strengths exceeding 345 MPa. These systems serve to minimize traffic disruption, accelerate construction schedules, and ensure quality control under factory conditions. Modular beam configurations currently occupy the largest product share due to versatility across span lengths and load ratings, while arch bridge demand accelerates in environmentally sensitive crossings where minimal pier intrusion matters. Highway applications generate the dominant revenue pool, though temporary structures for emergency response and military mobilization represent a fast-growing niche with premium pricing.
FHWA bridge design standards, EN 1090 execution class certifications, and AASHTO LRFD specifications collectively govern material selection, fatigue performance, and load-rating methodologies across North American and European procurement channels. EPA stormwater provisions and EU Green Deal embodied-carbon thresholds are pushing fabricators toward electric-arc furnace steel and recycled content documentation. Stakeholders must monitor evolving Buy America domestic content thresholds and emerging carbon-border adjustment mechanisms that threaten to reroute competitive advantage toward low-emission steel producers.
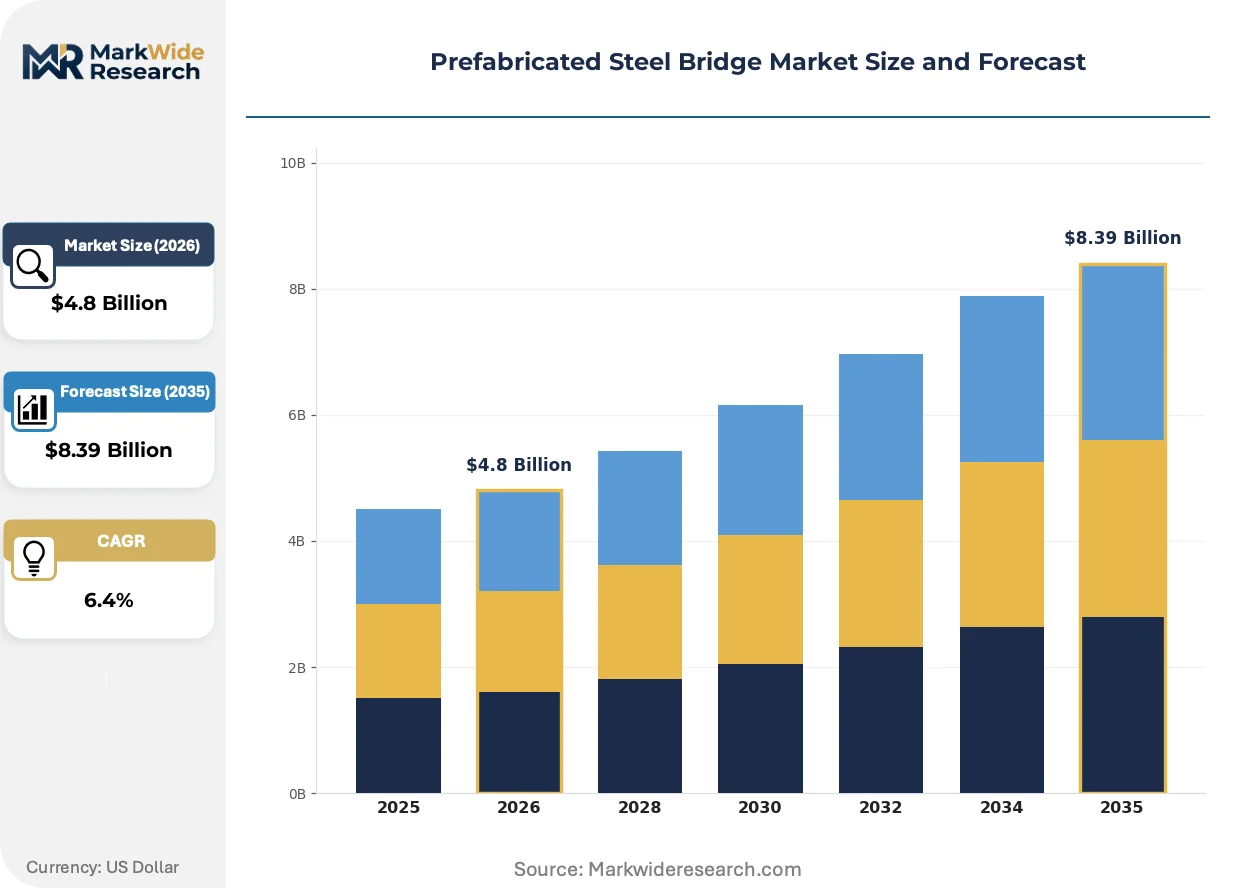
Market Dynamics
State DOTs and federal infrastructure programs are compressing project delivery timelines, forcing a structural shift toward off-site fabrication and rapid field assembly methods that minimize traffic disruption.
Growth Catalysts
- ASTM A709 Weathering Steel Specifications:Highway agencies specify corrosion-resistant grades that eliminate repainting cycles, extending bridge service life and cutting lifecycle maintenance budgets.
- Modular Panel Systems:Standardized beam configurations allow fabricators to pre-assemble complete superstructures in controlled factory conditions, reducing field welding and inspection delays.
- India:The National Highway Authority accelerates rural connectivity programs, creating sustained procurement pipelines for steel truss and girder systems across secondary road networks.
Market Restraints
- Scrap Steel Price Volatility:Electric-arc furnace feedstock costs fluctuate with commodity cycles, squeezing fabrication margins and complicating long-term contract pricing.
- Buy America Content Thresholds:FHWA domestic sourcing requirements restrict access to lower-cost imported plate and structural sections, elevating material acquisition costs for US-based projects.
- Geographic Supply Concentration:Heavy fabrication capacity clusters in Pennsylvania, Texas, and Jiangsu Province, creating regional bottlenecks during concurrent infrastructure award cycles.
Strategic Opportunities
- EU Green Deal Embodied-Carbon Thresholds:Carbon-border adjustment mechanisms favor low-emission steel producers, rewarding fabricators with documented recycled content and electric-arc furnace supply chains.
- Emergency Response Applications:Military and disaster-relief agencies require rapid-deployment modular systems for temporary river crossings, commanding premium pricing outside standard DOT procurement channels.
- China Railway Group Design-Build Integration:Vertically integrated project delivery models compress design-fabrication-erection handoffs, offering template for international expansion.
Industry Challenges
- Welder Certification Bottlenecks:AWS D1.5 bridge welding qualifications require specialized training programs that lag current demand, constraining fabrication throughput at peak construction seasons.
- EN 1090 Execution Class Compliance:European fabricators face extended factory production control audits and third-party inspections that delay order-to-delivery cycles by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Steel Bridge Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Bridges, Arch Bridges, Beam Bridges, Truss Bridges End User: Government Agencies, Construction Companies, Transportation Departments, Private Developers Application: Highway, Rail, Pedestrian, Temporary Structures Material Grade: Structural Steel, Alloy Steel, Weathering Steel, Others |
| Companies Covered | Acrow Bridge, Contech Engineered Solutions, High Steel Structures, Mabey Inc., TrueNorth Steel, Veritas Steel, U.S. Bridge, China Railway Group, American Bridge Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Steel Bridge Market Trends and Innovations
Digital fabrication workflows and sustainability mandates are converging to reshape how steel bridge components are engineered, sourced, and assembled across transportation corridors.
Building Information Modeling is decentralizing design authority from centralized engineering firms to fabrication shops equipped with CNC plasma cutting and robotic welding cells. Regional fabricators in the United States and Germany now generate shop drawings directly from parametric models, compressing the traditional engineer-of-record review cycle. This capability shift is enabling smaller shops to compete for complex curved-girder contracts previously reserved for national-scale contractors.
The EU Green Deal's embodied-carbon disclosure requirements are forcing specification changes across European procurement channels. Project owners now mandate Environmental Product Declarations for structural steel, favoring suppliers with electric-arc furnace production and verified scrap content. Fabricators in Germany and France are responding by securing long-term supply agreements with domestic green steel producers and investing in in-house carbon accounting systems.
Asset owners are unbundling design, fabrication, and erection contracts that were historically awarded as single-source design-build packages. State DOTs in the United States and provincial transport agencies in Canada now separate superstructure supply from installation, enabling competitive bidding among specialized fabricators and regional erection contractors. This disaggregation is most visible in the northeastern United States, where Pennsylvania and New York have adopted component-based procurement for routine span replacements.
Prefabricated Steel Bridge Market Segmentation
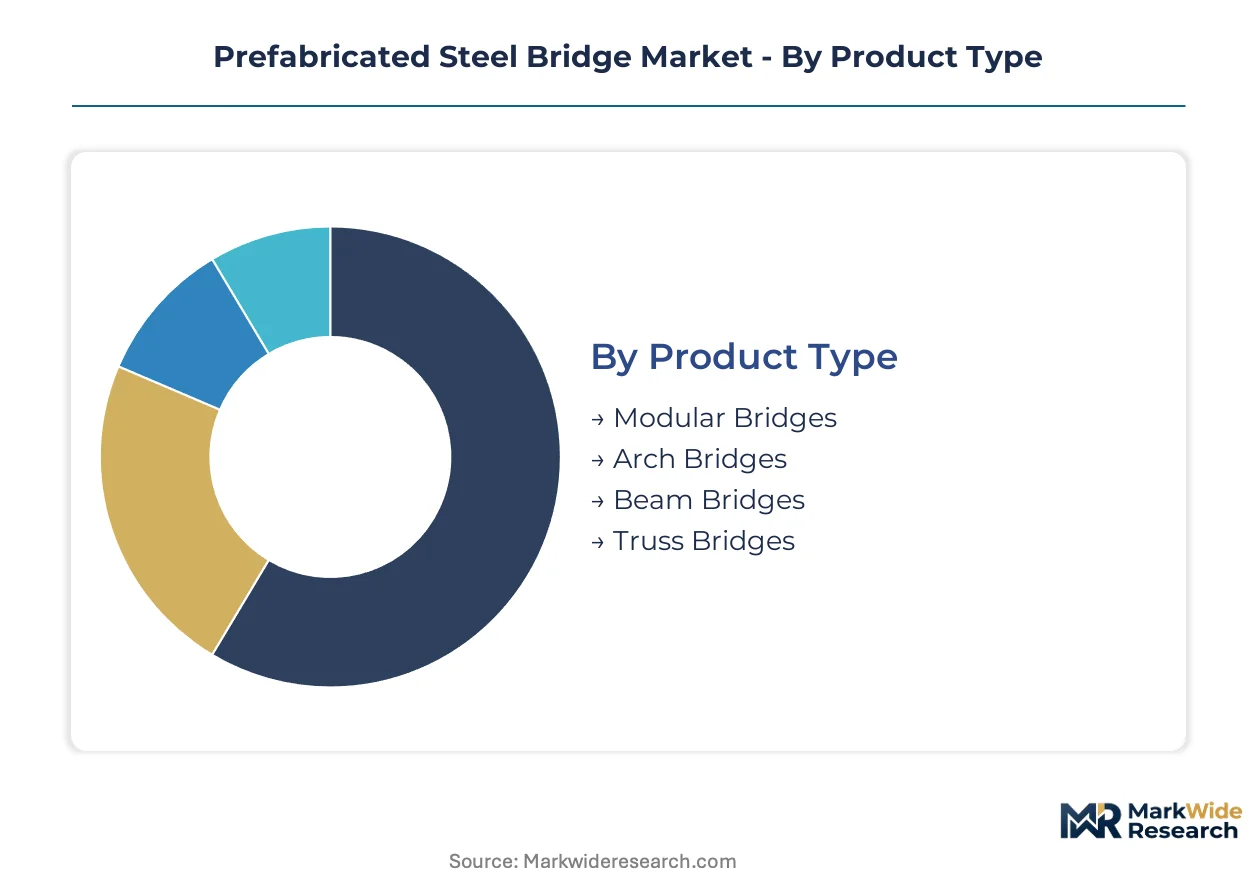
Structural configuration, procurement authority, and material specification each shape vendor selection and project economics in prefabricated steel bridge deployment. Buyers balance span requirements against lifecycle cost models and regulatory compliance thresholds.
Product Type:
Span length and site constraints determine which structural system delivers optimal total installed cost.
- Modular Bridges:Standardized panel systems fabricated to ASTM A709 specifications enable rapid field assembly with minimal specialized equipment. State DOTs in the United States and provincial agencies in Canada specify these systems for emergency replacements and routine span renewals where traffic closure windows are compressed.
- Arch Bridges:Curved compression members fabricated from weathering steel grades eliminate intermediate piers in environmentally sensitive crossings. Demand concentrates in European river corridors and protected watersheds in Germany and France where regulatory authorities restrict in-water construction.
- Beam Bridges:Simple girder configurations dominate procurement volume across rural connectivity programs.
- Truss Bridges:Triangulated frameworks serve longer spans and heavier load ratings in industrial corridor applications.
Modular bridges lead on scale; arch bridges lead on momentum.
End User:
Procurement authority and risk allocation models separate public-sector buyers from private developers.
- Government Agencies:Federal and state transportation departments specify weathering steel grades and enforce domestic content requirements through FHWA Buy America provisions. Contract awards follow design-bid-build protocols with extended qualification periods.
- Construction Companies:General contractors and bridge specialists purchase fabricated superstructures for design-build and public-private partnership delivery models. These buyers prioritize supplier flexibility on delivery schedules and field technical support.
- Transportation Departments:State and provincial DOTs maintain qualified vendor lists and recurring maintenance programs.
- Private Developers:Industrial facility owners and toll-road operators source custom configurations outside standard procurement channels.
Government agencies anchor procurement volume; construction companies are expanding most quickly.
Application:
Load rating and service duration requirements segment buyers by performance specification.
- Highway:Heavy-vehicle loadings per AASHTO LRFD specifications govern material selection and fatigue design for interstate and arterial corridors. State DOTs in the United States account for the dominant revenue concentration in this category.
- Temporary Structures:Military engineering units and disaster response agencies require rapid-deployment systems with premium pricing outside standard procurement cycles. Modular panel inventories stockpiled by defense ministries in NATO member states drive demand.
- Rail:Freight and passenger loadings impose stringent deflection limits and dynamic amplification factors.
- Pedestrian:Lighter load ratings enable slender profiles and architectural finishes in urban park systems.
Highway applications dominate revenue; temporary structures command the steepest expansion trajectory.
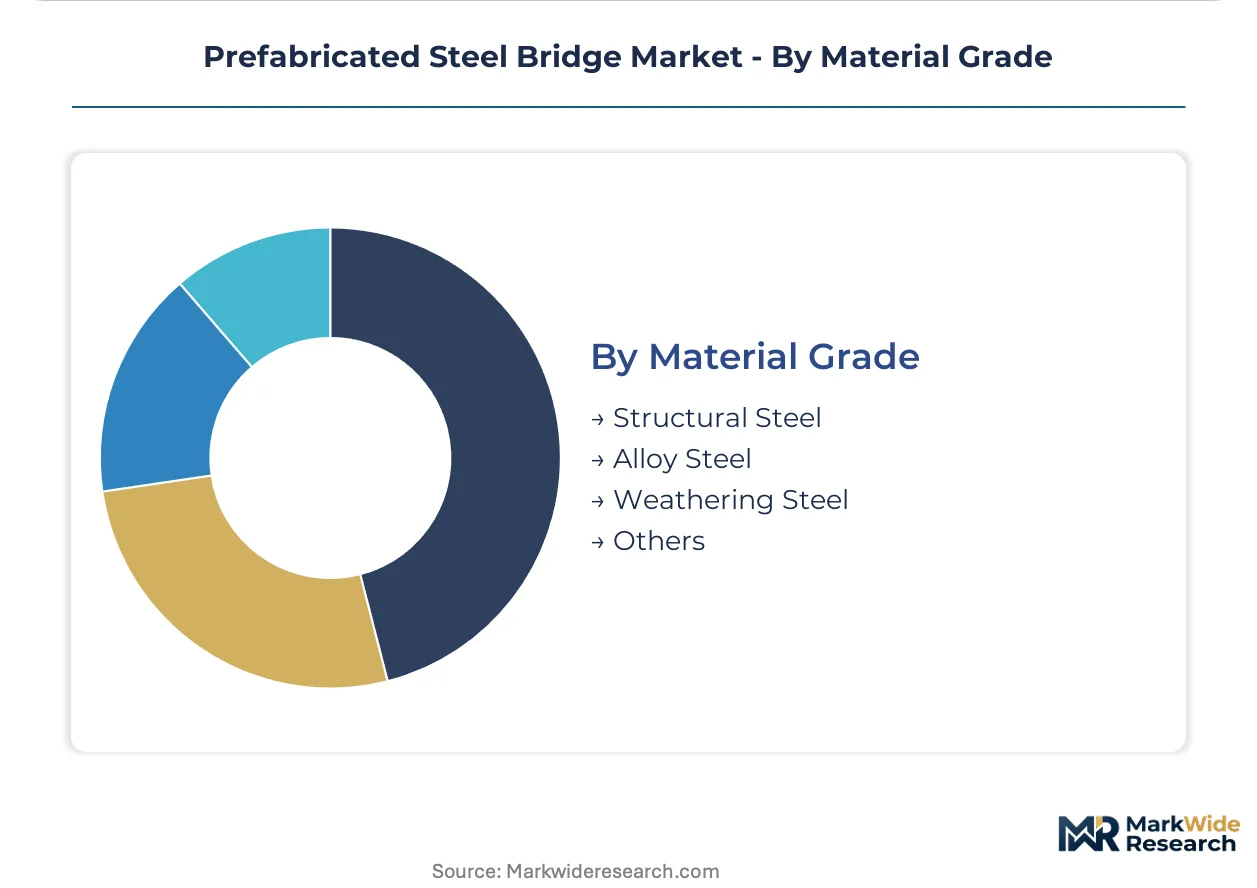
Material Grade:
Corrosion resistance and strength-to-weight ratios differentiate specification choices across climate zones.
- Weathering Steel:ASTM A709 Grade 50W and equivalent European grades form protective oxide patinas that eliminate repainting cycles. FHWA specifications now favor these compositions for new construction in the United States, cutting lifecycle maintenance budgets.
- Structural Steel:Conventional carbon grades remain specified for temporary installations and protected interior environments where atmospheric exposure is limited.
- Alloy Steel:High-strength low-alloy compositions serve specialized long-span applications requiring enhanced toughness.
- Others:Stainless and galvanized grades address aggressive marine or chemical exposure conditions.
Weathering steel leads on specification momentum; structural steel retains volume in temporary applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pennsylvania's steel fabrication corridor anchors the industry's geographic footprint, with concentrated heavy manufacturing capacity serving northeastern state DOT contracts and compressing delivery timelines for modular bridge systems.
United States
FHWA bridge design standards and Buy America domestic content requirements shape procurement for state transportation departments. The Bipartisan Infrastructure Law channels federal funding toward rural connectivity programs, accelerating superstructure replacements. Fabrication clusters in Pennsylvania and Texas supply weathering steel spans to DOTs facing compressed construction windows.
Germany
EN 1090 execution class certifications govern fabrication quality for European river crossings and environmentally sensitive corridors. The EU Green Deal's embodied-carbon thresholds favor electric-arc furnace steel with documented recycled content. Industrial concentration in the Ruhr region and Baden-Württemberg supports precision fabrication for arch bridge applications.
China
GB standards and dual carbon goals from the Ministry of Ecology and Environment reshape material specifications for domestic infrastructure. The National Highway Authority accelerates rural network expansion, creating procurement pipelines for truss and girder systems. Integrated design-build capabilities in Jiangsu Province compress project delivery timelines.
India
The National Highway Authority of India drives rural connectivity programs across secondary road networks, sustaining demand for standardized beam configurations. BIS certification requirements and PLI scheme incentives elevate domestic fabrication capacity. Industrial clusters in Gujarat and Maharashtra supply modular steel spans for state highway departments.
France
EU Green Deal carbon-border adjustment mechanisms favor low-emission steel producers with verified Environmental Product Declarations. Protected watershed regulations restrict in-water construction, elevating arch bridge specifications for river crossings. Fabrication capacity in Auvergne-Rhône-Alpes serves infrastructure renewal programs.
Prefabricated Steel Bridge Market Competitive Landscape
Global majors compete with regional champions across fabrication capacity and DOT qualification status, creating a tiered structure where scale advantages clash with local regulatory relationships. The vendor base separates into three strategic archetypes: vertically integrated design-build operators, specialized modular panel fabricators, and regional heavy steel shops serving qualified vendor lists. Dominant competitive moves include securing long-term supply agreements with electric-arc furnace steel producers and expanding captive welding certification programs to relieve throughput constraints.
Among Pennsylvania-based fabricators, High Steel Structures anchors the northeastern supply position through captive production capacity. Acrow Bridge occupies the standardized modular systems tier with rapid-assembly panel configurations. China Railway Group exemplifies the vertically integrated archetype, spanning structural design through alloy-grade fabrication within domestic procurement channels.
| Leading Market Players |
|---|
| Acrow Bridge |
| Contech Engineered Solutions |
| High Steel Structures |
| Mabey Inc. |
| TrueNorth Steel |
| Veritas Steel |
| U.S. Bridge |
| China Railway Group |
| American Bridge Company |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied-carbon disclosure requirements now gate qualified supply access and premium-tier pricing for fabricators serving European infrastructure procurement. Buyers without verified Environmental Product Declarations face exclusion from public tenders, while certified producers command material premiums across German and French bridge awards.
Pricing Analysis
Scrap steel feedstock costs pass through directly to fabrication quotes, compressing margins when commodity cycles spike. Three-tier pricing structure across premium, standard, and economy levels separates EN 1090-certified fabricators from uncertified competitors and spot-market suppliers. Pricing pressure stems from Buy America domestic content thresholds that elevate US plate acquisition costs above imported alternatives. State DOTs exhibit highest price sensitivity on routine span replacements, while military emergency-response buyers accept steep premiums for rapid-deployment inventory.
Supply Chain Analysis
Welder certification bottlenecks in Pennsylvania, Texas, and Jiangsu Province constrain throughput at peak construction seasons. Heavy fabrication capacity draws from electric-arc furnace steel mills in the United States and blast furnace producers in China. Supply chain risk centers on geographic concentration during concurrent infrastructure award cycles. Distribution runs through qualified vendor lists maintained by state transportation departments and direct design-build contracts with integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU carbon-border adjustment mechanisms widen cost spreads between European electric-arc furnace steel and conventional Asian blast furnace supply.
For Market Incumbents: Anticipate margin compression from emerging low-emission steel producers securing long-term supply agreements with state DOTs. Defensive positioning requires captive welding certification programs to relieve throughput constraints and backward integration into electric-arc furnace steel supply to satisfy EU Green Deal thresholds. For New Entrants and Emerging Players: Capture white-space in emergency-response modular systems where NATO defense ministries stockpile rapid-deployment inventory outside standard procurement channels. Target temporary structure applications with premium pricing and accelerated qualification pathways through military engineering unit relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional heavy fabrication shops with DOT qualification status but limited carbon-accounting capabilities. Long-term viability hinges on EN 1090 execution class compliance and documented green steel supply chains. Watch for carbon-border adjustment implementation timing as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Green Steel Supply Agreement | Secures electric-arc furnace capacity with verified recycled content for EU procurement compliance. |
| Welding Certification Expansion | Relieves AWS D1.5 qualification bottlenecks constraining Pennsylvania and Texas fabrication throughput. |
| Modular Panel Standardization | Compresses field assembly timelines for state DOT emergency replacement contracts. |
| Carbon Accounting System Investment | Enables Environmental Product Declaration generation for European infrastructure tenders. |
| Design-Build Integration | Compresses handoffs between engineering, fabrication, and erection phases in China Railway Group model. |
Research Methodology
Direct dialogue with bridge fabrication executives, state DOT procurement officers, AWS-certified welding instructors, and EN 1090 audit bodies grounded qualitative findings in operational reality. Secondary validation drew from FHWA bridge inventory databases, AASHTO LRFD specification updates, EU EPD registration systems, and customs trade data on structural steel imports. Bottom-up project pipeline analysis triangulated against top-down infrastructure budget allocations.
Segment-level outputs across product configuration, material grade, and procurement authority dimensions were modeled over the projection horizon. CAGRs were derived from historical award cycle analysis and elasticity-adjusted infrastructure spending trajectories. Forecast inputs incorporated weathering steel specification adoption curves, Buy America threshold evolution, and electric-arc furnace capacity expansion timelines.
Commodity price volatility, regulatory delay in carbon-border implementation, and welder certification program expansion rates are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions on infrastructure funding continuity and specification standardization momentum. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Girder Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Sandwich Plate System Market
Structural Construction
South Korea Construction Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
H Beam Market