
 Robotic Mill Liner Market | 2026-2036
Robotic Mill Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Mill Liner Market Analytics
Multi-source procurement for robotic mill liner systems is recalibrating how mining operators balance capital deployment against operational risk. Metso Outotec Corporation leverages its integrated mill services portfolio to anchor long-term service contracts across Scandinavian and Latin American mining corridors. Bradken sustains foundry-to-field manufacturing scale in Australia, while RME Russell Mineral Equipment dominates specialized relining machine design for SAG mill applications.
Robotic mill liners are engineered wear-resistant inserts installed inside grinding mills to protect shell structures from abrasive ore impact, typically fabricated from high-chrome white iron, rubber composites, or magnetic alloys bonded to steel backing plates. Their primary purpose is to extend mill availability while enabling automated replacement cycles that eliminate confined-space entry by maintenance crews. Steel liners retain the largest installed base across hard-rock mining, though composite liners are capturing faster growth in applications demanding reduced liner mass and lower noise emission. The technology dimension splits between remote control systems, which currently occupy the majority of active fleets, and AI-driven solutions that are attracting R&D investment for predictive wear monitoring.
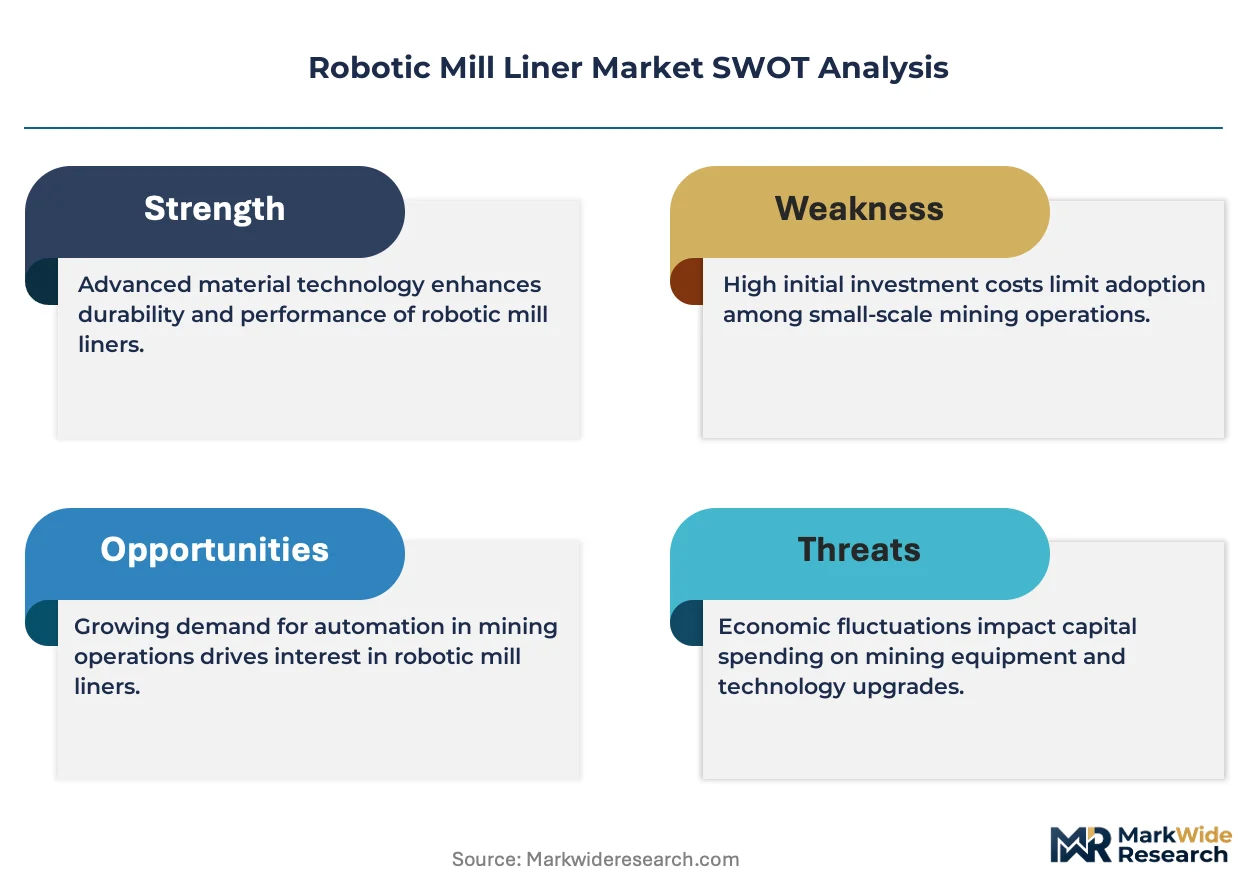
The US Mine Safety and Health Administration (MSHA) and Australia's Work Health and Safety Act impose strict protocols on confined-space entry and manual liner handling, directly elevating robotic alternatives in compliance planning. ISO 10218 industrial robot safety standards and IEC 61508 functional safety frameworks further shape equipment certification requirements for autonomous mill relining platforms. Stakeholders must weigh capital intensity against total cost of ownership models as automation tiers proliferate from teleoperated to fully autonomous systems.
Market Dynamics
Mining operators in Chile and Australia are accelerating capital reallocation toward autonomous relining platforms as confined-space fatality incidents trigger stricter enforcement of MSHA and Work Health and Safety Act protocols, compressing the viable window for manual liner replacement.
Growth Catalysts
- MSHA Confined-Space Mandates:The US regulator's enhanced penalties for manual entry violations are forcing copper and gold producers toward certified robotic platforms.
- Copper Concentrator Expansion:Chilean state-owned and private mining corridors are commissioning larger SAG mills with shorter relining cycles, creating sustained equipment demand.
- Predictive Wear Monitoring:AI-driven sensor arrays embedded in liner substrates are enabling condition-based replacement scheduling, reducing unplanned downtime.
Market Restraints
- High-Chrome White Iron Supply Concentration:Foundry capacity for abrasion-resistant alloys clusters in select Chinese and Indian manufacturing zones, exposing buyers to input volatility.
- IEC 61508 Certification Timelines:Functional safety validation for autonomous mill relining systems extends equipment qualification periods by 18-24 months.
- Manual Relining Labor Arbitrage:Contract maintenance crews in select Latin American jurisdictions retain cost advantages that delay robotic conversion at marginal operations.
Strategic Opportunities
- Peruvian Mining Corridors:Untapped concentrator capacity in the Andean copper belt offers first-mover positioning for integrated robotic service providers.
- Rubber-Steel Composite Convergence:Hybrid liner architectures combining elastomer dampening with metallic wear surfaces are opening applications in noise-sensitive underground installations.
- EU CSRD Reporting Requirements:Sustainability disclosure mandates are elevating robotic relining as a documented worker safety and emissions reduction measure.
Industry Challenges
- Mill-Specific Integration Engineering:Each SAG and ball mill configuration demands customized robotic end-effector design, fragmenting deployment economics.
- Autonomous Maintenance Technician Scarcity:Mining regions lack personnel trained in ISO 10218-compliant robot diagnostics and confined-space teleoperation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Mill Liner Market |
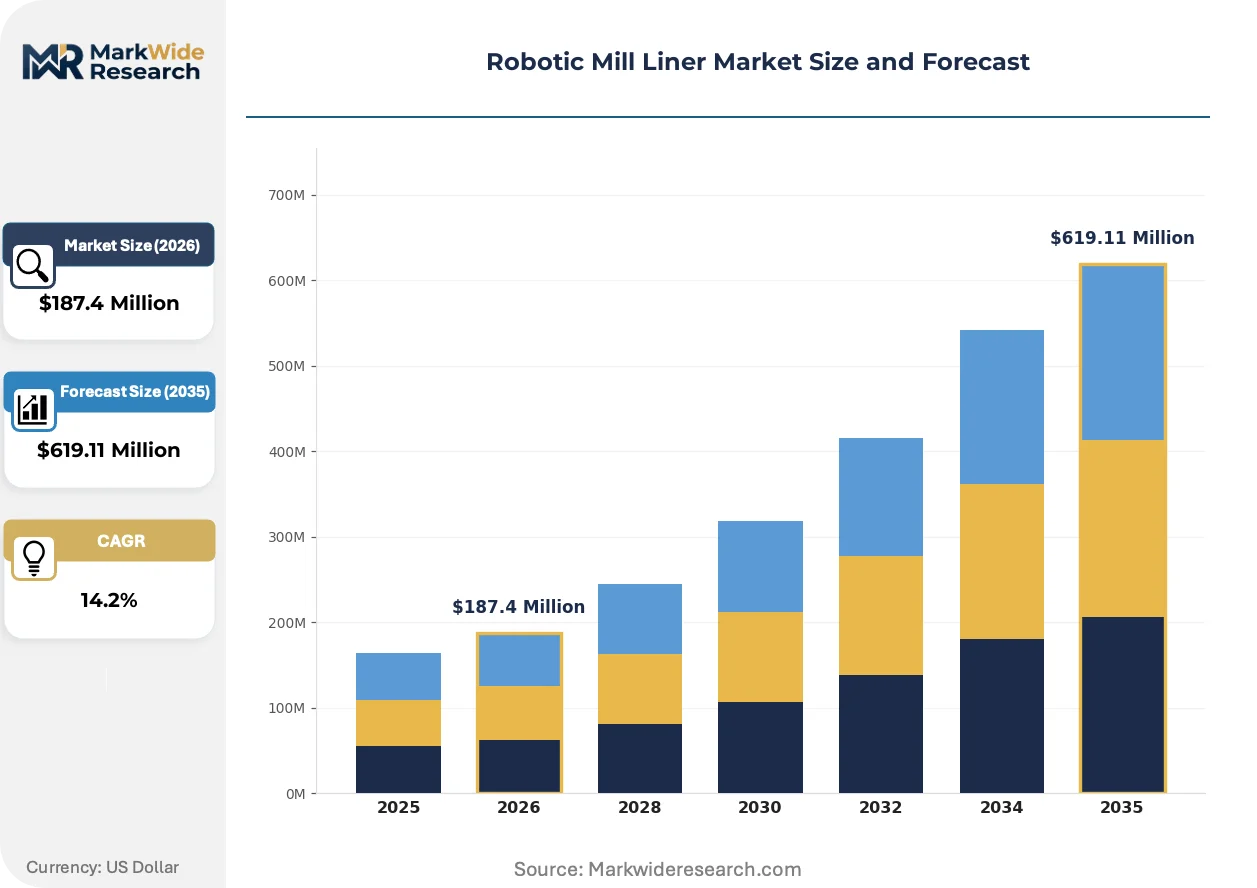
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Liners, Rubber Liners, Composite Liners, Magnetic Liners End User: Mining Industry, Cement Industry, Energy Sector, Construction Industry Installation Type: On-site Installation, Off-site Installation, Retrofits, Upgrades Technology: Automated Systems, Remote Control Systems, AI-Driven Solutions, Robotics |
| Companies Covered | Metso Outotec Corporation, Bradken, RME Russell Mineral Equipment, KUKA Robotics, ABB, EUROBOTS, FLSmidth, PaR Systems, RELINE UV ASEAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Mill Liner Market Evolving Landscape
Equipment manufacturers are embedding intelligence deeper into liner substrates and relining machinery, shifting competitive advantage from hardware durability toward data-driven availability guarantees and predictive service models.
Magnetic liner retention systems are absorbing installation cycle compression demands from high-throughput copper operations. Anglo American and Codelco installations in Chile are piloting these substrates for 30% faster changeout sequences. The technology is absorbing capital that previously flowed toward thicker conventional steel designs, forcing foundries to retool for composite fabrication.
Australia's Work Health and Safety Act amendments now mandate documented risk elimination hierarchies before any confined-space entry authorization. Mining contractors are responding by specifying ISO 10218-certified robotic platforms in tender documents. Western Australian iron ore concentrators are the most advanced in compliance-driven fleet conversion.
Service unbundling is fragmenting traditional mill maintenance contracts. Equipment owners are separating liner supply from installation services, creating openings for specialized robotic relining contractors. This pattern is most pronounced in Chilean copper operations, where concentrator maintenance budgets now distinguish between wear parts procurement and automated replacement execution.
Robotic Mill Liner Market Segmentation
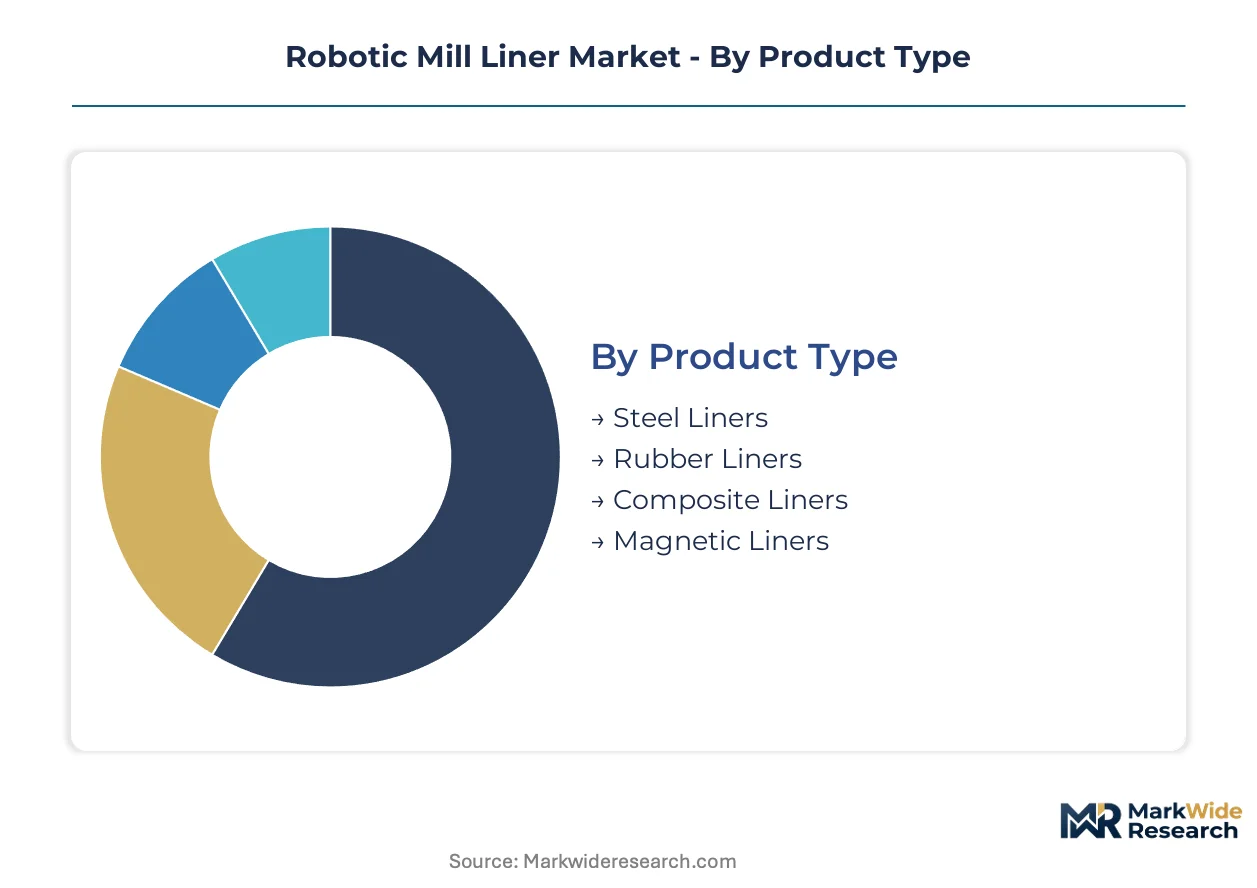
Segmentation in the robotic mill liner market reveals how capital deployment, operational risk, and regulatory compliance intersect across distinct equipment categories. Mining operators select liner materials and installation modalities based on ore abrasiveness, mill throughput requirements, and the regulatory environment governing confined-space work.
Product Type:
Capital intensity varies sharply across liner substrates, with metallurgical complexity and foundry tooling requirements driving upfront investment thresholds.
- Steel Liners:Fabricated from high-chrome white iron or manganese steel bonded to structural backing plates, these liners withstand extreme impact in SAG mill applications processing hard copper and gold ores. Chilean concentrator operators specify steel for primary grinding circuits where abrasion resistance outweighs mass considerations. Steel liners absorb the bulk of installed capacity across hard-rock mining corridors.
- Composite Liners:Hybrid elastomer-metallic architectures combine rubber dampening layers with hardened wear surfaces, reducing noise emission and liner mass for underground installations. Australian iron ore operators are specifying composite designs where Work Health and Safety Act noise thresholds constrain conventional steel deployment. Composite configurations are expanding most quickly in noise-sensitive applications.
- Rubber Liners:Molded elastomer inserts deliver impact absorption in secondary grinding and regrind circuits with moderate ore hardness.
- Magnetic Liners:Magnetic retention systems enable rapid changeout sequences without mechanical fastening, piloted by Codelco and Anglo American for 30% cycle compression.
Steel liners dominate capital deployment in greenfield concentrators; magnetic and composite variants are capturing retrofit budgets seeking operational flexibility.
End User:
Application concentration determines replacement frequency and robotic system specification, with ore throughput volume directly correlating to relining automation economics.
- Mining Industry:Copper, gold, and iron ore concentrators generate the preponderance of robotic mill liner demand, with SAG and ball mill relining cycles occurring every 6-18 months depending on ore abrasiveness. Chilean state-owned and private mining corridors commission the largest automated relining fleets. Mining applications command the steepest expansion trajectory for autonomous installation platforms.
- Cement Industry:Clinker grinding mills operate at lower impact intensity than mining applications, extending liner service intervals and compressing the automation payback window. European cement producers under EU CSRD reporting mandates are documenting robotic relining as worker safety and emissions reduction measures. Cement represents a secondary demand tier with concentrated procurement in Mediterranean production clusters.
- Energy Sector:Coal pulverizers and biomass grinding equipment require specialized liner geometries for fuel preparation circuits.
- Construction Industry:Aggregate processing mills for concrete and asphalt feedstock employ smaller-diameter equipment with limited robotic installation penetration.
Mining concentrates the majority of active robotic fleets; cement and energy applications are advancing compliance-driven adoption in regulated jurisdictions.
Installation Type:
Project modality shapes equipment procurement patterns, with greenfield concentrators embedding automation from commissioning while existing operations phase conversion through staged retrofits.
- On-site Installation:New mill construction and major concentrator expansions specify integrated robotic relining infrastructure during commissioning, locking in automation architecture from operational inception. Chilean copper belt greenfields are standardizing on-site robotic installation as a design requirement. On-site deployment captures the largest share of capital allocation in expansionary mining corridors.
- Retrofits:Existing manual relining operations convert to robotic platforms through staged equipment integration, requiring mill-specific end-effector engineering and confined-space infrastructure modification. Western Australian iron ore concentrators lead retrofit intensity following Work Health and Safety Act enforcement tightening. Retrofit activity is accelerating fastest in mature mining jurisdictions with aging manual fleets.
- Off-site Installation:Pre-fabricated liner modules assembled in controlled workshop environments reduce field exposure hours for specialized composite configurations.
- Upgrades:Incremental capability enhancements to existing robotic platforms extend functional safety certification and sensor integration.
On-site installation dominates new concentrator capital; retrofit and upgrade cycles are expanding as regulatory deadlines compress manual operation windows.
Technology:
Automation tier selection involves trade-offs between operational autonomy and certification complexity, with functional safety validation timelines extending equipment qualification for advanced systems.
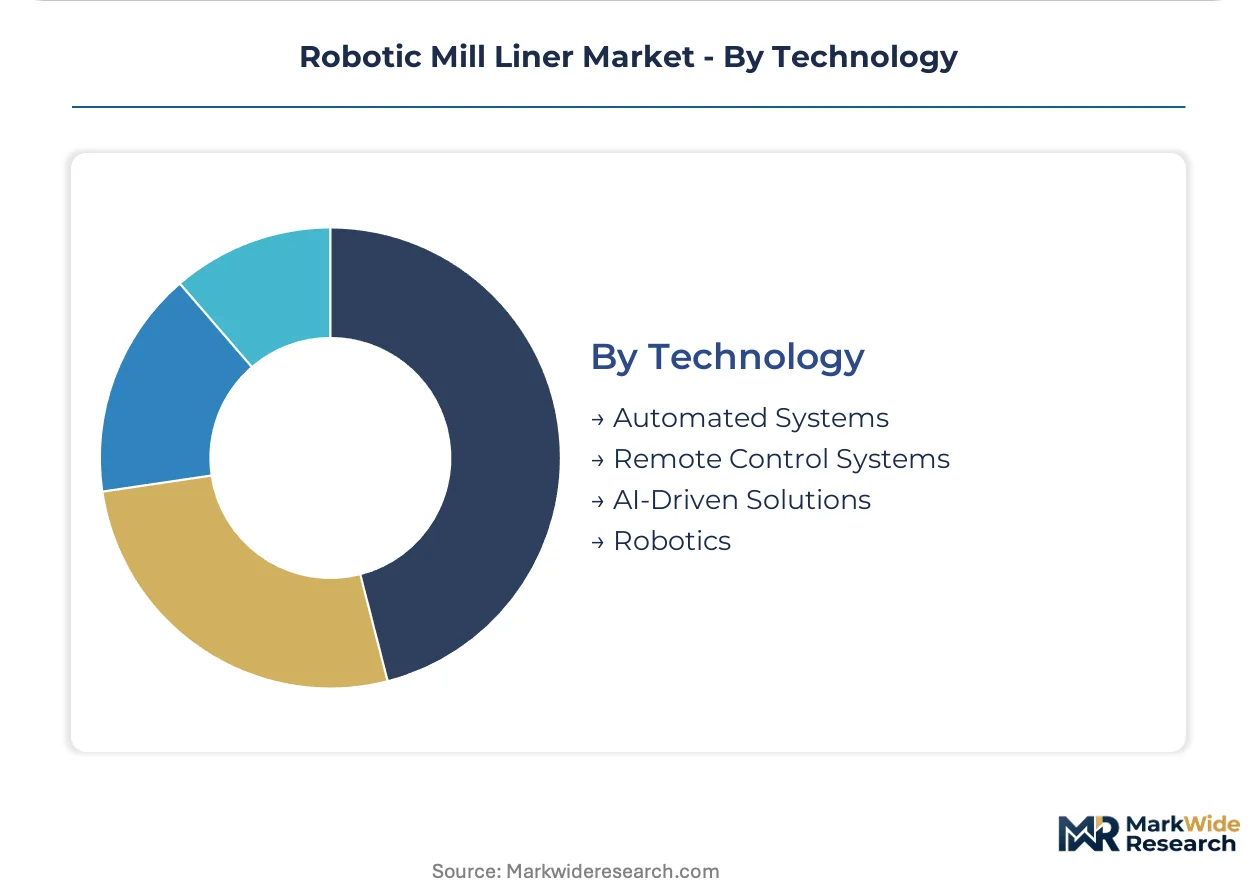
- Remote Control Systems:Teleoperated relining platforms with operator visualization and joystick manipulation currently constitute the majority of active fleets, balancing capital efficiency against confined-space risk reduction. MSHA-compliant remote systems are specified in US copper operations facing enhanced manual entry penalties. Remote control platforms retain the broadest installed base across mining geographies.
- AI-Driven Solutions:Sensor-embedded liners with predictive wear algorithms enable condition-based replacement scheduling, reducing unplanned downtime through substrate-integrated intelligence. Australian and Canadian operations are piloting AI platforms for ISO 10218-compliant autonomous sequences. AI-driven architectures are climbing the fastest in technology-forward mining jurisdictions.
- Automated Systems:Pre-programmed robotic sequences execute standardized liner changeout routines without continuous operator intervention.
- Robotics:Fully autonomous platforms with machine vision and adaptive end-effector control represent the frontier of mill relining automation.
Remote control systems anchor current fleet composition; AI-driven and fully autonomous platforms are absorbing disproportionate R&D investment for predictive service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean copper concentrate anchors regional demand patterns across the robotic mill liner market. Australian iron ore corridors and Canadian gold mining jurisdictions follow as secondary concentration zones.
Chile
State-owned Codelco and private copper concentrators commission the largest automated relining fleets. Chilean mining regulators enforce strict confined-space protocols under national occupational safety frameworks. The Antofagasta and Atacama mining corridors standardize robotic installation as a design requirement for new SAG mill capacity.
Australia
Western Australian iron ore operators lead retrofit intensity following Work Health and Safety Act enforcement tightening. Australia's national workplace safety regulator mandates documented risk elimination hierarchies before any confined-space entry authorization. The Pilbara concentrator cluster converts aging manual fleets to ISO 10218-certified robotic platforms.
Canada
Ontario and Quebec gold mining operations accelerate capital reallocation toward autonomous relining platforms. Provincial occupational health and safety boards impose strict protocols on manual liner handling in underground installations. The Abitibi gold belt pilots AI-driven sensor arrays for predictive wear monitoring.
United States
Copper and gold producers in Arizona and Nevada face enhanced MSHA penalties for manual entry violations. The US Mine Safety and Health Administration drives specification of certified robotic platforms in tender documents. Southwestern concentrator operations compress the viable window for manual liner replacement.
Peru
Untapped concentrator capacity in the Andean copper belt attracts first-mover positioning from integrated robotic service providers. Peru's national mining regulator aligns confined-space standards with international practice. The Arequipa and Ancash mining corridors expand adoption of automated liner replacement systems.
Robotic Mill Liner Market Competitive Landscape
Global majors compete with regional champions across mill services integration and specialized relining machine design. The vendor base splits between diversified mining equipment conglomerates and focused automation specialists. Three archetypes dominate: integrated mill services providers, foundry-to-field fabricators, and robotic system specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators seek to anchor long-term service contracts.
Within the integrated services tier, Metso Outotec Corporation and FLSmidth exemplify diversified mining equipment conglomerates that span liner supply through installation execution. Bradken represents the foundry-to-field archetype with Australian manufacturing scale. RME Russell Mineral Equipment occupies the specialist position in dedicated relining machine design for SAG mill applications.
| Leading Market Players |
|---|
| Metso Outotec Corporation |
| Bradken |
| RME Russell Mineral Equipment |
| KUKA Robotics |
| ABB |
| EUROBOTS |
| FLSmidth |
| PaR Systems |
| RELINE UV ASEAN |
| Others |
Value Network & Pricing Analysis
Family-owned foundry operators in India and China anchor the upstream tier, their fragmented ownership structures limiting pricing discipline despite concentrated high-chrome white iron capacity. This ownership pattern feeds into buyer leverage at mining concentrators, where procurement teams unbundle liner supply from installation services to compress vendor margins.
Pricing Analysis
Warranty and service bundling now separates premium-tier vendors from stripped-down commodity suppliers. Project-based contracting dominates, with ISO 10218 certification tier and geographic delivery cost driving price differentiation. Pricing pressure stems from contract maintenance crews in select Latin American jurisdictions retaining manual relining cost advantages. Tier 2 mining operators exhibit highest price sensitivity; tier 1 copper concentrators prioritize safety compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for worn liner refurbishment remain underdeveloped, fragmenting secondary material recovery. Foundry capacity clusters in China, India, and Australia, drawing from manganese ore, chromium, and rubber composite feedstocks. Single-source vulnerability concentrates in high-chrome white iron alloying elements. Distribution runs through mill services integrators and specialized robotic contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable vendors as IEC 61508 certification timelines and capital intensity force marginal automation providers toward exit.
For Market Incumbents: Anchor long-term service contracts through predictive wear monitoring integration, defending against specialized robotic relining contractors unbundling installation from liner supply. Backward integration into magnetic liner substrate fabrication secures differentiation as composite architectures displace conventional steel. For New Entrants and Emerging Players: Australia's Work Health and Safety Act amendments open a window for ISO 10218-certified platform providers targeting Western Australian iron ore retrofit cycles. Peruvian Andean copper belt concentrators offer white-space penetration with lower incumbent saturation. Lead with service-unbundled robotic installation contracts to bypass foundry capital barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian foundry-to-field fabricators with captive mill services relationships as manual relining labor arbitrage compresses. Five-to-ten year viability hinges on AI-driven predictive maintenance capability buildout. Monitor Chilean state-owned mining procurement tender specifications for autonomous platform mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Liner Fabrication | Captures 30% faster changeout premium piloted by Codelco and Anglo American. |
| ISO 10218 Certification Investment | Unlocks Australian Work Health and Safety Act-mandated retrofit contracts. |
| AI-Driven Predictive Wear Platform Development | Enables condition-based replacement scheduling reducing unplanned downtime. |
| Peruvian Mining Corridor Market Entry | Secures first-mover positioning in Andean copper belt concentrator expansion. |
| Service Unbundling Specialization | Captures installation-only contracts as Chilean operators separate procurement from execution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with mill maintenance directors, foundry operations managers, mining procurement leads, and robotic systems engineers. MSHA enforcement bulletins, Australian Work Health and Safety Act amendments, and Chilean mining regulator protocols supplied compliance trajectory inputs. Bottom-up concentrator fleet analysis triangulated against top-down equipment manufacturer revenue segmentation.
Granularity extended to liner material substrate, automation technology tier, installation modality, and end-use concentrator type across the analysis window. CAGRs derived from installed base replacement cycles, greenfield expansion pipelines, and regulatory compliance deadline modeling. Ore abrasiveness indices and relining frequency benchmarks informed segment-specific growth rates.
Caveats apply where IEC 61508 certification timeline extensions or high-chrome white iron supply disruptions could materially shift the outlook. Practitioners should monitor Chilean state-owned mining tender specifications and Australian Work Health and Safety Act enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
India Lathe Machines Market