
 Canada Composite Repair Market | 2026-2036
Canada Composite Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Composite Repair Market Outlook
Carbon fiber is shifting from luxury aerospace applications into mainstream industrial maintenance across Canadian energy and transportation sectors. Hexcel leverages its prepreg technology leadership to supply advanced repair materials for aviation and defense end-users. Citadel Technologies anchors its position through specialized pipeline composite wrap systems serving Alberta's oil sands infrastructure. Milliken Infrastructure competes on manufacturing scale, producing high-strength fiber reinforcements for civil and industrial rehabilitation projects nationwide.
Canada composite repair encompasses the restoration of fiber-reinforced polymer structures using bonded patches, scarf repairs, or overlay systems to restore mechanical integrity to damaged laminates. These repairs typically achieve 80-90% of original tensile strength when executed with vacuum infusion or prepreg techniques under controlled environmental conditions. Structural repair products command premium positioning due to load-bearing certification requirements in aerospace and energy applications. Hand layup technology dominates volume in marine and automotive segments where cost sensitivity outweighs precision demands. Carbon fiber material grades lead value pools given their deployment in flight-critical aerospace restoration and high-pressure pipeline reinforcement.
Transport Canada enforces airworthiness standards through Canadian Aviation Regulations that mandate composite damage assessment protocols for commercial operators. Health Canada and the Canadian Standards Association coordinate material safety certifications affecting resin systems and adhesive formulations used in structural rehabilitation. The Canadian Energy Regulator oversees integrity management requirements for fiber-reinforced pipeline repairs in federally regulated infrastructure. Stakeholders must monitor evolving provincial adoption of CSA S806 standards for fiber-reinforced polymers in building construction, as code harmonization between Ontario, Quebec, and British Columbia will determine contractor qualification requirements and market access conditions.
Market Dynamics
Transport Canada and Health Canada safety mandates are compressing inspection cycles for composite structures across aviation and energy infrastructure, forcing operators to accelerate repair schedules and expand certified contractor networks.
Growth Catalysts
- Aviation fleet aging:Commercial operators across Ontario and Quebec face escalating airframe restoration needs as regional aircraft exceed 20-year service thresholds, triggering structural composite interventions.
- CSA S806 code adoption:Provincial building authorities in British Columbia are incorporating fiber-reinforced polymer standards into seismic retrofit requirements, opening civil infrastructure rehabilitation demand.
- Pipeline integrity mandates:The Canadian Energy Regulator enforces continuous pressure vessel monitoring across Alberta's oil sands corridor, requiring fiberglass and carbon fiber wrap repairs for corrosion management.
Market Restraints
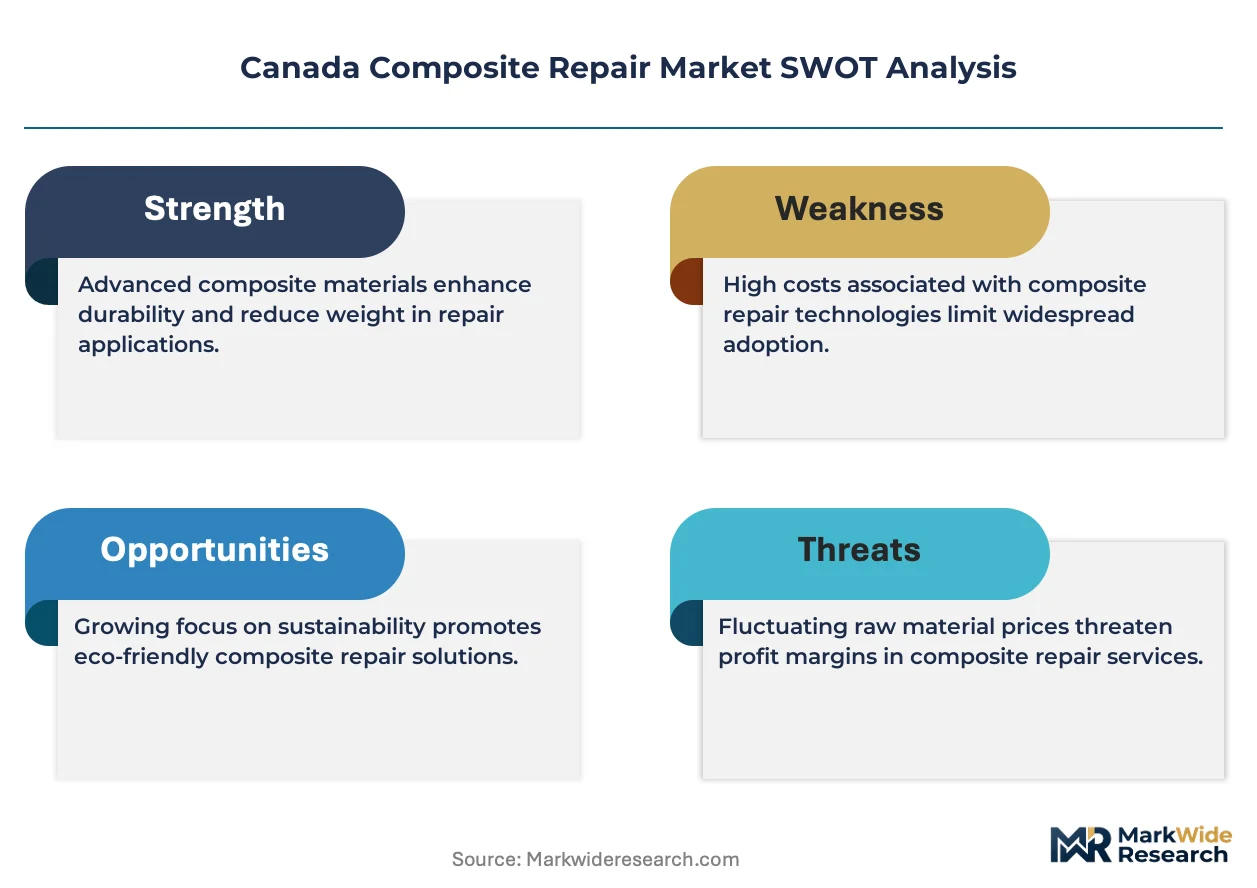
- Epoxy resin price volatility:Petrochemical feedstock fluctuations directly impact prepreg and adhesive material costs, squeezing contractor margins on fixed-price maintenance contracts.
- Specialized technician scarcity:Vacuum infusion and scarf repair certification programs produce fewer qualified practitioners than replacement demand requires, particularly in remote Western Canadian installations.
- Metallic repair substitution:Steel sleeve clamping retains cost advantage for low-pressure pipeline segments, limiting composite wrap penetration in price-sensitive maintenance budgets.
Strategic Opportunities
- Offshore wind foundation rehabilitation:Atlantic Canada's emerging turbine installations will require subsea composite pile repair capabilities that domestic contractors currently lack.
- Transport Canada drone inspection integration:Automated damage assessment protocols reduce downtime for commercial aviation operators, creating bundled repair service contracts.
- Prefabricated repair kit distribution:Direct-to-contractor material supply bypasses traditional distributor markups for marine and automotive hand layup segments.
Industry Challenges
- Multi-agency certification timelines:Health Canada material safety approvals and Transport Canada airworthiness qualifications run on parallel tracks, extending product commercialization cycles.
- Environmental control requirements:Temperature and humidity specifications for prepreg curing demand climate-controlled hangar and shop infrastructure that smaller operators cannot afford.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Composite Repair Market |
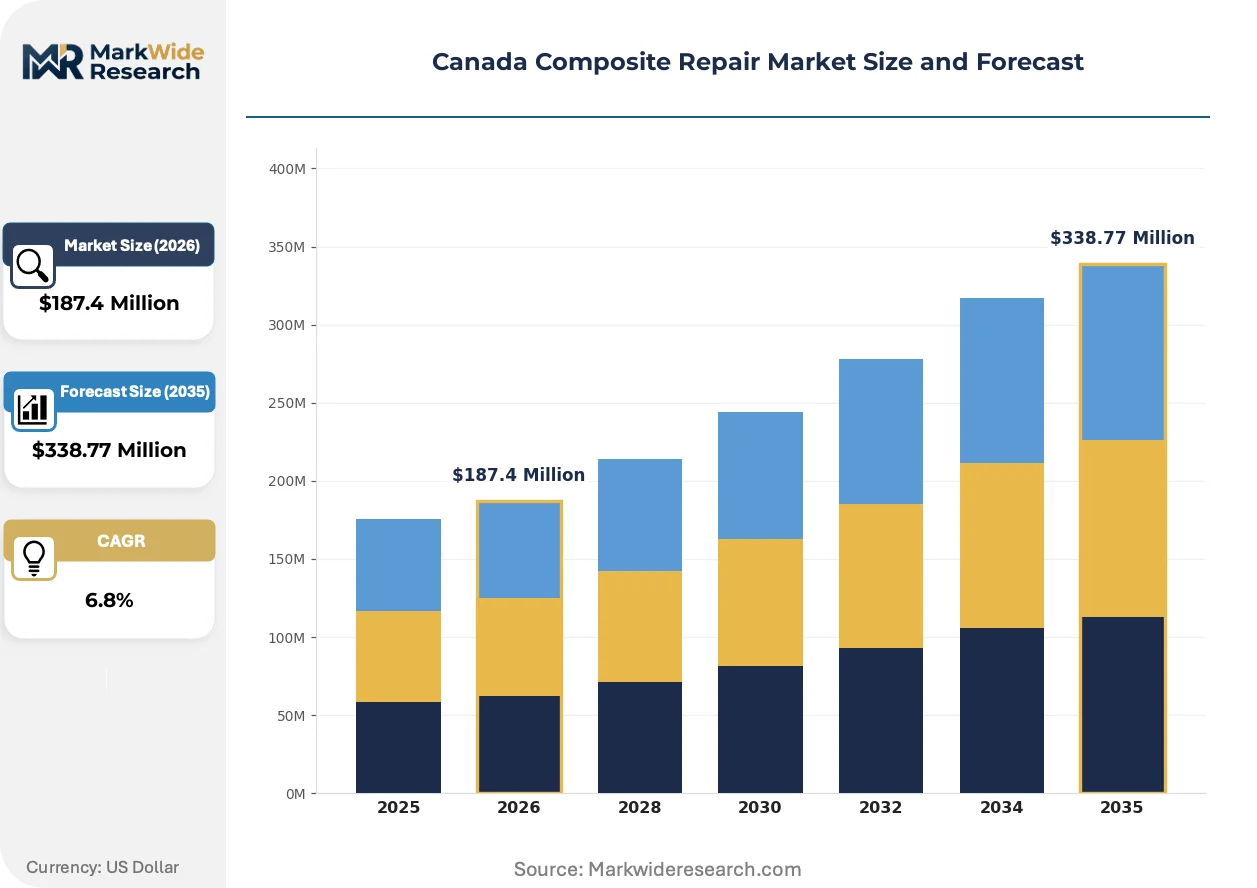
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural, Non-Structural, Surface Repair, Specialty Application: Aerospace, Marine, Automotive, Industrial Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Technology: Vacuum Infusion, Hand Layup, Prepreg, Resin Transfer Molding |
| Companies Covered | HAECO, Citadel Technologies, Milliken Infrastructure, T.D. Williamson, Fibrwraps, Hexcel, 3M, West Systems, WR Composites, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Composite Repair Market Strategic Shifts
Automation and digital inspection tools are compressing damage assessment timelines while expanding the addressable market for in-situ repairs previously requiring component replacement.
Vacuum-assisted resin transfer molding is expanding into high-pressure pipeline rehabilitation across Alberta's oil sands infrastructure. Midstream operators now specify VARTM wraps for corroded elbow joints and flange connections that previously required line shutdown and metallic replacement. The technique is expanding into geometries that hand layup cannot reliably seal, displacing mechanical clamp systems in critical pressure zones.
Transport Canada's evolving Canadian Aviation Regulations now mandate phased array ultrasonic testing for hidden delamination detection in primary flight structures. Airlines operating aging Bombardier and De Havilland fleets must deploy advanced NDT protocols before scheduled maintenance intervals. Repair stations in Toronto and Montreal are acquiring automated scanning equipment to meet these inspection frequencies, shifting competitive advantage toward capital-intensive facilities.
Maintenance procurement now bundles composite repair with predictive analytics subscriptions rather than transactional work orders. Large fleet operators in Quebec negotiate multi-year airframe restoration agreements incorporating real-time damage monitoring. This restructuring concentrates contract awards among integrated service providers capable of data interpretation and rapid response deployment across dispersed operating bases.
Canada Composite Repair Market Segmentation
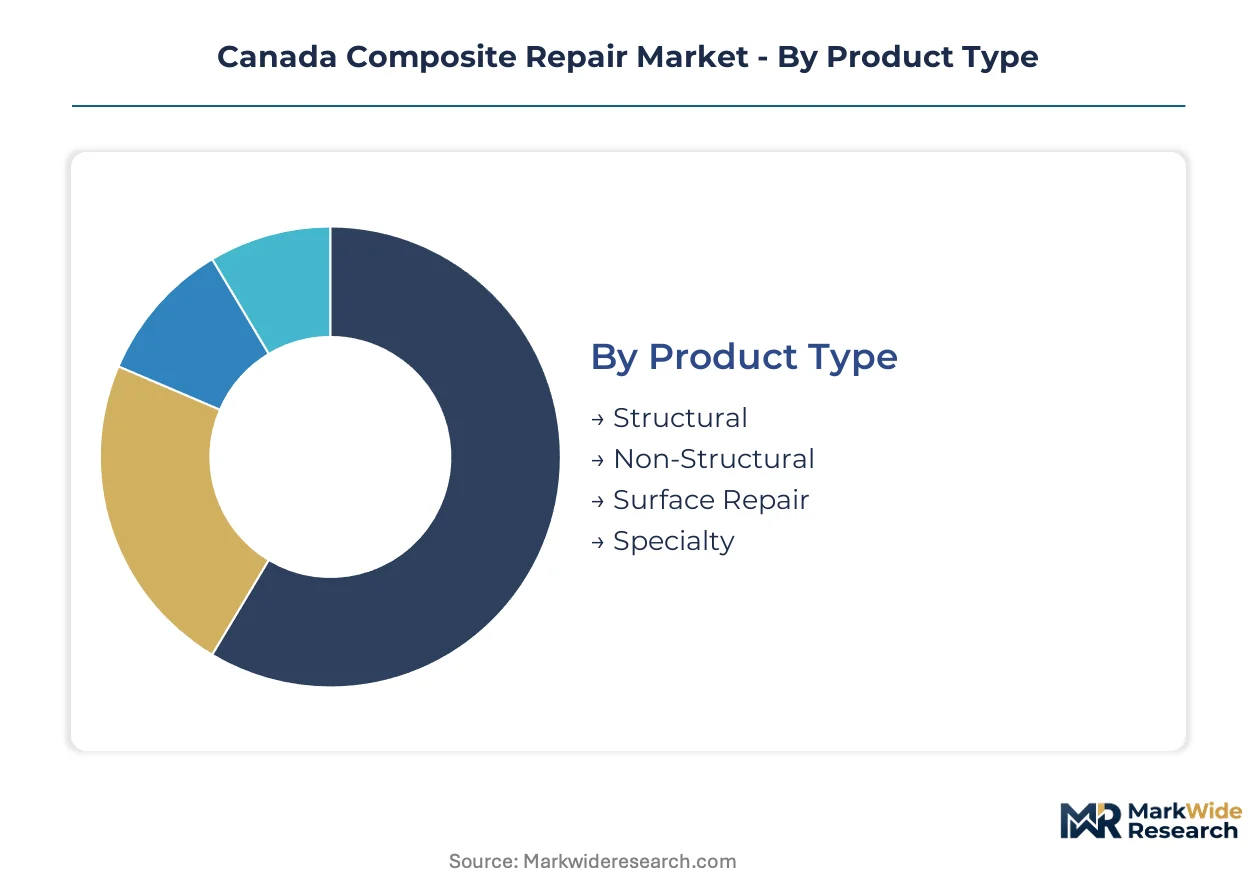
Segmentation in Canada's composite repair market reveals divergent capital requirements and certification barriers across product tiers, application verticals, and material grades. Repair contractors align their capability investments with the regulatory intensity of target end-uses rather than pursuing horizontal coverage.
Product Type:
Structural repairs demand the heaviest upfront investment in climate-controlled facilities, load-testing equipment, and Transport Canada certification pathways that smaller operators cannot finance.
- Structural:Load-bearing restoration using bonded scarf joints and stepped-laminate configurations to recover 80-90% of original tensile strength. Demand concentrates in Ontario and Quebec aerospace maintenance facilities where Bombardier and De Havilland fleets require airframe interventions that airworthiness directives mandate.
- Non-Structural:Cosmetic and semi-structural interventions including gelcoat restoration and minor laminate patching. Marine operators across British Columbia's coastal shipyards drive volume here, prioritizing cost efficiency over certification burden for below-waterline repairs.
- Surface Repair:Gelcoat refinishing and UV damage mitigation requiring minimal capital equipment.
- Specialty:Fire-resistant and radar-transparent formulations for military aviation applications with restricted contractor pools.
Most installed capacity flows through Structural repairs. Expansion is steepest in Non-Structural as commercial marine operators internalize basic maintenance capabilities.
Application:
Application segmentation maps directly to regulatory jurisdiction overlap, with aviation commanding the most stringent multi-agency oversight from Transport Canada and Health Canada.
- Aerospace:Primary flight structure restoration governed by Canadian Aviation Regulations damage tolerance requirements. Toronto and Montreal repair stations dominate, leveraging proximity to original equipment manufacturer engineering support and phased array ultrasonic testing infrastructure.
- Marine:Hull and superstructure rehabilitation across commercial fishing fleets and coastal ferry services. British Columbia's shipyards account for disproportionate demand given saltwater corrosion acceleration and extended vessel service lives.
- Automotive:Motorsport and specialty vehicle carbon fiber body panel repair with limited certified provider networks.
- Industrial:Pressure vessel and tank rehabilitation in Alberta's oil sands corridor, where fiberglass wrap systems address corrosion under insulation.
Revenue concentrates in Aerospace applications. Climbing the fastest is Industrial as pipeline integrity mandates from the Canadian Energy Regulator accelerate wrap system deployment.
Material:
Material selection determines margin structure through resin formulation complexity and storage requirements that shape distributor economics.
- Carbon Fiber:High-modulus reinforcement for flight-critical structures and high-pressure pipeline wraps. Aerospace MRO operators in Quebec specify aerospace-grade prepreg systems with frozen storage chains that exclude uncertified contractors.
- Glass Fiber:E-glass and S-glass reinforcements for marine hull repairs and industrial tank rehabilitation. Alberta's oil sands midstream operators specify fiberglass for corrosion-resistant pipeline wraps where pressure ratings permit lower modulus materials.
- Aramid Fiber:Ballistic and abrasion-resistant applications in armored vehicle and specialty marine segments.
- Hybrid:Combined fiber architectures optimizing cost-performance tradeoffs in wind turbine blade repair.
Carbon fiber commands the highest unit margins. Glass fiber delivers the steepest volume expansion through industrial infrastructure rehabilitation contracts.
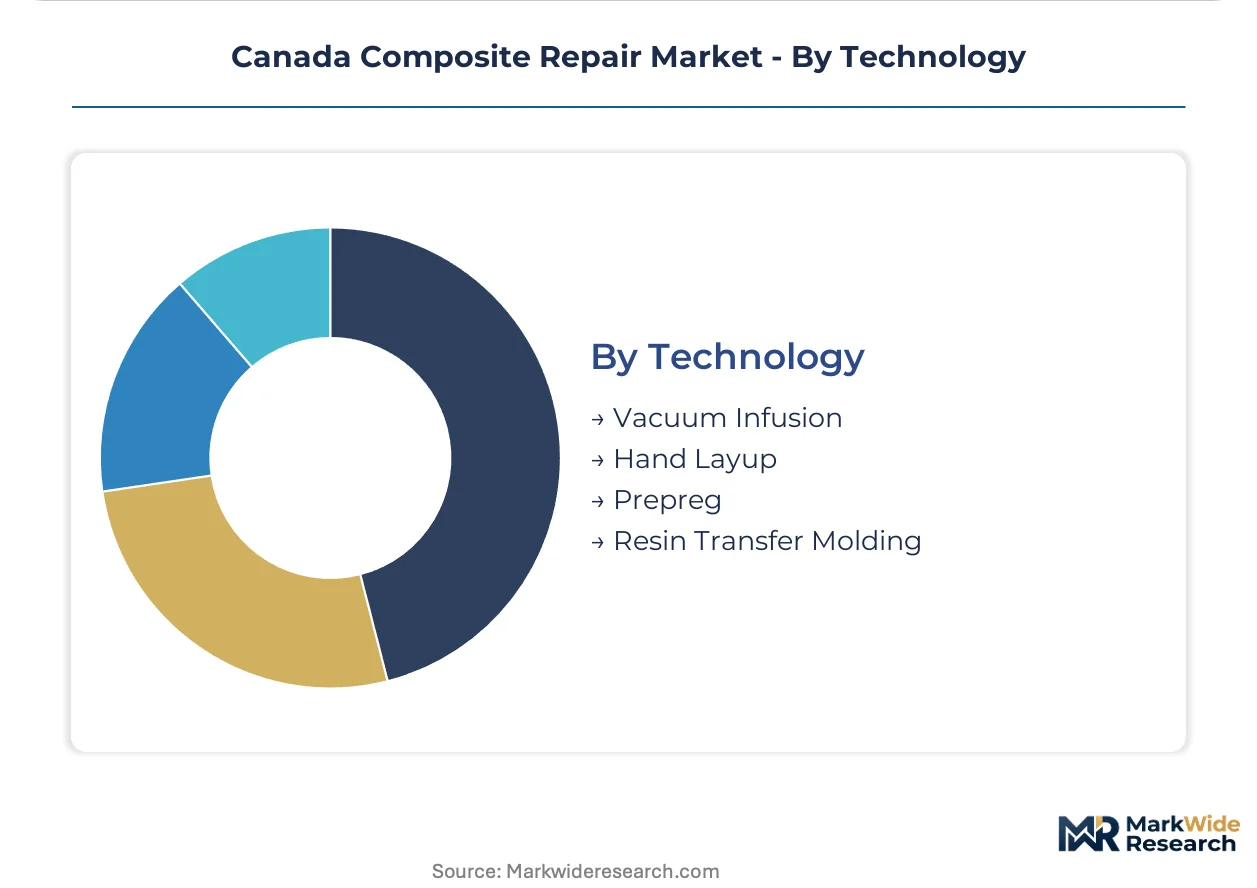
Technology:
Technology segmentation separates capital-intensive automated processes from labor-dependent manual techniques that dominate remote field deployment.
- Vacuum Infusion:Controlled resin impregnation under negative pressure achieving consistent fiber volume fractions for primary structure restoration. Western Canadian pipeline contractors deploy portable vacuum systems for in-situ pressure vessel repairs that hand layup cannot reliably seal.
- Hand Layup:Manual fiber placement and roller consolidation for non-critical repairs. Marine and automotive segments across coastal British Columbia and southern Ontario rely on this technique where cost sensitivity outweighs precision requirements and environmental control is impractical.
- Prepreg:Factory-impregnated fiber systems requiring frozen storage and autoclave or oven curing. Aerospace repair stations in Toronto and Montreal maintain dedicated climate-controlled prepreg facilities to meet Transport Canada airworthiness standards.
- Resin Transfer Molding:Closed-mold injection for complex geometric repairs with dimensional tolerance requirements.
Hand layup retains the largest installed base. Vacuum infusion is gaining share fastest as pipeline operators specify the technique for high-pressure wrap applications previously served by mechanical clamps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's aerospace corridor anchors Canadian composite repair capacity through Toronto and Montreal maintenance clusters serving Bombardier and De Havilland fleets. Transport Canada airworthiness directives and Health Canada material safety protocols compress inspection cycles across provincial repair networks.
Ontario
Bombardier fleet aging and regional airline MRO consolidation drive structural repair demand in Toronto Pearson corridor. Transport Canada Canadian Aviation Regulations mandate phased array ultrasonic testing infrastructure that only capital-intensive facilities can finance. Mississauga and Downsview repair stations cluster around original equipment manufacturer engineering support for primary flight structure restoration.
Quebec
De Havilland Dash 8 airframe restoration and military aviation maintenance sustain Montreal-area composite intervention volumes. Health Canada coordinates with Transport Canada on resin system safety certifications affecting adhesive formulations. Mirabel and Saint-Hubert aerospace clusters host prepreg-curing facilities meeting frozen storage chain requirements for flight-critical repairs.
Alberta
Oil sands pipeline integrity mandates from the Canadian Energy Regulator accelerate fiberglass and carbon fiber wrap deployment for corrosion management. Midstream operators specify vacuum-assisted resin transfer molding for high-pressure elbow joints and flange connections. Calgary and Edmonton serve as contractor coordination hubs for remote Western Canadian pressure vessel rehabilitation.
British Columbia
CSA S806 code adoption for seismic retrofit requirements opens civil infrastructure rehabilitation demand in Vancouver and Victoria. Coastal shipyards drive non-structural marine repair volume for commercial fishing fleets and ferry services. Saltwater corrosion acceleration extends vessel service lives through gelcoat restoration and laminate patching below the waterline.
Atlantic Canada
Emerging offshore wind turbine installations will require subsea composite pile repair capabilities that domestic contractors currently lack. Nova Scotia and Newfoundland energy infrastructure operators evaluate imported specialist deployment for foundation rehabilitation. Regional repair capacity concentrates on marine hull maintenance rather than subsea structural intervention.
Canada Composite Repair Market Competitive Environment
Technology licensing dominates the current landscape as material suppliers transfer prepreg and vacuum infusion protocols to certified repair stations. The vendor base separates into three tiers: multinational chemical conglomerates controlling resin formulation, specialized wrap system fabricators serving energy infrastructure, and regional MRO operators holding Transport Canada certifications. Two strategic archetypes define positioning: integrated material-service providers bundling predictive analytics with repair execution, and pure-play contractors competing on inspection response speed. Geographic expansion into Atlantic Canada and strategic partnerships with offshore wind developers represent the dominant competitive moves.
Among multinational material suppliers, Hexcel and 3M occupy positions exemplifying prepreg technology leadership and adhesive system scale respectively. Specialized infrastructure fabricators include Citadel Technologies and Milliken Infrastructure, representing archetypes of pipeline wrap system specialization and high-strength fiber reinforcement manufacturing. These four entities anchor the competitive structure through control of certified material supply chains that exclude uncertified contractors from premium aerospace and energy segments.
| Leading Market Players |
|---|
| HAECO |
| Citadel Technologies |
| Milliken Infrastructure |
| T.D. Williamson |
| Fibrwraps |
| Hexcel |
| 3M |
| West Systems |
| WR Composites |
| Others |
Value Chain & Pricing Dynamics
West Texas Intermediate crude benchmarks cascade through epoxy resin formulation costs, compressing contractor margins on fixed-price maintenance contracts across Alberta's oil sands corridor and Ontario's aerospace clusters. Transport Canada certification requirements for prepreg storage chains create tiered pricing separation between climate-controlled repair stations and field-deployed hand layup contractors.
Pricing Analysis
Petrochemical feedstock volatility passes through to prepreg and adhesive material costs, forcing project-based pricing with cost-plus escalation clauses for multi-year pipeline rehabilitation contracts. Price differentiation centers on Transport Canada airworthiness certification tier and frozen storage chain maintenance, with aerospace-grade structural repairs commanding substantial premiums over marine non-structural interventions. Cost compression in industrial wrap applications intensifies as steel sleeve clamping retains cost advantage for low-pressure segments. Marine operators across British Columbia exhibit highest price sensitivity, prioritizing cost efficiency over certification burden for below-waterline repairs.
Supply Chain Analysis
Certified composite technician scarcity in remote Western Canadian installations constrains repair station expansion and drives wage inflation through Calgary and Edmonton contractor hubs. Raw material supply concentrates in the United States, Japan, and Germany for aerospace-grade carbon fiber prepreg systems, while fiberglass reinforcement draws from domestic Canadian and Chinese manufacturing. The supply chain rests on epoxy resin and hardener formulations subject to petrochemical price volatility. Single-source vulnerability characterizes aerospace-grade frozen storage logistics. Distribution runs through authorized distributor networks for certified materials, with direct-to-contractor kit supply emerging in marine hand layup segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's composite repair market represents a late-cycle quality story as aging Bombardier and De Havilland fleets force structural restoration toward aerospace-grade specifications that exclude uncertified competitors.
For Market Incumbents: Anticipate metallic repair substitution pressure in Alberta's low-pressure pipeline segments by deepening backward integration into resin formulation and securing exclusive distributor agreements for vacuum infusion equipment. Transport Canada drone inspection mandates will compress response timelines, favoring capital-intensive facilities with automated scanning infrastructure over smaller operators lacking phased array ultrasonic testing capabilities. For New Entrants and Emerging Players: Launch via prefabricated repair kit distribution targeting British Columbia's marine non-structural segment, where cost sensitivity outweighs certification demands and hand layup techniques dominate. Atlantic Canada's emerging offshore wind infrastructure offers the most penetrable white space, as domestic contractors currently lack subsea composite pile repair capabilities. Bundle material supply with basic technician training programs to bypass established distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized pipeline wrap system fabricators holding Canadian Energy Regulator approvals and proprietary vacuum-assisted resin transfer molding protocols. Long-term viability hinges on regulatory compliance depth rather than scale economies across the five-to-ten year window. Monitor Transport Canada airworthiness directive issuance frequency as the inflection indicator for aerospace MRO capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in Transport Canada Airworthiness Standards | Phased array ultrasonic testing infrastructure excludes uncertified competitors from Toronto and Montreal aerospace clusters. |
| Backward Integration into Epoxy Resin Formulation | In-house adhesive production insulates margins from West Texas Intermediate price volatility in fixed-price contracts. |
| Geographic Expansion into Atlantic Canada Offshore Wind | Subsea composite pile repair capabilities address foundation rehabilitation demand that domestic contractors currently cannot serve. |
| Prefabricated Repair Kit Distribution Network | Direct-to-contractor marine supply bypasses traditional distributor markups in British Columbia's cost-sensitive shipyard segment. |
| Strategic Partnership with Drone Inspection Technology Providers | Automated damage assessment bundling creates multi-year service contracts with Quebec fleet operators requiring rapid response deployment. |
Study Parameters
Bottom-up aerospace and energy infrastructure modeling reconciled against top-down material supplier tracking forms the analytical core of this study. Primary interviews with MRO station managers, pipeline integrity engineers, composite technician training program directors, and Canadian Energy Regulator compliance officers combined with secondary validation from Transport Canada airworthiness directives, Canadian Standards Association S806 building code adoption records, Health Canada material safety filings, and provincial trade association membership databases.
Input-output matrices map resin formulation costs through prepreg manufacturing into repair service pricing across segmentation dimensions including product type, application vertical, material grade, and technology tier. CAGRs derive from regression analysis against fleet age demographics, pipeline integrity mandate timelines, and code adoption schedules throughout the forecast period. Industry-specific forecast inputs incorporate Bombardier and De Havilland aircraft retirement curves alongside Alberta oil sands midstream capital maintenance budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt epoxy resin price spikes or accelerated Transport Canada inspection frequency mandates. Forecasts reflect assumptions regarding CSA S806 provincial harmonization timing and vacuum infusion technician certification program graduation rates. Material deviation in Health Canada resin system safety approval timelines or Canadian Energy Regulator pipeline shutdown enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
H Beam Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Steel Beam Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Bridge Bearings Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
US Heavy Movable Bridges Market