
 Girder Market | 2026-2036
Girder Market Size, Share, and Industry Trends Forecast 2026-2036
Girder Market Insights
Aftermarket service revenue for structural steel inspection and retrofit is reconfiguring how suppliers capture lifetime value from infrastructure assets. ArcelorMittal leverages its global fabrication network to anchor long-term maintenance contracts. Nucor Corporation competes through mini-mill flexibility that sustains regional project responsiveness.
A girder is a horizontal structural member, typically fabricated from rolled steel with yield strengths of 250-355 MPa or prestressed concrete with tendon stresses exceeding 1,860 MPa, designed to resist bending moments and shear forces in buildings and bridges. Steel I-beam girders dominate commercial building applications due to standardized rolling efficiency and erection speed. Box girder designs capture premium positioning in long-span bridge projects where torsional rigidity governs performance requirements. Prefabrication methods accelerate transport infrastructure timelines by shifting assembly labor from congested sites to controlled factory floors.
ISO 3834 welding quality standards, EN 1090 execution classes for steel structures, and India's BIS IS 2062 structural steel specifications collectively govern market access and liability exposure for fabricators. China's GB/T 1591 high-strength low-alloy standards and Japan's JIS G 3101 general structural steel rules create layered compliance obligations for multinational suppliers. Stakeholders must monitor how evolving embodied-carbon thresholds in European procurement codes reshape material selection between conventional steel and emerging composite alternatives.
Market Dynamics
Bridge construction across Southeast Asia and China's high-speed rail corridor projects are concentrating fabrication capacity in East Asian port cities, while India's BIS certification mandates reshape procurement standards for structural steel quality.
Growth Catalysts
- GB/T 1591 high-strength low-alloy standards:China's national standardization push accelerates adoption of advanced steel grades in long-span bridge projects, reducing material tonnage requirements per kilometer of rail infrastructure.
- Prefabrication methods:Controlled factory floor assembly shifts labor away from congested urban construction sites, compressing transport infrastructure timelines by 30-40% in dense metropolitan corridors.
- Box girder designs:Torsional rigidity advantages capture premium positioning in cable-stayed and suspension bridge segments where wind loading and seismic performance govern engineering specifications.
Market Restraints
- Scrap steel price volatility:Mini-mill operators face margin compression when ferrous scrap benchmarks spike, forcing pass-through pricing that erodes competitive position against integrated producers.
- ISO 3834 welding certification backlog:Fabrication shops in emerging markets face 6-12 month qualification delays, constraining access to European infrastructure tenders governed by EN 1090 execution classes.
- Prestressed concrete substitution:Post-tensioned concrete girders with tendon stresses exceeding 1,860 MPa compete aggressively in medium-span bridge segments where steel I-beams previously dominated.
Strategic Opportunities
- Aftermarket inspection contracts:Structural steel retrofit and fatigue monitoring services create recurring revenue streams anchored to lifetime asset management rather than single-project fabrication.
- EU Green Deal embodied-carbon thresholds:Procurement codes in Germany, France, and the Netherlands increasingly favor low-carbon steel and composite alternatives, rewarding early certification investments.
- Indonesia-Malaysia-Thailand rail corridors:Underpenetrated Southeast Asian markets present fabrication partnerships with local steel producers seeking technology transfer for high-speed rail viaduct construction.
Industry Challenges
- EN 1090 EXC3/EXC4 welder certification scarcity:Qualified welding inspectors command 40% salary premiums, constraining capacity expansion for bridge fabricators targeting European export markets.
- Legacy ERP-to-factory automation integration:Mid-tier fabricators struggle to synchronize nesting software with plasma cutting tables, delaying just-in-sequence delivery for modular bridge projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Girder Market |
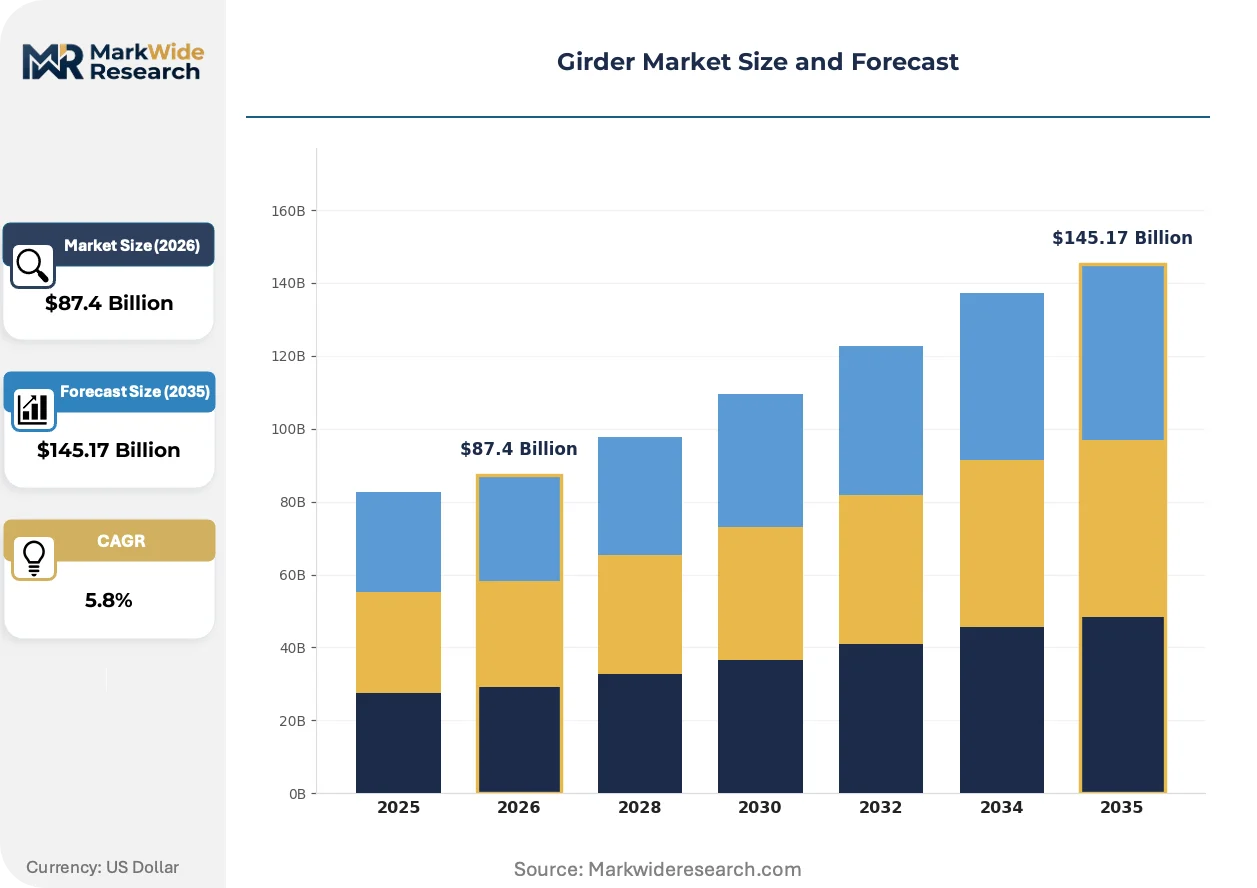
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Concrete, Timber, Aluminum, Composite Design Style: I-Beam, Box Girder, T-Beam, Lattice Girder, Cellular Girder Application Sector: Bridges, Commercial Buildings, Industrial Facilities, Transport Infrastructure, Stadiums Installation Method: Prefabrication, On-site Assembly, Modular Construction, Heavy Lifting, Cantilever Construction |
| Companies Covered | ArcelorMittal, JFE Holdings, Nippon Steel Corporation, Tata Steel Limited, POSCO, Nucor Corporation, China Baowu Steel Group Corporation, JSW Steel Ltd., Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Girder Market Trends and Innovations
Digital fabrication workflows and embodied-carbon accounting are reconfiguring how girder specifications move from engineering offices to factory floors, with compliance documentation now embedded in BIM models rather than appended as paper certifications.
High-strength weathering steel with autonomous protective oxide layers is collapsing maintenance cost structures for railway bridge owners. Indian Railways and China Railway Group are specifying these grades for new corridor construction, eliminating the 15-year repainting cycles that previously disrupted traffic. The technology is compressing lifecycle cost models that historically favored initial material savings over durability.
India's BIS IS 2062 structural steel specifications now mandate third-party factory production control audits for imported material, creating friction for Southeast Asian suppliers. The regulation forces fabricators to establish local testing partnerships or absorb 8-12 week certification delays. Bridge contractors in Maharashtra and Gujarat states are responding by consolidating procurement with domestic mills holding pre-approved BIS licenses.
Asset owners in Japan and South Korea are unbundling fabrication contracts from 30-year maintenance agreements, reversing the integrated EPC model that dominated 2010s infrastructure procurement. Railway operators now issue separate tenders for girder supply, installation supervision, and predictive inspection services. This pattern is most visible in Tokyo-Osaka Shinkansen extension segments and Seoul's metropolitan rail expansion corridors.
Girder Market Segmentation
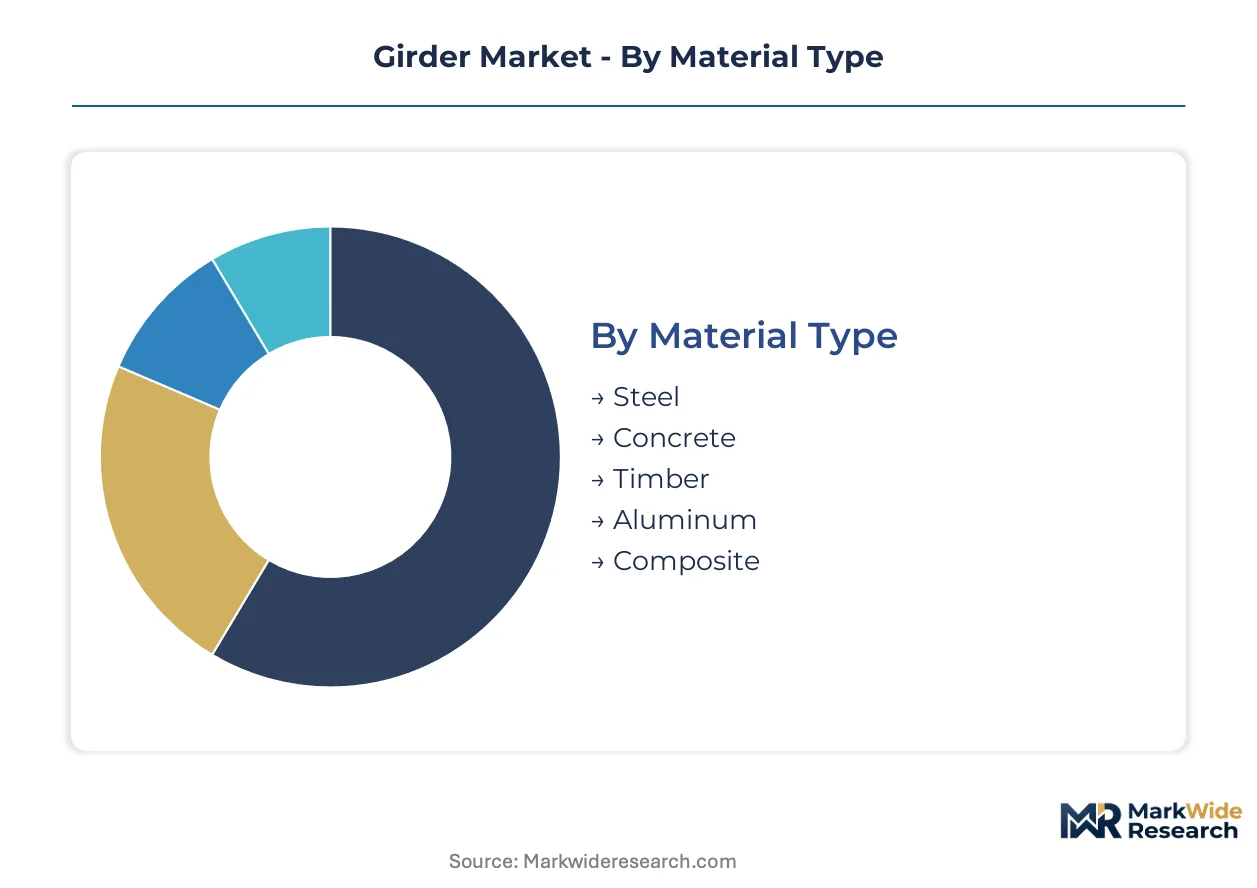
Girder procurement patterns diverge sharply across material grades and fabrication methods. Bridge contractors prioritize torsional performance metrics while commercial developers optimize for erection speed and crane capacity constraints.
Material Type:
Steel commands the shortest specification-to-delivery cycle through mill-direct rolling programs, while timber and composite alternatives face extended lead times due to lamination curing and resin hardening processes.
- Steel:Rolled sections with yield strengths of 250-355 MPa dominate through standardized I-beam and wide-flange profiles. China's high-speed rail corridor projects and India's BIS IS 2062 certified procurement anchor volume demand for this grade.
- Concrete:Prestressed designs with tendon stresses exceeding 1,860 MPa displace steel in medium-span bridge segments where corrosion resistance governs lifecycle cost models. Post-tensioned box girders capture share in Southeast Asian coastal infrastructure exposed to chloride ingress.
- Timber:Glulam and cross-laminated timber configurations serve Nordic commercial buildings pursuing embodied-carbon reduction targets under EU Green Deal procurement codes.
- Aluminum:Lightweight extrusions enable rapid deployment in temporary stadium structures and modular pedestrian bridges where transport weight limits constrain steel alternatives.
- Composite:Fiber-reinforced polymer and steel-concrete hybrid systems penetrate long-span applications demanding fatigue resistance beyond conventional material limits.
Steel anchors the volume base while composite systems gain share at the steepest rate as European asset owners embed carbon intensity thresholds in tender evaluation criteria.
Design Style:
Cost tiers separate standardized rolled sections from engineered hollow-box configurations, with premium positioning correlating directly to fabrication complexity and welding certification requirements.
- I-Beam:Open-section profiles rolled to standardized dimensions enable mass production efficiency and rapid site erection through bolted connections. Commercial building developers in Japan and South Korea specify these for repetitive bay structures.
- Box Girder:Closed-cell steel or concrete configurations deliver torsional rigidity for cable-stayed bridge decks and curved highway alignments. EN 1090 EXC4 execution class welding mandates restrict supplier pools for this segment.
- T-Beam:Precast concrete flanges with cast-in-place topping dominate parking structure construction across North American and Australian markets.
- Lattice Girder:Triangulated steel chord assemblies reduce material tonnage in long-span roof structures for industrial facilities and exhibition halls.
- Cellular Girder:Castellated and perforated web designs integrate building services routing for commercial buildings pursuing ceiling height optimization.
I-Beam configurations sustain the highest shipment volumes while box girder specifications expand most quickly in premium bridge infrastructure tenders.
Application Sector:
Customer type determines specification authority, with public infrastructure agencies enforcing national standards while private developers exercise discretion over material substitution.
- Bridges:Long-span structures demand rigorous fatigue analysis and wind-loading verification. China's GB/T 1591 high-strength low-alloy grades reduce material quantities per kilometer in high-speed rail viaducts.
- Commercial Buildings:Mid-rise steel frames prioritize erection speed to minimize financing carry costs. Japanese METI building codes influence seismic detailing requirements for this segment.
- Industrial Facilities:Heavy crane runway girders and process equipment supports require deflection limits stricter than commercial standards.
- Transport Infrastructure:Railway stations and airport terminals specify fire-rated coatings and acoustic damping treatments beyond standard structural requirements.
- Stadiums:Long-span roof girders with architecturally exposed steel demand aesthetic surface finishing and tight dimensional tolerances.
Bridge construction anchors the value base while transport infrastructure applications climb the fastest as Southeast Asian rail corridors advance through Indonesia, Malaysia, and Thailand.
Installation Method:
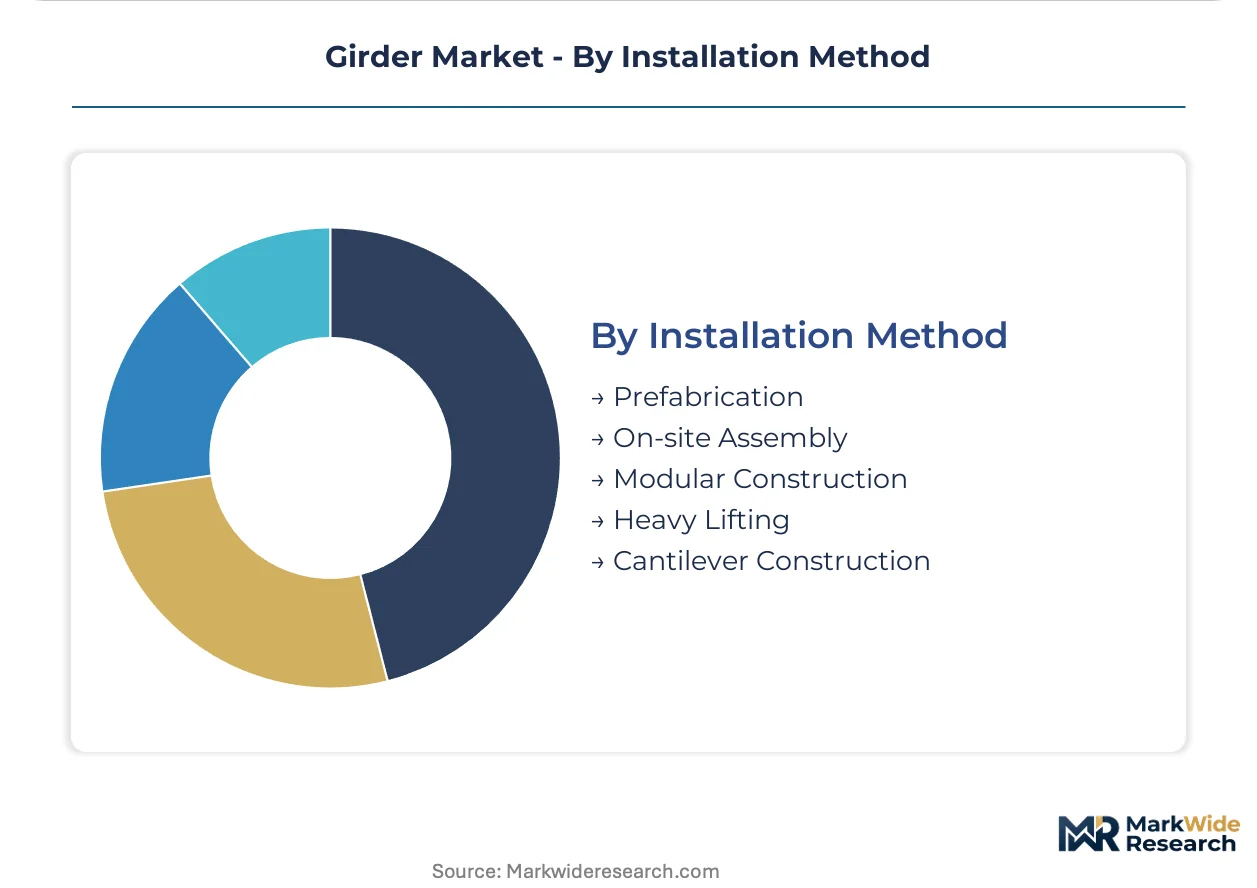
Supply concentration clusters around prefabrication hubs in East Asian port cities, while on-site assembly retains relevance in remote geographies lacking heavy-lift logistics infrastructure.
- Prefabrication:Factory-controlled welding under ISO 3834 quality systems shifts labor from congested urban sites to industrial zones. Chinese fabricators serving high-speed rail projects achieve 30-40% timeline compression through this approach.
- On-site Assembly:Bolted field connections accommodate irregular foundation conditions and last-minute design modifications. Indian bridge contractors in Maharashtra and Gujarat states retain this method for river crossings with unpredictable subsoil profiles.
- Modular Construction:Complete structural modules with integrated MEP systems target hospitality and healthcare buildings pursuing speed-to-market advantages.
- Heavy Lifting:Segmental erection using floating cranes and strand jacks enables bridge construction over navigable waterways without temporary supports.
- Cantilever Construction:Balanced cantilever methods for prestressed concrete box girders minimize environmental disturbance in ecologically sensitive corridors.
Prefabrication commands the dominant share position while modular construction gains traction at the steepest rate as labor shortages intensify in developed Asian economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge contractors in Vietnam and Indonesia exhibit acute price sensitivity to scrap steel fluctuations, while Japanese and South Korean rail agencies prioritize lifecycle durability over initial material cost, creating divergent procurement elasticities across Asian infrastructure markets.
China
High-speed rail viaduct construction along the Beijing-Shanghai corridor consumes GB/T 1591 certified high-strength low-alloy grades. The Ministry of Ecology and Environment enforces embodied-carbon disclosure requirements for state-funded infrastructure tenders. Fabrication clusters in Tangshan and Rizhao port cities concentrate capacity serving both domestic rail expansion and Southeast Asian export contracts.
India
Maharashtra and Gujarat state bridge authorities drive demand for BIS IS 2062 certified structural steel after third-party factory production control audits became mandatory for imports. The Central Electricity Authority coordinates material standards across power transmission infrastructure that shares fabrication capacity with bridge projects. Mumbai-Pune expressway expansion and Dedicated Freight Corridor segments concentrate procurement with domestic mills holding pre-approved licenses.
Japan
Shinkansen extension segments between Tokyo and Osaka unbundle 30-year maintenance agreements from initial girder supply contracts. METI building codes enforce seismic detailing requirements that elevate fabrication certification thresholds above regional norms. Nagoya-based fabrication networks specialize in EXC4 execution class welding for cable-stayed bridge decks serving Pacific coastal corridors.
South Korea
Seoul metropolitan rail expansion corridors specify predictive inspection services as separate tender packages from girder fabrication. The Ministry of Land, Infrastructure and Transport mandates fatigue monitoring protocols for railway bridge assets exceeding 50-year design lives. Busan-Ulsan industrial zones anchor heavy-lift modular assembly capacity for segmental bridge construction over navigable waterways.
Indonesia
Java-Bandung high-speed rail viaducts and trans-Sumatra highway bridges create underpenetrated demand for prefabricated box girder systems. The national infrastructure procurement regulator requires local content thresholds that force technology transfer partnerships with East Asian fabricators. Surabaya port clusters emerging as sub-assembly hubs serving archipelago logistics constraints.
Girder Market Competitive Landscape
Capability concentration sits with integrated steel producers commanding mill-direct rolling programs and EN 1090 EXC4 welding certifications; scale advantage sits with mini-mill operators sustaining regional project responsiveness through scrap-fed flexibility. The market structures around three archetypes: multinational integrated producers with global fabrication networks, regional mini-mill specialists with backward integration into scrap processing, and state-affiliated Asian steel groups with captive infrastructure demand. Dominant competitive moves include strategic partnerships for technology transfer in Southeast Asian rail corridors and portfolio diversification into aftermarket inspection services.
Among Luxembourg-based integrated producers, ArcelorMittal exemplifies the capability-concentrated tier through its global fabrication network anchoring long-term maintenance contracts. Charlotte-based Nucor Corporation occupies the scale-driven mini-mill position with regional responsiveness to scrap price volatility. Mumbai-headquartered Tata Steel Limited and Seoul-based POSCO represent state-influenced Asian groups with integrated positions spanning raw material access through finished girder supply.
| Leading Market Players |
|---|
| ArcelorMittal |
| JFE Holdings |
| Nippon Steel Corporation |
| Tata Steel Limited |
| POSCO |
| Nucor Corporation |
| China Baowu Steel Group Corporation |
| JSW Steel Ltd. |
| Thyssenkrupp AG |
| Others |
Pricing and Supply Chain Analysis
Tangshan and Rizhao port city fabrication clusters anchor Chinese GB/T 1591 certified capacity, concentrating margin capture with integrated mills commanding mill-direct rolling programs while mini-mill operators absorb scrap volatility pass-through.
Pricing Analysis
Aftermarket inspection and retrofit service contracts drive lifetime value realization, with three-tier pricing structure across premium EXC4-certified box girder systems, standard I-beam commercial configurations, and economy-grade regional mill offerings. Price differentiation hinges on EN 1090 execution class welding certification and bundled maintenance agreements. Pricing pressure stems from ferrous scrap benchmark spikes compressing mini-mill margins. Bridge contractors in Vietnam and Indonesia exhibit acute price sensitivity; Japanese rail agencies prioritize lifecycle durability over initial material cost.
Supply Chain Analysis
Supplier-financing facilities through East Asian port city fabrication networks extend payment terms to bridge contractors facing state procurement budget cycles. Supply concentrates in China, India, and Japan. Raw material flows draw from seaborne iron ore, ferrous scrap, and high-strength low-alloy additives. Single-source vulnerability sits with ISO 3834 welding certification bottlenecks constraining qualified fabrication shop capacity. Distribution runs through mill-direct programs for large infrastructure tenders and regional distributor networks for commercial building projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where EN 1090 EXC3/EXC4 welder certification scarcity creates regulatory entrenchment against price-based competition.
For Market Incumbents: Insulate fabrication capacity through backward integration into scrap processing and captive high-strength rolling mill capacity. Secure EXC4 welding inspector pipelines against 40% salary premiums eroding project margins. Consolidate maintenance contract portfolios as asset owners unbundle 30-year agreements from initial supply. For New Entrants and Emerging Players: Build out technology transfer partnerships with Indonesian and Malaysian state steel producers seeking GB/T 1591 process knowledge for high-speed rail viaduct construction. Target underpenetrated Southeast Asian rail corridors where local content thresholds force joint venture structures. Lead with prefabrication capability rather than commodity girder supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aftermarket inspection services as asset-light predictive monitoring platforms displace heavy fabrication equipment. Long-term viability favors service-revenue models anchored to lifetime asset management. Acquisition targets include regional mini-mill specialists with ISO 3834 certification and established maintenance contract books. Watch for EU Green Deal embodied-carbon threshold enforcement as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Processing | Mini-mill operators secure margin insulation against ferrous scrap price volatility through captive supply. |
| EXC4 Welding Certification Investment | Fabricators unlock premium box girder bridge tenders governed by EN 1090 execution class mandates. |
| Technology Transfer Partnership | East Asian fabricators satisfy Indonesian local content rules while accessing archipelago rail corridor demand. |
| Aftermarket Service Portfolio Buildout | Suppliers capture recurring revenue as Japanese and South Korean rail agencies unbundle maintenance agreements. |
| Low-Carbon Steel Certification Program | Early movers secure preferential positioning under EU Green Deal procurement codes in German and Dutch tenders. |
Research Methodology
A standing panel of bridge procurement officers, fabrication plant managers, EN 1090 welding inspectors, and railway asset maintenance directors provided ongoing calibration against secondary validation through customs trade data, BIS certification registries, SEC steel producer filings, and infrastructure tender databases. Bottom-up project pipeline analysis triangulated with top-down capacity utilization surveys across Tangshan, Rizhao, and Nagoya fabrication clusters.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling material type segmentation by steel grade certification, design style by torsional performance tier, application sector by public versus private procurement authority, and installation method by prefabrication intensity. CAGRs derived from capacity expansion announcements, rail corridor investment schedules, and substitution elasticity between prestressed concrete and steel alternatives.
Stress conditions across scrap steel price bands, welding certification queue durations, and EU embodied-carbon threshold enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure investment continuity and regulatory certification stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Bridge Construction Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Steel Beam Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Bridge Bearings Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market