
 China Structural Steel Fabrication Market | 2026-2036
China Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
China Structural Steel Fabrication Market Outlook
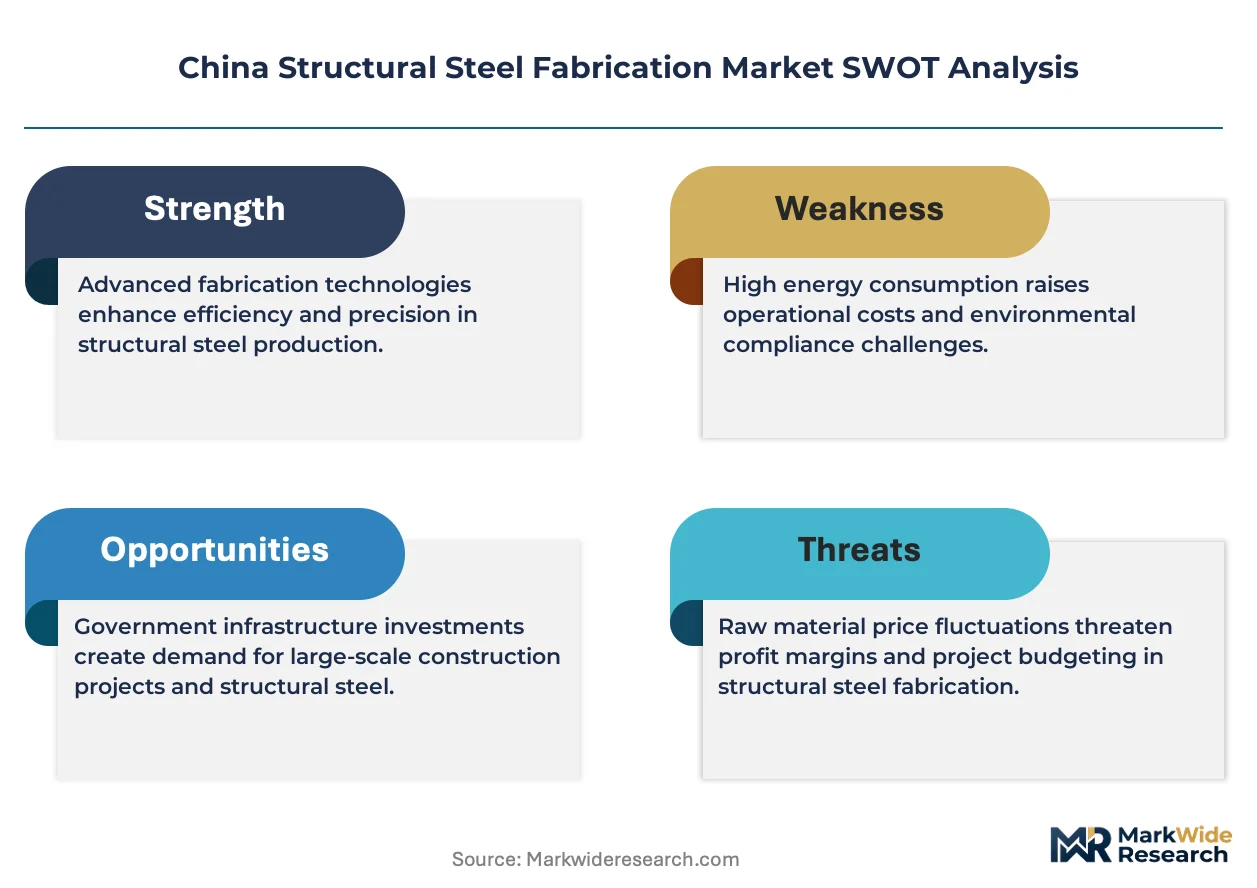
Project finance tied to municipal infrastructure bonds is rewriting capital access for mid-tier fabricators across China's interior provinces. Baowu Steel Group leverages captive raw steel supply to anchor cost positions in heavy-gauge structural sections. Zhejiang Southeast Space Frame Co., Ltd. sustains technology leadership through precision welding automation for stadium and airport roof trusses. Qingdao Wuxiao Group Co., Ltd. competes on coastal logistics, controlling port-adjacent fabrication yards that reduce beam transport costs to offshore wind installations.
Structural steel fabrication transforms hot-rolled sections and plate into engineered assemblies through cutting, welding, bending, and surface treatment to specified mechanical properties and dimensional tolerances. These fabricated components serve as the primary load-bearing skeleton for buildings, bridges, and industrial facilities where concrete cannot deliver comparable strength-to-weight ratios. Steel frames dominate commercial project workflows due to faster erection cycles and reduced site labor versus cast-in-place alternatives. Infrastructure applications represent the fastest-expanding demand pool as provincial governments prioritize railway stations, highway interchanges, and utility corridors. Steel plates command concentrated margin pools in energy sector applications including power plant boiler supports and petrochemical processing skids.
MIIT enforces GB standards for structural steel weld quality and fire resistance ratings that fabricators must certify before bidding on state-funded projects. The Ministry of Ecology and Environment (MEE) carbon intensity benchmarks are forcing electric-arc furnace integration and scrap-based production quotas that reshape mill-fabricator supply agreements. China's dual carbon goals mandate embodied carbon disclosures for public construction tenders, creating compliance barriers for smaller shops lacking lifecycle assessment capabilities. Stakeholders must monitor how provincial implementation timelines for these standards will fragment fabrication capacity between certified tier-one suppliers and restructuring regional players.
Market Dynamics
MIIT's tightening GB standards for seismic-resistant steel weld quality are compressing fabrication capacity toward certified tier-one suppliers, forcing provincial restructuring of mid-tier shops unable to meet embodied carbon disclosure mandates for public tenders.
Growth Catalysts
- Western provincial infrastructure megaprojects:Railway stations, highway interchanges, and utility corridors across Sichuan and Shaanxi are absorbing record tonnage of fabricated structural sections.
- Dual carbon goals mandate:Public construction tenders now require embodied carbon disclosures, accelerating demand for electric-arc furnace and scrap-based fabrication partnerships.
- Offshore wind installation surge:Coastal fabrication yards in Jiangsu and Shandong are scaling heavy-gauge beam production for turbine foundation jackets.
Market Restraints
- Hot-rolled coil price volatility:Input cost swings from Baowu Steel Group and other integrated mills compress margin visibility for independent fabricators bidding on fixed-price municipal contracts.
- Coastal yard concentration:Port-adjacent fabrication capacity clusters along the Yangtze River Delta and Bohai Rim, exposing supply chains to typhoon-related logistics disruptions.
- Prefabricated concrete substitution:Modular concrete systems are capturing low-rise commercial and residential frames where speed-to-erection matters less than material cost.
Strategic Opportunities
- Central province fabrication gaps:Henan and Hubei lack sufficient certified structural steel capacity to meet inland infrastructure bond-funded projects, creating first-mover positioning for qualified entrants.
- Building-integrated photovoltaics convergence:Roof truss fabricators combining steel framing with solar mounting systems can capture premium positioning in green building tenders.
- Scrap-based EAF partnerships:MIIT carbon intensity benchmarks incentivize fabricators to secure captive scrap supply agreements with emerging electric-arc furnace operators.
Industry Challenges
- Certified welder scarcity:GB-standard seismic weld qualification programs face bottlenecks, delaying shop certification timelines and constraining qualified production capacity.
- Lifecycle assessment capability gaps:Smaller regional fabricators lack embedded carbon calculation infrastructure to compete for state-funded projects under dual carbon disclosure rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Structural Steel Fabrication Market |
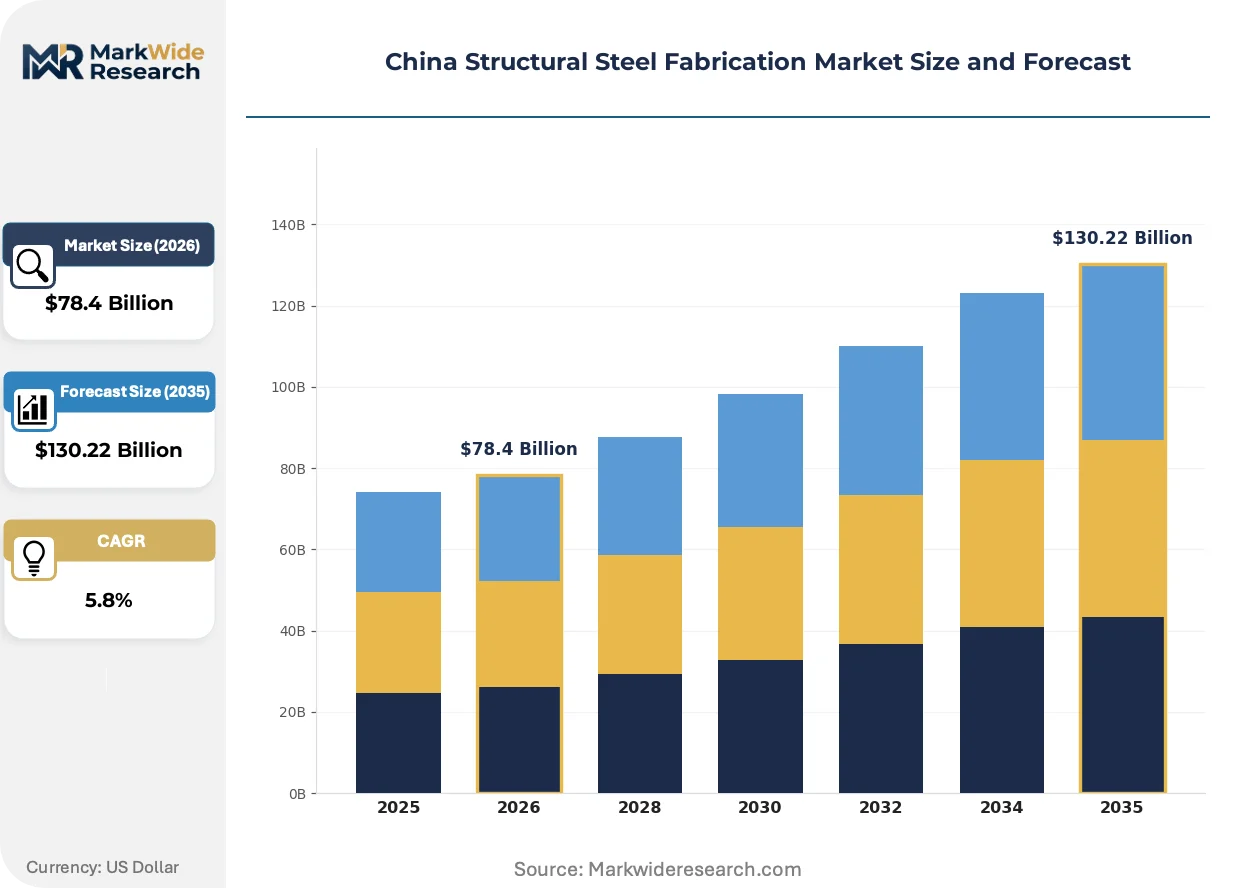
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Beams, Steel Columns, Steel Frames, Steel Plates End User: Construction, Manufacturing, Energy, Transportation Technology: Welding, Cutting, Bending, Assembly Application: Residential Buildings, Commercial Projects, Infrastructure, Industrial Structures |
| Companies Covered | Zhejiang Southeast Space Frame Co., Ltd., Hebei Baofeng Steel Structure Co., Ltd., Baowu Steel Group, China Steel Structure Co. Ltd., Qingdao Havit Steel Structure Co., Ltd., Qingdao Xinguangzheng Steel Structure Co., Ltd., Dongguan Hongye Steel Structure Co., Ltd., Qingdao Wuxiao Group Co., Ltd., ATAD Steel Structure Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Structural Steel Fabrication Market Strategic Shifts
Fabrication workflows are converging with digital quality assurance and automated welding systems, compressing tolerance variance while MIIT environmental benchmarks reshape material sourcing. These forces are redrawing competitive positioning between coastal scale players and technology-focused specialists.
Robotic welding workstations equipped with machine vision are digitizing seam tracking and defect detection in real-time. Stadium and airport roof truss specialists are deploying these systems to reduce rework rates on complex geometries. The technology is digitizing quality documentation chains, enabling direct data feeds into GB-standard compliance portals required for state project bidding.
MIIT carbon intensity benchmarks are forcing electric-arc furnace integration into mill-fabricator supply agreements. Fabricators must now certify scrap-based content percentages before bidding on provincial infrastructure bonds. Heavy-gauge structural sections for energy applications face the steepest compliance ramps, with power plant boiler support fabricators restructuring supplier relationships to meet disclosure thresholds.
Buyers are consolidating fabrication awards around full-service providers capable of design-assist and erection sequencing. Municipal infrastructure agencies in the Yangtze River Delta are abandoning piecemeal component sourcing in favor of integrated frame-and-connection packages. This concentration is most visible in Shanghai megaproject tenders, where single-source accountability for dimensional tolerance and schedule risk commands premium positioning.
China Structural Steel Fabrication Market Segmentation
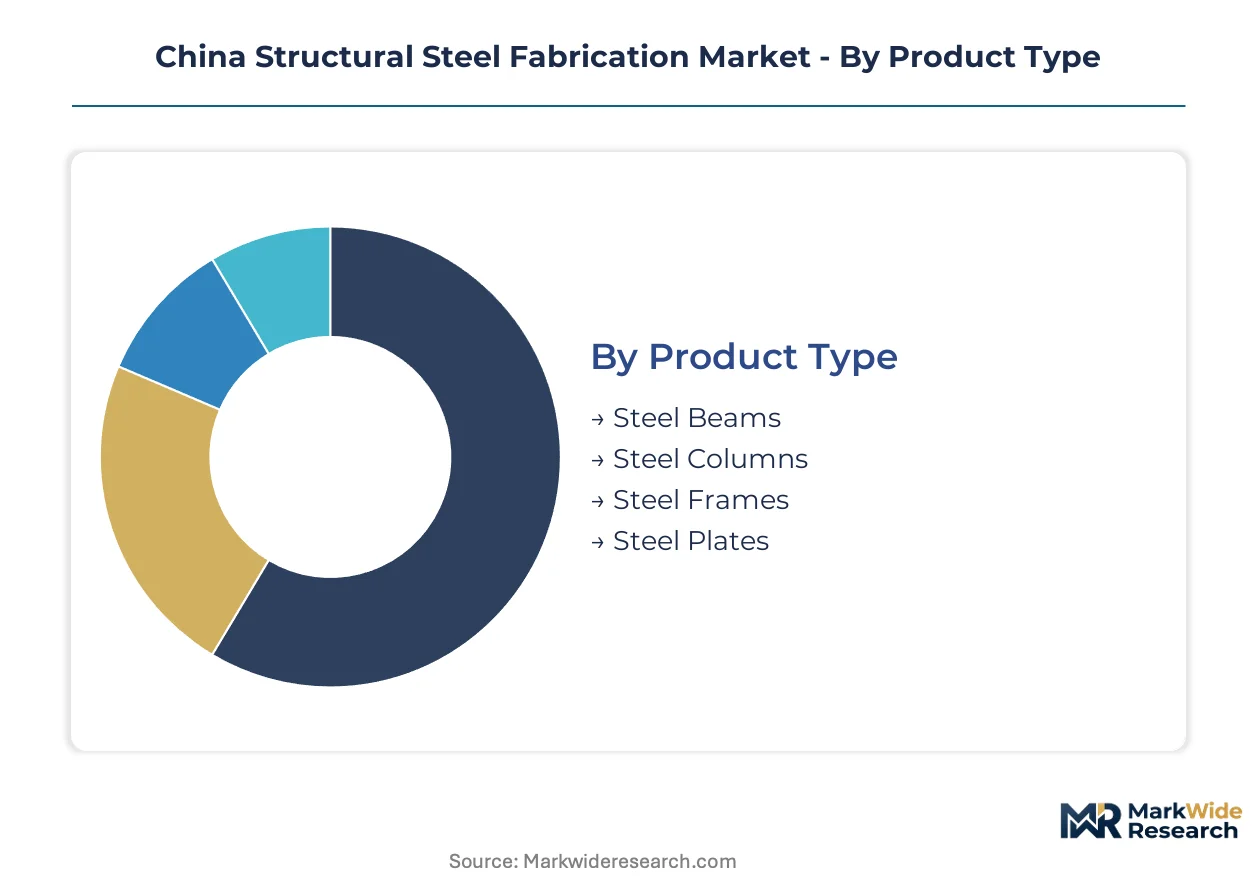
Structural steel fabrication in China fragments across product geometries, end-use intensity, and processing technologies that determine compliance thresholds and margin capture. Understanding these dimensions clarifies where MIIT certification requirements and dual carbon disclosure rules concentrate competitive pressure.
Product Type:
Spanning from linear members to planar systems, product categories align with load-bearing function and fabrication complexity.
- Steel Beams:Hot-rolled I-sections and welded plate girders form the horizontal load-transfer backbone for multi-story frames. Western provincial infrastructure megaprojects across Sichuan and Shaanxi are absorbing record tonnage of welded plate girders for highway interchanges and railway station roofs.
- Steel Columns:Vertical compression members in H-section or box configurations anchor building stability against seismic lateral forces. Box columns with internal diaphragm welding dominate high-rise commercial cores in Shanghai and Shenzhen where GB seismic standards enforce the tightest tolerance bands.
- Steel Frames:Pre-assembled portal and moment-resisting systems reduce field welding and accelerate erection schedules. Modular frame packages are gaining share in Yangtze River Delta logistics warehouses where speed-to-occupancy drives procurement decisions.
- Steel Plates:Flat-rolled sections processed into gusset plates, connection angles, and stiffeners for localized stress distribution. Heavy-gauge plate fabrication concentrates in energy sector boiler supports and petrochemical skids where thickness tolerances command premium positioning.
Established volume favors steel beams; emerging adoption favors steel frames.
End User:
Demand intensity and certification stringency diverge sharply across buyer categories.
- Construction:Commercial and residential building developers represent the dominant demand pool for fabricated structural members. Municipal infrastructure bond flows into western provinces are accelerating beam and column orders for railway stations and utility corridors.
- Manufacturing:Industrial facility builders require heavy-gauge frames for crane-runway buildings and process plant structures. Automotive and electronics manufacturing campuses in Jiangsu are driving demand for wide-span portal frames with integrated mezzanine systems.
- Energy:Power generation and petrochemical infrastructure demands specialized high-strength sections with elevated temperature resistance. Offshore wind turbine foundation jackets from Jiangsu and Shandong coastal yards are climbing the fastest among energy applications.
- Transportation:Bridge and airport terminal constructors specify fracture-critical members with enhanced Charpy toughness ratings. Long-span airport roof trusses for Chengdu and Xi'an expansions are absorbing precision-welded tubular sections from certified tier-one suppliers.
Construction commands current volume dominance; energy exhibits the steepest expansion trajectory.
Technology:
Process capabilities determine which fabricators qualify for state-funded project tiers.
- Welding:Arc and submerged-arc processes join cut sections into specified geometries with certified penetration profiles. Robotic welding workstations with machine vision are compressing rework rates for complex stadium roof trusses.
- Cutting:Plasma, laser, and oxy-fuel systems shape raw sections to dimensional tolerances before assembly. High-definition plasma cutting dominates heavy plate preparation for energy sector boiler supports.
- Bending:Cold and hot forming operations curve linear members into arches and tapered profiles for architectural expression. Curved roof truss segments for airport terminals require CNC-controlled roll bending to maintain structural integrity.
- Assembly:Fit-up and bolting operations integrate welded subcomponents into transportable modules for field erection. Pre-assembly of frame modules in port-adjacent yards reduces offshore wind foundation installation time at sea.
Welding anchors certified supplier status; assembly integration determines project award concentration.
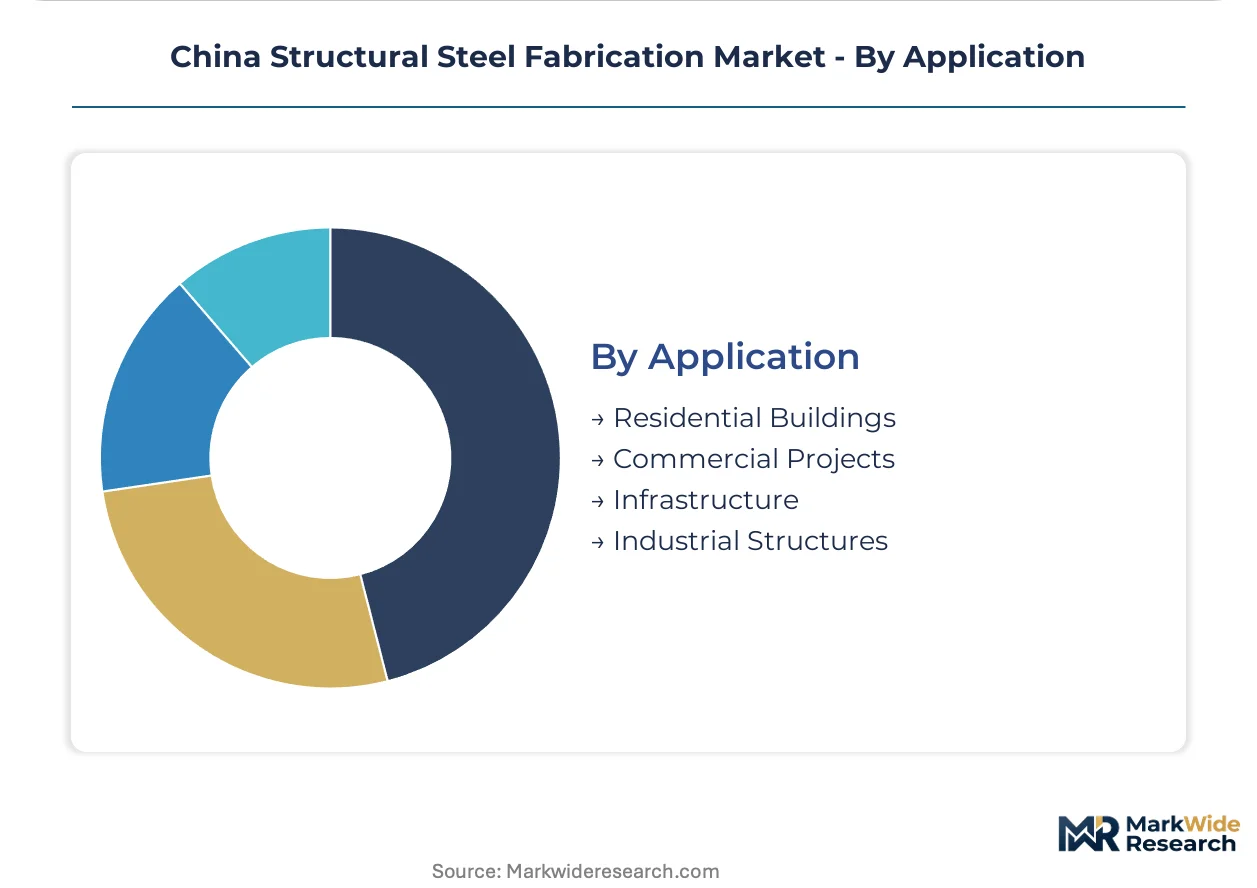
Application:
Building typology dictates performance specifications and embodied carbon disclosure thresholds.
- Residential Buildings:Low-rise housing frames utilize light-gauge cold-formed sections for cost-sensitive projects. Prefabricated concrete substitution is capturing market share in residential mid-rise construction where material cost outweighs speed priorities.
- Commercial Projects:Office towers and retail complexes demand high-strength moment frames for open floor plates. Shanghai megaproject tenders are consolidating awards around full-service providers capable of design-assist and erection sequencing.
- Infrastructure:Railway stations, highway interchanges, and utility corridors absorb the heaviest structural tonnage. Provincial infrastructure bond issuance across western China is accelerating demand for seismic-certified welded sections.
- Industrial Structures:Manufacturing plants and warehouse facilities prioritize wide spans and heavy crane capacity. Logistics corridor development in Henan and Hubei is exposing certified fabrication capacity gaps for inland industrial projects.
Infrastructure leads absolute tonnage; commercial projects concentrate premium-margin fabrication awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal infrastructure agencies and state-owned developers concentrate procurement power across China's provincial clusters, directing fabrication awards toward certified suppliers positioned near bond-funded megaproject sites.
Yangtze River Delta
Shanghai megaprojects and Jiangsu offshore wind installations absorb the heaviest fabricated tonnage in this cluster. MIIT carbon intensity benchmarks force fabricators to certify scrap-based content percentages before bidding on provincial infrastructure bonds. Port-adjacent fabrication yards in Nantong and Taicang reduce beam transport costs to turbine foundation jacket sites.
Pearl River Delta
Shenzhen high-rise commercial cores and Guangzhou airport expansions demand box columns with internal diaphragm welding for seismic performance. GB standards for structural steel weld quality compress capacity toward certified tier-one suppliers in Foshan and Dongguan. Prefabricated frame packages for logistics warehouses concentrate awards around full-service providers with design-assist capabilities.
Beijing-Tianjin-Hebei
State-funded transportation terminals and utility corridors across Hebei drive demand for fracture-critical bridge members. MEE embodied carbon disclosure mandates create compliance barriers for smaller regional shops lacking lifecycle assessment infrastructure. Tianjin port-adjacent yards anchor heavy-gauge section production for power plant boiler supports.
Sichuan-Chongqing
Western provincial railway stations and highway interchanges absorb record tonnage of welded plate girders. Municipal infrastructure bond issuance accelerates beam and column orders for seismic-certified sections. Chengdu fabricators face certified welder scarcity as GB-standard qualification programs encounter bottlenecks.
Shandong Peninsula
Qingdao and Yantai coastal yards scale heavy-gauge beam production for offshore wind foundation jackets. MIIT push for green building materials tightens fabrication tolerances for energy sector applications. Typhoon exposure risks concentrate supply chain vulnerability in this port-dependent cluster.
China Structural Steel Fabrication Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where state project certification requirements fragment the vendor base. Integrated steel mills with captive raw material supply anchor cost positions in heavy-gauge structural sections. Independent fabricators differentiate through precision welding automation or coastal logistics control. Dominant competitive moves include electric-arc furnace partnerships for carbon compliance and pre-assembly integration for design-assist positioning.
Among coastal fabricators, Qingdao Wuxiao Group Co., Ltd. and Qingdao Havit Steel Structure Co., Ltd. occupy positions within the port-adjacent logistics tier, while Zhejiang Southeast Space Frame Co., Ltd. exemplifies the precision-automation specialist archetype for complex roof truss applications.
| Leading Market Players |
|---|
| Zhejiang Southeast Space Frame Co., Ltd. |
| Hebei Baofeng Steel Structure Co., Ltd. |
| Baowu Steel Group |
| China Steel Structure Co. Ltd. |
| Qingdao Havit Steel Structure Co., Ltd. |
| Qingdao Xinguangzheng Steel Structure Co., Ltd. |
| Dongguan Hongye Steel Structure Co., Ltd. |
| Qingdao Wuxiao Group Co., Ltd. |
| ATAD Steel Structure Corporation |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port corridors anchor cost differentiation between coastal fabricators and inland competitors, with Nantong-Taicang logistics advantages compressing delivered pricing for offshore wind foundation jackets while central province buyers absorb 12-18% freight premiums on heavy-gauge sections.
Pricing Analysis
Cost-plus municipal contracts indexed to Baowu Steel Group hot-rolled coil monthly settlements dominate procurement structures for state-funded infrastructure. Price differentiation separates GB-certified seismic weld tier-one suppliers from uncertified regional shops bidding on private commercial frames. Pricing pressure stems from fixed-price bond-funded projects locking fabricators into volatile raw material exposure. Municipal agencies exhibit highest price sensitivity, while energy sector buyers prioritize certified quality over unit cost.
Supply Chain Analysis
Upstream hot-rolled coil and heavy plate feedstock draws from Baowu Steel Group, Shougang, and Ansteel integrated mills concentrated in Hebei and Liaoning. Scrap-based electric-arc furnace billet supplies from emerging Jiangsu and Shandong operators reshape mill-fabricator sourcing agreements under MIIT carbon intensity benchmarks. Single-source vulnerability concentrates in coastal port-adjacent fabrication yards exposed to typhoon logistics disruption. Distribution runs through direct mill-fabricator offtake agreements for state projects, with spot market fragmentation serving private commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated concrete modular systems threaten structural steel substitution in low-rise commercial and residential construction, forcing incumbents to defend through certification moats and integrated service bundling.
For Market Incumbents: Build certification moats around GB-standard seismic weld qualifications and embodied carbon disclosure capabilities. Secure captive electric-arc furnace scrap supply agreements to meet MIIT carbon intensity benchmarks. Expand design-assist and erection sequencing services to capture Shanghai megaproject tenders consolidating around single-source accountability. For New Entrants and Emerging Players: Central province fabrication gaps in Henan and Hubei represent the most penetrable entry point for qualified operators targeting inland infrastructure bond-funded projects. Partner with emerging electric-arc furnace operators for scrap-based supply chain positioning. Lead with building-integrated photovoltaics roof truss convergence to differentiate in green building tenders. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned steel mill fabrication divisions facing MIIT restructuring pressure and dual carbon compliance gaps. Long-term viability centers on certified tier-one positioning with lifecycle assessment infrastructure. Watch provincial implementation timelines for GB-standard welder qualification bottlenecks as inflection indicators for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Arc Furnace Partnership | MIIT carbon benchmarks force scrap-based supply restructuring for state project eligibility. |
| Robotic Welding Automation | Machine vision systems compress rework rates for complex stadium and airport roof trusses. |
| Design-Assist Service Expansion | Shanghai megaproject tenders consolidate awards around integrated frame-and-connection packages. |
| Central Province Capacity Buildout | Infrastructure bond flows into Henan and Hubei expose certified fabrication supply gaps. |
| Building-Integrated Photovoltaics Convergence | Roof truss fabricators combining steel framing with solar mounting capture green tender premiums. |
Study Parameters
Cross-validation between fabricator procurement directors and municipal infrastructure agency engineers anchors the qualitative findings in operational reality. Primary interviews with GB-standard welding certification program administrators, electric-arc furnace operations managers, and offshore wind EPC contractors combined with secondary validation from MIIT policy circulars, MEE carbon intensity disclosure filings, and provincial infrastructure bond issuance databases. Bottom-up project pipeline assessments and top-down steel consumption forecasts triangulate market sizing.
Calibration against historical tonnage absorption patterns across product geometries and end-use applications shapes the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end-user intensity, processing technology, and application typology with embodied carbon disclosure thresholds. CAGRs derive from regression analysis of infrastructure investment flows and steel intensity coefficients. Forecast inputs incorporate MIIT welder qualification program expansion rates and provincial dual carbon implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in municipal bond issuance volumes and hot-rolled coil price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding GB-standard certification penetration and scrap-based supply chain restructuring. Cross-checking against China Iron and Steel Association production data and provincial infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Glue Laminated Beams Market
Structural Construction
Bridge Bearings Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Steel Beam Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Bridge Construction Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Girder Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market