
 Steel Beam Market | 2026-2036
Steel Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Beam Market Insights
Market Context
Buyer consolidation among mega-project developers is restructuring procurement patterns across commercial construction. ArcelorMittal leverages its integrated mining-to-distribution model to secure multi-year supply agreements with consolidated buyers. Nucor Corporation anchors its position through electric arc furnace flexibility that responds faster to volatile order books. Tata Steel differentiates via specialized high-strength beam grades for seismic-zone specifications in South Asian infrastructure.
Technical Definition and Segment Structure
Steel beams are structural load-bearing members, typically hot-rolled from carbon or alloy steel billets into standardized cross-sectional profiles with yield strengths ranging from 250 MPa to 550 MPa, engineered to resist bending, shear, and axial forces in buildings, bridges, and industrial frameworks. H-Beams dominate volume in multi-story construction due to their superior moment-resisting capacity and efficient concrete composite action, while I-Beams retain primacy in industrial mezzanine and retrofit applications where weight minimization governs design. High Strength Steel grades command expanding share in long-span infrastructure as engineers push column-free spans beyond conventional limits, though Carbon Steel maintains cost-driven dominance in residential and light commercial verticals.
Regulatory Frame and Outlook
China's SAMR enforces GB/T 11263 for hot-rolled H-section steel with escalating traceability requirements, while India's BIS mandates IS 2062 certification for structural steel used in government-funded projects, effectively filtering import access. The EU's Construction Products Regulation and CE marking requirements for structural steel components create compliance cost tiers that favor producers with in-house testing laboratories. Stakeholders must monitor how evolving embodied-carbon disclosure rules in European public procurement reshape material-grade preferences and supplier qualification thresholds.
Market Dynamics
Mega-project developers in the Middle East are consolidating procurement into fewer but larger contracts, forcing producers to restructure sales operations around bundled supply agreements rather than spot-market transactions. China's GB standards for structural steel are tightening weld-quality requirements, adding compliance costs that filter smaller mills from premium-grade segments.
Growth Catalysts
- India's western corridor infrastructure:Demand concentrates from Mumbai to Gujarat as port connectivity and industrial zone expansion accelerate beam consumption for logistics hubs and manufacturing facilities.
- GB/T 11263 weld-quality escalation:China's SAMR mandates enhanced traceability for hot-rolled H-section steel, pushing domestic mills toward automated inspection systems that improve yield consistency.
- High-strength steel adoption:Engineers specify grades above 460 MPa yield strength for long-span bridges and column-free commercial floors, expanding the addressable premium segment.
Market Restraints
- Iron ore and scrap price volatility:Input cost swings of 30-40 percent within single quarters compress mill margins and destabilize contract pricing negotiations.
- Chinese supply concentration:Over 55 percent of global H-beam capacity sits in Hebei and Jiangsu provinces, creating regional disruption risk from environmental shutdown mandates.
- Cross-laminated timber substitution:Mass timber gains building code approval for mid-rise residential in North America and Europe, displacing steel framing in select verticals.
Strategic Opportunities
- Saudi Arabia's NEOM and Red Sea projects:Giga-developments require multi-year supply commitments that favor producers with captive raw material and logistics integration.
- EU embodied-carbon disclosure rules:Public procurement mandates for Environmental Product Declarations create first-mover advantage for mills with electric arc furnace and renewable energy configurations.
- Seismic-zone specialization:Japan's METI and California's building codes drive demand for ductile beam grades with enhanced energy dissipation capacity.
Industry Challenges
- Welding technician certification backlog:China's new GB standards require recertification of fabrication crews, creating project delays at peak construction seasons.
- CE marking laboratory capacity:European producers face 12-16 week queues for third-party structural steel testing, constraining speed-to-market for new product grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Beam Market |
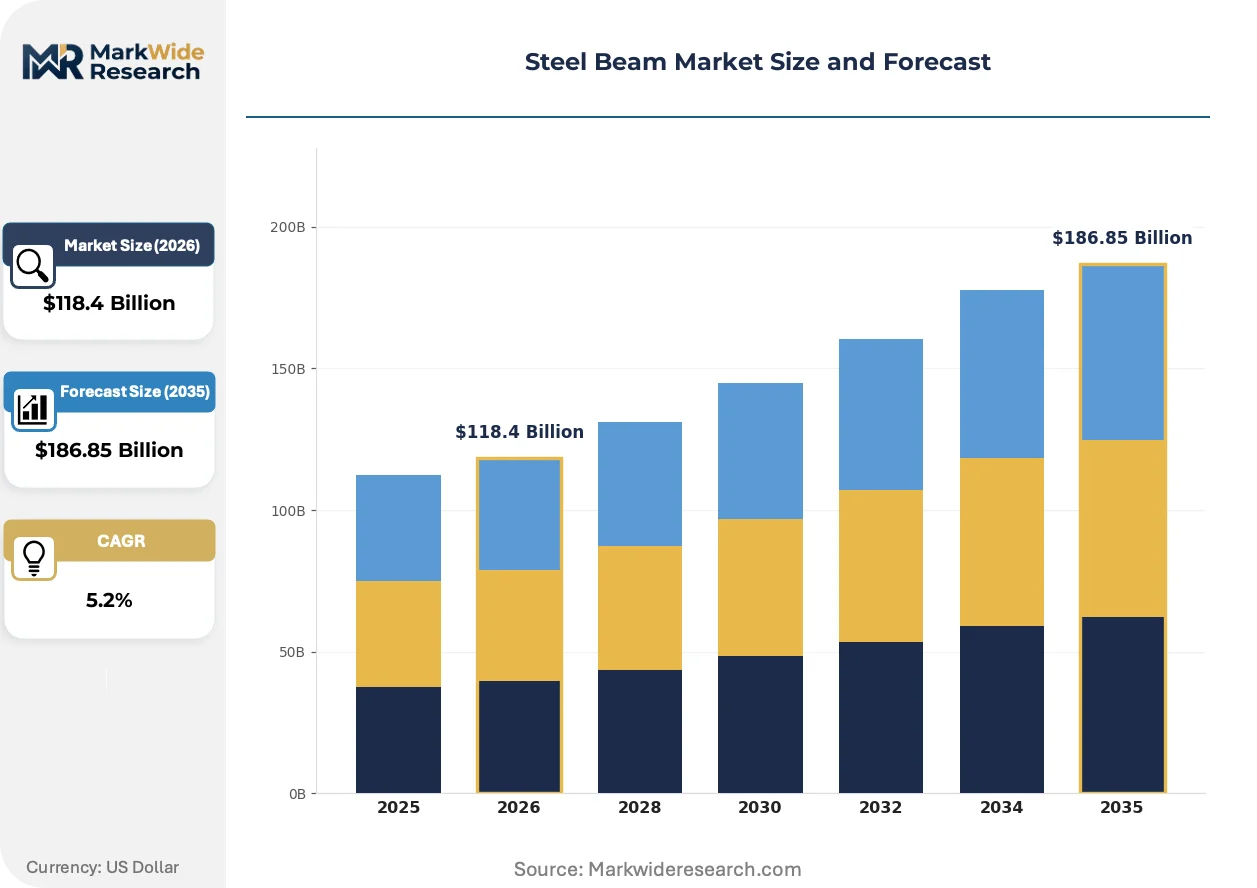
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $186.85 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: I-Beams, H-Beams, T-Beams, Channel Beams End Use: Construction, Infrastructure, Industrial, Marine Material Grade: Structural Steel, High Strength Steel, Carbon Steel, Alloy Steel Manufacturing Process: Hot Rolled, Cold Rolled, Welded, Cut-To-Length |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, Tata Steel, Nucor Corporation, POSCO, China Baowu Steel Group, JSW Steel, Thyssenkrupp AG, United States Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Beam Market Trends and Innovations
Digital fabrication and sustainability mandates are converging to reshape how steel beams are specified, produced, and delivered across construction value chains. These shifts favor integrated producers with data infrastructure and low-carbon process credentials.
Building information modeling is integrating directly with automated beam cutting and drilling lines, enabling fabrication shops to receive machine-ready files from structural engineers without intermediate detailing stages. Infrastructure contractors in Germany and Japan are adopting this workflow fastest, compressing project timelines by three to four weeks on complex steel frames.
The EU's Construction Products Regulation now requires CE-marked structural components to include declared environmental performance data, affecting import eligibility from non-EU mills. Producers in Turkey and India are investing in ISO 14025-compliant EPD programs to maintain access to Dutch and German public works tenders.
Developer procurement teams are consolidating annual steel requirements into single-source framework agreements with volume guarantees and fixed-price escalators, displacing traditional spot purchasing through distributors. This pattern is most visible in Saudi Arabia's Public Investment Fund projects and India's National Highways Authority contracts.
Steel Beam Market Segmentation
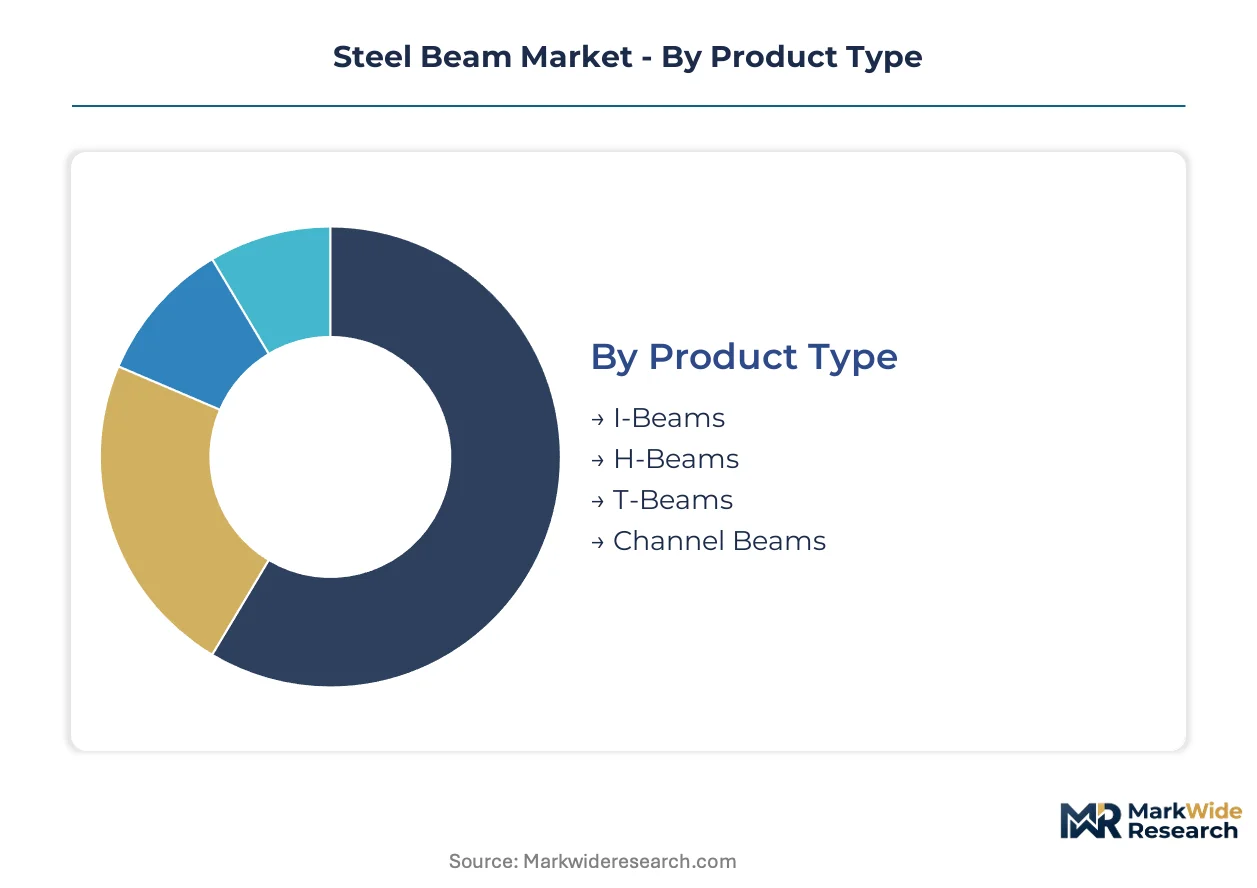
Steel beam procurement patterns diverge sharply across product geometry, end-use specifications, and compliance regimes. Certification requirements from China's SAMR, India's BIS, and the EU's CPR create tiered qualification barriers that reshape competitive access within each segment.
Product Type:
GB/T 11263 certification for hot-rolled H-sections imposes automated inspection mandates that favor capital-intensive producers, while I-beam specifications under ASTM A6 allow broader mill participation.
- H-Beams:Wide-flange profiles engineered for superior moment-resisting capacity in multi-story construction. Demand concentrates in India's western corridor from Mumbai to Gujarat as logistics hub construction accelerates, with Chinese environmental shutdowns in Hebei province periodically disrupting supply.
- I-Beams:Tapered-flange sections optimized for weight minimization in industrial mezzanine and retrofit applications. North American mass timber code approvals are displacing steel framing in mid-rise residential verticals, constraining volume expansion in select geographies.
- T-Beams:Asymmetric profiles serving bridge deck and precast concrete composite systems, common in Japan's seismic-zone infrastructure.
- Channel Beams:U-section members for equipment framing and secondary structural supports, prevalent in German industrial construction.
H-Beams sits at the top of the volume ranking, with T-Beams climbing the fastest in seismic-specialist markets.
End Use:
Cost stratification across application tiers separates premium infrastructure specifications from commoditized residential procurement.
- Construction:Multi-story commercial and residential framing requiring IS 2062 certification for Indian government-funded projects. Saudi Arabia's NEOM and Red Sea giga-developments are consolidating procurement into multi-year framework agreements with volume guarantees.
- Infrastructure:Long-span bridges and transportation corridors driving adoption of grades above 460 MPa yield strength. EU embodied-carbon disclosure rules in public procurement favor mills with electric arc furnace configurations.
- Industrial:Manufacturing facilities and warehouse frameworks where automated beam cutting lines compress project timelines.
- Marine:Offshore platforms and port structures demanding corrosion-resistant alloy formulations.
Construction commands the largest revenue pool, while Infrastructure gains share fastest on high-strength grade premiums.
Material Grade:
Margin structures vary dramatically by metallurgical complexity and testing laboratory access.
- Structural Steel:Standard carbon-manganese grades governed by IS 2062 and GB/T 700 specifications, dominant in Indian and Chinese residential verticals.
- High Strength Steel:Microalloyed grades exceeding 460 MPa yield for column-free commercial floors and long-span bridges. Japan's METI and California building codes drive ductile beam specifications with enhanced energy dissipation capacity.
- Carbon Steel:Cost-driven grades for light commercial and residential applications where BIS certification filters import competition.
- Alloy Steel:Chromium and nickel-enhanced formulations for marine and extreme climate exposure, requiring specialized heat treatment protocols.
Structural Steel maintains volume leadership, with High Strength Steel expanding most quickly on engineering specification upgrades.
Manufacturing Process:
Supply chain configuration determines speed-to-market and carbon intensity positioning.
- Hot Rolled:Continuous casting and rolling from billets at temperatures above 950°C, producing standardized profiles for bulk construction. Hebei and Jiangsu provinces concentrate over half of global H-beam capacity, creating regional disruption risk.
- Cold Rolled:Room-temperature forming of thinner-gauge sections with tighter dimensional tolerances for precision industrial applications.
- Welded:Plate assembly into custom profiles, with China's GB standards tightening weld-quality requirements and recertification backlogs delaying peak-season projects.
- Cut-To-Length:Service center processing of mill-length sections into project-specific dimensions, integrating with BIM-to-fabrication workflows in Germany and Japan.
Hot Rolled dominates tonnage throughput, with Cut-To-Length gaining traction fastest on digital fabrication adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hebei province concentrates over half of global H-beam capacity, while India's western corridor from Mumbai to Gujarat is accelerating beam consumption for logistics infrastructure. Regulatory divergence between these markets is reshaping supplier qualification requirements.
China
Hebei and Jiangsu provinces host the majority of domestic H-beam mills, though environmental shutdown mandates periodically disrupt supply. SAMR enforces GB/T 11263 with escalating automated inspection requirements for hot-rolled sections. Tianjin's port cluster serves as the primary export hub for Southeast Asian infrastructure contracts.
India
The Mumbai-Gujarat corridor drives concentrated demand for logistics hubs and manufacturing facilities. BIS mandates IS 2062 certification for all government-funded structural steel projects, filtering import access. JSW Steel and Tata Steel anchor production in Maharashtra and Odisha respectively.
United States
Nucor Corporation leverages electric arc furnace flexibility across the Southeast and Midwest to respond to volatile order books. OSHA welding standards and AISC certification requirements govern fabrication quality. Texas and Georgia industrial zones absorb significant beam volume for warehouse construction.
Germany
The Construction Products Regulation requires CE-marked structural components with declared environmental performance data. Ruhr Valley producers face 12-16 week queues for third-party testing laboratory capacity. Bavaria's industrial construction sector favors precision-cut channel beams for equipment framing.
Saudi Arabia
NEOM and Red Sea giga-developments consolidate procurement into multi-year framework agreements with volume guarantees. SFDA-equivalent building codes and PIF procurement standards favor suppliers with captive raw material integration. Jeddah's fabrication yards are expanding to meet peak-season demand.
Steel Beam Market Competitive Landscape
Chinese producers anchor the volume tier through concentrated Hebei-Jiangsu capacity; European and Japanese specialists hold premium-grade positions through certification-intensive workflows. The market structure is consolidating around bundled supply agreements rather than spot-market transactions. Three archetypes dominate: integrated mining-to-distribution conglomerates, electric arc furnace flex operators, and seismic-specialist high-strength grade producers. Competitive moves center on captive raw material integration and multi-year framework contracting with mega-project developers.
Within the integrated conglomerate tier, ArcelorMittal and China Baowu Steel Group exemplify upstream-controlled positioning. Nucor Corporation occupies a distinctive position as an electric arc furnace operator with rapid response capabilities. Tata Steel represents the seismic-specialist vector through its focus on high-strength grades for South Asian infrastructure specifications. These three anchors illustrate how process configuration and geographic clustering determine competitive access to premium contract tiers.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| Tata Steel |
| Nucor Corporation |
| POSCO |
| China Baowu Steel Group |
| JSW Steel |
| Thyssenkrupp AG |
| United States Steel Corporation |
| Others |
Pricing and Supply Chain Analysis
Iron ore and scrap metal feedstock volatility cascades through mill pricing tiers as Hebei province's concentrated H-beam capacity creates asymmetric bargaining power between Chinese producers and consolidated Middle Eastern buyers. Contract structures now embed quarterly price escalators that transfer input cost swings downstream, while spot-market discounts widen during environmental shutdown periods when regional supply tightens.
Pricing Analysis
Capacity additions in Saudi Arabia's Jeddah fabrication corridor are reshaping price floors for premium-grade structural steel across the Gulf Cooperation Council procurement pool. Three-tier pricing structure across premium, standard, and economy levels separates seismic-certified ductile grades from commodity carbon steel and import-restricted IS 2062 certified tonnage. Pricing pressure stems from Chinese environmental mandates that periodically constrain Hebei mill output, forcing spot buyers toward higher-cost alternative sourcing. Mega-project developers with multi-year framework agreements exhibit lowest price sensitivity, while light commercial contractors in volatile order-book environments face compressed margins from rapid input cost pass-through.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Arabia's Public Investment Fund and India's National Highways Authority mandate qualification of at least two certified mills per contract, fragmenting procurement across Hebei, Jiangsu, Maharashtra, and Odisha production clusters. Raw material dependencies rest on Australian iron ore fines, Turkish scrap metal flows, and Indonesian nickel alloys for corrosion-resistant grades. Single-source vulnerability concentrates in Hebei province where over half of global H-beam capacity faces unscheduled environmental compliance shutdowns. Distribution runs through Tianjin port consolidation for Southeast Asian export markets and direct mill-to-site logistics for Indian western corridor infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's SAMR enforcement of GB/T 11263 weld-quality traceability and India's BIS IS 2062 certification mandates are restructuring supplier qualification thresholds and consolidating procurement toward integrated producers.
For Market Incumbents: Acquire automated inspection systems and in-house metallurgical testing laboratories to defend premium-grade positioning against emerging electric arc furnace operators with faster carbon-intensity credentials. Cement multi-year framework agreements with Saudi Arabia's NEOM and Red Sea giga-developments before new mill capacity enters the Gulf market. Cross-laminated timber substitution in North American mid-rise residential verticals and mass timber code approvals in European jurisdictions threaten traditional steel framing volumes, requiring incumbents to deepen seismic-specialist grade differentiation. For New Entrants and Emerging Players: Launch via cut-to-length service center partnerships that integrate with German and Japanese BIM-to-fabrication workflows, bypassing capital-intensive hot-rolling capacity requirements. Target India's western corridor logistics hub construction where BIS certification barriers filter import competition but local fabrication capacity remains undersupplied. Penetrate through specialized high-strength grades above 460 MPa yield strength for long-span bridge specifications where engineering specification upgrades outpace incumbent capacity expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental compliance costs and automated inspection mandates filter smaller mills from premium-grade segments, creating acquisition opportunities for distressed Chinese provincial producers. Prioritize electric arc furnace configurations with renewable energy sourcing that align with EU embodied-carbon disclosure rules and Dutch-German public procurement EPD requirements. Monitor Hebei province environmental shutdown frequency as the inflection indicator for regional supply disruption and margin expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Iron Ore | ArcelorMittal secures raw material cost stability for multi-year Middle Eastern supply agreements. |
| Automated Weld Inspection Deployment | Chinese mills meet SAMR GB/T 11263 traceability mandates and filter smaller competitors from premium segments. |
| ISO 14025 EPD Certification Program | Turkish and Indian producers maintain access to Dutch and German public works tenders under EU CPR requirements. |
| Seismic-Grade Metallurgical R&D Investment | Tata Steel captures specification premiums from Japan's METI and California building code ductility requirements. |
| BIM-Integrated Cut-to-Length Service Expansion | German and Japanese fabricators compress project timelines by eliminating intermediate detailing stages. |
Research Methodology
Multiple input streams — executive interviews with steel mill procurement directors, primary fieldwork with infrastructure contractor engineering teams, and regulatory filing analysis — were reconciled against customs trade databases and BIS certification registries. Conversations with Saudi PIF project managers, Indian NHAI contract officers, and German Ruhr Valley fabrication shop owners supplied demand-side validation. Secondary sources included SAMR GB standard publications, EU Construction Products Regulation guidance documents, and SEC 10-K disclosures from listed producers. Bottom-up volume modeling from segment-grade consumption patterns and top-down macro construction spend projections were triangulated for convergence.
Data-stream reconciliation across product geometry, material grade, manufacturing process, and end-use application dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from regression analysis against historical construction spend elasticities and infrastructure investment pipeline visibility. Modeled inputs incorporated Hebei province environmental shutdown probability distributions, Indian western corridor logistics hub completion schedules, and EU embodied-carbon disclosure rule implementation phasing.
Several conditions sit outside the modeled scope, including unscheduled Chinese provincial environmental mandates beyond historical frequency patterns, abrupt shifts in mass timber building code approvals in North American jurisdictions, and geopolitical disruptions to Australian iron ore export flows. Forecasts reflect documented assumptions regarding SAMR enforcement consistency and BIS certification processing timelines. Deviation in Chinese environmental policy stringency or Indian infrastructure appropriation pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Bridge Bearings Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Global Rebar Splice Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
South Korea Construction Market
Structural Construction
Supported Scaffolding Market
Structural Construction
H Beam Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
North America Structural Steel Fabrication Market