
 United Arab Emirates Structural Steel Fabrication Market | 2026-2036
United Arab Emirates Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Structural Steel Fabrication Market Insights
Aftermarket service revenue is narrowing as a distinct margin pool as fabricators integrate installation and maintenance into original contracts. Emirates Steel Fabrication leverages its captive rolling capacity to control input costs across beam and column production. Mabani Steel LLC anchors its position through specialized plate fabrication for energy sector clients. Arabian International Company Ras Al Khaimah competes on geographic reach, operating fabrication yards closer to northern emirates project sites.
Structural steel fabrication encompasses the cutting, welding, drilling, and surface treatment of hot-rolled or welded sections to produce load-bearing members for buildings and infrastructure, with typical yield strengths ranging from 250 MPa to 355 MPa per UAE-specific material grades. Beams and columns command the largest share of product output due to repetitive demand from high-rise construction, while modular installation is gaining traction as developers compress project schedules through off-site assembly. Plates serve industrial and maritime applications where thicker sections and specialized coatings resist corrosive environments.
MOHAP enforces fire resistance ratings and structural integrity standards for steel assemblies in occupied buildings, while the Emirates Authority for Standardization and Metrology governs material certification and traceability. These frameworks elevate compliance costs for smaller fabricators but create barrier-to-entry advantages for accredited producers. Stakeholders must monitor evolving green building mandates and embodied carbon disclosure requirements that will reshape procurement criteria for government-backed developments.
Market Dynamics
Mega-project construction in Dubai and Abu Dhabi is compressing project timelines and forcing fabricators to adopt modular assembly methods. This schedule pressure is restructuring contract terms and eroding the traditional separation between fabrication and installation services.
Growth Catalysts
- MOHAP Fire and Life Safety Code amendments:Tighter material certification requirements are filtering out unaccredited suppliers and concentrating demand among compliant fabricators with traceable supply chains.
- Energy infrastructure corridors:Specialized plate fabrication for oil, gas, and renewable energy projects is absorbing excess capacity from commercial construction slowdowns.
- Modular installation methods:Off-site assembly is accelerating project delivery and expanding the addressable market for pre-fabricated structural systems.
Market Restraints
- Hot-rolled steel input volatility:Fluctuations in global steel pricing compress margins for fabricators without captive rolling capacity or long-term supply agreements.
- Emirates Authority for Standardization and Metrology certification costs:Material traceability and testing requirements impose fixed compliance burdens that disadvantage smaller fabricators.
- Reinforced concrete substitution:Lower initial cost and established local supply chains for concrete continue to capture mid-rise residential and institutional projects.
Strategic Opportunities
- Ras Al Khaimah and northern emirates project concentration:Geographic expansion of fabrication yards closer to emerging construction clusters reduces logistics costs and bid response times.
- Green building mandates and embodied carbon disclosure:Upcoming government procurement criteria will favor fabricators with verified environmental product declarations and low-carbon steel sourcing.
- Digital fabrication convergence:Integration of building information modeling with automated cutting and welding equipment is enabling mass customization at scale.
Industry Challenges
- Welder certification and specialized trade skills:Shortages of certified welders for high-strength steel assemblies constrain output capacity during peak construction cycles.
- MOHAP compliance timeline compression:Accelerated project schedules conflict with mandatory fire resistance testing and documentation review periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Structural Steel Fabrication Market |
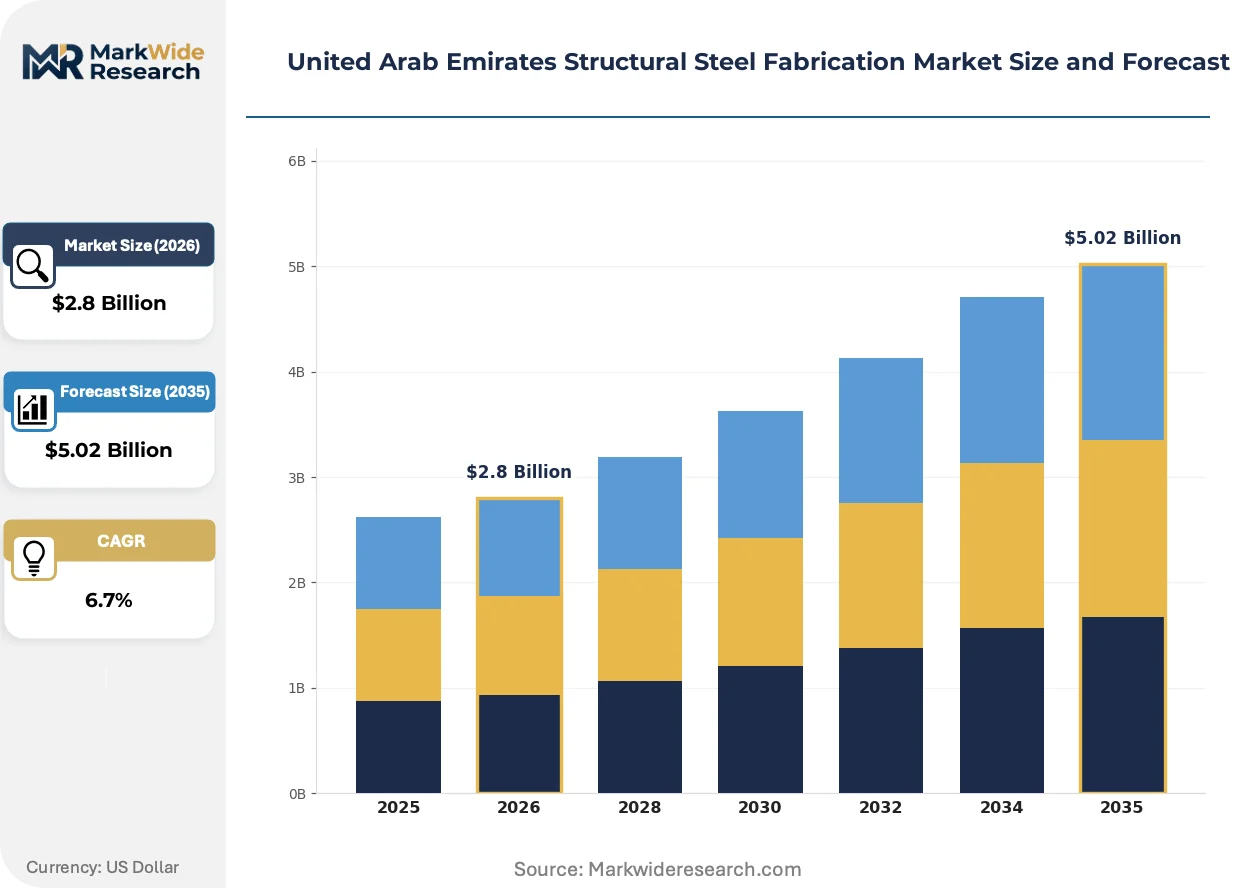
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Columns, Frames, Plates Application: Construction, Infrastructure, Industrial, Maritime End User: Contractors, Developers, Government, Fabricators Installation: On-site, Off-site, Modular, Custom |
| Companies Covered | Arabian International Company Ras Al Khaimah, Mabani Steel LLC, IMCC, Standard Steel Fabrication Co LLC, Techno Steel, Al Habtoor Steel Fabrication, Emirates Steel Fabrication, Al Dhabi Steel LLC, Standard Fabrication and Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Structural Steel Fabrication Market Trends and Innovations
Digital workflows and sustainability mandates are restructuring how structural steel moves from raw material to installed building component. These forces are compressing traditional project phases and introducing new performance criteria into procurement decisions.
Building information modeling is migrating from design visualization into fabrication floor control systems. Contractors in Dubai's high-rise commercial sector are mandating BIM-to-fabrication data handoffs. This technology shift is eliminating rework and enabling just-in-time steel delivery to congested urban sites.
MOHAP amendments to the UAE Fire and Life Safety Code are elevating fire resistance ratings for structural steel assemblies. Fabricators must now document intumescent coating thickness and thermal performance through third-party testing. Commercial tower developers are responding by specifying pre-certified assemblies earlier in design development.
Integrated design-build contracts are consolidating procurement authority with fewer decision-makers. General contractors in Abu Dhabi's energy infrastructure sector are absorbing fabrication selection into early-phase vendor qualification. This concentration is visible in lump-sum turnkey awards where fabricators assume installation risk alongside production scope.
United Arab Emirates Structural Steel Fabrication Market Segmentation
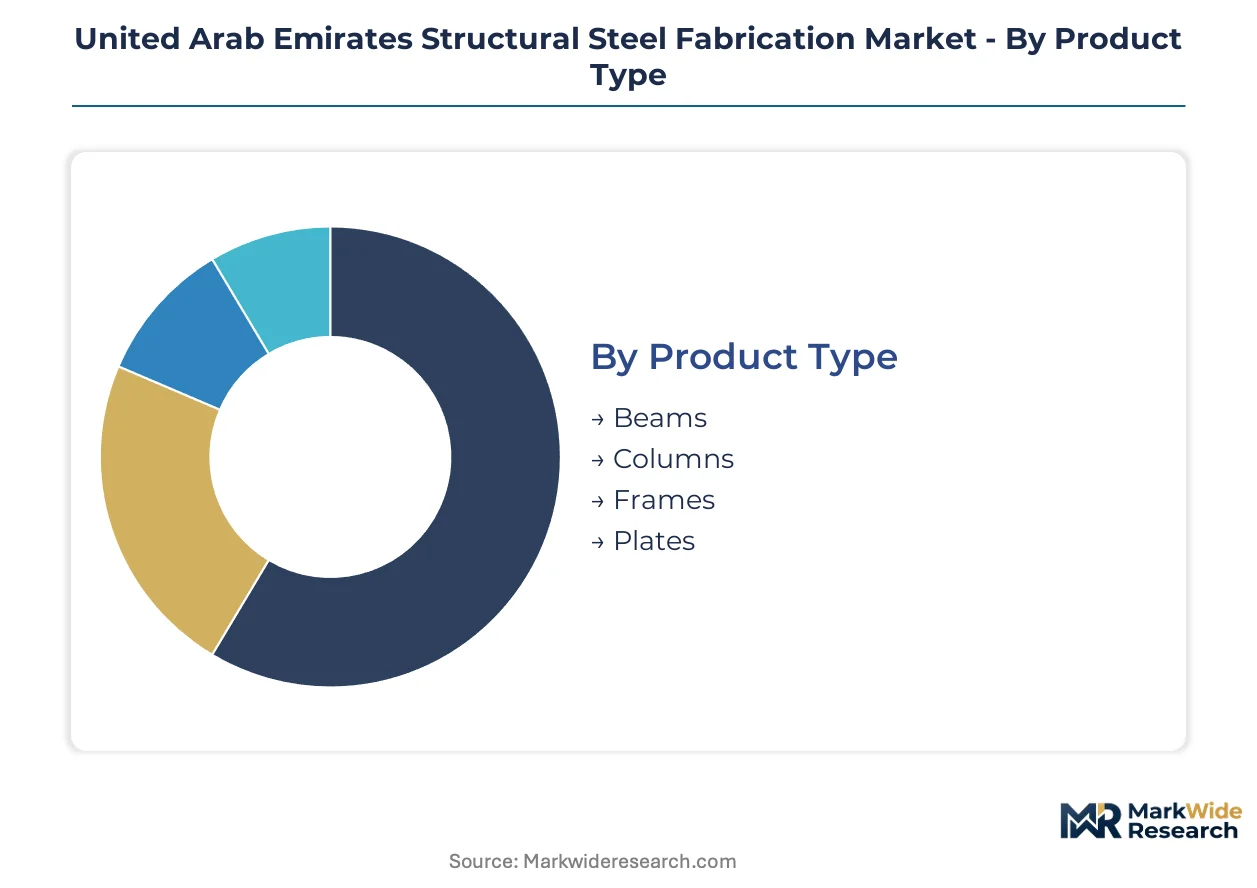
Segmentation in UAE structural steel fabrication reveals how demand concentrates across product geometries, project delivery methods, and procurement authority. Understanding these divisions exposes where margin pools form and where compliance burdens shift.
Product Type:
Mature segments dominate volume throughput while emerging geometries capture premium positioning through specialized certification requirements.
- Beams:Hot-rolled I-sections and H-sections with yield strengths of 250-355 MPa form the backbone of high-rise commercial towers. Dubai's mega-project pipeline absorbs repetitive beam production runs, though welder certification bottlenecks constrain peak-cycle output.
- Columns:Box sections and built-up profiles resist compressive loads in mid-rise and high-rise construction. Abu Dhabi government-backed developments specify these for fire-rated assemblies under MOHAP amendments, tightening supplier qualification thresholds.
- Frames:Portal and moment-resisting frame systems for industrial warehousing.
- Plates:Thick-section plate for energy infrastructure and maritime applications.
Beams handle the majority of throughput; Plates is expanding most quickly on share as energy corridor investments accelerate.
Application:
Cost tier stratification separates high-complexity, specification-heavy projects from standardized, price-sensitive procurement.
- Construction:Commercial towers and mixed-use developments in Dubai and Abu Dhabi compress schedules through design-build delivery. General contractors bundle fabrication and installation risk, eroding traditional service boundaries.
- Infrastructure:Bridges, transport terminals, and utility structures require extended corrosion protection warranties. Emirates Authority for Standardization and Metrology traceability mandates elevate documentation costs for these long-life assets.
- Industrial:Manufacturing facilities and process plants in northern emirates.
- Maritime:Port infrastructure and offshore support structures.
Construction commands the dominant revenue position; Infrastructure is gaining share fastest as federal investment corridors mature.
End User:
Customer type determines contract structure, with procurement authority concentrating among integrated delivery vehicles.
- Contractors:General and specialty contractors in Dubai's high-rise sector absorb fabrication selection into early-phase vendor qualification. Lump-sum turnkey awards transfer installation risk to fabricators, compressing margin visibility.
- Developers:Master developers in Abu Dhabi specify pre-certified steel assemblies during design development to accelerate MOHAP compliance timelines.
- Government:Federal and emirate-level procurement for public buildings and infrastructure.
- Fabricators:Tier-2 fabricators purchasing semi-finished components for downstream processing.
Contractors drive the largest contract volume; Government procurement is climbing the fastest as sovereign development pipelines expand.
Installation:
Volume concentration favors methods that reduce site labor and compress project schedules in congested urban environments.
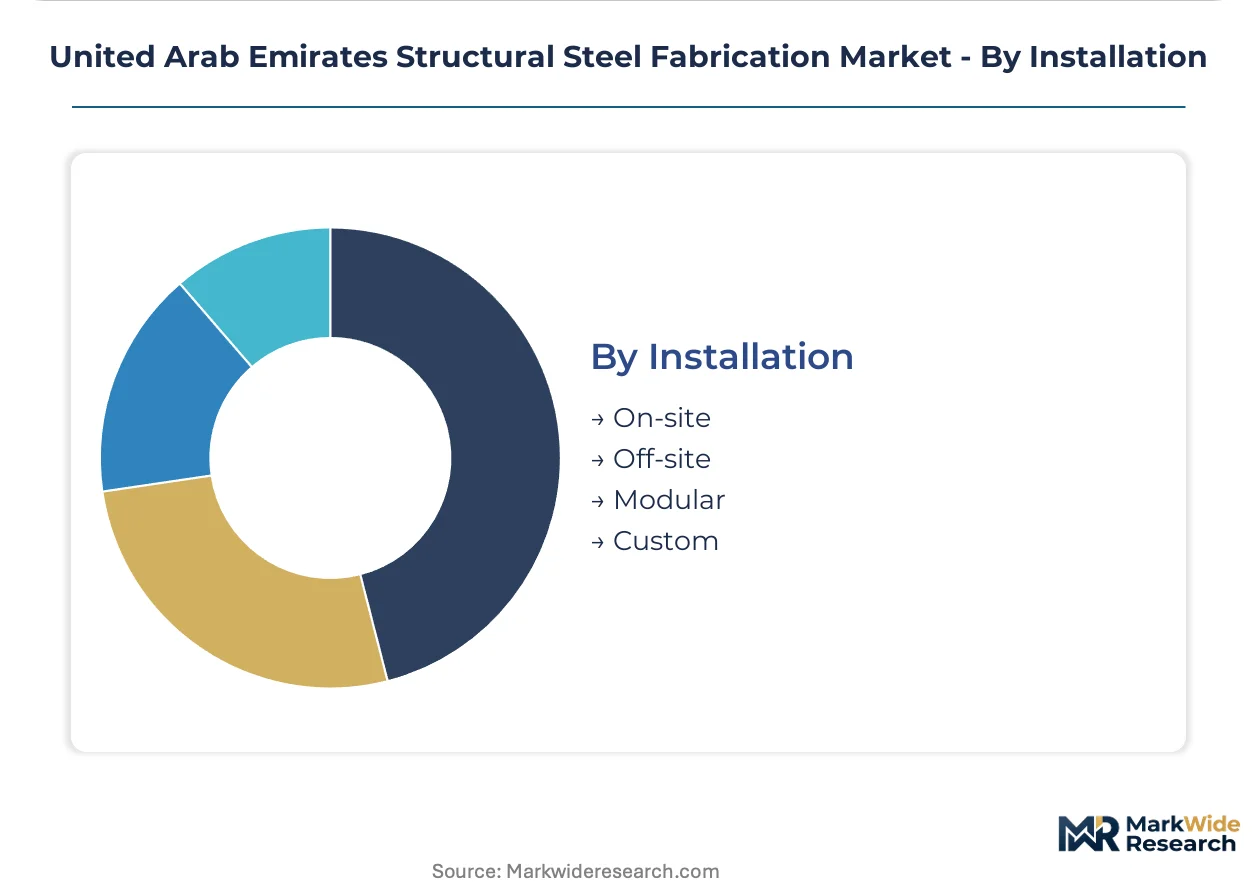
- On-site:Traditional stick-built erection persists for remote projects and complex geometries where transport economics favor field welding. Northern emirates project sites with limited modular yard access rely on this method.
- Off-site:Controlled-facility fabrication with just-in-time delivery to Dubai's constrained construction zones. BIM-to-fabrication data handoffs eliminate rework and coordinate steel arrival with crane availability.
- Modular:Pre-assembled structural modules for repetitive building typologies.
- Custom:Bespoke fabrication for signature architectural or specialized industrial requirements.
On-site retains the largest installed base; Modular is advancing fastest as developers prioritize schedule certainty over first-cost minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the UAE emirates. Dubai and Abu Dhabi buyers prioritize schedule certainty and certification compliance over unit pricing, while northern emirates procurement remains acutely price-sensitive with thinner specification requirements.
Dubai
High-rise commercial towers and mega-project construction absorb the majority of premium-grade structural steel output. MOHAP fire resistance mandates compress vendor qualification timelines, filtering contracts toward pre-certified fabricators. The Jebel Ali industrial corridor hosts concentrated fabrication capacity serving Dubai's compressed construction schedules.
Abu Dhabi
Federal infrastructure investment and sovereign development pipelines anchor steel consumption for energy and government buildings. The Emirates Authority for Standardization and Metrology enforces material traceability standards that elevate documentation burdens. Khalifa Industrial Zone fabrication yards position close to major project clusters.
Sharjah
Mid-rise industrial warehousing and logistics facilities drive standardized beam and column demand with thinner margin profiles. Cost competition from unaccredited suppliers pressures compliant fabricators to absorb certification overhead. The Hamriyah Free Zone concentrates lower-tier fabrication serving price-sensitive procurement.
Northern Emirates
Ras Al Khaimah and Fujairah project sites rely on traditional on-site erection due to limited modular yard access and transport economics. Geographic distance from Dubai fabrication centers creates logistics cost premiums that disadvantage schedule-sensitive developments. Local fabrication capacity expansion is narrowing bid response gaps.
United Arab Emirates Structural Steel Fabrication Market Competitive Landscape
Capability concentration sits with tier-one integrated producers; scale advantage sits with specialized plate fabricators serving energy corridors. The vendor base stratifies across three tiers: captive rolling mills with backward integration, regional specialists with geographic anchoring, and project-specific job shops competing on price. Strategic moves center on modular assembly integration and northern emirates yard expansion to compress logistics lead times.
Among UAE-based fabricators, Emirates Steel Fabrication exemplifies the integrated tier with captive rolling capacity, while Mabani Steel LLC occupies the specialized energy-sector position, and Arabian International Company Ras Al Khaimah anchors geographic proximity advantages in northern emirates markets.
| Leading Market Players |
|---|
| Arabian International Company Ras Al Khaimah |
| Mabani Steel LLC |
| IMCC |
| Standard Steel Fabrication Co LLC |
| Techno Steel |
| Al Habtoor Steel Fabrication |
| Emirates Steel Fabrication |
| Al Dhabi Steel LLC |
| Standard Fabrication and Engineering |
| Others |
Pricing and Supply Chain Analysis
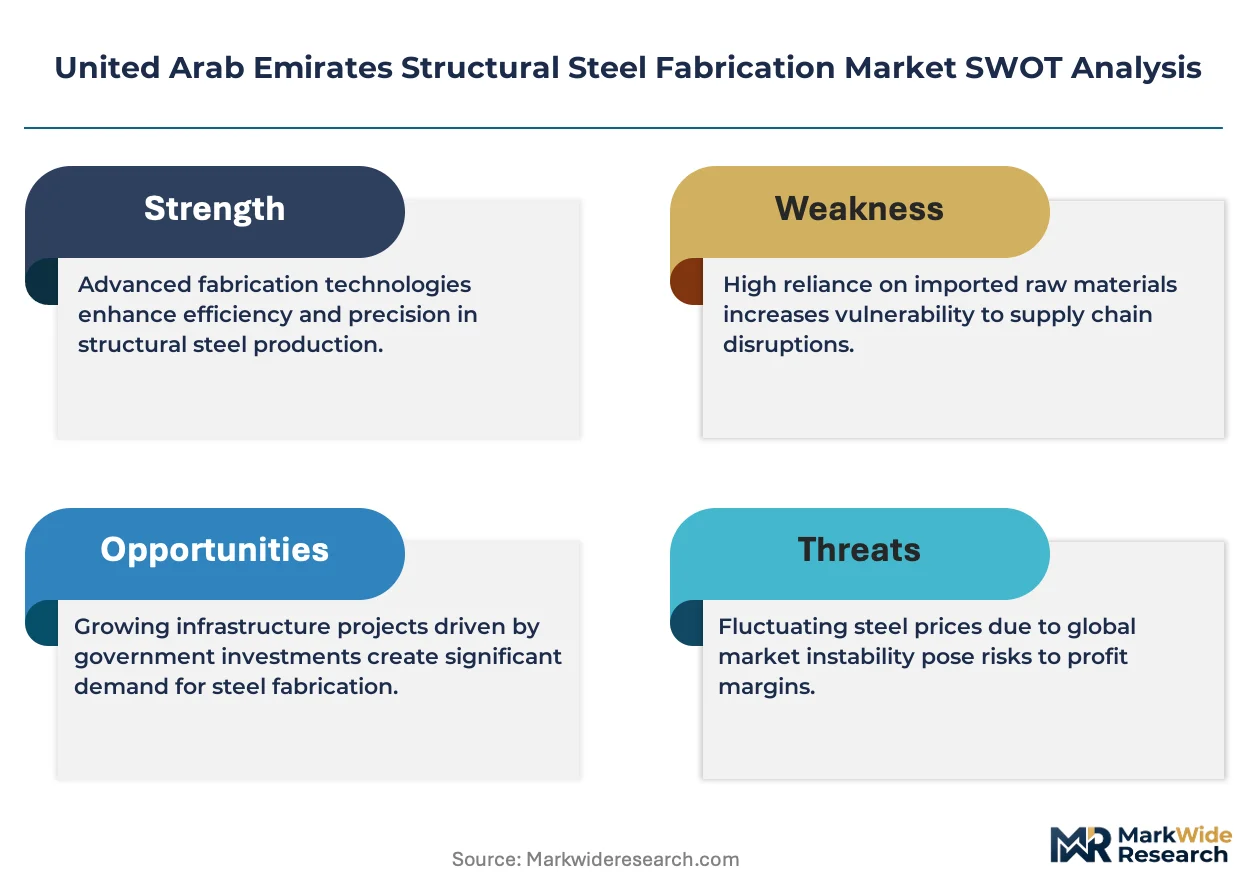
Overcapacity in Dubai's Jebel Ali fabrication corridor compresses contract margins while simultaneously accelerating consolidation toward pre-certified suppliers with traceable steel sourcing. This utilization imbalance rewards Emirates Steel Fabrication's captive rolling capacity with input cost stability while squeezing job-shop competitors on spot-market hot-rolled purchases.
Pricing Analysis
Project-based lump-sum contracts dominate high-rise commercial procurement in Dubai, transferring installation risk to fabricators and collapsing traditional service boundaries. Price differentiation rests on MOHAP fire-resistance certification tier and geographic delivery proximity to congested urban sites. Pricing pressure stems from reinforced concrete substitution in mid-rise residential developments. Government-backed Abu Dhabi buyers exhibit lowest price sensitivity; Sharjah industrial warehousing procurement shows highest.
Supply Chain Analysis
Tariff exposure between China and the UAE on specialty plate grades elevates input cost volatility for energy-sector fabricators without long-term offtake agreements. Geographic supply concentration centers on domestic Emirates Steel rolling capacity, Saudi billet imports, and Chinese plate shipments. Raw material dependencies include hot-rolled coil, heavy plate, and zinc coating inputs. Single-source vulnerability persists for high-strength grades above 355 MPa. Distribution runs through just-in-time delivery coordination with crane scheduling at Dubai construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Abu Dhabi sovereign developers and Dubai design-build contractors, fragmenting traditional fabricator-customer relationships into bundled procurement vehicles. This consolidation compresses margin visibility and elevates qualification barriers for non-integrated suppliers.
For Market Incumbents: Build certification moats around MOHAP pre-approval status for fire-rated assemblies. Acquire welder training capacity to relieve peak-cycle bottlenecks. Expand modular yard footprint into Ras Al Khaimah to compress logistics lead times against geographic competitors. Cement backward integration into coating application to capture margin pool from third-party surface treatment.
For New Entrants and Emerging Players: Build out specialized plate fabrication capacity serving northern emirates energy infrastructure corridors. Target maritime and offshore support structures where specification requirements filter out unaccredited competition. Penetrate through pre-certified assembly packages that accelerate developer compliance timelines. Anchor go-to-market strategy through EPC contractor early-phase vendor qualification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated cutting and welding equipment as BIM-to-fabrication convergence accelerates. Long-term viability favors fabricators with verified environmental product declarations ahead of green procurement mandates. Acquisition targets should display captive rolling relationships or specialized energy-sector positioning. Monitor Emirates Authority for Standardization and Metrology enforcement intensity as inflection signal for compliance-cost barrier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Yard Expansion | Geographic proximity to Ras Al Khaimah project clusters reduces logistics premiums and bid response times. |
| Backward Integration into Coating | In-house intumescent application captures margin from third-party surface treatment and accelerates MOHAP compliance. |
| Welder Certification Pipeline | Captive training capacity relieves peak-cycle output constraints from certified high-strength steel assembly shortages. |
| Environmental Product Declaration | Verified low-carbon steel sourcing positions for upcoming Abu Dhabi green procurement criteria. |
| BIM-to-Fabrication Data Handoff | Automated cutting and welding equipment integration enables mass customization at scale for compressed Dubai schedules. |
Research Methodology
A spread of perspectives from fabrication plant managers, EPC contractor procurement leads, MOHAP compliance officers, and steel trading desk analysts converged on the working assumptions. Primary fieldwork combined structured interviews with operational stakeholders across Dubai, Abu Dhabi, and Ras Al Khaimah fabrication yards. Secondary validation drew from Emirates Authority for Standardization and Metrology certification databases, UAE customs trade statistics, SEC filings of listed steel producers, and project development tracking systems. Bottom-up capacity utilization estimates triangulated against top-down construction spend projections.
Demand-supply balance modeling anchored volume forecasts across the analysis window. Segmentation dimensions included product geometry, application complexity tier, end-user procurement authority, and installation method. CAGRs derived from elasticity-adjusted construction pipeline absorption rates. Industry-specific inputs incorporated MOHAP amendment implementation timelines and energy infrastructure corridor investment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive modular assembly adoption by Dubai developers or accelerated green procurement mandates in Abu Dhabi would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Canada Composite Repair Market
Structural Construction
Bridge Bearings Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
H Beam Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market