
 Russia Transportation Infrastructure Construction Market | 2026-2036
Russia Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Transportation Infrastructure Construction Market Analytics
A widening capital-intensity divergence between players is redrawing competitive tiers in Russia's transportation infrastructure construction sector. MOSTOTREST leverages its specialized bridge engineering heritage to dominate complex river-crossing contracts across the Volga basin. ENKA sustains a diversified portfolio spanning highway, rail, and airport development, allowing it to navigate cyclical public spending shifts. Russian Highways anchors the federal road network through direct state backing and priority access to sovereign project pipelines.
Russia transportation infrastructure construction encompasses the design, engineering, and building of roads, bridges, railways, and airports using materials such as reinforced concrete, structural steel, and polymer-modified asphalt with design lives typically spanning 50-100 years for major structures. Its primary purpose is to enable reliable movement of freight and passengers across Russia's vast territory while supporting economic connectivity between industrial centers and export corridors. Road and railway project types currently absorb the majority of public capital allocation due to their scale and network completeness mandates. Smart construction technology is gaining traction fastest among segments as contractors deploy GPS-guided earthmoving and drone-based progress monitoring to compress schedules on remote Siberian sites. Concrete remains the dominant material type by volume, though steel competes aggressively in bridge superstructures where longer spans reduce foundation counts.
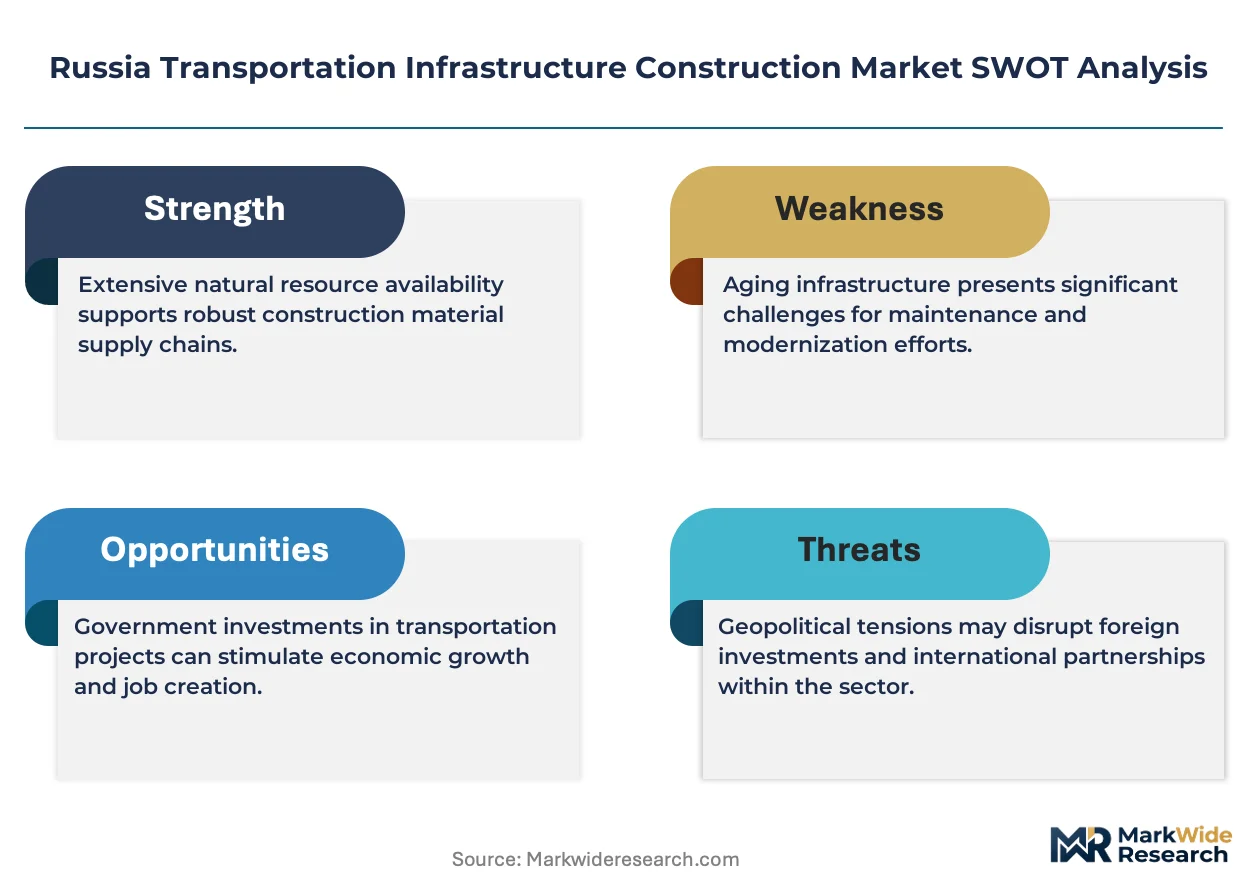
Russia's Federal Antimonopoly Service oversees competitive tendering under the Contract System Law, while GOST standards administered by Rosstandart govern material specifications and structural safety requirements for all federally funded works. Regional transport ministries layer additional procurement rules that shape contractor eligibility and bonding requirements, particularly for projects exceeding one billion rubles in value. Stakeholders must monitor how sanctions-driven equipment import restrictions reshape technology choices and domestic substitution timelines for critical construction machinery.
Market Dynamics
Federal procurement mandates under Russia's Contract System Law are compressing contractor margins while simultaneously accelerating technology substitution timelines for sanctioned equipment categories. This regulatory pressure is fragmenting the vendor base between state-backed incumbents and agile regional specialists.
Growth Catalysts
- Trans-Siberian cold-chain modernization:Freight operators are expanding temperature-controlled corridor investments along Russia's primary east-west rail artery. This infrastructure supports agricultural export growth to Asian markets.
- Central Federal District ring-road expansion:Moscow's orbital highway network requires continuous capacity upgrades to accommodate commercial vehicle volumes. Federal budget allocations prioritize this corridor completion.
- GOST-R certification harmonization:Rosstandart's material standardization reduces technical barriers for domestic suppliers. Unified specifications accelerate project approval timelines across federal subjects.
Market Restraints
- Equipment import substitution costs:Sanctions-driven restrictions on European and Japanese construction machinery force contractors toward unproven domestic alternatives. Replacement timelines extend project schedules by 15-25%.
- Polymer-modified asphalt supply concentration:Specialty binder production clusters in the Volga Federal District. Transportation costs to Siberian and Far Eastern sites inflate material budgets disproportionately.
- Arctic construction seasonality:Permafrost regions limit viable construction windows to 90-120 days annually. Foundation engineering complexity multiplies capital requirements per kilometer.
Strategic Opportunities
- High-speed rail corridor development:The Moscow-Kazan route represents Russia's first genuine high-speed passenger infrastructure. Design contracts for 400 km/h track systems remain contested.
- Drone-based progress monitoring:Remote Siberian sites increasingly deploy unmanned aerial systems for earthwork verification. This technology convergence reduces survey crew requirements by 60%.
- Northwest Federal District port access roads:St. Petersburg's container terminal expansion requires connecting highway capacity. Regional transport ministry tenders prioritize foreign-trade corridor completion.
Industry Challenges
- Geotechnical engineering talent scarcity:Permafrost foundation design requires specialized expertise concentrated in academic institutes. Contractor recruitment struggles against hydrocarbon sector compensation benchmarks.
- Smart construction system integration:GPS-guided earthmoving equipment must interface with legacy project management platforms. Data format incompatibilities delay real-time scheduling optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Transportation Infrastructure Construction Market |
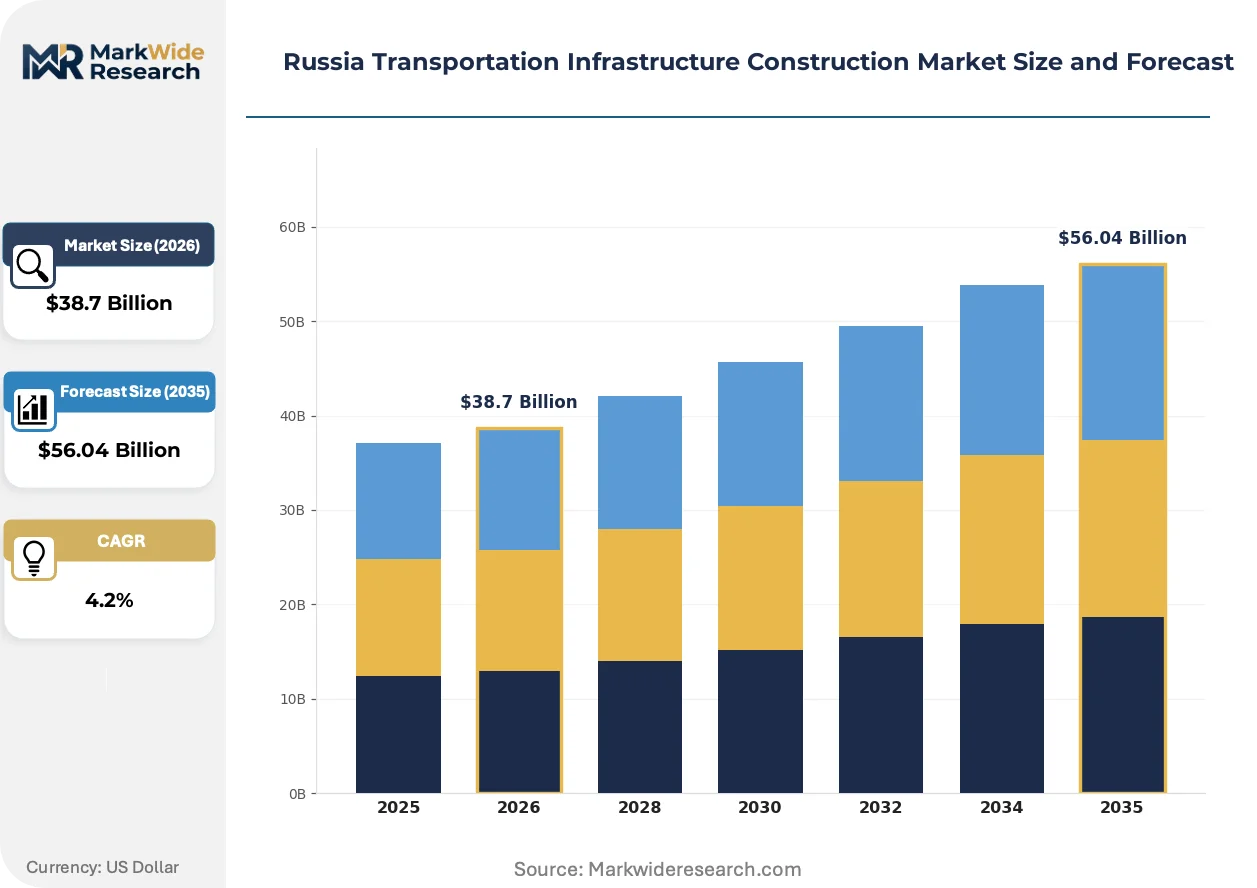
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Road, Bridge, Railway, Airport Material Type: Concrete, Steel, Asphalt, Composite Technology: Building Information Modeling, Smart Construction, Modular Construction, Green Technology End User: Government, Private Sector, Contractors, Investors |
| Companies Covered | ENKA, MOSTOTREST, Mosproekt-3, RZD International, AVTOBAN, Russian Highways, AO Institute Stroyproekt, Transstroy, Aecon Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Transportation Infrastructure Construction Market Evolving Landscape
Digital construction workflows are compressing traditional design-bid-build timelines while simultaneously elevating precision requirements for earthwork and structural placement. Contractors face capability investments in sensor networks and machine control systems to remain eligible for federal tender participation.
Polymer-modified asphalt formulations incorporating recycled tire rubber are fragmenting traditional petroleum-based supply relationships. Regional road agencies in the Volga and Southern Federal Districts specify these blends for heavy-traffic corridors. The technology is enabling domestic waste-stream valorization while reducing temperature susceptibility in extreme climate zones.
Russia's Federal Antimonopoly Service enforcement of competitive tendering under the Contract System Law is restructuring procurement eligibility criteria. Contractors must now demonstrate BIM competency and quality management system certification to qualify for projects exceeding one billion rubles. The Southern Federal District's transport infrastructure program has adopted these requirements most aggressively, excluding traditional low-bid specialists.
Consolidated maintenance contracting is displacing fragmented repair procurement across federal highway networks. Russian Highways and regional operators are bundling 10-15 year lifecycle responsibility into single-source agreements. This shift is most visible in the Central Federal District, where ring-road asset management contracts now incorporate predictive analytics and automated defect detection.
Russia Transportation Infrastructure Construction Market Segmentation
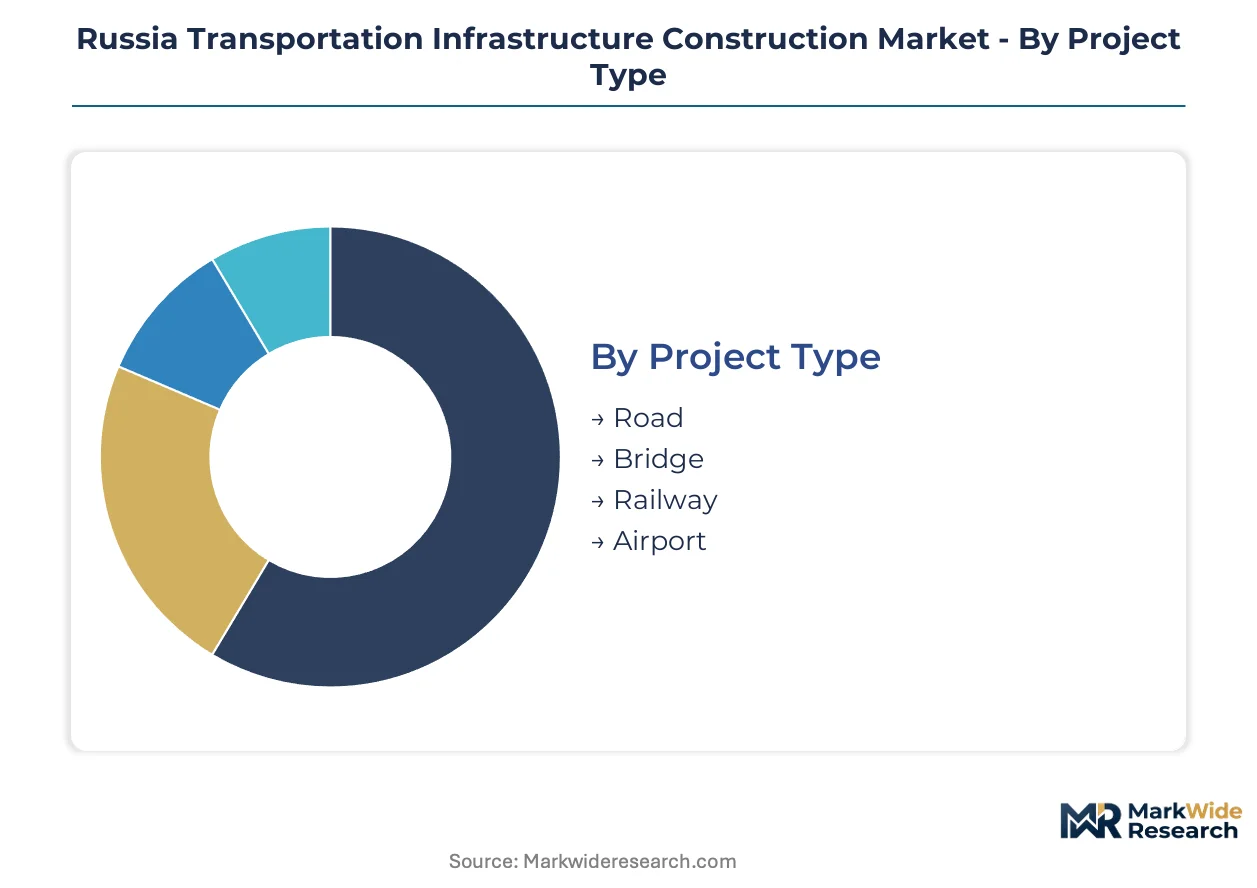
Russia's transportation infrastructure construction market segments along four critical dimensions that determine contractor capability requirements and procurement eligibility. Project type and material selection govern capital intensity and technical specialization, while technology adoption and end-user structure shape competitive positioning under federal tender mandates.
Project Type:
Railway and airport segments face the strongest substitution pressure from modular prefabrication methods that compress traditional cast-in-place construction timelines.
- Road:Highway and arterial road construction employs polymer-modified asphalt and reinforced concrete pavement systems designed for 50-year service lives. Demand concentrates in the Central Federal District around Moscow's ring-road expansion, driven by federal budget prioritization of orbital highway capacity upgrades. Road construction retains volume leadership; railway holds the steepest expansion curve.
- Bridge:River-crossing structures utilize steel superstructures for spans exceeding 200 meters, reducing foundation counts in permafrost zones. The Volga basin generates concentrated demand for complex bridge engineering, with MOSTOTREST leveraging specialized heritage to dominate this segment. Bridge contracts require GOST-certified welding protocols and geotechnical expertise concentrated in academic institutes.
- Railway:Track systems encompass conventional lines and emerging high-speed corridors. The Moscow-Kazan route represents Russia's first 400 km/h passenger infrastructure, with design contracts contested among specialized consortia.
- Airport:Runway and terminal construction demands precision grading and specialized pavement formulations for heavy aircraft loading. Regional hub modernization in the Northwest Federal District drives tender activity.
Road construction commands the largest share of federal capital allocation; high-speed railway development is gaining share fastest.
Material Type:
Cost tier stratification separates commodity materials from performance-engineered alternatives, with asphalt and steel occupying distinct procurement channels.
- Concrete:Reinforced concrete dominates by volume across foundations, pavements, and structural elements, with GOST-R certification harmonization accelerating domestic supplier qualification. The material's thermal mass properties suit permafrost foundation design in Arctic construction windows limited to 90-120 days annually.
- Steel:Structural steel competes aggressively in bridge superstructures and long-span applications, with longer spans reducing foundation counts in challenging geologies. Specialty grades face import substitution pressures under sanctions-driven equipment restrictions.
- Asphalt:Petroleum-based binders serve standard applications; polymer-modified formulations incorporating recycled tire rubber fragment traditional supply relationships in heavy-traffic Volga and Southern Federal District corridors.
- Composite:Fiber-reinforced polymer materials address corrosion resistance in aggressive climates, though domestic production capacity remains concentrated in import-dependent channels.
Concrete maintains absolute volume dominance; polymer-modified asphalt variants are expanding most quickly.
Technology:
Application maturity varies sharply, with BIM now mandatory for large tenders while smart construction systems face integration friction with legacy platforms.
- Building Information Modeling:BIM competency is mandatory for federal projects exceeding one billion rubles under Contract System Law enforcement by the Federal Antimonopoly Service. The Southern Federal District has adopted these requirements most aggressively, excluding traditional low-bid specialists from eligibility.
- Smart Construction:GPS-guided earthmoving and drone-based progress monitoring compress schedules on remote Siberian sites, reducing survey crew requirements by 60%. Data format incompatibilities with legacy project management platforms delay real-time optimization.
- Modular Construction:Prefabricated bridge elements and precast concrete components accelerate installation in seasonally constrained Arctic windows.
- Green Technology:Low-carbon concrete formulations and energy-efficient lighting systems respond to emerging federal sustainability procurement criteria.
BIM represents the baseline qualification threshold; smart construction systems are climbing the fastest.
End User:
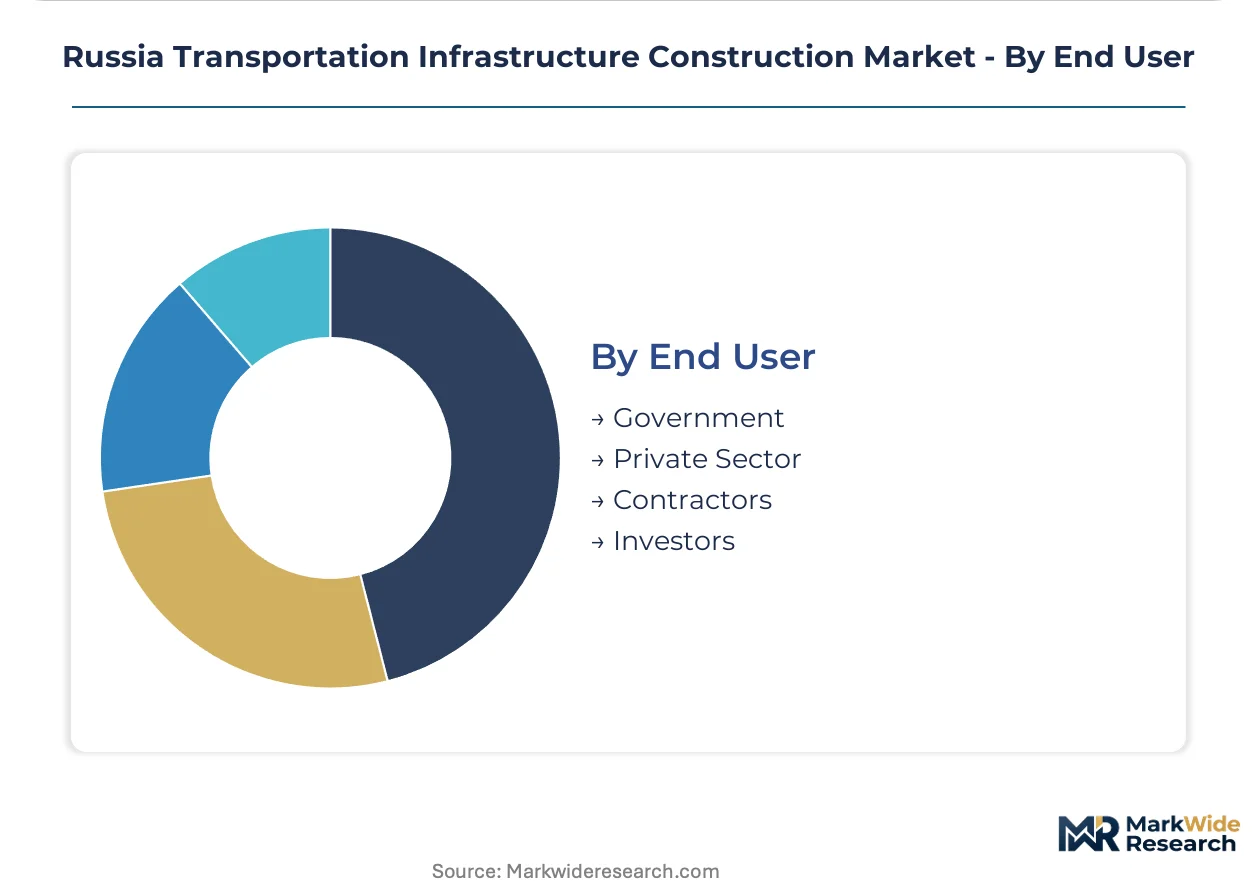
Customer type concentration reflects Russia's state-directed infrastructure investment model, with government procurement shaping contractor specialization.
- Government:Federal and regional transport ministries allocate capital through competitive tendering under the Contract System Law, with Russian Highways anchoring sovereign project pipelines through direct state backing.
- Private Sector:Freight logistics operators fund cold-chain corridor investments along the Trans-Siberian route, supporting agricultural export growth to Asian markets.
- Contractors:Construction firms bid as prime contractors or consortium members, with consolidated maintenance contracting displacing fragmented repair procurement across federal highway networks.
- Investors:Infrastructure investment vehicles and development finance institutions participate in long-term asset management agreements incorporating predictive analytics.
Government procurement retains absolute volume leadership; private freight operator investment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import logistics flows through Russia's federal districts are reshaping capital allocation priorities. The Central Federal District absorbs the largest share of road and rail investment due to Moscow's ring-road expansion and high-speed rail planning. Regional transport ministries layer procurement rules that govern contractor eligibility for projects exceeding one billion rubles.
Central Federal District
Moscow's orbital highway network drives continuous capacity upgrades for commercial vehicle volumes. The Federal Antimonopoly Service enforces competitive tendering under the Contract System Law for all federally funded works. The Moscow-Kazan high-speed rail corridor represents Russia's first 400 km/h passenger infrastructure, with design contracts contested among specialized engineering consortia.
Volga Federal District
River-crossing bridge demand concentrates in the Volga basin, requiring complex steel superstructures for spans exceeding 200 meters. Rosstandart's GOST-R certification harmonization accelerates material standardization across federal subjects. Specialty polymer-modified asphalt production clusters here, though transportation costs to remote sites inflate material budgets disproportionately.
Siberian Federal District
Freight logistics operators are expanding cold-chain corridor investments along the Trans-Siberian rail artery to support agricultural export growth to Asian markets. Permafrost foundation design limits viable construction windows to 90-120 days annually, multiplying capital requirements per kilometer. GPS-guided earthmoving and drone-based progress monitoring compress schedules on remote sites, reducing survey crew requirements.
Northwest Federal District
St. Petersburg's container terminal expansion requires connecting highway capacity for foreign-trade corridor completion. Regional transport ministry tenders prioritize port access roads under consolidated maintenance contracting models. BIM competency mandates for projects exceeding one billion rubles have been adopted most aggressively here, excluding traditional low-bid specialists from eligibility.
Far Eastern Federal District
Arctic construction seasonality and permafrost geotechnical complexity constrain foundation engineering options. The Federal Law on the Contract System mandates competitive tendering for state infrastructure contracts across this export-gateway region. Domestic substitution timelines for sanctioned construction machinery extend project schedules by 15-25% as contractors shift from European and Japanese equipment.
Russia Transportation Infrastructure Construction Market Competitive Landscape
Concentration sits with state-backed incumbents possessing direct sovereign pipeline access. The vendor base stratifies between specialized bridge engineering heritage holders and diversified highway-rail-airport portfolio operators. Three archetypes dominate: federal road network anchors with priority state backing, complex infrastructure specialists leveraging academic geotechnical expertise, and diversified EPC contractors navigating cyclical public spending shifts. Competitive moves center on consolidated maintenance contracting bundling 10-15 year lifecycle responsibility, and BIM competency certification to qualify for large tender participation.
Among the named players, ENKA and MOSTOTREST occupy distinct positioning archetypes. ENKA represents the diversified EPC model spanning multiple transportation modes, allowing portfolio balance across cyclical federal budget allocations. MOSTOTREST exemplifies specialized infrastructure heritage, with its name signaling bridge-focused engineering concentration. Russian Highways anchors the state-backed tier through direct federal backing and sovereign project pipeline priority. These three illustrate how competitive positioning stratifies between breadth-driven diversification and depth-driven technical specialization under Russia's state-directed procurement framework.
| Leading Market Players |
|---|
| ENKA |
| MOSTOTREST |
| Mosproekt-3 |
| RZD International |
| AVTOBAN |
| Russian Highways |
| AO Institute Stroyproekt |
| Transstroy |
| Aecon Group Inc. |
| Others |
Value Network & Pricing Analysis
Scale economies in polymer-modified asphalt production concentrate manufacturing capacity within the Volga Federal District, creating geographic price floors that inflate material budgets for Siberian and Far Eastern projects disproportionately. Federal procurement mandates under the Contract System Law compress contractor margins while simultaneously accelerating technology substitution timelines for sanctioned equipment categories.
Pricing Analysis
State transport ministries anchor pricing structures through competitive tendering under the Contract System Law, with project-based contract awards dominating federal infrastructure allocation. Price differentiation rests on BIM competency certification and GOST-R compliance tier, separating qualified consortia from traditional low-bid specialists. Cost compression in bridge steel and specialty binders is intensifying because sanctions restrict European and Japanese supply channels. Regional contractors exhibit highest price sensitivity due to bonding requirements for projects exceeding one billion rubles, while federal incumbents with sovereign pipeline access maintain pricing power through direct state backing.
Supply Chain Analysis
Strategic stockpiling of steel and cement prevails among contractors facing Arctic construction windows limited to 90-120 days annually, justifying inventory carrying costs against permafrost foundation complexity. Supply concentration centers on domestic Russian production for concrete and structural steel, with China and Turkey serving as alternative channels for specialty grades displaced by sanctions. Raw material dependencies include petroleum-based asphalt binders, polymer additives, and geotechnical instrumentation. Single-source vulnerability runs through European construction machinery now restricted by import controls. Distribution feeds from Volga-based production clusters through rail and river corridors to remote federal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-speed rail corridor development and drone-based progress monitoring are disrupting traditional construction economics, with the Moscow-Kazan route representing Russia's first genuine 400 km/h passenger infrastructure inflection. Federal Antimonopoly Service enforcement of BIM mandates for large tenders is restructuring competitive eligibility criteria across sovereign project pipelines.
For Market Incumbents: Compound sovereign pipeline access by securing consolidated maintenance contracts bundling 10-15 year lifecycle responsibility across Central Federal District ring-road assets. Deepen backward integration into domestic construction machinery production to offset sanctions-driven equipment substitution costs. Defend against agile regional specialists by accelerating smart construction system deployment on remote Siberian sites. For New Entrants and Emerging Players: GOST-R certification fast-track programs offer entry pathways into Volga Federal District bridge engineering contracts where MOSTOTREST heritage concentration leaves specialist gaps. White-space targets include drone-based progress monitoring services for Trans-Siberian cold-chain corridor investments and modular prefabrication for seasonally constrained Arctic foundations. Penetrate through technology partnership models with established contractors lacking in-house sensor network capabilities. For Investors and Strategic Acquirers: Specialized geotechnical engineering firms with permafrost foundation expertise represent acquisition targets given talent scarcity against hydrocarbon sector compensation benchmarks. Long-term viability frames around federal budget prioritization of export corridor completion and agricultural logistics modernization. Watch for inflection when domestic construction machinery substitution timelines compress from current 15-25% schedule extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Consolidated Maintenance Contracting | Bundles 10-15 year lifecycle responsibility into single-source agreements with Russian Highways. |
| BIM Competency Certification | Qualifies contractors for federal projects exceeding one billion rubles under Contract System Law enforcement. |
| Domestic Equipment Substitution | Reduces sanctions exposure by shifting from European and Japanese construction machinery to Russian alternatives. |
| Cold-Chain Corridor Investment | Supports agricultural export growth to Asian markets along Trans-Siberian freight routes. |
| Drone-Based Progress Monitoring | Compresses schedules on remote Siberian sites while reducing survey crew requirements substantially. |
Research Methodology
Desk research of federal procurement databases, Rosstandart GOST certification records, and regional transport ministry tender documentation preceded structured interviews with project directors at federal highway agencies, procurement officers at Russian Highways, geotechnical engineering leads from academic institutes, and equipment procurement managers at diversified EPC contractors. Primary fieldwork combined with secondary validation from customs trade data, Federal Antimonopoly Service enforcement records, and contractor financial disclosures. Bottom-up project pipeline aggregation and top-down federal budget allocation analysis provided triangulation.
Variance decomposition across project type, material selection, technology adoption tier, and end-user structure shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include road-rail-bridge-airport project categories, concrete-steel-asphalt-composite material tiers, BIM-smart-modular-green technology maturity levels, and government-private-contractor-investor customer archetypes. CAGRs derived from historical capital allocation patterns and announced sovereign pipeline commitments, with specific inputs from high-speed rail corridor development timelines and cold-chain logistics investment trajectories.
The analysis sits within stated boundaries; outcomes outside sustained federal budget prioritization of infrastructure or accelerated domestic equipment substitution would require recalibration. Forecasts reflect assumptions regarding Contract System Law enforcement continuity and GOST-R harmonization progress. Revision becomes warranted when sanctions-driven supply chain reconfiguration crosses threshold velocity or Arctic construction seasonality constraints intensify beyond historical baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Middle East Pipeline Construction Market