
 Bridge Construction Market | 2026-2036
Bridge Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Construction Market Intelligence
EU Green Deal procurement rules is rebalancing the cost-of-entry calculus for contractors bidding on publicly funded spans across member states. VINCI leverages its integrated design-build capabilities to pre-certify low-carbon concrete mixes before tender submission. China Communications Construction Company anchors its competitiveness through captive steel fabrication and marine equipment fleets spanning three continents.
Bridge construction encompasses the engineering, fabrication, and assembly of load-bearing structures spanning physical obstacles, typically employing reinforced concrete with specified compressive strengths exceeding 30 MPa or weathering steel grades such as ASTM A709 to achieve 75-100 year design lives against fatigue and corrosion. The primary purpose is maintaining uninterrupted transportation networks for vehicular, rail, and pedestrian traffic across waterways, valleys, and urban corridors. Concrete dominates material type selection for medium-span government contracts due to localized aggregate supply and lower skilled-labor requirements, while composite decks are capturing premium-margin segments where accelerated construction windows justify higher material costs. Cable-stayed methods are expanding fastest among construction method categories for spans exceeding 500 meters, displacing conventional suspension in seismic zones where single-tower configurations reduce foundation complexity.
ISO 12944 coating standards, EN 1993 Eurocode 3 steel design provisions, and EPA stormwater permitting under the Clean Water Act collectively shape material specifications, corrosion protection warranties, and environmental compliance timelines for cross-border projects. China's GB 50017 steel design code and MEE emissions enforcement add parallel certification layers for contractors sourcing fabricated members from Chinese mills. Stakeholders must monitor divergence between EU carbon-border adjustment mechanisms and developing-economy procurement rules to anticipate where contract bundling advantages will shift.
Market Dynamics
EU Green Deal procurement rules are compressing the competitive set for publicly funded bridge contracts by mandating embodied carbon disclosures before bid submission, effectively filtering contractors without pre-certified low-carbon concrete supply chains.
Growth Catalysts
- India's Dedicated Freight Corridors:The Ministry of Railways is awarding multi-span rail bridges across the Delhi-Mumbai and Delhi-Kolkata industrial belts, creating sustained demand for precast segmental construction.
- EU Carbon Border Adjustment Mechanism:Infrastructure procurement in member states now rewards contractors sourcing certified low-emission steel and concrete, accelerating specification shifts toward weathering steel grades.
- Cable-stayed seismic adaptation:Single-tower configurations are displacing conventional suspension in Japan and Chilean seismic zones, reducing foundation complexity for spans exceeding 500 meters.
Market Restraints
- Scrap steel price volatility:Weathering steel fabrication costs fluctuate with Turkish and Vietnamese scrap export quotas, compressing margins for ASTM A709-grade suppliers.
- Fabrication concentration in China:GB 50017-certified mills control 60% of global long-span steel box girder capacity, creating single-source vulnerability for contractors outside domestic supply chains.
- Coating warranty limitations:ISO 12944 C5-M category protective systems face performance gaps in tropical high-humidity zones, restricting design life guarantees below 50 years in Southeast Asian river crossings.
Strategic Opportunities
- Vietnam's Mekong Delta connectivity:The transport ministry is bundling 12 river-spanning contracts with Japanese ODA financing, opening entry points for contractors with seismic design expertise.
- Composite deck hybridization:Glass fiber-reinforced polymer bridge decks are penetrating premium segments where 72-hour installation windows justify material cost premiums over conventional concrete.
- Design-build bundling mandates:US state DOTs under FHWA encouragement are consolidating engineering and construction risk under single contractors, favoring firms with captive in-house design capacity.
Industry Challenges
- Welding inspector certification backlog:EN 1090-2 execution class 4 requirements for fatigue-critical joints face 8-month examiner availability delays in Germany and Poland, stalling steel superstructure mobilization.
- Legacy bearing replacement sequencing:Pot bearing and disc bearing inventories from 1980s installations require staged traffic management during retrofit, complicating urban corridor maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Construction Market |
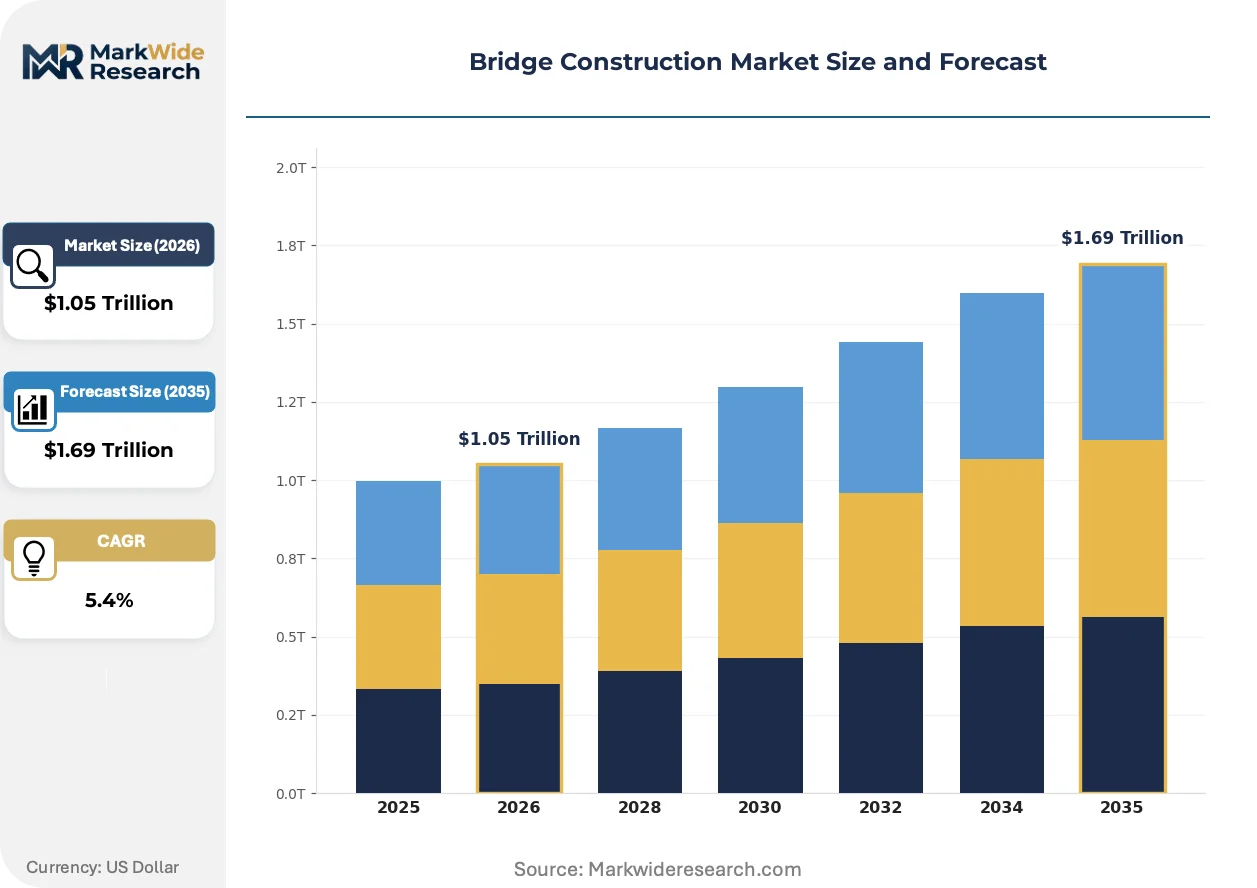
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $1.69 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Concrete, Composite, Timber Construction Method: Precast, Cast-in-Situ, Incremental Launching, Cable-Stayed End User: Government, Private, Contractors, Infrastructure Developers Bridge Type: Arch, Beam, Suspension, Truss |
| Companies Covered | VINCI, ACS Group, China Communications Construction Company, Skanska, Bouygues Construction, China Railway Group, China State Construction Engineering, Kiewit Corporation, China Railway Construction Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Construction Market Strategic Shifts & Innovations
Digital fabrication and materials science are compressing traditional design-construction handoffs while regulatory carbon accounting is embedding itself into procurement specifications ahead of physical construction.
Ultra-high performance concrete (UHPC) with compressive strengths exceeding 150 MPa is unifying deck and girder functions into monolithic cross-sections. State DOTs in Texas and Virginia are specifying UHPC for accelerated bridge construction pilot programs. This unifying material logic is collapsing the traditional substructure-superstructure interface, enabling single-pour solutions that halve field-cure timelines.
REACH Annex XIV authorization requirements for chromium trioxide in corrosion protection coatings are forcing reformulation of ISO 12944-compliant epoxy systems. European fabricators are transitioning to zinc-rich silicate alternatives with shorter pot lives, increasing shop throughput pressure. The regulatory squeeze most affects German and Dutch contractors serving North Sea maritime exposure categories.
Asset owners are consolidating lifecycle cost accountability under extended warranty contracts spanning 30-year design lives. British Columbia's Ministry of Transportation and Infrastructure now requires corrosion-performance bonds from steel suppliers, transferring degradation risk upstream. This contractual shift concentrates procurement authority among contractors with captive coating application facilities and metallurgical testing laboratories.
Bridge Construction Market Segmentation
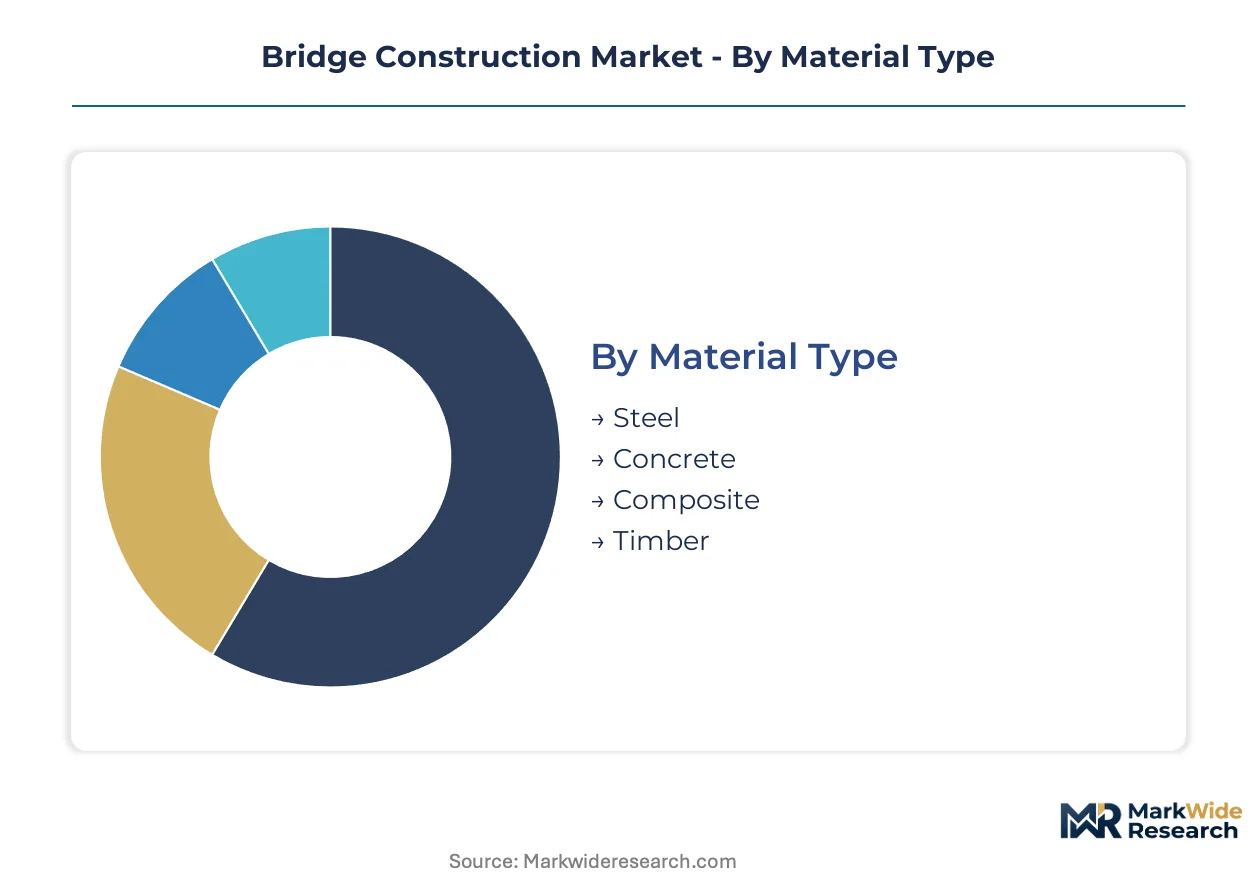
Bridge construction segmentation reveals how material selection, construction methodology, and client procurement patterns determine project economics and competitive positioning. Contractors align capabilities with specific segment requirements to secure contract flows.
Material Type:
Standalone structural materials dominate government highway contracts, while composite systems embed into accelerated construction programs requiring rapid traffic restoration.
- Steel:Weathering grades such as ASTM A709 achieve 75-100 year design lives through controlled oxide formation. Indian Dedicated Freight Corridors and EU Green Deal procurement are concentrating demand for low-emission steel with embodied carbon disclosures.
- Concrete:Reinforced mixes exceeding 30 MPa compressive strength form the backbone of medium-span government contracts leveraging localized aggregate supply. Southeast Asian river-crossing projects favor precast segmental concrete for cost predictability in high-humidity environments.
- Composite:Glass fiber-reinforced polymer decks penetrate premium segments where installation speed justifies material premiums.
- Timber:Glulam and cross-laminated timber systems serve pedestrian and light vehicular spans in Nordic markets with sustainable forestry certification.
Concrete leads volumes today; composite is gaining share fastest.
Construction Method:
Cost tier stratification separates labor-intensive conventional methods from capital-intensive mechanized systems commanding premium contract values.
- Precast:Factory-cast segments transported to site enable standardized quality control and reduced weather dependency. India's Ministry of Railways specifications for Delhi-Mumbai and Delhi-Kolkata corridors favor precast segmental construction for multi-span rail bridges.
- Cable-Stayed:Single-tower configurations reduce foundation complexity in seismic zones. Japanese and Chilean specifications for spans exceeding 500 meters are displacing conventional suspension with this method.
- Cast-in-Situ:Monolithic pours suit complex geometries and site-specific constraints where transport logistics preclude precast delivery.
- Incremental Launching:Sequential segment pushing minimizes environmental disruption over sensitive waterways and active transport corridors.
Precast dominates contract awards; cable-stayed methods are expanding most quickly for long-span applications.
End User:
Procurement authority concentration varies by project scale, with government entities bundling design-build risk and private developers seeking turnkey delivery.
- Government:Public agencies specify material standards and warranty terms through competitive tender processes. EU member states now mandate embodied carbon disclosures before bid submission, filtering contractor pools.
- Contractors:Firms with captive design capacity capture consolidated risk contracts under FHWA-encouraged US state DOT bundling mandates.
- Private:Industrial facility owners and toll concession operators prioritize lifecycle cost optimization over first-cost minimization.
- Infrastructure Developers:Special purpose vehicles aggregate financing and construction risk for bundled corridor projects.
Government procurement leads volumes today; contractor-led design-build is climbing the fastest.
Bridge Type:
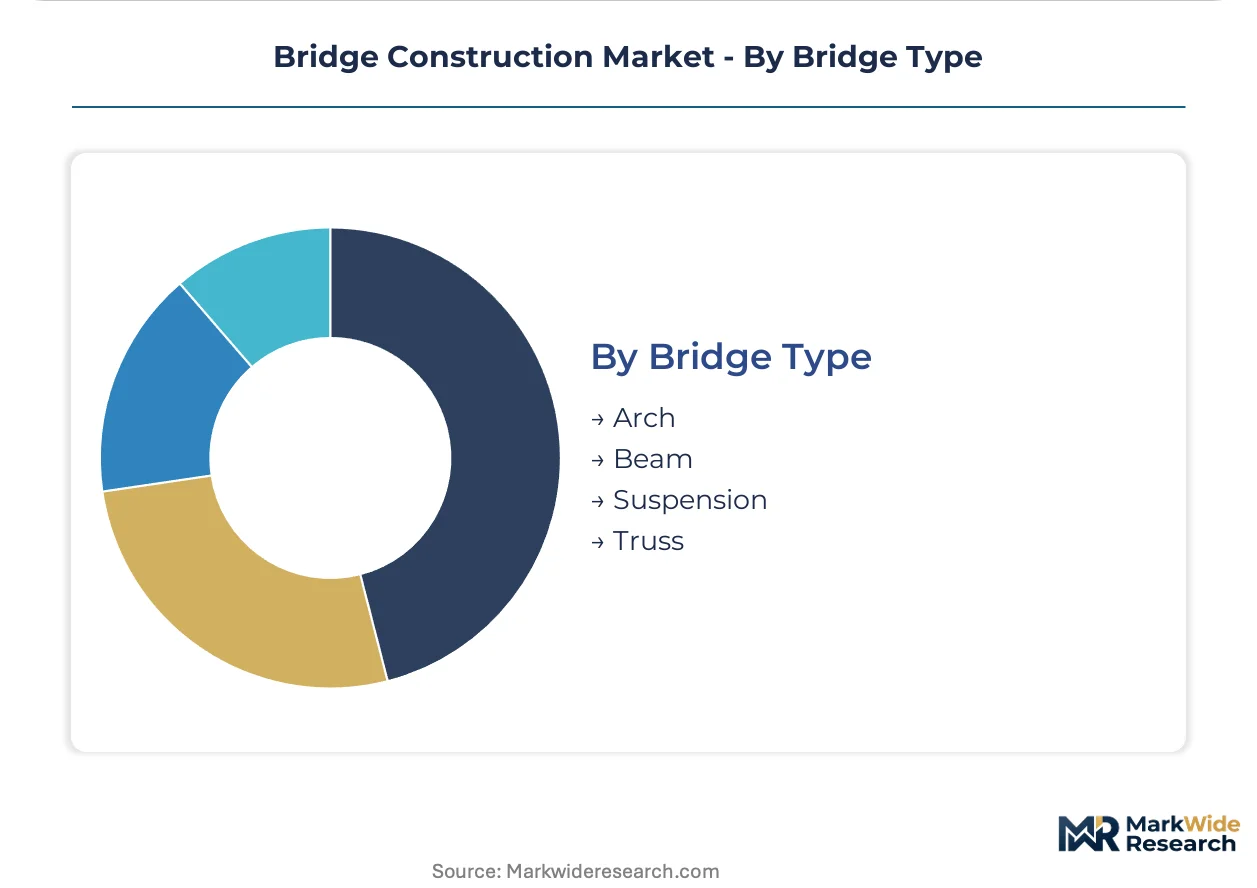
Structural form selection tracks span length, foundation conditions, and seismic exposure with distinct regional specialization patterns.
- Beam:Simple and continuous girder configurations handle routine highway crossings up to 100 meters with minimal maintenance regimes.
- Cable-Stayed:(see Construction Method for technical treatment; here as structural classification) Harp and fan arrangements optimize tower geometry for urban constraints.
- Arch:Compression-dominant behavior suits deep valley crossings with stable rock abutments.
- Truss:Open web systems reduce wind loading for railway and pedestrian applications.
- Suspension:Main cable systems retain dominance for the longest spans where aerodynamic stability governs design.
Beam bridges dominate unit volumes; cable-stayed configurations show steepest expansion trajectory for major crossings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering labor pools in Germany, India, China, Japan, and the United States anchor regional bridge construction capacity. These concentrations align with government infrastructure spending corridors and specialized fabrication clusters.
United States
The Federal Highway Administration encourages design-build bundling across state DOTs, consolidating risk under single contractors. EPA stormwater permitting under the Clean Water Act shapes environmental compliance timelines for cross-border projects. Texas and Virginia DOTs specify ultra-high performance concrete for accelerated bridge construction pilots in urban corridors.
Germany
EN 1090-2 execution class 4 requirements for fatigue-critical joints face examiner availability delays, stalling steel superstructure mobilization. REACH Annex XIV authorization pressures chromium trioxide coating reformulation, forcing zinc-rich silicate alternatives. The Ruhr industrial cluster hosts metallurgical testing laboratories serving corrosion-performance bonds for North Sea maritime exposure.
India
The Ministry of Railways awards multi-span rail bridges across Delhi-Mumbai and Delhi-Kolkata industrial belts, creating sustained demand for precast segmental construction. BIS standards govern reinforced concrete compressive specifications for government highway contracts. Gujarat and Maharashtra aggregate localized supply chains for medium-span concrete structures.
China
GB 50017-certified mills control global long-span steel box girder capacity, creating single-source vulnerability for contractors outside domestic supply chains. MEE emissions enforcement adds parallel certification layers for fabricated members. The Yangtze River Delta concentrates captive steel fabrication and marine equipment fleets spanning three continents.
Japan
Single-tower cable-stayed configurations displace conventional suspension in seismic zones, reducing foundation complexity for spans exceeding 500 meters. METI procurement guidelines favor weathering steel grades with embodied carbon disclosures. The Kansai region around Osaka maintains specialized seismic design expertise for river-crossing projects.
Bridge Construction Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale-driven bundling advantages clash with niche technical expertise. The vendor base clusters around three strategic archetypes: integrated design-build operators with captive engineering capacity, state-linked constructors with domestic procurement preference, and regional specialists with seismic or accelerated construction credentials. Competitive moves concentrate on design-build bundling mandates and pre-certification of low-carbon material supply chains ahead of tender submission.
Within the integrated conglomerate tier, VINCI leverages pre-certified low-carbon concrete capabilities, while China Communications Construction Company anchors competitiveness through captive fabrication assets. Among state-linked constructors, China Railway Group and China State Construction Engineering occupy positions shaped by domestic procurement flows and GB 50017-certified mill access. These named entities exemplify how geographic origin and corporate structure map onto divergent competitive vectors in publicly funded infrastructure markets.
| Leading Market Players |
|---|
| VINCI |
| ACS Group |
| China Communications Construction Company |
| Skanska |
| Bouygues Construction |
| China Railway Group |
| China State Construction Engineering |
| Kiewit Corporation |
| China Railway Construction Corporation |
| Others |
Cost & Logistics Intelligence
Captive steel fabrication and in-house marine equipment fleets anchor both supply security and pricing power for contractors bidding on long-span infrastructure contracts. Contractors without backward integration into GB 50017-certified mills or precast concrete batching face margin compression when scrap volatility or aggregate shortages spike input costs.
Pricing Analysis
Design-build bundling versus unbundled engineering-procurement-construction splits stratify contract economics across the bridge construction market. Project-based lump-sum pricing dominates government tenders, with differentiation driven by embodied carbon certification tiers under EU Green Deal procurement and seismic design class ratings for seismic-zone contracts. Cost compression in weathering steel grades is intensifying because Turkish and Vietnamese scrap export quotas create input volatility. Government agencies exhibit highest price sensitivity due to competitive tender mandates, while private toll concessionaires prioritize lifecycle cost optimization over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese GB 50017-certified mills controlling global long-span steel box girder capacity. Raw material dependencies center on scrap steel feedstock, Portland cement clinker, and zinc-rich silicate coating formulations. Tariff exposure on fabricated structural members creates procurement risk for contractors outside domestic Chinese supply chains. Distribution runs through project-specific direct delivery from fabrication yards to construction sites, with marine equipment fleets enabling self-performed heavy lifting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bridge construction market functions as a stable compounder anchored by government-backed rail and highway corridor spending across industrializing economies. Infrastructure procurement cycles generate predictable contract flows with multi-year visibility.
For Market Incumbents: Lock in pre-certified low-carbon concrete supply chains ahead of EU tender submissions to filter competitor pools. Capture captive coating application facilities and metallurgical testing laboratories to meet British Columbia-style corrosion-performance bond requirements. Defensive consolidation around EN 1090-2 execution class 4 welding certification capacity addresses examiner availability bottlenecks stalling German and Polish steel mobilization.
For New Entrants and Emerging Players: Digital design-build platforms enabling rapid seismic adaptation modeling open entry into Vietnam's Mekong Delta river-crossing contracts bundled with Japanese ODA financing. Target composite deck hybridization segments where glass fiber-reinforced polymer installation speed justifies material premiums. Lead with 72-hour accelerated construction guarantees to penetrate urban corridor maintenance contracts requiring minimal traffic disruption.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with seismic design credentials because single-tower cable-stayed configurations are displacing conventional suspension across Japan and Chile. Focus acquisition screening on firms with captive UHPC batching capacity serving Texas and Virginia DOT accelerated bridge construction programs. Monitor divergence between EU carbon-border adjustment mechanisms and developing-economy procurement rules as the inflection signal for where contract bundling advantages will shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | GB 50017-certified mill access eliminates single-source vulnerability for long-span box girders. |
| Pre-Certification of Low-Carbon Concrete Mixes | EU Green Deal embodied carbon disclosures filter competitor pools before tender submission. |
| Seismic Design Capability Investment | Single-tower cable-stayed expertise captures Japanese and Chilean spans exceeding 500 meters. |
| UHPC Batching Capacity Expansion | Texas and Virginia DOT pilot programs specify ultra-high performance concrete for accelerated construction. |
| Corrosion-Performance Bond Underwriting | British Columbia Ministry of Transportation requirements transfer degradation risk upstream to suppliers. |
Research Approach
Bottom-up infrastructure project pipeline modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with bridge design engineers, state DOT procurement officers, steel fabrication plant managers, and coating application specialists combined with secondary validation from FHWA guidance documents, EU tender databases, BIS concrete standards filings, and customs trade data on structural steel imports. Triangulation across these sources ensures demand-side project visibility aligns with supply-side fabrication and materials capacity.
Historical contract award trendline analysis informs projection frameworks across material type, construction method, and end-user segmentation dimensions. Modeled variables include precast segmental versus cast-in-situ method splits, government versus private procurement authority shares, and weathering steel versus reinforced concrete material selection patterns. CAGRs derive from project pipeline velocity tracked through transport ministry budget allocations and multilateral development bank financing disbursements.
Scrap steel price volatility, welding inspector certification backlogs, and regulatory divergence between EU carbon-border mechanisms and developing-economy procurement rules are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Sandwich Plate System Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Global Rebar Splice Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Bridge Bearings Market
Structural Construction
Timber Frame Construction Market
Structural Construction
H Beam Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Steel Beam Market