
 Steel Fabrication Market | 2026-2036
Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Fabrication Market Analysis
Skilled welder availability is rotating from a bottleneck in North American yards to a managed constraint as apprenticeship pipelines expand. ArcelorMittal leverages its integrated European mill network to supply certified structural sections across infrastructure projects. Nucor Corporation anchors its position through electric-arc furnace flexibility and scrap-based circular production. thyssenkrupp AG differentiates via precision engineering capabilities in complex bridge and energy components.
Steel fabrication transforms raw or semi-finished steel into dimensionally precise structural components through thermal cutting, welding, and mechanical forming, typically achieving tolerances within millimeters for load-bearing assemblies. The process serves as the backbone of modern infrastructure, converting mill-produced beams and plates into project-specific frameworks for buildings, bridges, and industrial machinery. Beams and plates command the largest share of fabricated tonnage, reflecting their dominance in commercial construction and heavy industrial frameworks. The energy end-user segment is expanding fastest, driven by offshore wind jacket foundations and power grid transmission towers. Welding technology retains the deepest margin pools, as coded welders and automated robotic systems create defensible quality barriers that commodity cutting cannot replicate.
FDA and OSHA standards govern worker exposure and structural integrity in US food processing and industrial facilities, while the EU's CE marking and F-Gas Regulation shape material specifications and environmental compliance for exported European projects. China's GB standards and dual carbon goals from MEE are tightening emission thresholds for imported fabricated steel, altering competitive access for non-compliant producers. Stakeholders must monitor how carbon intensity certification evolves from a procurement preference into a contractual gate for project eligibility.
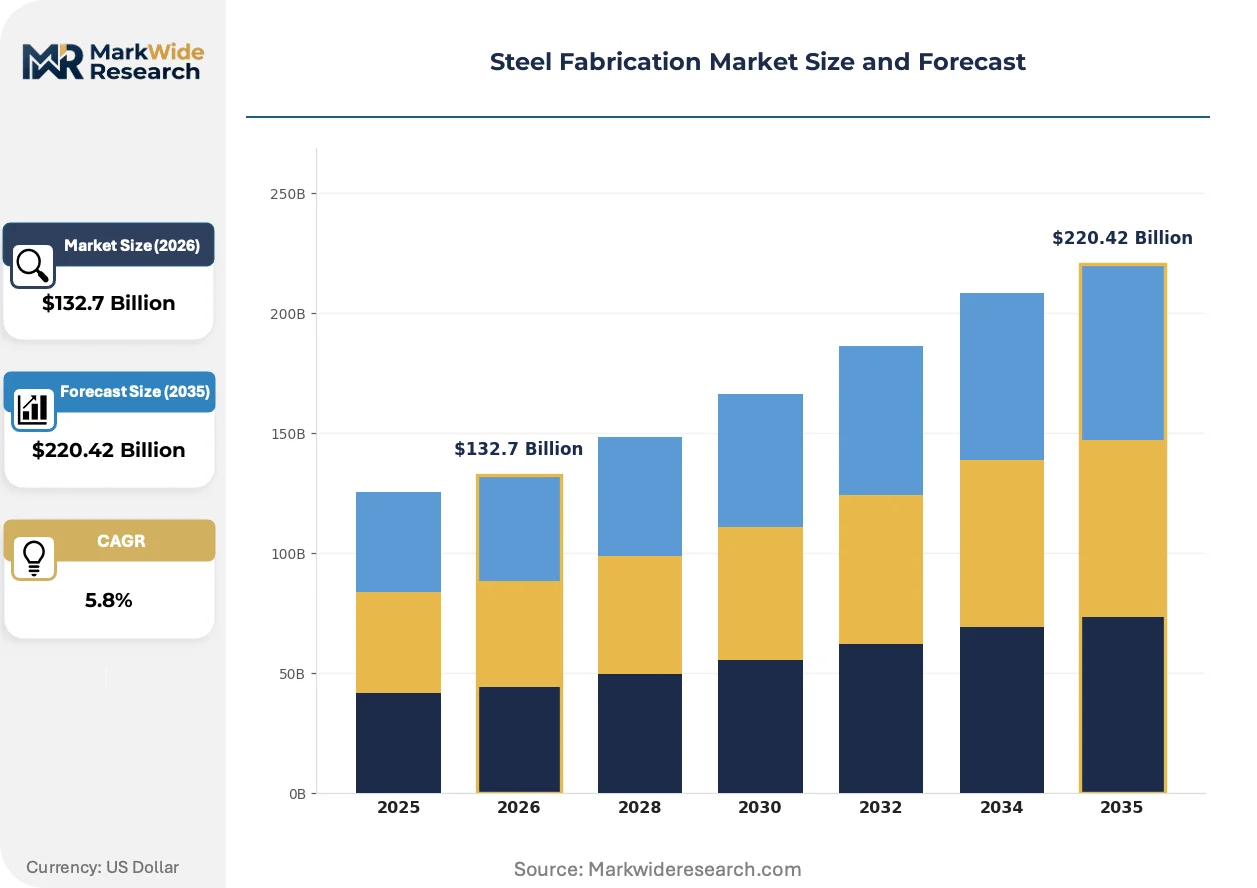
Market Dynamics
The EU's Carbon Border Adjustment Mechanism is redirecting mill sourcing decisions toward low-emission producers, compressing margins for carbon-intensive fabricators while rewarding certified low-carbon steel suppliers with preferential access to European infrastructure contracts.
Growth Catalysts
- Offshore Wind Jacket Foundations:Energy developers in the North Sea and Baltic Sea are procuring record tonnages of fabricated tubular steel for monopile and jacket structures, creating dedicated demand pools for certified marine-grade fabricators.
- India's Industrial Corridor Expansion:Infrastructure build-out between Mumbai and Delhi is concentrating demand for structural steel frameworks across logistics hubs, manufacturing parks, and power transmission networks.
- CE Marking Compliance Premium:European project eligibility now requires documented carbon intensity certification, pulling procurement toward mills and fabricators with verified Environmental Product Declarations.
Market Restraints
- Scrap Price Volatility:Electric-arc furnace operators face margin compression when ferrous scrap inventories tighten, particularly in US Gulf Coast markets dependent on shredded auto feedstock.
- Specialized Welder Concentration:Coded welders capable of ASME Section IX and AWS D1.1 certification remain concentrated in legacy industrial regions, limiting expansion capacity for new fabrication yards.
- Aluminum Substitution in Lightweighting:Bridge designers and transport equipment manufacturers are specifying aluminum extrusions for corrosion-critical applications where weight reduction outweighs material cost premiums.
Strategic Opportunities
- Vietnam Infrastructure Absorption:Commercial construction across Ho Chi Minh City and Hanoi is absorbing fabricated structural steel volumes that exceed domestic mill capacity, creating import substitution openings for ASEAN-certified fabricators.
- Modular Construction Prefabrication:Building developers are shifting from site-welded frames to factory-fabricated volumetric modules, rewarding fabricators with precision cutting and robotic welding capabilities.
- Green Hydrogen Pipeline Fabrication:High-pressure hydrogen transmission networks require specialized steel grades and welding protocols, opening premium contract pools for fabricators with ASME B31.12 certification.
Industry Challenges
- Multi-Standard Certification Overlap:Fabricators serving both EU and US markets must maintain parallel compliance with CE marking, AWS codes, and OSHA worker exposure standards, extending quality system audit cycles.
- Automated Welding System Integration:Robotic seam tracking and adaptive fill control require capital deployment and reprogramming expertise that mid-tier yards struggle to resource without technical partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Fabrication Market |
| Market Size in 2026 | $132.7 Billion |
| Market Size in 2035 | $220.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Plates, Channels, Pipes End User: Construction, Automotive, Energy, Aerospace Technology: Welding, Cutting, Punching, Bending Application: Infrastructure, Machinery, Shipbuilding, Railways |
| Companies Covered | Sure Steel, Inc., Cleveland-Cliffs Inc., Lexicon, Inc., ArcelorMittal, Steel Dynamics, Inc., Schuff Steel Co., Nucor Corporation, thyssenkrupp AG, Basden Steel Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Fabrication Market Emerging Trajectories
Digital thread integration from BIM models to CNC cutting tables is compressing fabrication lead times and dimensional error rates, while regulatory carbon accounting is embedding emissions tracking into every procurement specification.
Laser-arc hybrid welding is supplanting conventional submerged arc processes in heavy plate joining. Offshore wind foundation fabricators in Denmark and Germany are adopting this technology for root pass efficiency in thick-walled tubular joints. The process is enabling single-sided welding of jacket nodes that previously required multi-position manual passes, compressing yard cycle times by eliminating repositioning delays.
China's MEE dual carbon goals are tightening emission thresholds for imported fabricated steel, altering competitive access for non-compliant producers. The GB standards revision now requires embodied carbon disclosure for structural steel entering state-funded projects. European and Korean fabricators with ISO 14064-verified carbon footprints are capturing preferential placement in Chinese renewable energy tenders.
Asset owners are unbundling fabrication from installation contracts, creating direct procurement relationships with certified shops. EPC firms in Southeast Asia are responding by establishing approved vendor lists that bypass traditional subcontractor tiers. This disintermediation is most visible in Singapore's data center construction pipeline, where hyperscale operators specify fabricators directly to enforce welding traceability standards.
Steel Fabrication Market Segmentation
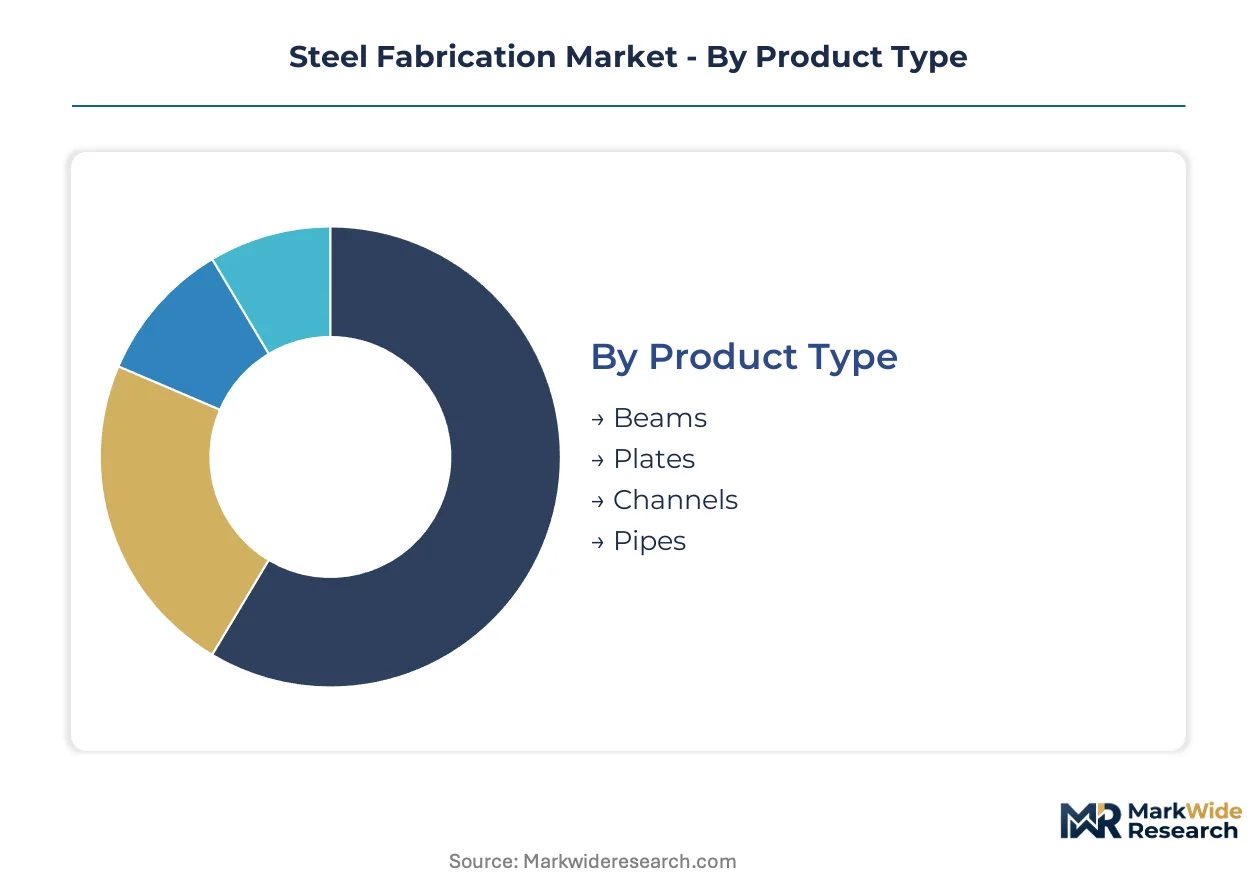
Steel fabrication segmentation reveals distinct margin profiles across product geometries, end-use specifications, and process technologies. Each dimension carries different certification burdens, geographic sourcing patterns, and capital intensity requirements that shape competitive positioning.
Product Type:
Beams and plates flow predominantly into domestic infrastructure and commercial construction across North America and Europe, while channels and pipes serve export-oriented energy and industrial machinery markets with stricter marine-grade and pressure-vessel certifications.
- Beams:Wide-flange and H-section structural members achieve millimeter tolerances through thermal cutting and automated welding. Demand concentrates in India's Mumbai-Delhi industrial corridor for logistics hubs and manufacturing parks, driven by government-backed infrastructure build-out. Beams command the established base.
- Plates:Flat-rolled steel sections ranging from 3mm to 150mm thickness undergo plasma or laser cutting before edge preparation and welding. European offshore wind developers in the North Sea procure record tonnages for monopile and jacket foundations, pulling procurement toward CE-marked fabricators with Environmental Product Declarations. The steepest expansion runs through plates.
- Channels:C-section and U-section profiles serve lighter structural frameworks and equipment skids. Japanese automotive OEMs specify JIS-certified channels for assembly line infrastructure and stamping press foundations.
- Pipes:Hollow structural sections and pressure tubing require specialized forming and seam welding. Green hydrogen transmission networks in Germany specify ASME B31.12-certified pipe fabricators for high-pressure containment.
Beams anchor volume throughput in established construction markets. Plates capture the steepest expansion trajectory through offshore wind and energy transition investments.
End User:
Construction and automotive segments operate on cost-tier differentiation with domestic procurement preferences, while energy and aerospace command premium certification tiers with cross-border sourcing flexibility.
- Construction:Commercial buildings, bridges, and industrial facilities consume fabricated steel for load-bearing frames and lateral systems. Vietnam's Ho Chi Minh City and Hanoi construction markets absorb volumes exceeding domestic mill capacity, creating import substitution openings for ASEAN-certified suppliers.
- Automotive:Stamping press foundations, assembly line structures, and logistics equipment require precision-toleranced fabrication. German OEMs specify CE-marked structural components with documented carbon intensity under EU Green Deal procurement rules.
- Energy:Power generation, transmission, and renewable infrastructure demand certified pressure vessels and lattice towers. Offshore wind jacket foundations in Denmark and Germany are procuring record tubular steel tonnages, rewarding fabricators with laser-arc hybrid welding capabilities.
- Aerospace:Hangar structures, test facility frameworks, and manufacturing cleanrooms require ultra-tight dimensional control. US FAA facility standards govern structural integrity for airframe assembly infrastructure.
Construction maintains volume leadership across fabrication yards. Energy is climbing the fastest through renewable infrastructure build-out.
Technology:
Welding and cutting technologies stratify by automation maturity and certification depth, while punching and bending serve lower-margin standardized production with regional equipment supplier concentration.
- Welding:Arc, MIG, TIG, and robotic seam-tracking processes create coded quality barriers that commodity operations cannot replicate. ASME Section IX and AWS D1.1 certification requirements concentrate skilled welders in legacy US industrial regions, limiting expansion capacity for new fabrication yards.
- Cutting:Plasma, laser, and oxy-fuel thermal separation prepares edges for subsequent joining. Digital thread integration from BIM models to CNC cutting tables is compressing lead times and dimensional error rates in European infrastructure projects.
- Punching:Mechanical and hydraulic perforation creates bolt holes and access openings in lighter gauge material. Standardized punching equipment dominates mid-tier fabrication serving commercial construction.
- Bending:Press brake and roll forming shapes plates and sections into curved geometries. China's GB standards revision requires embodied carbon disclosure for bent structural components entering state-funded projects.
Welding retains the deepest margin pools through certification scarcity. Cutting is gaining share fastest through digital integration and automation.
Application:
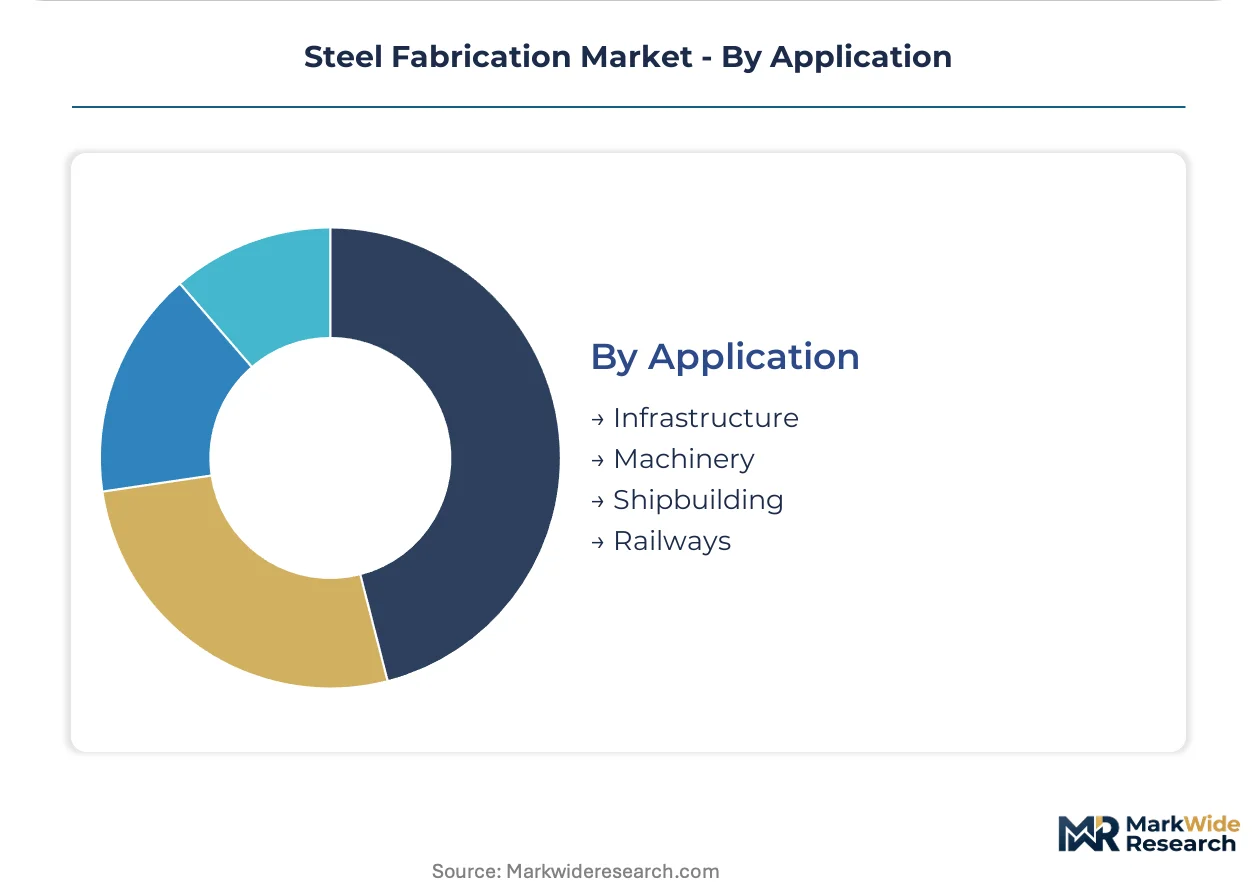
Infrastructure and machinery applications dominate domestic procurement with public sector specification control, while shipbuilding and railways operate under specialized classification society and operator certification regimes with concentrated supplier bases.
- Infrastructure:Bridges, highways, and public buildings require load-rated structural assemblies with full material traceability. Singapore's data center construction pipeline sees hyperscale operators specifying fabricators directly to enforce welding traceability standards, bypassing traditional EPC subcontractor tiers.
- Machinery:Industrial equipment frames, material handling systems, and process skids demand precision-toleranced fabrication. US OSHA standards govern worker exposure and structural integrity in food processing and industrial facilities.
- Shipbuilding:Hull sections, deck structures, and offshore platforms require marine-grade steel and certified welding procedures. Korean fabricators with ISO 14064-verified carbon footprints capture preferential placement in Chinese renewable energy tenders.
- Railways:Rolling stock underframes, station infrastructure, and maintenance facilities specify fatigue-resistant fabrication. India's dedicated freight corridors between Mumbai and Delhi concentrate demand for rail-specific structural frameworks.
Infrastructure commands the established base through public project volume. Shipbuilding is expanding most quickly through offshore wind foundation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. European buyers prioritize carbon-certified structural sections under CBAM compliance, while Asian markets absorb record tonnages for commercial construction with less stringent emission thresholds. North American procurement balances domestic mill supply against skilled fabrication capacity constraints.
Germany
Offshore wind developers in the North Sea and Baltic Sea procure record tonnages of fabricated tubular steel for monopile and jacket structures. The EU's Carbon Border Adjustment Mechanism redirects mill sourcing toward low-emission producers with Environmental Product Declarations. Fabrication clusters in Bremen and Rostock concentrate marine-grade welding capacity for certified jacket foundations.
United States
Commercial construction across Texas and Florida absorbs structural steel volumes despite skilled welder shortages in Gulf Coast fabrication yards. OSHA standards govern worker exposure and structural integrity in food processing and industrial facilities. Nucor Corporation anchors supply through electric-arc furnace flexibility and scrap-based circular production across its Southeastern mill network.
India
Government-backed infrastructure build-out between Mumbai and Delhi concentrates demand for structural steel frameworks across logistics hubs and manufacturing parks. The country's national steel regulator enforces BIS certification for load-bearing assemblies in public projects. ArcelorMittal leverages its integrated mill network to supply certified structural sections for the industrial corridor expansion.
Vietnam
Commercial construction across Ho Chi Minh City and Hanoi absorbs fabricated structural steel volumes exceeding domestic mill capacity. ASEAN certification requirements shape procurement eligibility for imported fabricated components. Fabricators with CE marking compliance capture premium positioning in high-rise and industrial park developments.
China
State-funded renewable energy tenders pull procurement toward fabricators with ISO 14064-verified carbon footprints. MEE dual carbon goals tighten emission thresholds for imported fabricated steel under revised GB standards. Yangtze River Delta fabrication clusters adapt to embodied carbon disclosure requirements for structural steel entering infrastructure projects.
Steel Fabrication Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-cap regional fabricators filling geographic gaps. The upper tier commands premium positioning through certified low-carbon production and multi-standard compliance capabilities. Three archetypes dominate: integrated mill-fabricators with captive steel supply, precision engineering specialists serving complex infrastructure, and scale-driven operators leveraging electric-arc furnace feedstock flexibility. Competitive moves center on strategic partnerships for automated welding technology access and geographic expansion into ASEAN infrastructure markets.
Among North American operators, Nucor Corporation and Cleveland-Cliffs Inc. exemplify the integrated mill-fabricator archetype with captive steel production and circular feedstock models. ArcelorMittal occupies a position spanning both European and Indian markets through its multinational mill network. thyssenkrupp AG represents the precision engineering specialist tier, differentiated by complex bridge and energy component capabilities. These three anchors illustrate how certification depth and geographic footprint stratify competitive positioning across carbon-regulated and high-growth infrastructure markets.
| Leading Market Players |
|---|
| Sure Steel, Inc. |
| Cleveland-Cliffs Inc. |
| Lexicon, Inc. |
| ArcelorMittal |
| Steel Dynamics, Inc. |
| Schuff Steel Co. |
| Nucor Corporation |
| thyssenkrupp AG |
| Basden Steel Corp. |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for CE-marked heavy plate from European mills concentrate pricing power among certified fabricators with Environmental Product Declarations, while spot-market buyers in Southeast Asia absorb 20-30 day inventory cycles that compress margins when scrap prices spike. This divergence between long-contract stability and short-cycle volatility shapes how procurement teams balance qualification costs against price exposure.
Pricing Analysis
Long-term offtake agreements dominate procurement for offshore wind jacket foundations and hydrogen pipeline infrastructure, locking in tonnage commitments across multi-year horizons. Spot-market transactions govern commercial construction in Vietnam and India, where project-based bidding exposes fabricators to ferrous scrap volatility. Price differentiation rests on certification tier—ASME Section IX and AWS D1.1 coded welding commands 15-25% premiums over commodity fabrication—while CE marking compliance under EU Green Deal rules creates additional tier separation. Cost compression in standard structural beams is intensifying as Chinese mills with ISO 14064-verified footprints capture share in ASEAN markets. Buyers in energy and aerospace segments demonstrate lowest price sensitivity, prioritizing traceability and weld qualification over unit economics.
Supply Chain Analysis
Strategic stockpiling of marine-grade plate and certified weld wire characterizes European and North American fabrication yards preparing for CBAM compliance deadlines, while just-in-time inventory models prevail in Southeast Asian construction markets with faster project cycles. Raw material supply concentrates in China, India, and Germany for flat-rolled steel, with South Korea and Japan anchoring specialty alloy feedstock for pressure-vessel applications. Fabrication capacity draws from scrap-intensive electric-arc furnace networks in the US Gulf Coast and integrated blast furnace complexes in Western Europe. Single-source vulnerability runs through Chinese GB-standard mills supplying state-funded renewable energy tenders. Distribution runs through approved vendor lists established by EPC contractors and direct procurement relationships with hyperscale data center operators in Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel fabrication operates as a regulatory-entrenchment defensive moat: welding certification scarcity and carbon-intensity disclosure requirements create switching costs that lock asset owners into qualified supplier relationships.
For Market Incumbents: Shield market position by deepening backward integration into scrap sorting and direct reduced iron supply to control input cost volatility against Gulf Coast shredded auto feedstock tightness. Expand ASME B31.12 certification coverage for hydrogen pipeline fabrication before green hydrogen infrastructure tenders accelerate. Prioritize robotic welding system partnerships to offset skilled welder concentration in legacy industrial regions. For New Entrants and Emerging Players: Fast-track ASEAN certification for Vietnam's Ho Chi Minh City and Hanoi construction markets, where domestic mill capacity shortfalls create immediate import substitution openings. Target modular construction prefabrication for data center and logistics hub developers shifting from site-welded frames to factory-fabricated volumetric modules. Establish technical partnerships with European automation suppliers for laser-arc hybrid welding capability transfer. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because carbon-border mechanisms and embodied carbon disclosure rules are converting welding qualification and EPD verification from procurement preferences into contractual gates. Acquisition candidates include mid-tier fabricators with multi-standard compliance (CE marking, AWS codes, OSHA standards) and established relationships with offshore wind developers in the North Sea. Watch for inflection when CBAM compliance costs exceed 8-10% of project steel budgets, triggering accelerated consolidation toward low-carbon integrated mill-fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Supply | Captures margin compression protection when US Gulf Coast shredded auto feedstock tightens. |
| ASME B31.12 Certification Investment | Unlocks premium contract pools for German green hydrogen transmission network fabrication. |
| Robotic Welding System Deployment | Compresses cycle times for Danish offshore wind jacket foundation nodes. |
| Environmental Product Declaration Verification | Secures preferential placement in Chinese state-funded renewable energy tenders. |
| ASEAN Certification Fast-Track | Captures import substitution openings in Vietnam's domestic mill capacity shortfall. |
Methodological Framework
The analysis maps beams, plates, channels, and pipes alongside welding, cutting, punching, and bending technologies, each validated through fabrication yard managers, EPC procurement leads, coded welding supervisors, and carbon certification auditors. Primary interviews with these stakeholders combined with secondary validation against customs/trade data, mill shipment reports, SEC filings from integrated steel producers, and project development databases for offshore wind and hydrogen infrastructure. Bottom-up tonnage estimates by product geometry and end-use segment triangulated against top-down regional consumption figures from national steel associations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-user industry, process technology, and application dimensions alongside carbon-intensity certification tier and geographic regulatory cluster. CAGRs derived from regression analysis of historical mill shipments and announced project pipelines, with specific inputs including offshore wind capacity additions in the North Sea and Baltic Sea, India's Mumbai-Delhi industrial corridor infrastructure commitments, and Vietnam commercial construction permit data.
Decision-makers should treat outputs as directional under assumptions of continued CBAM implementation, sustained offshore wind foundation demand, and stable scrap supply elasticity; material deviation in any would warrant model refresh. Revision becomes warranted when carbon-border compliance costs cross project budget thresholds or when ASEAN domestic mill capacity expansion outpaces construction absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market