
 Sandwich Plate System Market | 2026-2036
Sandwich Plate System Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Plate System Market Analytics
Modular panel bundling is consolidating buyer preference around factory-integrated sandwich plate systems that reduce on-site welding. SPS Technology leverages its patented elastomer core bonding process to anchor premium marine contracts. Kingspan Group sustains its position through geographic dominance in European cold-chain construction. TATA Steel competes on manufacturing scale across Indian and Southeast Asian infrastructure projects.
A sandwich plate system comprises two high-strength face sheets metallurgically or adhesively bonded to a lightweight core material, typically achieving stiffness-to-weight ratios exceeding solid plate equivalents by 40-60% depending on core geometry. The configuration serves primarily to reduce structural mass while maintaining buckling resistance in marine decks, offshore platforms, and architectural facades. Composite product types lead volume shipments due to corrosion advantages in saltwater environments, though metal variants command margin pools in blast-resistant and fire-rated specifications. Marine applications represent the fastest-growing demand cluster as shipyards adopt prefabricated deck panels to compress build cycles. Aluminum and steel materials occupy distinct specification tiers, with carbon fiber penetrating selectively in aerospace and high-performance marine racing segments.
The International Maritime Organization's Energy Efficiency Existing Ship Index and the EU Green Deal's embodied carbon reporting rules shape material selection and core recyclability requirements for sandwich plate suppliers. Lloyd's Register and DNV classification societies enforce face-to-core delamination thresholds that filter subscale manufacturers from commercial marine approvals. Stakeholders must monitor how IMO carbon intensity indicators redirect retrofit demand toward lightweight deck replacements versus full hull redesigns.
Market Dynamics
Shipbuilders in South Korea and Japan are compressing vessel construction cycles through prefabricated deck panel adoption, forcing core material suppliers to align production cadence with modular yard schedules rather than traditional plate delivery timelines.
Growth Catalysts
- IMO Energy Efficiency Existing Ship Index:The regulation mandates carbon intensity reductions for existing fleets, driving retrofit demand for lightweight deck replacements that improve vessel energy performance without full hull redesign.
- Recyclable aluminum honeycomb cores:These materials satisfy EU Green Deal embodied carbon reporting requirements while maintaining saltwater corrosion resistance, positioning composite sandwich systems for premium marine specifications.
- East Asian shipyard clusters:Concentrated demand from South Korean and Japanese builders creates economies of scale for elastomer core bonding processes, reducing per-unit manufacturing costs across production runs.
Market Restraints
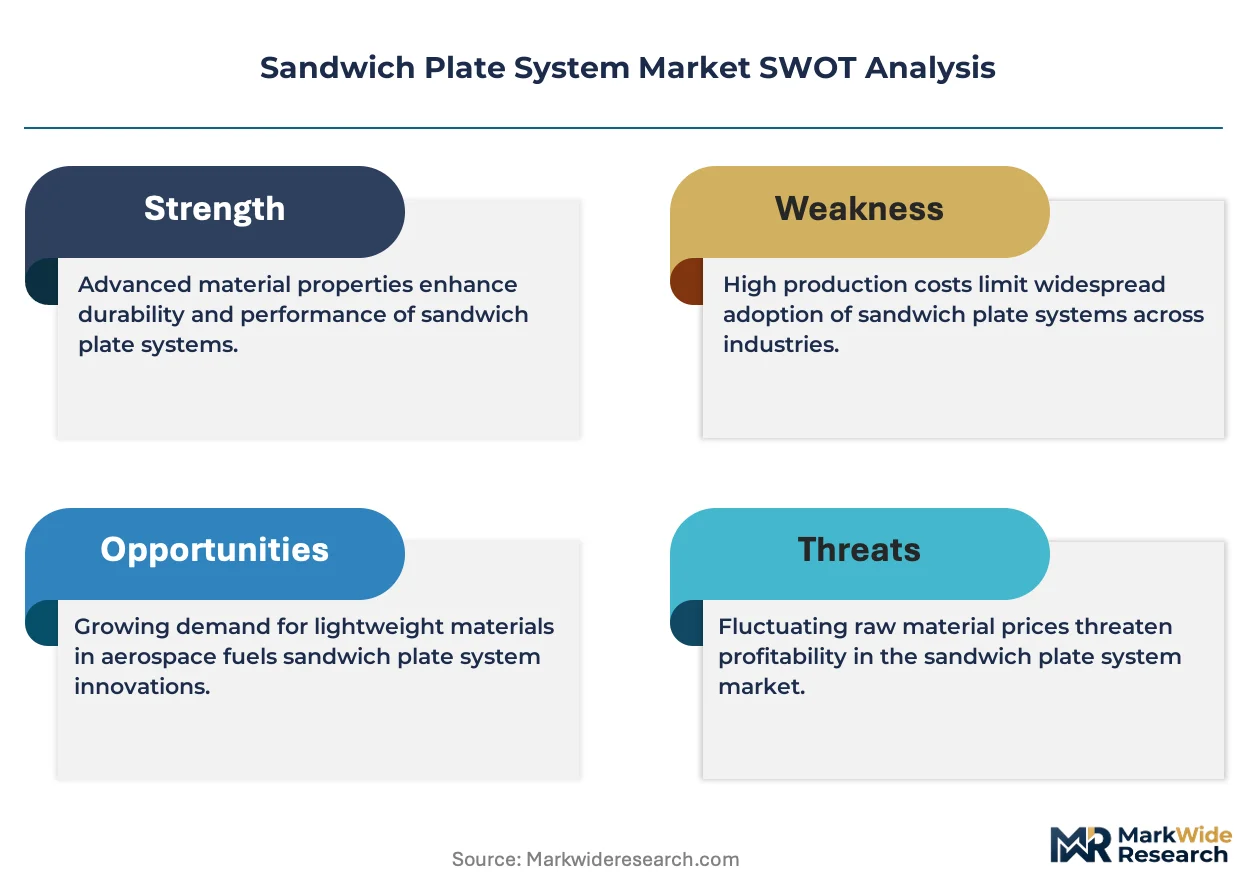
- Aramid fiber price volatility:Ballistic-grade core material input costs fluctuate with aerospace and defense procurement cycles, compressing margins for blast-resistant specification suppliers.
- DNV classification society delamination thresholds:Stringent face-to-core bond testing requirements filter subscale manufacturers from commercial marine approvals, consolidating supply around certified producers.
- Solid steel plate substitution:Fire-rated specifications in certain offshore platform segments retain preference for conventional metallurgy where thermal performance certification remains faster to obtain.
Strategic Opportunities
- Nordic offshore wind installation vessel demand:Denmark, Norway, and Sweden are expanding jack-up fleet capacity, creating specification pull for heavy-duty sandwich plate decking with integrated cable management channels.
- Factory-integrated panel bundling:Modular construction methods enable shipyards to outsource complete deck section fabrication, shifting value capture upstream to system integrators with bonding automation capabilities.
- EU Green Deal circular economy mandates:Recyclability requirements for construction materials create competitive differentiation for suppliers offering closed-loop core material recovery programs.
Industry Challenges
- Lloyd's Register certification timelines:Extended approval cycles for novel core geometries delay product commercialization, requiring sustained R&D investment without near-term revenue offset.
- Adhesive bonding technician scarcity:Specialized elastomer core application skills concentrate in mature marine manufacturing regions, constraining capacity expansion into emerging shipbuilding geographies.
- Legacy hull integration complexity:Retrofit installations demand custom interface engineering between sandwich plate decks and existing steel framing, increasing project engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Plate System Market |
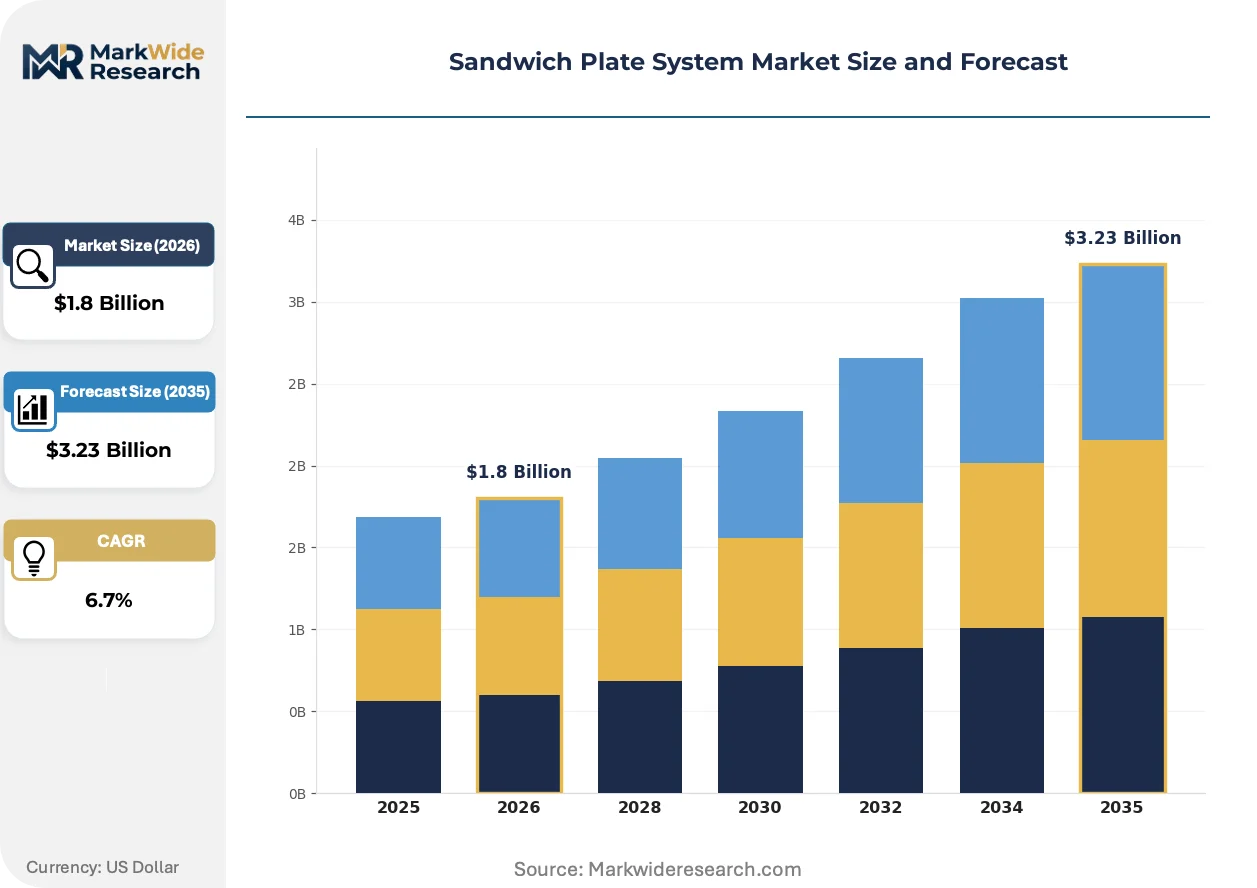
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Metal, Rigid, Flexible Application: Marine, Construction, Aerospace, Automotive End User: Manufacturers, Contractors, Engineers, Architects Material: Aluminum, Steel, Glass Fiber, Carbon Fiber |
| Companies Covered | IE-SPS, SPS Technology, Kingspan Group, Assan Panel, TATA Steel, ArcelorMittal, NCI Building Systems, Metecno, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Plate System Market Evolving Landscape
Material science advances and regulatory carbon accounting are converging to reshape core specification preferences, with bonding process automation emerging as the critical production differentiator.
Recyclable thermoplastic elastomer cores are absorbing market share from thermoset alternatives in European marine specifications. German and Dutch shipyards specify these materials for newbuild passenger vessels seeking EU Green Deal compliance. The technology is absorbing certification investment from classification societies, compressing approval timelines for sustainable material categories.
REACH chemical substance restrictions are forcing reformulation of legacy adhesive bonding agents used in sandwich plate fabrication. Industrial consequence includes accelerated qualification of bio-based epoxy alternatives by core suppliers serving North Sea offshore platforms. Metal-faced specifications for blast-resistant applications face the most acute reformulation pressure, driving R&D concentration among defense-oriented producers.
Buyer preference is consolidating around factory-integrated deck modules rather than component supply. Shipyards in South Korea and Japan now procure complete panel sections with pre-installed insulation and outfitting penetrations, displacing traditional on-site welding and assembly. This specification shift is most visible in cruise vessel newbuild programs where construction cycle compression delivers measurable capital cost reduction.
Sandwich Plate System Market Segmentation
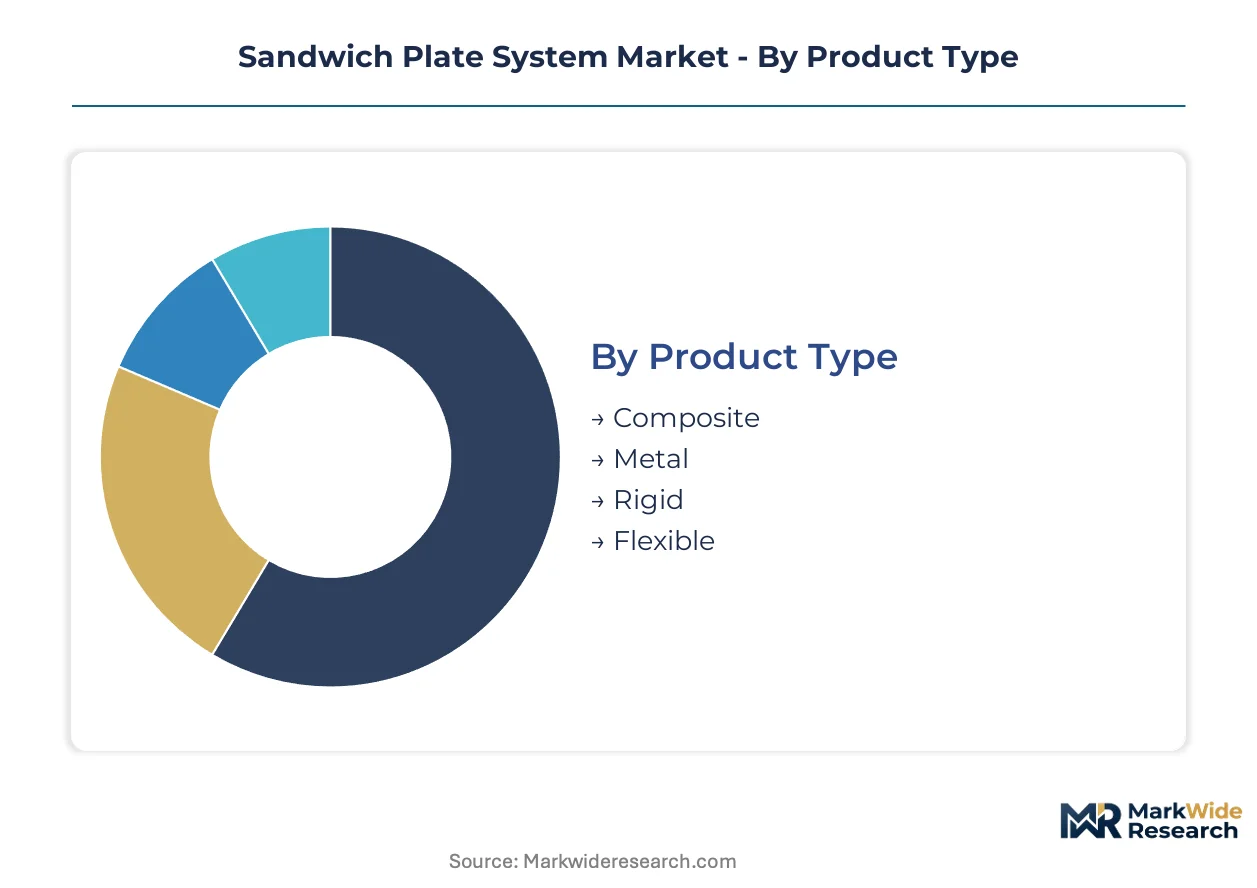
Sandwich plate system procurement patterns diverge sharply across specification tiers, with marine retrofit cycles and offshore construction timelines driving replacement demand in composite categories while metal variants serve ballistic and fire-rated permanence requirements. Understanding segment boundaries reveals where bonding automation investments concentrate and where certification barriers filter supplier participation.
Product Type:
Upgrade cycles for existing vessel decks and architectural facades create divergent replacement timelines across core material categories, with thermoplastic elastomer bonding processes compressing factory integration lead times.
- Composite:Thermoset and thermoplastic polymer matrices bonded to honeycomb or foam cores achieve 40-60% mass reduction versus solid plate equivalents. Shipyards in South Korea and Japan specify these systems for cruise vessel newbuild programs where EU Green Deal embodied carbon reporting accelerates recyclable thermoplastic adoption over legacy thermoset alternatives.
- Metal:Aluminum and steel face sheets with metallic or elastomer cores deliver blast resistance and fire ratings exceeding polymer specifications. Demand concentrates in offshore platform helidecks and naval vessel protection systems where DNV delamination thresholds and thermal performance certification retain preference for conventional metallurgy despite higher structural mass.
- Rigid:Closed-cell foam and honeycomb cores with minimal compressibility under load serve primary structural decking applications. Nordic offshore wind installation vessels specify rigid configurations for jack-up leg interface zones.
- Flexible:Elastomeric core materials accommodate vibration damping and acoustic isolation in machinery mounting and passenger vessel comfort applications. German shipyards integrate flexible panels for engine room isolation.
Volume placements concentrate in Composite; the faster expansion belongs to Metal.
Application:
Construction cycle compression and regulatory carbon intensity mandates are redirecting specification flows across end-use verticals, with modular prefabrication methods displacing on-site assembly in time-sensitive programs.
- Marine:Prefabricated deck panels with pre-installed insulation and outfitting penetrations compress vessel build cycles. South Korean shipyard clusters drive specification pull for factory-integrated modules with elastomer core bonding automation.
- Construction:Cold-chain facilities and architectural facades demand thermal bridge elimination and rapid envelope closure. Kingspan Group's European geographic dominance anchors specification share in refrigerated warehouse construction.
- Aerospace:Carbon fiber face sheets with aramid or aluminum honeycomb cores achieve specific stiffness requirements for interior monuments and cargo liners. Boeing and Airbus supplier qualification timelines filter subscale manufacturers.
- Automotive:Battery enclosure protection and structural floor panels utilize aluminum honeycomb configurations for crash energy management. European electric vehicle platforms specify recyclable core materials for end-of-life compliance.
Marine captures the dominant placement volume; Construction is climbing the fastest.
End User:
Technical specification authority and procurement scale separate direct buyers from influencer categories, with factory-integrated panel bundling shifting value capture toward system integrators with bonding automation capabilities.
- Manufacturers:Shipbuilders and modular construction fabricators procure complete deck sections with pre-installed systems. Japanese cruise vessel programs outsource entire superstructure modules to certified bonding specialists.
- Contractors:Installation and retrofit project managers demand custom interface engineering between sandwich plate decks and legacy steel framing. Lloyd's Register certification requirements extend approval timelines for novel geometries.
- Engineers:Structural and naval architects specify face sheet alloys, core densities, and adhesive systems for load-bearing applications. DNV classification society rules govern face-to-core delamination thresholds.
- Architects:Aesthetic and environmental performance requirements drive facade specification in commercial and institutional buildings. EU Green Deal circular economy mandates influence material selection.
Manufacturers dominate direct procurement volume; Contractors are gaining share fastest.
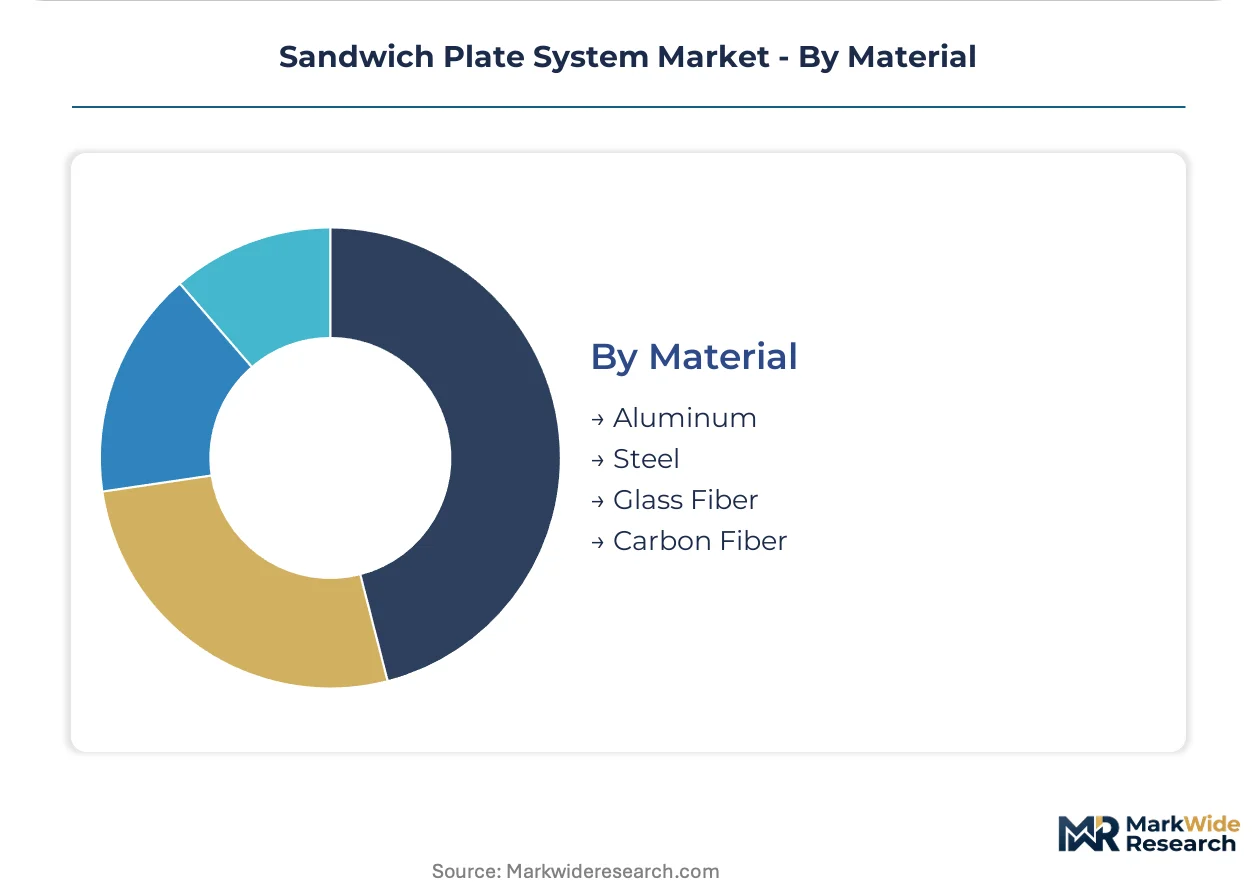
Material:
Corrosion resistance, specific strength, and recyclability tradeoffs position each alloy and fiber category in distinct specification tiers, with carbon fiber penetration limited to performance-premium segments by cost structure.
- Aluminum:5000 and 6000 series alloys deliver saltwater corrosion resistance with density advantages over steel. Recyclable honeycomb cores satisfy EU Green Deal embodied carbon rules for European marine newbuilds.
- Steel:High-strength low-alloy grades command blast-resistant and fire-rated specifications where thermal performance certification remains faster to obtain than composite alternatives. Offshore platform segments retain steel preference.
- Glass Fiber:E-glass and S-glass reinforced polymer face sheets balance cost and mechanical performance in commercial marine and architectural applications. REACH chemical restrictions force adhesive reformulation.
- Carbon Fiber:T700 and T800 grade prepregs achieve specific stiffness metrics for aerospace interiors and high-performance marine racing. Aramid fiber price volatility compresses margins for ballistic-grade suppliers.
Aluminum leads placement volume; Carbon Fiber shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian shipyard clusters concentrate production capacity while European yards drive specification innovation through regulatory carbon mandates. Consumption gravity splits between Korean and Japanese newbuild programs and Nordic offshore wind installation fleets.
South Korea
DSME and Hyundai Heavy Industries compress cruise vessel construction cycles through prefabricated deck panel procurement. The Ministry of Trade, Industry and Energy enforces dual carbon goals that redirect material selection toward recyclable core systems. Ulsan and Geoje shipyard clusters demand factory-integrated modules with elastomer core bonding automation.
Japan
JMU and Imabari Shipbuilding outsource complete superstructure modules to certified bonding specialists for newbuild programs. METI industrial standards govern face-to-core delamination thresholds in commercial marine approvals. Nagasaki and Yokohama manufacturing zones anchor specification pull for lightweight hull structures in LNG carrier segments.
Germany
Meyer Werft and Flensburger Schiffbau-Gesellschaft specify thermoplastic elastomer cores for EU Green Deal compliance in passenger vessel newbuilds. ECHA REACH chemical restrictions force adhesive reformulation among core suppliers serving North Sea offshore platforms. Papenburg and Flensburg shipyards lead factory-integrated panel bundling adoption.
Norway
Ulstein and Vard expand jack-up fleet capacity for offshore wind installation, creating demand for heavy-duty sandwich plate decking with integrated cable management. DNV classification society rules enforce stringent bond testing requirements that filter subscale manufacturers. Alesund and Bergen maritime clusters concentrate engineering expertise for arctic specification decks.
United States
Gulf Coast shipyards retrofit existing tanker fleets with lightweight deck replacements to meet IMO Energy Efficiency Existing Ship Index carbon intensity reductions. EPA environmental compliance programs influence material selection for naval vessel protection systems. Houston and New Orleans industrial corridors sustain demand for blast-resistant metal-faced specifications in offshore platform helidecks.
Sandwich Plate System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The vendor base organizes around bonding automation capabilities and classification society certification holdings. Three archetypes dominate: steel mill-integrated producers leveraging metallurgical scale, construction materials conglomerates with cold-chain distribution networks, and marine-focused technology licensors with proprietary core bonding patents. Capacity expansion and geographic licensing agreements constitute the primary competitive moves as players seek to align production cadence with East Asian shipyard schedules.
Within the technology-licensing tier, SPS Technology represents the elastomer core bonding specialist archetype through its patented fabrication processes. Kingspan Group exemplifies the construction materials conglomerate model with European geographic concentration in cold-chain facility specifications. TATA Steel occupies a position among steel mill-integrated producers competing on manufacturing scale across infrastructure project segments. These three anchors illustrate how competitive positioning diverges between premium marine specifications and volume construction applications.
| Leading Market Players |
|---|
| IE-SPS |
| SPS Technology |
| Kingspan Group |
| Assan Panel |
| TATA Steel |
| ArcelorMittal |
| NCI Building Systems |
| Metecno |
| BASF |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers in South Korea and Japan anchor supply concentration around Ulsan and Geoje shipyard clusters, translating state-supported capacity expansion into disciplined pricing power for elastomer core bonding specialists while compressing margins for uncertified competitors.
Pricing Analysis
Margin tightening in factory-integrated panel tiers reflects East Asian shipyard procurement consolidation around certified bonding specialists with Lloyd's Register approvals. Three-tier pricing structure across premium marine, standard construction, and economy retrofit levels separates DNV-certified specifications from uncertified alternatives. Cost-down pressure on composite core categories accelerates because EU Green Deal embodied carbon rules force thermoplastic reformulation investments. Contractors managing legacy hull retrofits exhibit highest price sensitivity due to custom interface engineering overruns, while cruise vessel newbuild programs prioritize certification tier over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from South Korean and Japanese shipbuilders mandate multi-supplier qualification for elastomer core bonding processes, preventing single-source dependency despite geographic concentration. Supply draws from German adhesive formulators, Chinese aluminum honeycomb producers, and Norwegian aramid fiber specialists. Raw material dependencies span thermoplastic elastomer resins, high-strength aluminum alloys, and bio-based epoxy alternatives. Single-source vulnerability concentrates in patented bonding automation equipment. Distribution runs through factory-integrated module suppliers directly to shipyard assembly lines, displacing traditional component wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive bonding technician scarcity props pricing for certified specialists, constraining capacity expansion and sustaining margin premiums for automated production lines across the analysis window.
For Market Incumbents: Hedge against solid steel plate substitution in fire-rated offshore segments by deepening backward integration into recyclable thermoplastic core production. Expand capacity in Papenburg and Flensburg corridors to capture EU Green Deal compliance premiums. Defend certification moats through accelerated Lloyd's Register investment in novel core geometries. For New Entrants and Emerging Players: System integrators with bonding automation capabilities represent the most penetrable channel partner type for factory-integrated panel bundling. Target Nordic offshore wind installation vessel specifications where jack-up fleet expansion outpaces certified supplier capacity. Enter through thermoplastic elastomer core recycling program partnerships with German passenger vessel yards. For Investors and Strategic Acquirers: DNV approval timeline compression for sustainable material categories is the leading indicator that thermoplastic core specialists will command acquisition premiums. Five-to-ten year viability favors technology-licensing archetypes with patented elastomer bonding processes over steel mill-integrated commodity producers. Watch for Lloyd's Register fast-track designations as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Patented Bonding Automation Investment | Secures Lloyd's Register certification timelines for East Asian shipyard contracts. |
| Thermoplastic Core Recycling Program | Locks in EU Green Deal compliance premiums from German passenger vessel builders. |
| Geographic Licensing Agreement | Aligns production cadence with Ulsan and Geoje modular yard schedules. |
| Classification Society Certification Fast-Track | Compresses DNV delamination threshold approval for novel core geometries. |
| Factory-Integrated Panel Bundling Partnership | Captures value upstream from South Korean cruise vessel newbuild programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with shipyard procurement directors, adhesive bonding technicians, classification society surveyors, and thermoplastic core R&D leads with Lloyd's Register approval databases, ECHA REACH substance registrations, and Korean Ministry of Trade import statistics. Bottom-up vessel deck procurement estimates triangulated against top-down sandwich plate system production capacity assessments.
Data-stream reconciliation across product type, application, end user, material, and regional shipyard cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories weighted by EU Green Deal compliance intensity and IMO carbon intensity indicator retrofit cycles. Forecast inputs incorporated elastomer core bonding automation adoption curves and recyclable thermoplastic certification timeline compression.
Caveats apply where aramid fiber price volatility or Lloyd's Register approval delays could materially shift the outlook. Forecasts reflect assumptions around East Asian shipyard cluster expansion rates and Nordic offshore wind installation vessel procurement timelines. Deviation in EU Green Deal circular economy mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Girder Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Bridge Construction Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Glue Laminated Beams Market