
 Structural Steel Market | 2026-2036
Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Steel Market Analysis
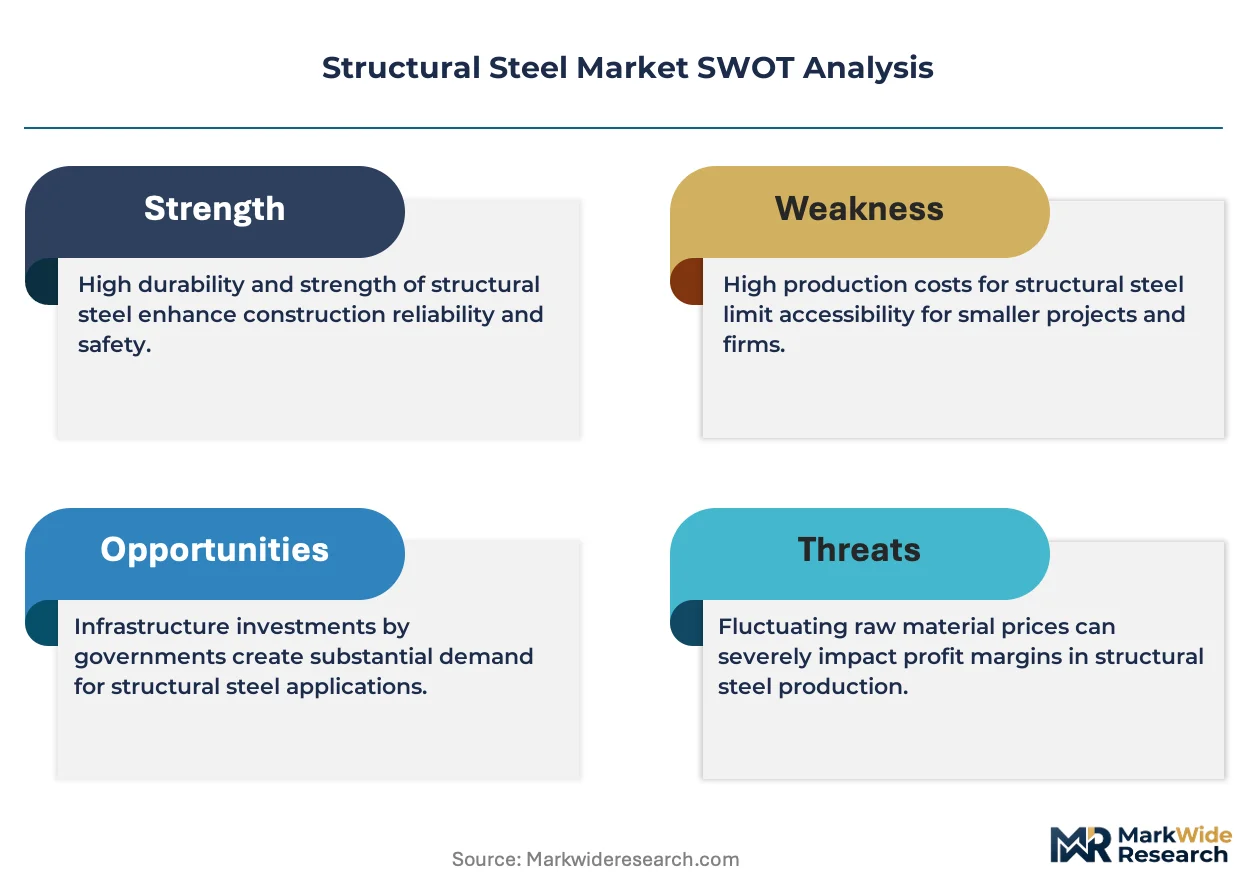
Maintenance and fabrication support services is pivoting how structural steel contracts are structured, shifting volume-based sales toward lifecycle partnerships. ArcelorMittal leverages its European service center network to anchor long-term supply agreements with engineering firms. Nucor Corporation sustains cost leadership through electric arc furnace flexibility across its southeastern US mills. POSCO competes on premium-grade beam consistency for high-rise projects in Northeast Asia.
Structural steel comprises carbon and low-alloy steel sections hot-rolled or welded to specified yield strengths, typically ranging from 250 to 690 MPa, engineered to bear compressive and tensile loads in framed construction. Hollow sections command premium pricing in infrastructure applications where torsional resistance and clean architectural lines reduce secondary fabrication. Channels and angle bars occupy mature replacement cycles in industrial facilities, while I-beams lead absolute tonnage across commercial building skeletons. Application splits show infrastructure outpacing residential structures in margin contribution due to specification complexity and longer contract tenors.
China's SAMR enforces updated GB standards for structural steel grades, while India's BIS mandates ISI certification for hot-rolled sections used in public works. The EU's Construction Products Regulation requires CE marking for steel sold into member state building projects. Buyers must track how carbon border adjustments and embodied carbon disclosure rules reshape supplier qualification criteria.
Market Dynamics
Seismic certification requirements from China's SAMR are compressing supplier qualification timelines while concentrating procurement authority among engineering firms capable of documenting full material traceability. This regulatory pressure is reshaping contract structures away from spot purchasing toward multi-year lifecycle partnerships.
Growth Catalysts
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade structural sections used in public infrastructure are accelerating domestic melt capacity additions along the Mumbai-Gujarat industrial corridor.
- GB 50011 seismic design standards:China's updated building code mandates Grade 400 MPa minimum yield strength for high-rise frames, forcing specification upgrades across commercial developments in Chengdu and Xi'an.
- Hollow section specification in bridge infrastructure:State highway authorities in Germany and Japan are specifying rectangular hollow sections for elevated expressway spans, prioritizing torsional rigidity and reduced maintenance access requirements.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when shredded auto scrap spreads widen beyond 15 percent of hot-rolled coil pricing, particularly affecting southeastern US production economics.
- Concentrated merchant bar supply:Long-product capacity in the EU clusters among three integrated producers, creating bottleneck risk for small-batch angle and channel orders required by industrial maintenance contractors.
- Composite floor deck substitution:Post-tensioned concrete slab systems are capturing mid-rise commercial projects below 12 stories where fire rating requirements and span flexibility outweigh steel speed-of-erection advantages.
Strategic Opportunities
- Vietnam's manufacturing corridor expansion:Industrial park developers in Bac Ninh and Hai Phong are specifying pre-engineered metal buildings for electronics assembly facilities, creating demand for standardized frame packages.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in for imported iron and steel is creating first-mover advantage for European mills with verified Scope 3 emissions data and renewable energy certificates.
- 3D detailing-to-fabrication workflow convergence:Building information modeling platforms linked directly to CNC plasma cutting lines are compressing engineering-to-delivery cycles for complex truss geometries in stadium and airport projects.
Industry Challenges
- Welding procedure qualification bottlenecks:Certified weld inspectors capable of interpreting EN 1090 execution class requirements remain scarce in Central and Eastern European fabrication shops, delaying CE marking for exported structural assemblies.
- Embodied carbon disclosure compliance:Project developers in France and the Netherlands must document cradle-to-gate emissions per ISO 14025, forcing steel suppliers to implement Environmental Product Declaration programs with third-party verification timelines exceeding 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Steel Market |
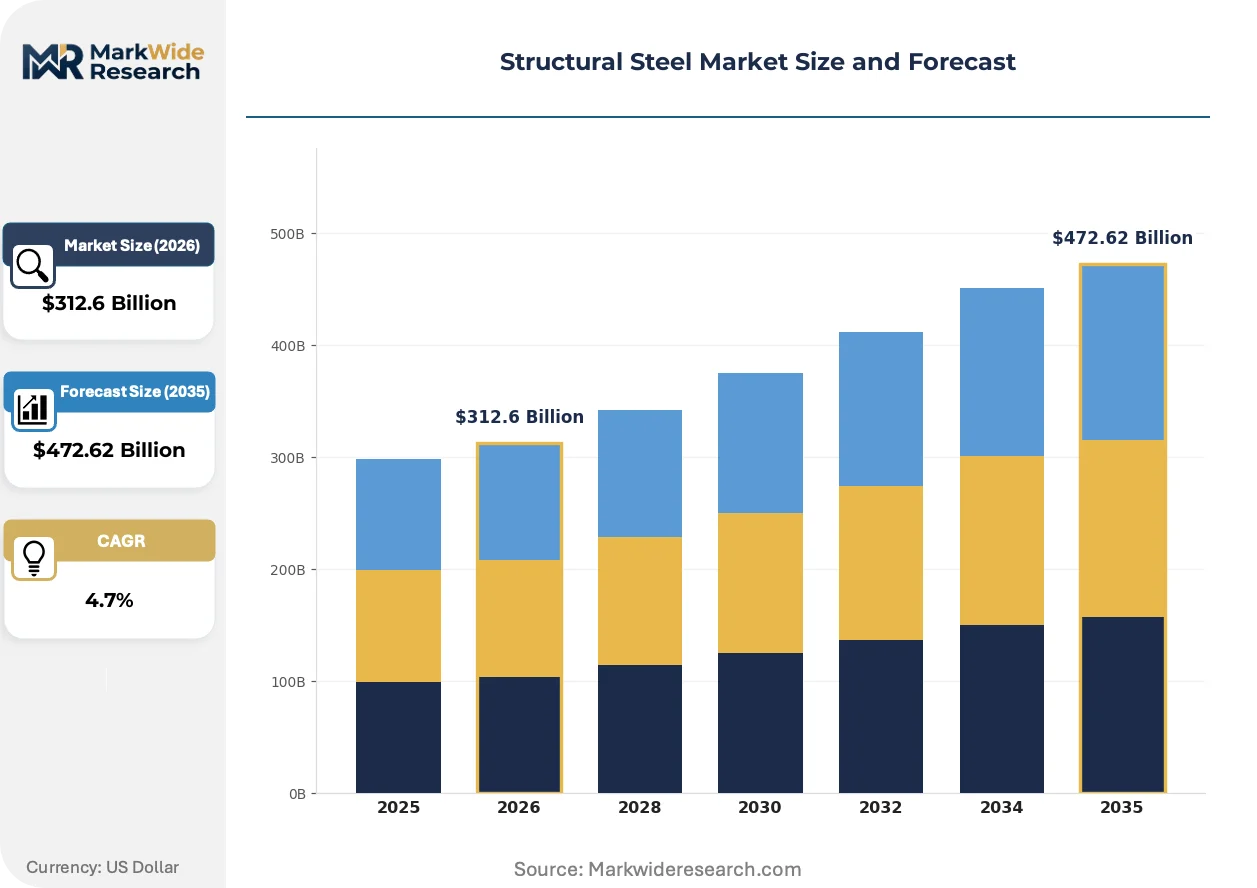
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: I-Beams, Channels, Angle Bars, Hollow Sections Application: Commercial Buildings, Residential Structures, Infrastructure, Industrial Facilities End User: Construction Companies, Engineering Firms, Fabricators, Contractors Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Retail Stores |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, Tata Steel, Hyundai Steel, Gerdau S.A., JSW Steel, Nucor Corporation, United States Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Steel Market Emerging Trajectories
Digital fabrication workflows and emissions transparency requirements are converging to redefine how structural steel is specified, procured, and certified across commercial and infrastructure verticals.
High-strength low-alloy grades with 690 MPa yield strength are expanding into long-span airport terminal roofs and stadium cantilevers where section depth constraints compete with load requirements. Japanese general contractors are specifying these grades for 2025-2028 Olympic venue retrofits in Tokyo and Sapporo, compressing beam counts by 30 percent compared to conventional 355 MPa designs. The technology is expanding into modular high-rise construction where reduced self-weight enables larger prefabricated floor cassettes.
The EU's Construction Products Regulation now mandates CE marking under EN 1090-1 for all structural steel components sold into member state building projects, with execution class EXC3 or EXC4 required for seismic zones. German and Italian engineering firms are pre-qualifying suppliers based on factory production control audits rather than traditional material test certificates alone. French public works contracts now require EPD verification as a technical bid evaluation criterion, favoring mills with renewable-powered electric arc furnace operations.
Lifecycle service contracts are displacing traditional tonnage-based purchasing in European commercial developments, with engineering-procurement-construction firms assuming responsibility for maintenance, inspection, and end-of-life decommissioning. Nucor Corporation and ArcelorMittal have established dedicated service center networks to anchor these arrangements, capturing recurring revenue streams beyond initial steel supply. The model is most visible in UK and German logistics warehouse developments where 25-year lease structures align with long-term structural performance guarantees.
Structural Steel Market Segmentation
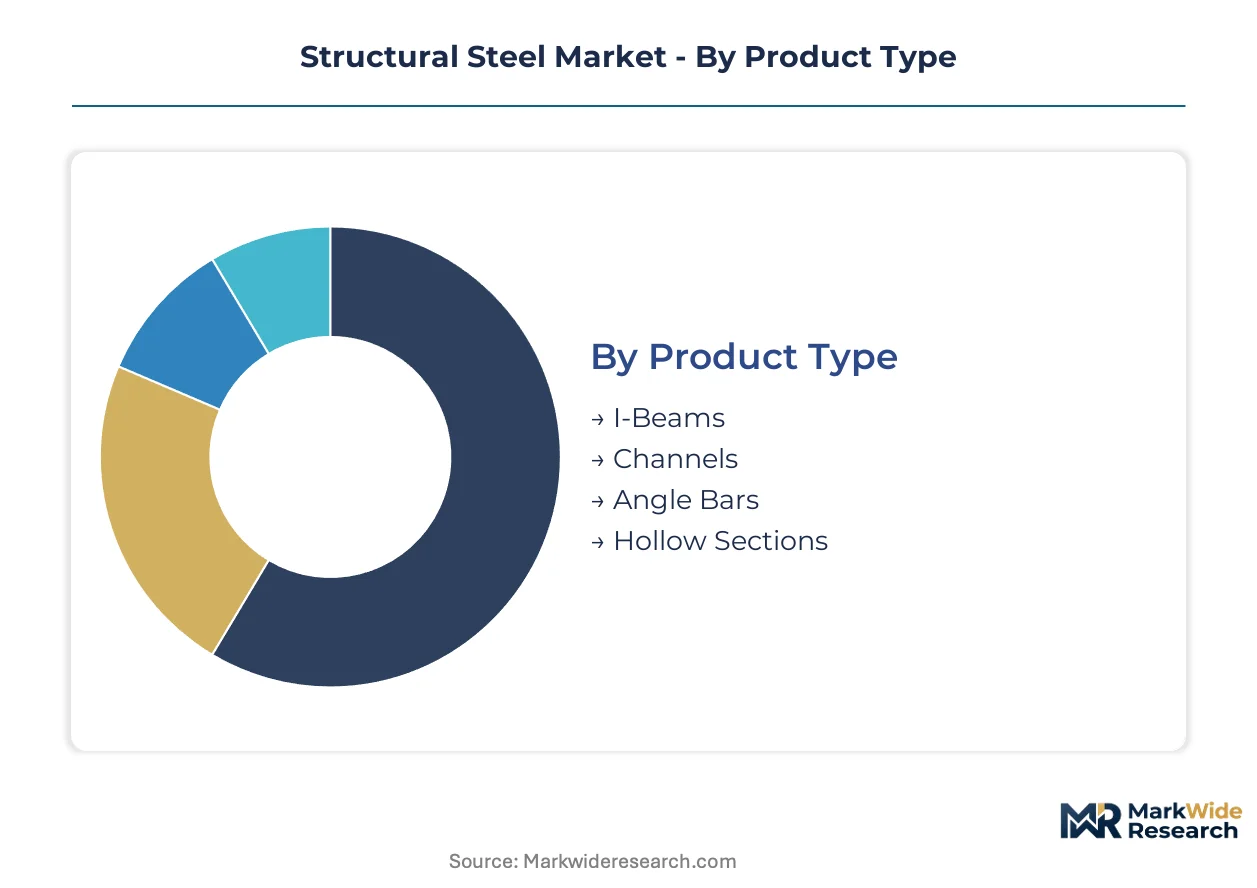
Structural steel procurement decisions cascade through multiple classification layers, each imposing distinct certification burdens and margin profiles. Specification engineers weight product geometry against load requirements while procurement teams navigate channel economics and end-user integration complexity.
Product Type:
CE marking under EN 1090-1 applies universally, yet execution class requirements vary sharply by section geometry. Hollow sections demand EXC3 or EXC4 factory production control for seismic applications, while merchant bars face lighter documentation burdens in industrial maintenance cycles.
- Hollow Sections:Rectangular and circular hollow sections deliver superior torsional rigidity with clean architectural lines that reduce secondary fabrication. Bridge authorities in Germany and Japan specify these for elevated expressway spans where maintenance access constraints favor enclosed geometries. Seismic zones require EXC4 execution class certification, compressing qualified supplier pools.
- I-Beams:Wide-flange sections dominate commercial building skeletons through standardized connection detailing and established erection protocols. India's western corridor from Mumbai to Gujarat concentrates demand for Grade 400 MPa minimum yield strength under tightening BIS certification timelines. GB 50011 compliance in China's high-rise markets forces specification upgrades.
- Channels:C-shaped sections serve industrial facility frameworks and equipment support structures with mature replacement cycles.
- Angle Bars:L-shaped profiles occupy maintenance and bracing applications where small-batch orders create supply bottlenecks in concentrated EU long-product capacity.
I-Beams sit at the top of the volume ranking, with Hollow Sections climbing the fastest.
Application:
Contract tenors and specification complexity create divergent margin profiles across end-use categories. Infrastructure projects embed multi-decade performance guarantees that reshape supplier qualification criteria.
- Infrastructure:Highway bridges, airport terminals, and stadium projects command premium pricing through specification complexity and extended contract durations. Japanese Olympic venue retrofits specify 690 MPa yield strength grades for long-span roof structures. EN 1090 execution class requirements and EPD verification under French and Dutch procurement rules concentrate procurement authority among integrated engineering firms.
- Commercial Buildings:High-rise frames and logistics warehouses drive absolute tonnage with standardized section requirements. China's GB 50011 seismic design standards mandate Grade 400 MPa minimum yield strength, forcing material upgrades in Chengdu and Xi'an developments. Lifecycle service contracts displace spot purchasing in UK and German logistics warehouse markets.
- Industrial Facilities:Manufacturing plants and process enclosures generate steady replacement demand with lighter certification burdens.
- Residential Structures:Mid-rise housing competes with post-tensioned concrete alternatives below 12 stories where fire ratings and span flexibility outweigh steel erection speed.
Commercial Buildings generate the largest revenue base, with Infrastructure expanding most quickly.
End User:
Procurement authority concentrates among actors capable of documenting full material traceability through fabrication and erection phases.
- Engineering Firms:Design-build and EPC contractors assume lifecycle responsibility for structural performance, anchoring multi-year supply agreements. ArcelorMittal leverages European service center networks to capture recurring revenue streams beyond initial steel supply. These firms pre-qualify suppliers based on factory production control audits rather than material test certificates alone.
- Construction Companies:General contractors coordinate steel procurement with erection sequencing, favoring suppliers with integrated fabrication capabilities. Nucor Corporation sustains cost leadership through electric arc furnace flexibility across southeastern US mills serving this channel.
- Fabricators:Specialist shops convert raw sections to finished assemblies, facing welding procedure qualification bottlenecks for EN 1090 CE marking.
- Contractors:Trade specialists execute field erection with tight coordination demands on delivery timing and section availability.
Construction Companies move the highest tonnage volumes, with Engineering Firms gaining procurement authority fastest.
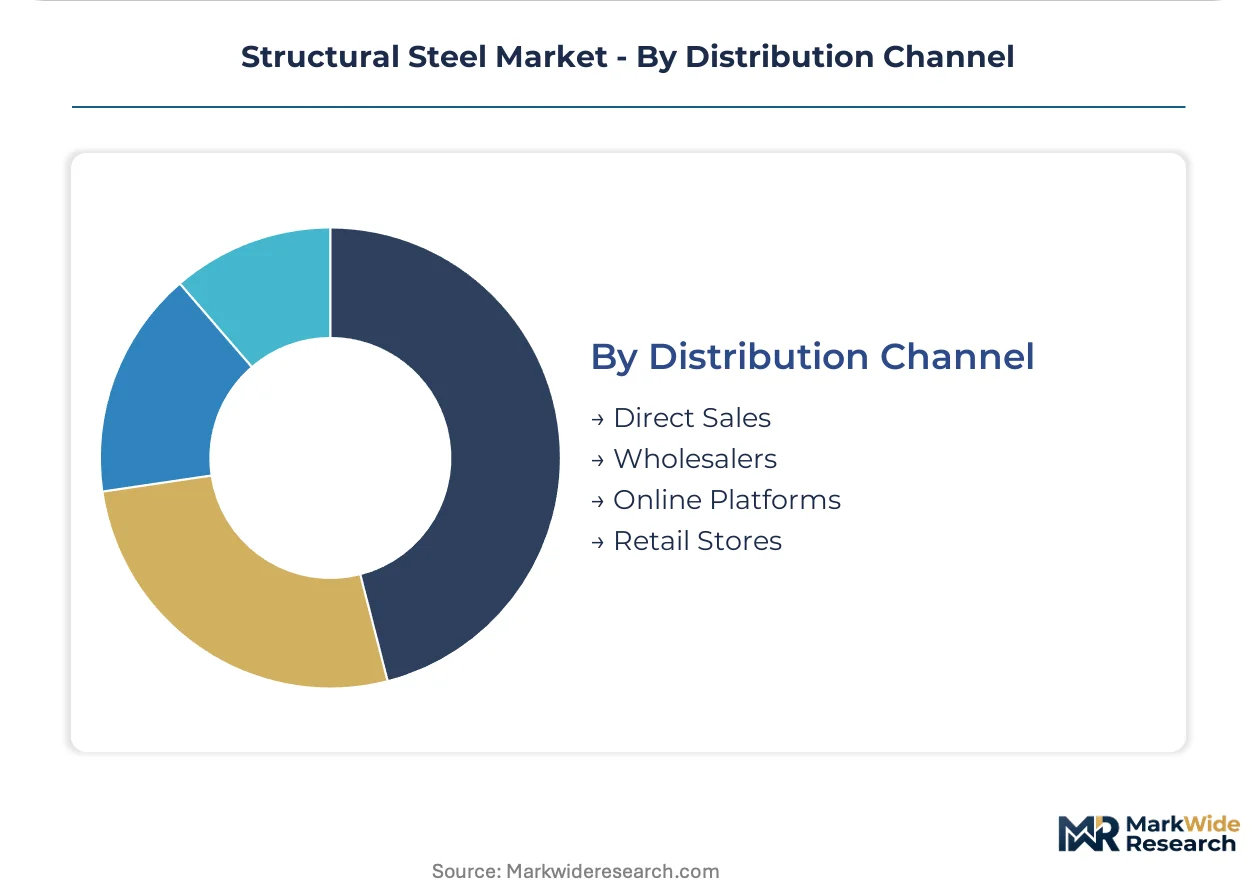
Distribution Channel:
Channel selection determines lead time reliability and technical support depth, with digital platforms emerging for standardized specifications.
- Direct Sales:Mill-direct relationships dominate large infrastructure and commercial projects requiring customized rolling schedules and certified material traceability. POSCO competes on premium-grade beam consistency for high-rise projects through direct channels.
- Wholesalers:Regional distributors stock standard sections for construction companies with predictable demand patterns and lighter documentation requirements.
- Online Platforms:Digital procurement channels gain traction for standardized pre-engineered metal building packages in Vietnam's Bac Ninh and Hai Phong manufacturing corridors.
- Retail Stores:Local outlets serve small-batch maintenance orders with limited technical support and spot pricing volatility.
Direct Sales commands the value premium, with Online Platforms expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where structural steel production concentrates, as mills migrate toward jurisdictions with lower carbon-compliance costs while buyers in stringent markets pay premiums for verified low-emission supply chains.
China
Seismic-resistant high-rise construction in Chengdu and Xi'an is driving specification upgrades to Grade 400 MPa yield strength under SAMR-enforced GB 50011 standards. The national regulator's tightened material certification timelines are compressing qualified supplier pools and forcing procurement consolidation among engineering firms with full traceability documentation. Production clusters in Hebei and Jiangsu provinces are investing in electric arc furnace conversions to meet dual carbon goals while maintaining export competitiveness.
India
Public infrastructure expansion along the Mumbai-Gujarat western corridor is accelerating demand for high-grade structural sections certified under BIS-mandated ISI standards. The national steel regulator's quality enforcement is tightening timelines for hot-rolled section approval in government contracts. Specialty steel production-linked incentives are attracting melt capacity additions to Dahej and Hazira industrial zones, with domestic mills capturing share from import-dependent project developers.
Germany
Bridge authorities specifying rectangular hollow sections for elevated expressway spans are prioritizing torsional rigidity and reduced maintenance access requirements under EN 1090 execution class standards. The EU's Construction Products Regulation mandates CE marking with factory production control audits favoring integrated producers. Ruhr Valley fabrication clusters face welding procedure qualification bottlenecks as certified inspectors capable of interpreting EXC3 and EXC4 requirements remain scarce.
United States
Southeastern mills serving commercial building developers are sustaining cost leadership through electric arc furnace flexibility amid volatile shredded auto scrap spreads. OSHA workplace safety enforcement and state-level building codes create uneven compliance burdens across regional markets. Gulf Coast industrial corridor expansions in Texas and Louisiana are driving demand for standardized frame packages in petrochemical and LNG facility construction.
Vietnam
Industrial park developers in Bac Ninh and Hai Phong are specifying pre-engineered metal buildings for electronics assembly facilities, creating demand for standardized structural steel frame packages. The national construction ministry's building code harmonization with ASEAN standards is simplifying import certification for Chinese and Korean mill supply. Northern manufacturing corridor growth is outpacing domestic long-product capacity, forcing reliance on cross-border procurement from integrated regional producers.
Structural Steel Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mills commanding premium positioning in specification-heavy infrastructure while regional fabricators compete on speed and customization for commercial building cycles. Market structure tilts toward consolidation at the melt stage, with long-product capacity clustering among three dominant archetypes: transnational diversified steelmakers with service center networks, electric arc furnace specialists with scrap-flexible cost structures, and state-linked Asian producers with captive raw material access. Competitive moves center on backward integration into scrap collection and renewable energy sourcing, plus geographic expansion through mill acquisitions in high-demand corridors.
Within the transnational diversified tier, ArcelorMittal and Nippon Steel Corporation exemplify the service-center-anchored model, using European and Japanese fabrication networks to lock in multi-year lifecycle contracts. POSCO represents the state-linked Asian archetype, occupying a position where premium-grade beam consistency for high-rise projects anchors direct sales relationships with engineering-procurement-construction firms. Nucor Corporation sits within the electric arc furnace specialist category, exemplifying how scrap-flexible southeastern US operations sustain cost leadership in commercial building segments with lighter certification burdens.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| Tata Steel |
| Hyundai Steel |
| Gerdau S.A. |
| JSW Steel |
| Nucor Corporation |
| United States Steel Corporation |
| Others |
Supply Flow & Price Mechanics
GB 50011 seismic certification mandates from China's SAMR are compressing qualified supplier pools and forcing procurement consolidation among engineering firms with full material traceability documentation, which concentrates pricing power among integrated mills capable of factory production control audits and EXC4 execution class certification.
Pricing Analysis
Distributor margin layers in structural steel vary sharply by certification burden, with three-tier pricing structure across premium, standard, and economy levels separating EXC4-certified hollow sections from merchant bars and spot-market angles. Price differentiation rests on EN 1090 execution class and BIS ISI certification timelines, with seismic-grade sections commanding substantial premiums over industrial maintenance grades. Cost compression in standard I-beams is intensifying because electric arc furnace operators face margin pressure when shredded auto scrap spreads widen. Small-batch industrial contractors prove most price-sensitive, while infrastructure EPC firms prioritize specification compliance over unit economics.
Supply Chain Analysis
Certification and qualification gating through EN 1090 factory production control audits and BIS ISI mark approvals concentrates supply authority among integrated producers with in-house metallurgical testing capabilities. Geographic supply concentration centers on China, India, and Germany, with Hebei and Jiangsu provinces, the Mumbai-Gujarat corridor, and Ruhr Valley fabrication clusters anchoring regional output. Raw material dependencies draw from iron ore pellets, shredded auto scrap, and ferroalloy additives. Single-source vulnerability persists in EU long-product capacity where three integrated producers dominate merchant bar supply. Distribution runs through mill-direct channels for infrastructure projects and regional wholesalers for commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural steel functions as a stable compounder anchored by infrastructure replacement cycles and seismic code upgrades that perpetually refresh specification demand across mature economies and emerging markets alike.
For Market Incumbents: Deepen backward integration into scrap collection networks and renewable energy sourcing to defend against carbon border adjustment exposure, while expanding service center footprints in India's western corridor to capture PLI-linked specialty steel demand. ArcelorMittal's European lifecycle partnership model offers a template for anchoring multi-year contracts with engineering-procurement-construction firms. For New Entrants and Emerging Players: Industrial maintenance contractors in Central and Eastern European fabrication shops represent an underserved buyer archetype facing acute welding procedure qualification bottlenecks for EN 1090 CE marking. Vietnam's Bac Ninh and Hai Phong manufacturing corridors offer penetrable geography for pre-engineered metal building packages, with digital procurement platforms enabling direct-to-fabricator distribution bypassing established wholesaler networks. For Investors and Strategic Acquirers: Asymmetric upside sits with electric arc furnace specialists with verified Scope 3 emissions data and renewable energy certificates, positioned for EU Carbon Border Adjustment Mechanism phase-in advantages. Five-to-ten year viability favors mills with captive scrap supply and high-grade structural section capabilities. Watch for BIS certification timeline tightening in Indian public works as an inflection signal for domestic capacity consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Collection | Secures feedstock cost stability for electric arc furnace operators facing shredded auto scrap volatility. |
| Renewable Energy Certificate Procurement | Enables EU CBAM compliance and EPD verification under French and Dutch procurement rules. |
| Service Center Network Expansion | ArcelorMittal leverages European fabrication networks to anchor multi-year lifecycle contracts with EPC firms. |
| EN 1090 EXC4 Certification Investment | Unlocks seismic-zone infrastructure procurement where qualified supplier pools remain compressed. |
| 3D Detailing-to-Fabrication Platform Integration | Compresses engineering-to-delivery cycles for complex truss geometries in stadium and airport projects. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with steel procurement managers at engineering-procurement-construction firms, plant managers at integrated mills, certified weld inspectors at fabrication shops, and regulatory affairs leads at national standards bodies with secondary validation from customs trade data, BIS certification registries, SEC 10-K filings, and EN 1090 factory production control audit records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated volume and value estimates.
Segment-weighting approaches applied product type, application vertical, end-user procurement authority, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from regression against construction output indices, infrastructure investment flows, and steel intensity per square meter by building type. Forecast inputs incorporated PLI scheme disbursement timelines, GB 50011 adoption curves, and electric arc furnace capacity conversion schedules.
Underlying measurement precision varies by segment; infrastructure and commercial building applications carry tighter precision than residential substitution dynamics. Forecasts reflect documented assumptions regarding scrap price elasticity, certification timeline enforcement, and carbon border adjustment implementation scope. A model refresh is warranted upon material change in BIS ISI mark approval timelines or EU CBAM phase-in acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
UK Facade Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Fabricated Structural Steel Market