
 Global Concrete Contractor Market | 2026-2036
Global Concrete Contractor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Contractor Market Analysis
Data center developers are rotating toward specialized concrete contractors as hyperscalers expand capacity. CRH leverages its vertically integrated cement-to-concrete network to capture premium infrastructure projects. Heidelberg Materials anchors European low-carbon concrete demand through its ECOPact product line. UltraTech Cement dominates Indian industrial flooring and foundation work through captive ready-mix capacity.
A concrete contractor executes the placement, finishing, and curing of Portland cement-based mixtures with specified compressive strengths typically ranging from 3,000 to 6,000 psi for structural applications. The primary purpose spans foundations, pavements, structural frames, and precast elements across building and civil engineering projects. Infrastructure work leads by project volume due to highway, bridge, and utility investments across multiple continents. Precasting technology is accelerating fastest as off-site fabrication reduces labor exposure and accelerates schedules. Design-build contracts concentrate margin pools by bundling engineering risk with construction execution.
The EPA enforces Buy Clean procurement standards that restrict embodied carbon in federally funded concrete, while the EU Green Deal's carbon border adjustments pressure import-dependent contractors to certify supply chain emissions. India's BIS mandates IS 456 compliance for reinforced concrete work, creating certification barriers for uncredentialed regional operators. China's MEE enforces dual carbon goals that constrain high-emission ready-mix plants near urban centers. Stakeholders must monitor how fragmented local permitting interacts with tightening national decarbonization timelines to avoid stranded equipment investments.
Market Dynamics
Carbon accounting mandates are fragmenting procurement specifications across federal, state, and municipal tiers, forcing contractors to maintain parallel compliance systems for embodied emissions tracking.
Growth Catalysts
- Data center hyperscaler expansion:Cloud infrastructure buildouts in Northern Virginia, Frankfurt, and Singapore require specialized high-load foundation work with accelerated curing protocols.
- Buy Clean procurement standards:EPA enforcement of embodied carbon limits on federally funded projects creates certified contractor preference tiers in US infrastructure awards.
- Low-carbon concrete mandates:California's SB 596 and New York's Local Law 97 impose compliance deadlines that rotate demand toward suppliers with verified Environmental Product Declarations.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production concentrates cost exposure in European and Chinese supply basins subject to carbon border adjustments.
- Regional supply concentration:Ready-mix capacity clusters within 90-minute haul radius of urban demand centers, constraining project mobility and bidding flexibility.
- Labor productivity ceilings:Mechanical compaction and finishing remain partially manual, limiting throughput scaling against fixed project timelines.
Strategic Opportunities
- Carbon capture utilization in concrete:CO2 mineralization during mixing creates performance-grade products qualifying for green procurement premiums in public works.
- Modular precast expansion:Off-site fabrication of structural elements compresses site schedules and reduces weather-dependent labor exposure.
- India's industrial corridor buildout:Dedicated freight corridors and semiconductor fabrication parks generate multi-year foundation and flooring contracts.
Industry Challenges
- EPD certification backlog:Third-party verification timelines for Environmental Product Declarations lag project bid windows, excluding uncredentialed contractors from qualified bidder pools.
- Equipment stranding risk:Diesel-powered mixer fleets face municipal zero-emission zones in Shanghai, Los Angeles, and London with accelerated compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Contractor Market |
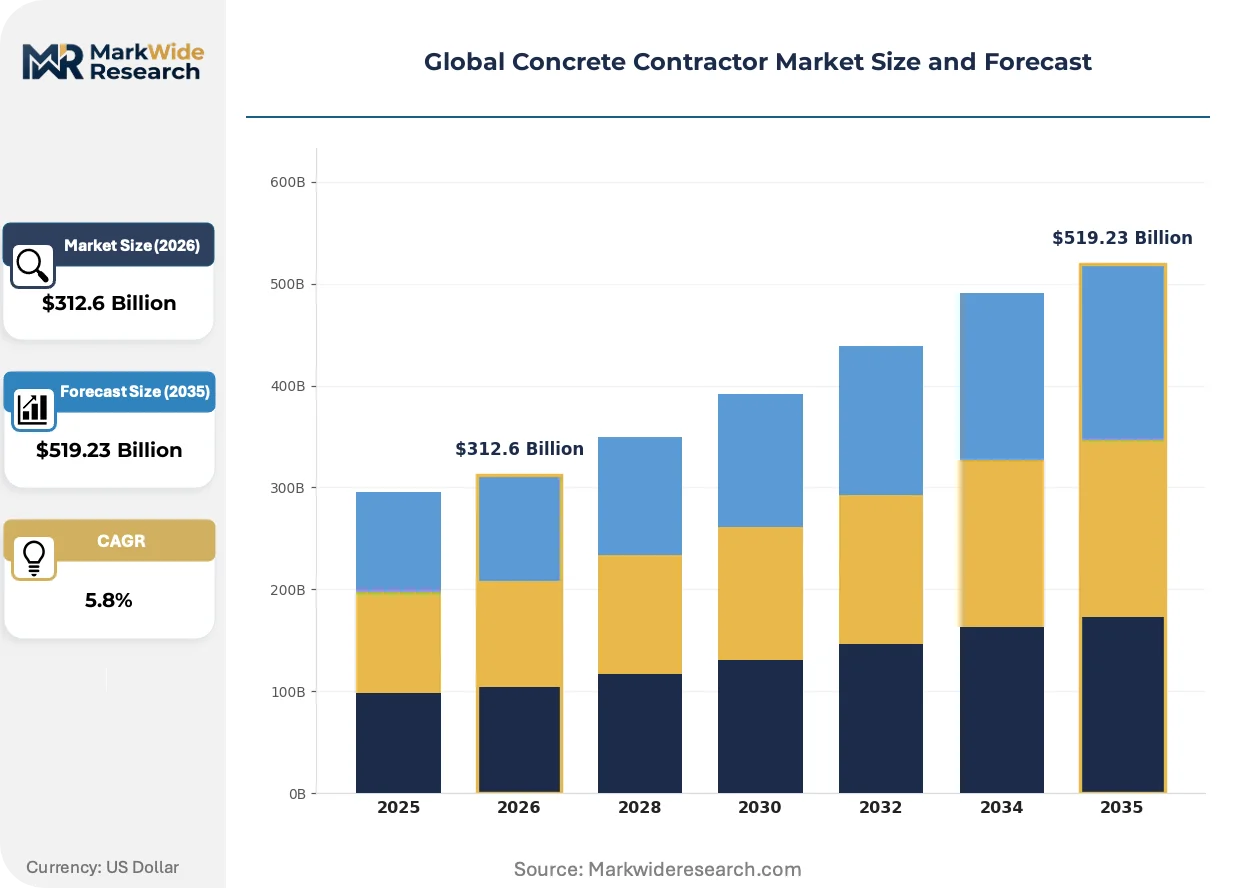
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Industrial, Infrastructure Project Size: Small, Medium, Large, Extra-Large Contract Type: Design-Build, General Contracting, Construction Management, Design-Bid-Build Technology: Casting, Precasting, 3D Printing, Pumping |
| Companies Covered | CRH, Anhui Conch Cement, Holcim, Votorantim Cimentos, UltraTech Cement, Heidelberg Materials, China National Building Material, Titan Cement, CEMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Contractor Market Emerging Trajectories
Digital fabrication and alternative binder chemistries are compressing traditional placement timelines while regulatory pressure on embodied carbon forces material specification changes upstream of contractor procurement.
Geopolymer and alkali-activated binder systems are decomposing the Portland cement monopoly in structural precast applications. Data center developers in Northern Virginia and Amsterdam are specifying these mixes for foundation mat pours to meet corporate net-zero commitments. The technology is decomposing century-old supply relationships between ready-mix incumbents and general contractors.
EU Green Deal carbon border adjustments are reshaping import economics for cementitious materials entering European project sites. Contractors sourcing from non-EU kilns now face documentation burdens and tariff exposure that domestic producers exploit in competitive bidding. German and French infrastructure authorities are accelerating local supply preference clauses in response.
Performance-based specifications are displacing prescriptive mix designs in US federal and state transportation contracts. Highway agencies in Texas, California, and Florida now accept contractor-proposed alternatives meeting durability benchmarks rather than mandating minimum cement content. This shift rewards firms with in-house materials engineering capabilities and compresses margins for specification-following competitors.
Global Concrete Contractor Market Segmentation
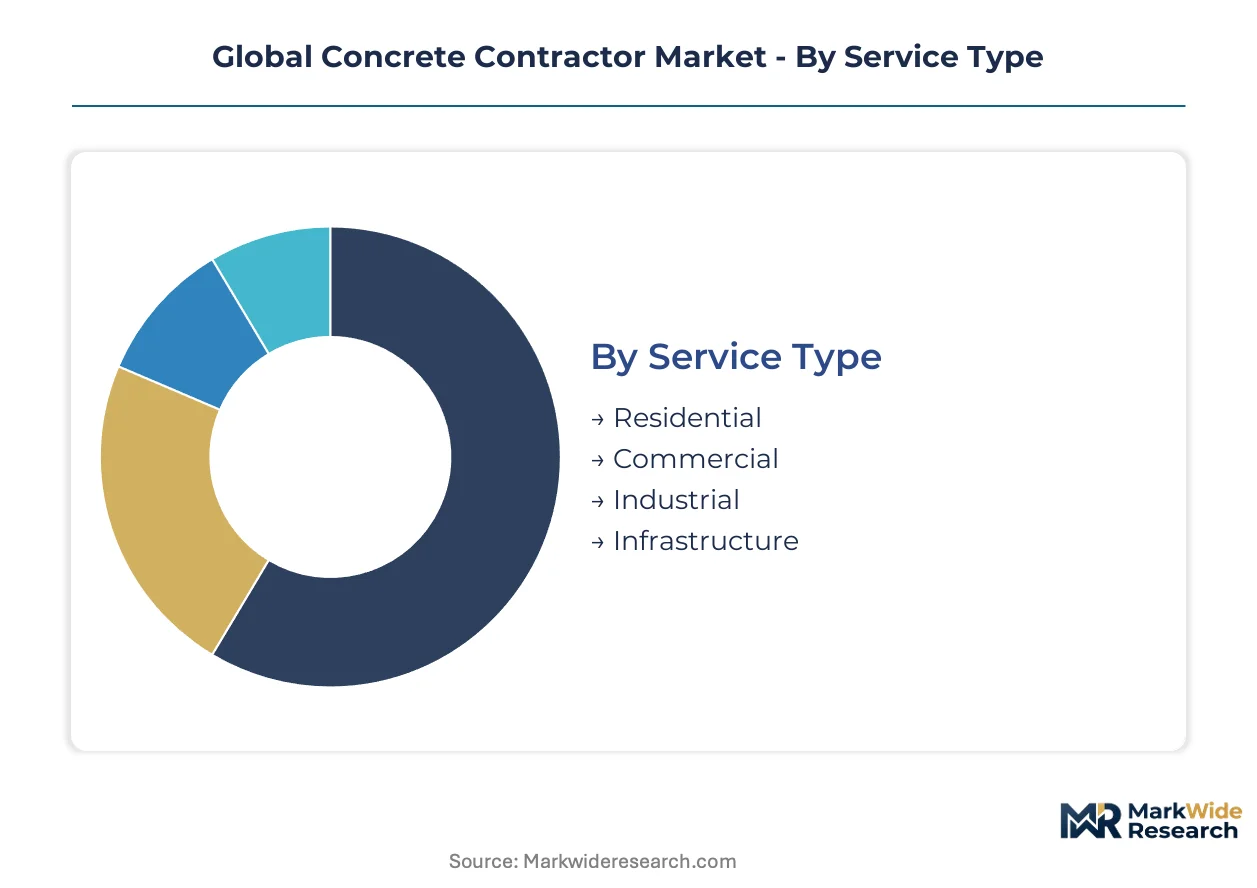
Concrete contractor specialization determines margin capture and equipment utilization across divergent project workflows. Segmentation reveals how service mix, scale thresholds, and technology adoption separate premium-positioned operators from specification-following competitors.
Service Type:
Residential concrete work faces the strongest substitution pressure from prefabricated foundation systems and modular construction methods that bypass on-site placement entirely.
- Residential:Single-family foundations, driveways, and decorative flatwork dominate this tier, with demand clustering in suburban expansion corridors around Dallas-Fort Worth and Bangalore where housing starts outpace commercial permits. Labor intensity and weather exposure compress margins relative to other service tiers.
- Commercial:Office buildings, retail centers, and hospitality projects require higher-strength specifications and accelerated curing protocols to meet tenant delivery schedules. This segment captures premium pricing in data center-adjacent markets where hyperscalers demand specialized high-load foundation expertise.
- Industrial:Manufacturing floors, warehouse slabs, and heavy equipment foundations specify 4,000+ psi concrete with fiber reinforcement for abrasion resistance.
- Infrastructure:Highway paving, bridge decks, and utility structures carry the longest project durations and most stringent Buy Clean compliance requirements.
Infrastructure anchors the volume base while Commercial gains share at the steepest rate.
Project Size:
Cost tier stratification separates equipment-heavy operators capable of continuous pour logistics from labor-dependent regional contractors.
- Extra-Large:Airport runways, nuclear containment structures, and major highway interchanges require dedicated batch plants, specialized pumping equipment, and multi-shift crews coordinated across months-long schedules. Only vertically integrated national operators or consortiums qualify for this tier.
- Large:Industrial campuses, distribution centers, and mid-rise commercial structures represent the optimal scale for ready-mix utilization and fleet amortization. Contractors in this tier balance in-house engineering with subcontracted specialty trades.
- Medium:Local commercial builds and multi-family residential projects constitute the most competitive bidding environment.
- Small:Residential repairs, decorative concrete, and minor flatwork serve as entry points for independent operators with minimal capital requirements.
Large projects anchor the volume base while Extra-Large contracts expand most quickly as infrastructure megaprojects proliferate.
Contract Type:
Customer type preferences are fragmenting across public and private procurement channels with divergent risk allocation models.
- Design-Build:Single-source responsibility for engineering and construction compresses schedules and concentrates margin pools for contractors with in-house design capabilities. This model dominates data center and industrial projects where speed-to-market outweighs first-cost optimization.
- Construction Management:Owner-contractor collaboration with transparent cost-plus fee structures attracts sophisticated clients seeking schedule control without assuming full construction risk. This approach expands in healthcare and institutional builds.
- General Contracting:Traditional fixed-price arrangements with owner-supplied designs remain standard for public infrastructure and standardized commercial work.
- Design-Bid-Build:Sequential procurement with lowest-responsive-bid award mechanics persists in municipal and federal projects subject to competitive bidding statutes.
Design-Build anchors the volume base while Construction Management climbs the fastest among private institutional clients.
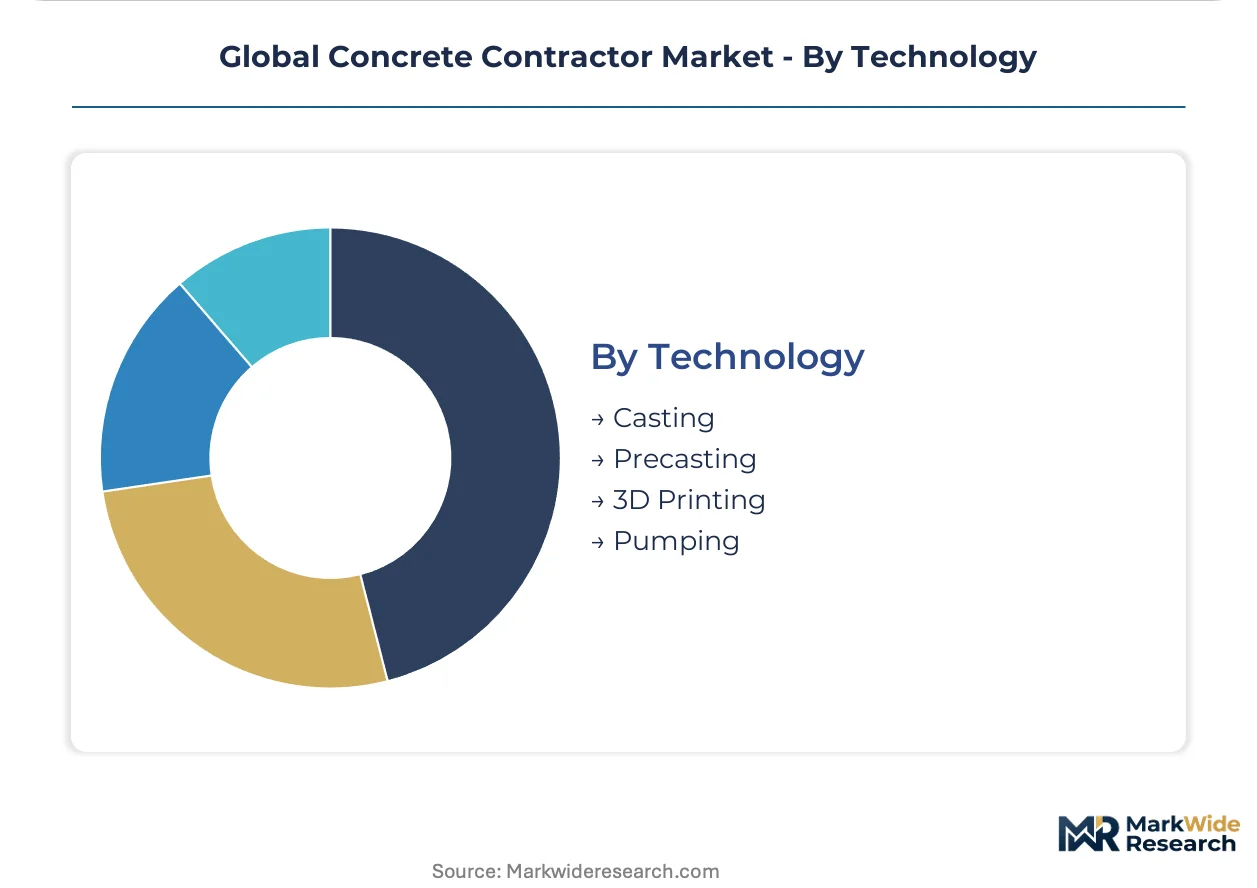
Technology:
Application maturity varies sharply across placement methods, with some technologies displacing century-old practices while others remain confined to niche demonstration projects.
- Precasting:Off-site fabrication of structural elements in climate-controlled plants eliminates weather exposure and accelerates site schedules. This technology is expanding fastest in European and North American markets where labor constraints and quality consistency drive adoption for bridge beams, wall panels, and foundation elements.
- Pumping:Truck-mounted boom and line pumps enable continuous placement at heights and distances impossible with crane-and-bucket methods. This capability is essential for high-rise cores and remote infrastructure sites where mixer truck access is constrained.
- Casting:Conventional form-and-pour methods persist across residential and small commercial work where equipment minimization preserves bidding flexibility.
- 3D Printing:Layered deposition of cementitious materials remains experimental for structural applications, constrained by build speed limitations and code approval gaps.
Casting anchors the volume base while Precasting gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican cement exports flow into US border states where infrastructure and industrial buildouts absorb cross-border supply. Trade corridors concentrate contractor activity near major consumption clusters.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives specialized foundation demand. EPA Buy Clean standards enforce embodied carbon limits on federally funded highway and bridge work. California's SB 596 mandates low-carbon concrete compliance deadlines that rotate procurement toward certified contractors.
China
Dual carbon goals from MEE constrain high-emission ready-mix plants near Shanghai and Beijing urban centers. Infrastructure stimulus in western provinces sustains multi-year contractor backlogs for highway and utility projects. Yangtze River Delta manufacturing clusters generate industrial flooring specifications.
India
Dedicated freight corridors and semiconductor fabrication parks create sustained foundation and flooring demand. BIS mandates IS 456 compliance for reinforced concrete work, erecting certification barriers for uncredentialed regional operators. Gujarat and Maharashtra industrial zones concentrate captive ready-mix capacity.
Germany
EU Green Deal carbon border adjustments reshape import economics for cementitious materials entering project sites. Federal transport ministries accelerate local supply preference clauses in competitive bidding. Rhine-Ruhr industrial corridors anchor precast fabrication clusters serving Dutch and Belgian markets.
UAE
NEOM and Red Sea Project megaprojects generate extra-large contract opportunities for specialized foundation contractors. Municipal zero-emission zones in Dubai and Abu Dhabi accelerate diesel fleet replacement timelines. Saudi cross-border material flows supply concrete for giga-project concrete demand.
Global Concrete Contractor Market Vendor Landscape
Player mix skews toward vertically integrated cement-to-concrete networks with captive raw material supply. Market structure concentrates around national champions controlling batch plant networks within 90-minute haul radii of urban demand centers. Two strategic archetypes dominate: diversified building materials conglomerates with infrastructure project capabilities, and regional ready-mix specialists with local permitting relationships. Competitive moves center on M&A for geographic density and carbon capture technology licensing for green procurement qualification.
Within the diversified conglomerate tier, CRH and Heidelberg Materials occupy positions exemplifying backward integration from cement production into project execution. Among emerging market specialists, UltraTech Cement anchors Indian industrial flooring demand through captive capacity. CEMEX represents the scale-driven archetype with cross-border project logistics capabilities spanning North American and European markets.
| Leading Market Players |
|---|
| CRH |
| Anhui Conch Cement |
| Holcim |
| Votorantim Cimentos |
| UltraTech Cement |
| Heidelberg Materials |
| China National Building Material |
| Titan Cement |
| CEMEX |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between hyperscale data center developers and specialized concrete contractors lock in multi-year supply access while anchoring price visibility against Portland cement volatility. These arrangements concentrate bargaining power with buyers who bundle foundation, flooring, and structural work into single-source contracts, compressing margins for specification-following competitors unable to offer integrated project delivery.
Pricing Analysis
Current-generation low-carbon concrete commands premium positioning against conventional Portland cement mixes and emerging geopolymer alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified suppliers from regional ready-mix operators and uncredentialed independents. Price differentiation hinges on certification grade and geographic delivery cost, with carbon-accounting compliance intensifying cost compression in the standard tier. Public infrastructure agencies exhibit highest price sensitivity due to competitive bidding statutes, while data center hyperscalers prioritize performance guarantees over first-cost optimization.
Supply Chain Analysis
China, India, and the United States anchor global clinker production and ready-mix concrete distribution networks. The supply chain draws from limestone quarries, energy-intensive kiln operations, and regional batch plant networks within 90-minute haul radii of urban demand centers. Single-source vulnerability concentrates in Portland cement supply basins subject to carbon border adjustments and energy price shocks. Distribution runs through vertically integrated cement-to-concrete networks and independent ready-mix specialists serving localized project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around hyperscale data center developers and federal infrastructure agencies that bundle multi-year concrete work into single-source contracts, fragmenting pricing power across the contractor base.
For Market Incumbents: Shield margin pools by deepening backward integration into low-carbon binder production and accelerating EPD certification timelines ahead of state mandate deadlines. Defensive positioning requires captive supply of supplementary cementitious materials to offset Portland cement price volatility, while channel control through design-build relationships protects against emerging precast specialists. For New Entrants and Emerging Players: Differentiate on carbon capture utilization technology and modular precast fabrication capabilities to bypass entrenched ready-mix relationships. The most penetrable white space sits in data center-adjacent foundation work requiring accelerated curing protocols, with go-to-market traction achievable through direct contracting with hyperscalers seeking specialized high-load expertise outside legacy supplier networks. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors vertically integrated operators with certified low-carbon supply chains and captive raw material access. Long-term viability centers on consolidation plays for regional ready-mix density and technology licensing for CO2 mineralization processes. The signal to watch is municipal zero-emission zone enforcement timelines that strand diesel-powered fleet assets.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Utilization Licensing | CO2 mineralization technology unlocks green procurement premiums in EPA Buy Clean infrastructure awards. |
| Modular Precast Capacity Expansion | Off-site fabrication compresses data center schedules and reduces weather-dependent labor exposure. |
| Backward Integration into SCM Supply | Captive fly ash and slag sourcing hedges Portland cement price volatility from energy cost shocks. |
| EPD Certification Acceleration | Third-party verification enables bidding in California SB 596 and New York Local Law 97 compliance pools. |
| Zero-Emission Fleet Transition | Electric mixer deployment preserves market access in Shanghai, Los Angeles, and London municipal zones. |
Methodological Framework
Operator-level perspectives from batch plant managers, data center construction directors, public works procurement officers, and precast fabrication engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement records, state infrastructure procurement databases, cement industry trade association filings, and customs data on clinker imports. Bottom-up project pipeline analysis triangulated against top-down cement consumption forecasts to establish volume and value estimates.
Sensitivity analysis tested forecast robustness across varying assumptions for carbon accounting mandate adoption rates and hyperscale data center capex cycles over the projection horizon. The analytical framework modeled segmentation across service type, project size tier, contract structure, and placement technology, with regional regulatory clusters as an additional dimension. CAGRs derived from trend extrapolation of historical cement consumption patterns adjusted for policy-driven demand shifts, incorporating clinker substitution rates and precast adoption curves as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure stimulus and enforceable low-carbon procurement deadlines would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance timelines and energy transition pathways for kiln operations. Recalibration cycles align with material shifts in EPA Buy Clean enforcement intensity and state-level embodied carbon mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Supported Scaffolding Market
Structural Construction
H Beam Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Canada Composite Repair Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
GCC Structural Steel Fabrication Market