
 UAE Prefabricated Building and Structural Steel Market | 2026-2036
UAE Prefabricated Building and Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Prefabricated Building and Structural Steel Market Intelligence
The gap between premium engineered systems and commodity-grade panelized units is rebalancing as project owners demand faster certification cycles. Emirates Steel anchors the upstream supply chain through its integrated melt shop and rolling mill complex in Abu Dhabi. Al Jazeera Steel Products differentiates through specialized cold-formed sections for warehousing and logistics infrastructure. Al Futtaim Engineering competes by controlling distribution networks across the northern emirates.
Prefabricated building and structural steel encompasses factory-manufactured structural members and volumetric modules designed for rapid site assembly, typically fabricated from hot-rolled sections, cold-formed profiles, or composite sandwich panels with specified fire ratings and thermal performance. These systems serve commercial and industrial construction where schedule compression and labor efficiency outweigh traditional cast-in-place methods. Modular buildings command premium margins due to MEP integration complexity and factory QA protocols, while steel frames dominate volume in warehouse and logistics applications. Panelized systems are gaining share in residential mid-rise projects where developers seek repeatable facade assemblies with shorter cycle times.
MOHAP oversees construction product safety declarations, while the UAE's civil defense authorities enforce fire resistance testing for structural steel coatings and compartmentalization systems. Estidama Pearl Rating and Dubai Green Building Regulations mandate embodied carbon thresholds that filter out non-compliant imported modules. Stakeholders must track how federal procurement guidelines for government projects will privilege locally fabricated structural components over re-exported alternatives.
Market Dynamics
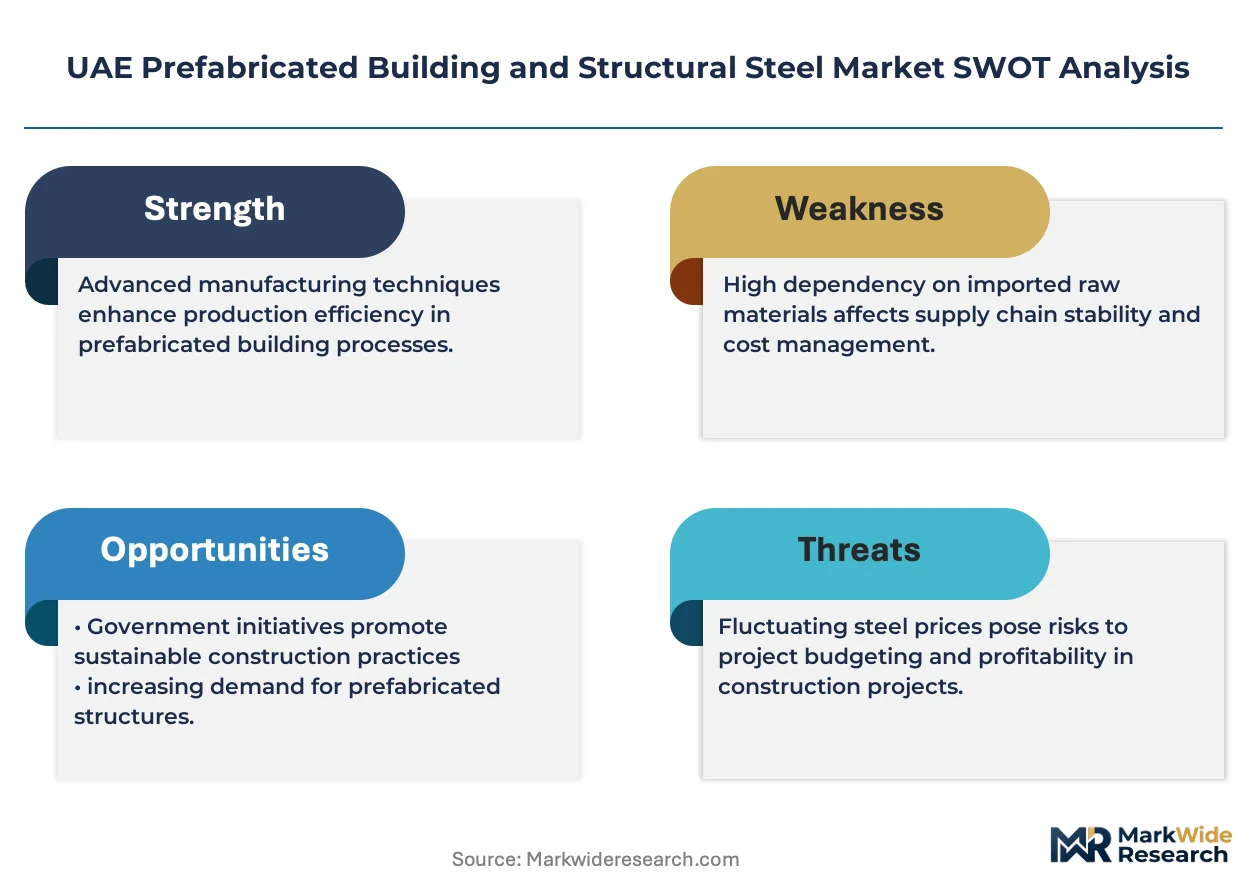
Estidama Pearl Rating and Al Sa'fat standards are compressing certification timelines while filtering out non-compliant imports, forcing developers to source locally fabricated modules with verified embodied carbon data.
Growth Catalysts
- Estidama Pearl mandates:Developers pursuing 2+ Pearl ratings must specify low-carbon structural steel and insulated panel systems, accelerating specification shifts across Dubai's mega-project corridor.
- Expo City redevelopment:The conversion of legacy exhibition infrastructure into permanent commercial and residential districts requires rapid-deployment volumetric modules with integrated MEP systems.
- South Dubai logistics zones:E-commerce fulfillment center construction is pulling cold-formed steel framing and clear-span warehouse structures at compressed schedules.
Market Restraints
- Scrap steel price volatility:Emirates Steel's melt shop operations face input cost swings tied to regional scrap collection rates and export competition from Turkish mills.
- Abu Dhabi supply concentration:Integrated primary steel production clusters in the emirate create geographic dependency for hot-rolled sections serving northern emirates projects.
- Fire resistance coating bottlenecks:Civil defense authority testing protocols for intumescent paints create certification queues that delay module release from fabrication yards.
Strategic Opportunities
- Ras Al Khaimah industrial expansion:The emirate's developing manufacturing zones lack established structural steel fabricators, creating first-mover positioning for panelized system providers.
- Building-integrated photovoltaics convergence:Prefabricated facade manufacturers combining sandwich panels with embedded solar laminates can capture premium margins in net-zero commercial projects.
- Federal procurement localization:Pending government project guidelines privileging UAE-fabricated components over re-exported alternatives will reshape competitive bidding dynamics.
Industry Challenges
- Welding certification scarcity:International Welding Engineer qualifications required for structural steel supervision remain underrepresented in the domestic workforce, constraining fabrication yard expansion.
- Legacy cast-in-place contractor resistance:Established construction firms with invested formwork and labor networks delay modular adoption, fragmenting project delivery methodologies.
- Estidama documentation burden:Pearl Rating submissions require granular embodied carbon calculations that many imported module suppliers cannot provide, disqualifying otherwise cost-competitive bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Prefabricated Building and Structural Steel Market |
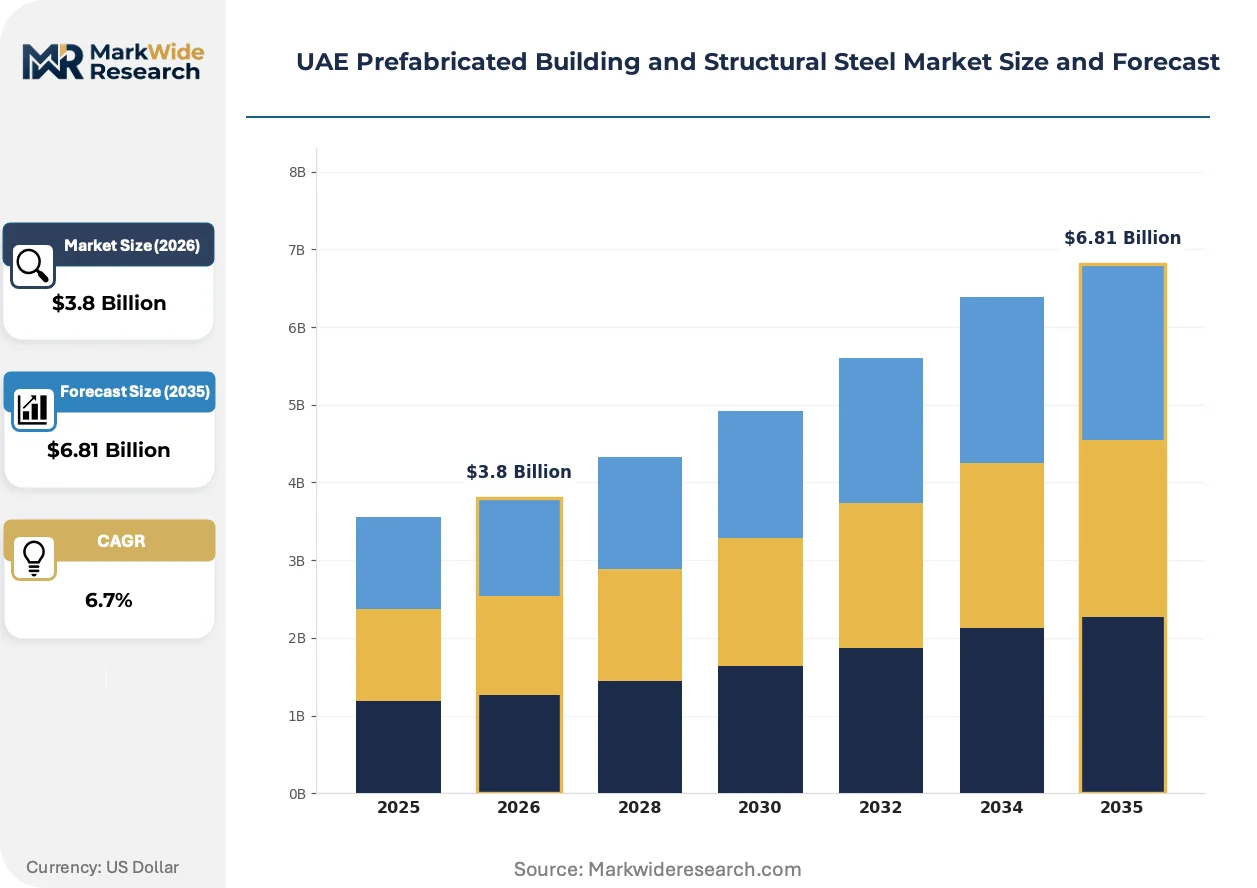
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Pre-Engineered Structures, Steel Frames, Panelized Systems Application: Residential Construction, Commercial Spaces, Industrial Facilities, Infrastructure Projects Delivery Mode: On-site Assembly, Off-site Fabrication, Hybrid Methods, Turnkey Solutions End User: Construction Companies, Real Estate Developers, Government Projects, Private Owners |
| Companies Covered | Al Habtoor Group, Al Mufeed Engineering, Emirates Steel, Al Maktoum Group, Al Qudra Holding, Al Jaber Group, Al Shafar General Contracting, Al Jazeera Steel Products, Al Futtaim Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Prefabricated Building and Structural Steel Market Strategic Shifts & Innovations
Digital fabrication workflows and material traceability systems are compressing design-to-delivery cycles while embedding compliance documentation directly into module specifications.
Building information modeling integrated with automated CNC plasma cutting is expanding into structural steel fabrication workflows. Mid-rise residential developers in Dubai's suburban corridors are adopting these digitally sequenced production methods to achieve facade tolerance guarantees. The technology is expanding into markets previously served by conventional stick-built framing, compressing competitive differentiation around schedule certainty.
Al Sa'fat technical guidelines for Dubai's building envelope performance are mandating thermal transmittance thresholds that disqualify conventional steel framing without continuous insulation breaks. Manufacturers are responding by engineering thermally broken connection details and composite panel assemblies. Residential mid-rise projects in Dubai South and Jebel Ali are experiencing the most acute specification pressure under these thermal mandates.
Developer procurement teams are consolidating vendor lists around fabricators with in-house engineering capabilities and direct Estidama documentation support. Traditional distributor-intermediary relationships are thinning as buyers seek single-point accountability for Pearl Rating compliance. This consolidation pattern is most visible among Dubai-based real estate developers managing multi-phase master plans with repeatable building typologies.
UAE Prefabricated Building and Structural Steel Market Segmentation
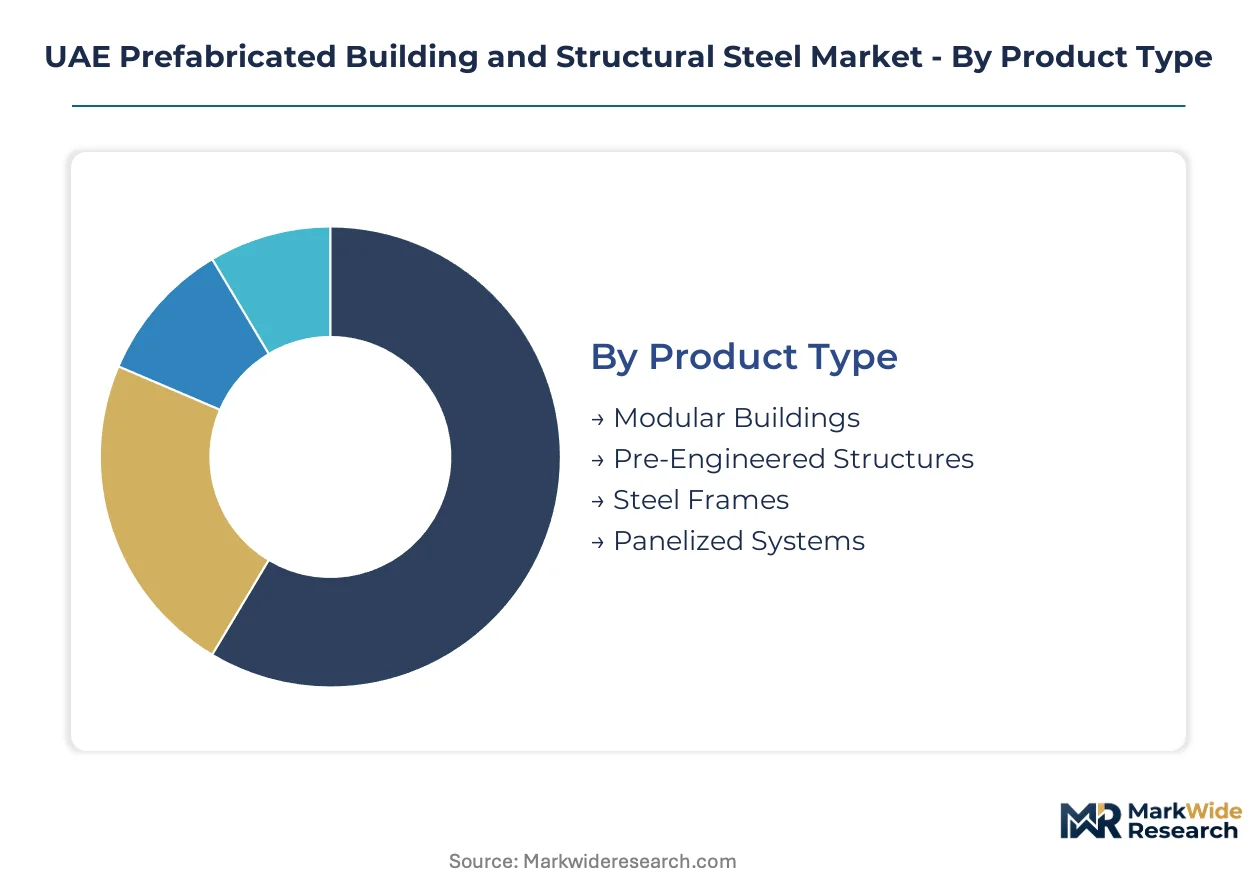
Segmentation in the UAE prefabricated building market reveals how procurement priorities diverge across project types. Buyers weigh speed-to-occupancy against certification complexity, with each segment demanding distinct fabrication capabilities and compliance documentation.
Product Type:
Buyers differentiate by the degree of factory completion they require before site delivery.
- Modular Buildings:Volumetric units with integrated MEP systems and interior finishes arrive 85-95% complete from fabrication yards. Expo City redevelopment projects specify these for hotel and residential towers where concurrent site preparation accelerates overall schedules. Estidama Pearl documentation requirements favor suppliers with captive engineering teams capable of embodied carbon calculations.
- Pre-Engineered Structures:Primary rigid frames with secondary purlins and girts engineered for specific load conditions dominate warehouse and logistics construction. South Dubai fulfillment centers specify these for clear-span requirements exceeding 40 meters. Delivery timelines compress to 8-12 weeks for repeat building typologies.
- Steel Frames:Hot-rolled and cold-formed structural members assembled on-site serve mid-rise residential and commercial projects where facade customization matters. Dubai South developers specify these for thermal break integration mandated by Al Sa'fat envelope standards.
- Panelized Systems:Factory-built wall, floor, and roof assemblies with specified insulation and fire ratings suit residential projects seeking repeatable facade modules. Jebel Ali corridor mid-rise developments are adopting these for Pearl Rating compliance without full volumetric complexity.
Pre-engineered structures lead volumes today; modular buildings are gaining share fastest.
Application:
Project owners segment by the regulatory intensity and speed requirements each building type demands.
- Residential Construction:Government-backed affordable housing initiatives in Dubai and Abu Dhabi specify prefabricated systems for schedule compression. MOHAP safety declarations and Estidama Pearl mandates filter supplier qualification, favoring fabricators with local engineering presence.
- Commercial Spaces:Office and retail developments in Dubai's mega-project corridor require rapid-deployment solutions with integrated MEP. Net-zero commercial projects are specifying building-integrated photovoltaic facades, combining sandwich panels with embedded solar laminates.
- Industrial Facilities:E-commerce fulfillment centers and manufacturing plants in South Dubai logistics zones pull clear-span steel structures. Cold-formed framing dominates for smaller warehousing in Ras Al Khaimah's developing industrial zones.
- Infrastructure Projects:Federal procurement guidelines for government projects privilege locally fabricated components, reshaping competitive bidding for bridges, utilities, and transport facilities.
Industrial facilities command the largest project scale; residential construction is expanding most quickly.
Delivery Mode:
Contractor capabilities and site constraints determine how fabrication and assembly responsibilities split.
- On-site Assembly:Fabricated members delivered as kits for field bolting and welding suits projects with established local labor networks. Legacy cast-in-place contractors often prefer this mode to preserve existing workforce relationships.
- Off-site Fabrication:Complete modules manufactured in controlled factory environments with full QA protocols command premium margins. Estidama documentation requirements and civil defense fire resistance testing favor this mode for Pearl-rated projects.
- Hybrid Methods:Structural frames fabricated off-site with panelized infill assembled on-site balances speed and customization. Dubai-based developers managing multi-phase master plans specify these for repeatable building typologies.
- Turnkey Solutions:Single-point accountability for design, fabrication, installation, and certification appeals to real estate developers consolidating vendor lists. Procurement teams are thinning traditional distributor relationships in favor of fabricators with in-house engineering.
On-site assembly retains the widest contractor base; turnkey solutions are climbing the fastest.
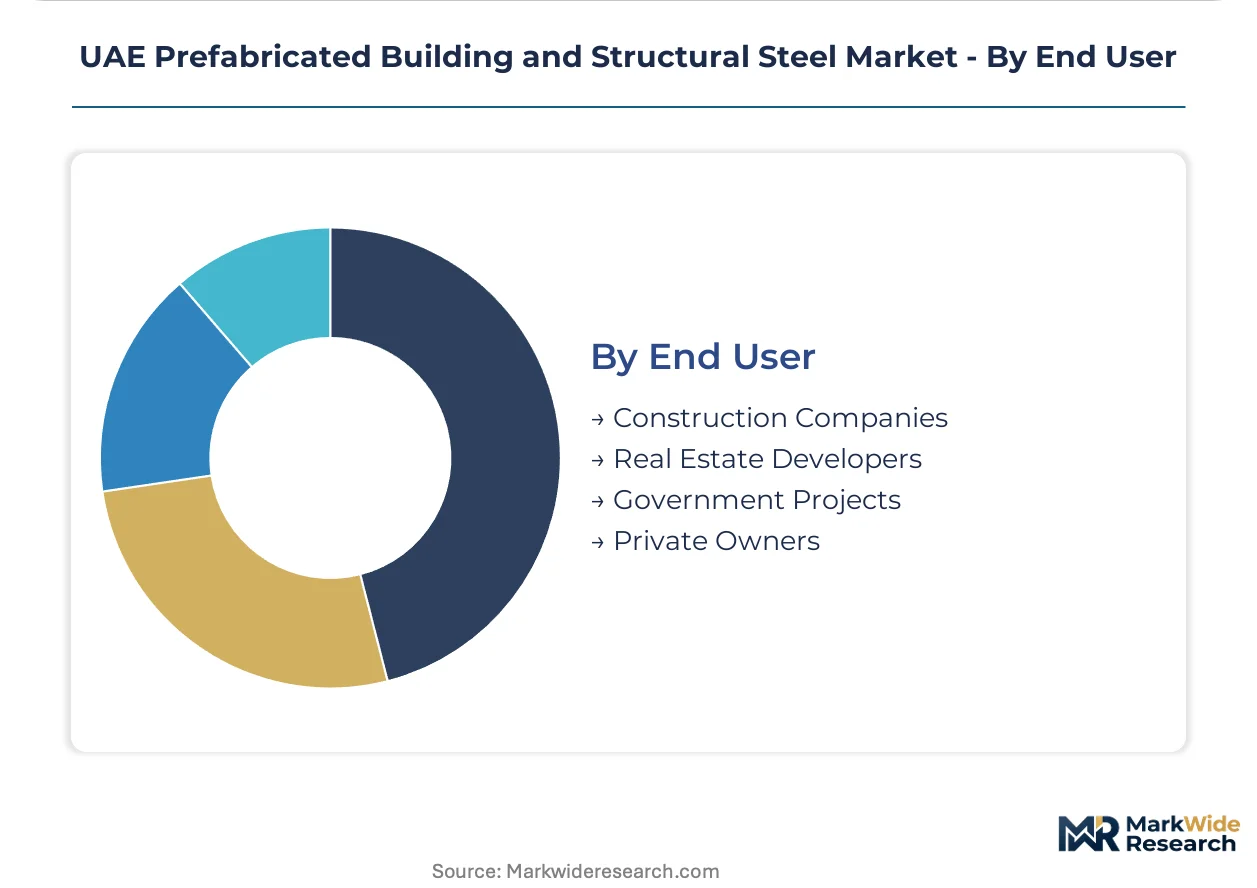
End User:
Procurement sophistication and compliance burden vary sharply across buyer types.
- Construction Companies:General contractors with invested formwork and labor networks often resist modular adoption, fragmenting project delivery methodologies. Those with International Welding Engineer qualifications capture structural steel supervision roles.
- Real Estate Developers:Dubai-based developers pursuing multi-phase master plans consolidate vendor lists around fabricators with direct Estidama documentation support. Repeatable building typologies in Dubai South and Jebel Ali drive panelized system specifications.
- Government Projects:Federal procurement guidelines pending implementation will privilege UAE-fabricated components over re-exported alternatives. MOHAP oversees construction product safety declarations for public infrastructure.
- Private Owners:Individual and corporate clients for standalone commercial and residential projects often lack technical procurement capabilities, relying on contractor recommendations for specification decisions.
Real estate developers drive premium segment volumes; government projects are reshaping competitive dynamics fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands the largest project pipeline for prefabricated systems, while Abu Dhabi anchors upstream steel production through integrated melt shop operations. Sharjah and the Northern Emirates represent emerging fabrication zones with lower land costs and expanding industrial zones.
Dubai
Expo City redevelopment and South Dubai logistics zones drive volumetric module demand for rapid-deployment commercial and residential towers. Estidama Pearl Rating mandates filter supplier qualification toward fabricators with embodied carbon documentation capabilities. Jebel Ali corridor developers specify panelized systems for mid-rise residential projects requiring Al Sa'fat thermal compliance.
Abu Dhabi
Emirates Steel's integrated melt shop and rolling mill complex supplies hot-rolled sections across the northern emirates. Government-backed affordable housing initiatives accelerate specification shifts toward factory-manufactured structural solutions. Khalifa Industrial Zone fabrication yards face certification queues from civil defense fire resistance testing protocols.
Sharjah
Industrial land availability attracts panelized system providers seeking lower-cost manufacturing bases than Dubai. MOHAP construction product safety declarations apply equally here, maintaining compliance parity across emirates. Hamriyah Free Zone developing manufacturing clusters lack established structural steel fabricators, creating positioning opportunities.
Northern Emirates
Ras Al Khaimah's developing industrial zones pull cold-formed steel framing for smaller warehousing applications. Federal procurement guidelines pending implementation will privilege UAE-fabricated components in government projects across these emirates. Al Sa'fat-equivalent standards under development in Ajman and Fujairah will extend thermal performance mandates beyond Dubai.
UAE Prefabricated Building and Structural Steel Market Key Industry Players
Top-tier vendors anchor integrated steel production and large-scale fabrication, while mid-tier specialists compete on cold-formed sections and distribution networks. The vendor base clusters around three archetypes: upstream integrated producers controlling melt-to-finish supply chains, engineering-led fabricators with Estidama documentation capabilities, and distribution-focused intermediaries with northern emirates coverage. Dominant competitive moves include captive supply chain control over hot-rolled sections and consolidation of vendor lists by developer procurement teams seeking single-point accountability.
Among upstream integrated producers, Emirates Steel anchors primary steel supply through its Abu Dhabi melt shop complex. Al Jazeera Steel Products occupies a position within the specialized cold-formed sections tier, while Al Futtaim Engineering sits within the distribution-network archetype controlling northern emirates access. These three represent the structural diversity of competitive positioning: captive production, technical specialization, and geographic coverage respectively.
| Leading Market Players |
|---|
| Al Habtoor Group |
| Al Mufeed Engineering |
| Emirates Steel |
| Al Maktoum Group |
| Al Qudra Holding |
| Al Jaber Group |
| Al Shafar General Contracting |
| Al Jazeera Steel Products |
| Al Futtaim Engineering |
| Others |
Cost & Logistics Intelligence
Captive melt-to-finish integration at Emirates Steel's Abu Dhabi complex anchors supply-side pricing power for hot-rolled structural sections across the northern emirates. This upstream control insulates domestic producers from Turkish mill competition while compressing margin capture for distributors lacking fabrication capabilities.
Pricing Analysis
Capacity additions in Ras Al Khaimah's developing industrial zones are reshaping price floors for cold-formed steel framing. Three-tier pricing structure across premium certified, standard grade, and economy panelized systems separates Estidama Pearl-compliant modules from commodity imports. Pricing pressure stems from scrap steel volatility feeding Emirates Steel's melt shop operations. Government procurement teams show least price sensitivity given certification mandates, while private mid-rise residential developers in Dubai South exhibit highest sensitivity to per-square-meter differentials.
Supply Chain Analysis
Estidama Pearl documentation requirements and civil defense fire resistance testing create qualification gates that thin import competition. Primary steel production concentrates in Abu Dhabi, with hot-rolled sections flowing to Dubai and Sharjah fabrication yards. Raw material feeds draw from regional scrap collection networks, direct reduced iron shipments, and coating chemical imports. Single-source vulnerability sits with Emirates Steel's integrated complex serving the northern emirates. Distribution runs through project-direct relationships with real estate developers, bypassing traditional intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE market offers geographic-arbitrage positioning between Abu Dhabi's captive steel production and Dubai's premium project pipeline, with regulatory compliance costs in Dubai creating margin capture opportunities for northern emirate fabricators.
For Market Incumbents: Acquire welding certification capabilities and International Welding Engineer qualifications to expand fabrication yard capacity. Defend against cold-formed steel specialists from Ras Al Khaimah by locking long-term offtake agreements with Emirates Steel for hot-rolled sections. Channel control through direct developer relationships insulates against distributor disintermediation. For New Entrants and Emerging Players: Capture first-mover positioning in Ras Al Khaimah's Hamriyah Free Zone manufacturing clusters where established structural steel fabricators remain absent. Target smaller warehousing and logistics applications in the northern emirates where Al Sa'fat-equivalent standards are still under development. Lead with building-integrated photovoltaic facade assemblies for net-zero commercial projects in Dubai's mega-project corridor. For Investors and Strategic Acquirers: Consolidation pressure builds where Estidama documentation capabilities concentrate among engineering-led fabricators with captive supply chain relationships. Long-term viability favors vertically integrated specialists controlling melt-to-module production within the UAE federal procurement perimeter. Watch for implementation of pending government project guidelines privileging locally fabricated components as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Collection | Secures input cost stability for Emirates Steel's Abu Dhabi melt shop against Turkish export competition. |
| Estidama Documentation Investment | Enables Pearl Rating compliance bids for Dubai Expo City redevelopment and South Dubai logistics projects. |
| Ras Al Khaimah Manufacturing Footprint | Captures lower land costs while positioning for northern emirates industrial zone expansion. |
| Building-Integrated Photovoltaic Partnership | Combines sandwich panel production with embedded solar laminates for net-zero commercial specifications. |
| International Welding Engineer Recruitment | Removes fabrication yard expansion constraints from scarce domestic certification availability. |
Research Approach
Bottom-up project pipeline modeling reconciled against top-down steel production tracking forms the analytical core of this study. Primary interviews with real estate development executives, fabrication yard operations managers, civil defense certification officers, and MOHAP regulatory leads combined with secondary validation from Emirates Steel production disclosures, Dubai Land Department project registrations, Estidama Pearl Rating submissions, and customs import data. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of prefabricated building adoption rates across Dubai's mega-project corridor informed projection parameters. Segmentation dimensions modeled include product type, application, delivery mode, and end user, with additional granularity on thermal performance tier and certification status. CAGRs were derived from fitted growth curves applied to disclosed project pipelines and steel consumption patterns. Forecast inputs incorporate scrap steel price sensitivity and regulatory compliance cost trajectories.
Scrap steel price volatility, civil defense testing protocol delays, and federal procurement guideline timing are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding project completion schedules and regulatory implementation pace. A model refresh is warranted upon material change in Estidama Pearl Rating enforcement intensity or Emirates Steel capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Bridge Bearings Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Canada Composite Repair Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Bridge Construction Market
Structural Construction
Ceiling Expansion Joint Market