
 Sheet Metal Fabrication Equipment Market | 2026-2036
Sheet Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Metal Fabrication Equipment Market Insights
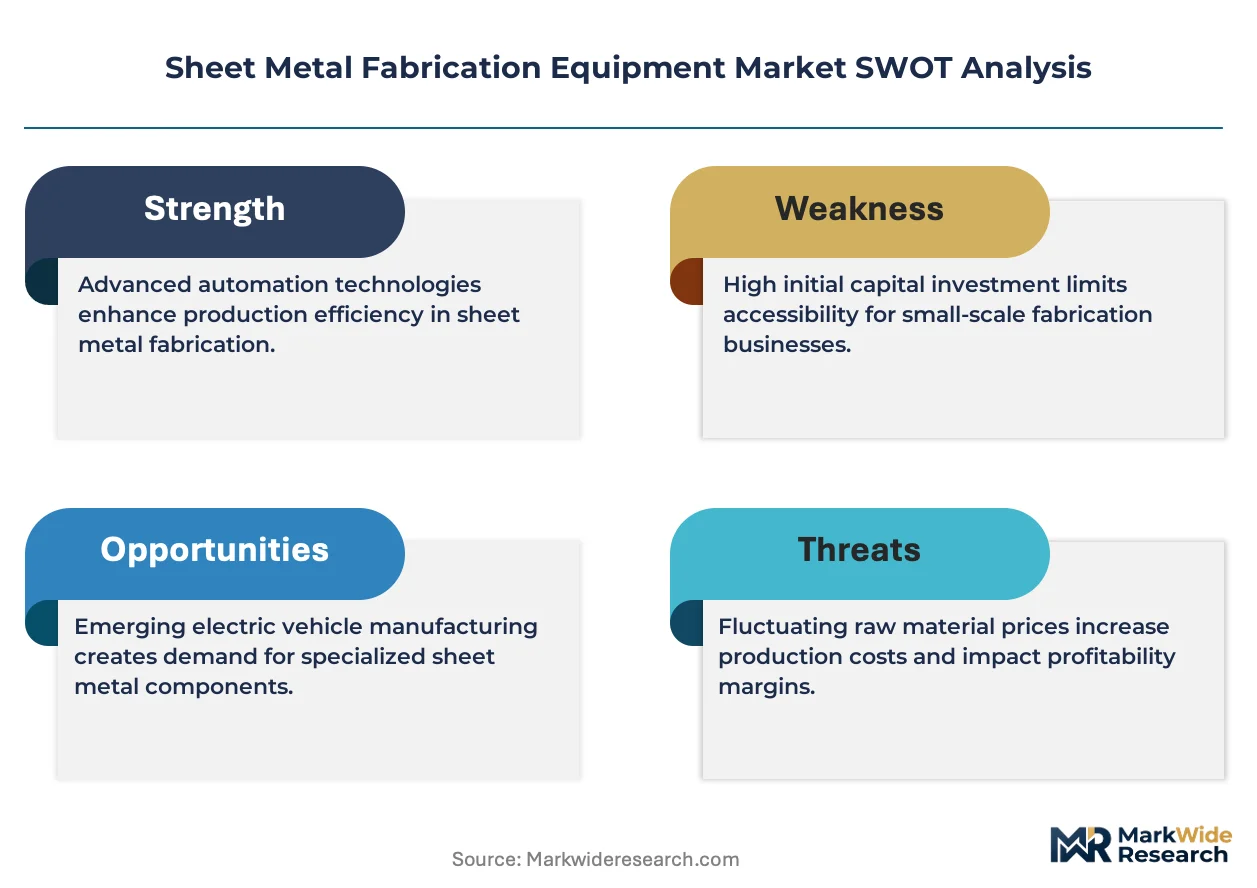
Software-defined predictive maintenance is realigning how OEMs monetize sheet metal fabrication equipment. TRUMPF Group leverages remote diagnostics and cloud-based uptime guarantees to extend recurring revenue beyond hardware sales. Amada Corporation anchors its competitive stance through deep integration of automated tool-change systems with subscription-based software updates. Yamazaki Mazak Corporation differentiates by controlling a global service network that sustains long-term client retention across high-mix, low-volume environments.
Sheet metal fabrication equipment encompasses machinery that cuts, forms, punches, or joins metal sheets typically ranging from 0.5 mm to 25 mm thickness, operating through mechanical force, thermal energy, or electrochemical processes to produce precision-engineered components for industrial assembly. Laser cutting machines dominate value capture due to rising throughput requirements in aerospace-grade aluminum and titanium processing, while servo-electric press brakes represent the fastest-expanding technology segment as manufacturers replace hydraulic systems to cut energy consumption and improve positional repeatability within ±0.01 mm. CNC technology leads installed base volume but plasma systems retain defensible positions in thick-plate shipbuilding applications where edge quality tolerances remain less stringent.
OSHA machine guarding standards and the EU Machinery Directive shape product design mandates, compelling manufacturers to integrate light-curtain safety systems and interlocked access panels as baseline configurations. EPA air-emission thresholds for metal cutting coolants and particulate filtration influence capital-equipment specification sheets across US-based fabrication workshops. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to autonomous nesting and defect-detection algorithms embedded in next-generation control systems.
Market Dynamics
Software-defined predictive maintenance is realigning how OEMs monetize sheet metal fabrication equipment, extending recurring revenue beyond hardware sales through remote diagnostics and cloud-based uptime guarantees.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates push fabricators toward fiber laser and electric servo systems, accelerating capital replacement cycles in precision manufacturing clusters.
- Aerospace-grade aluminum processing:Airframe program expansions drive laser cutting machine procurement for titanium and aluminum sheet fabrication.
- Germany:Precision component clusters anchor procurement concentration, sustaining demand for CNC press brakes with ±0.01 mm repeatability specifications.
Market Restraints
- Input cost volatility:Rare earth magnet prices for servo-electric drive systems create margin pressure on press brake manufacturers.
- Supply concentration risk:Fiber laser source production concentrates in Chinese and German suppliers, exposing buyers to single-source dependencies.
- Technical limitation:Plasma cutting systems face displacement in thin-sheet applications where laser edge quality tolerances are mandatory.
Strategic Opportunities
- Underpenetrated geography:Vietnam's emerging electronics manufacturing base presents first-mover positioning for automated nesting software vendors.
- Technology convergence:AI-driven defect detection algorithms embedded in next-generation control systems create differentiation in high-mix, low-volume environments.
- Regulatory tailwind:EU AI Act risk-classification frameworks for autonomous nesting systems will favor early-certified equipment suppliers.
Industry Challenges
- Capex intensity:Fiber laser cutting systems require substantial upfront investment, compressing payback periods for mid-tier fabrication workshops.
- Skill gap in servo-electric maintenance:Hydraulic system expertise dominates the technician workforce, creating training bottlenecks for electric press brake deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Metal Fabrication Equipment Market |
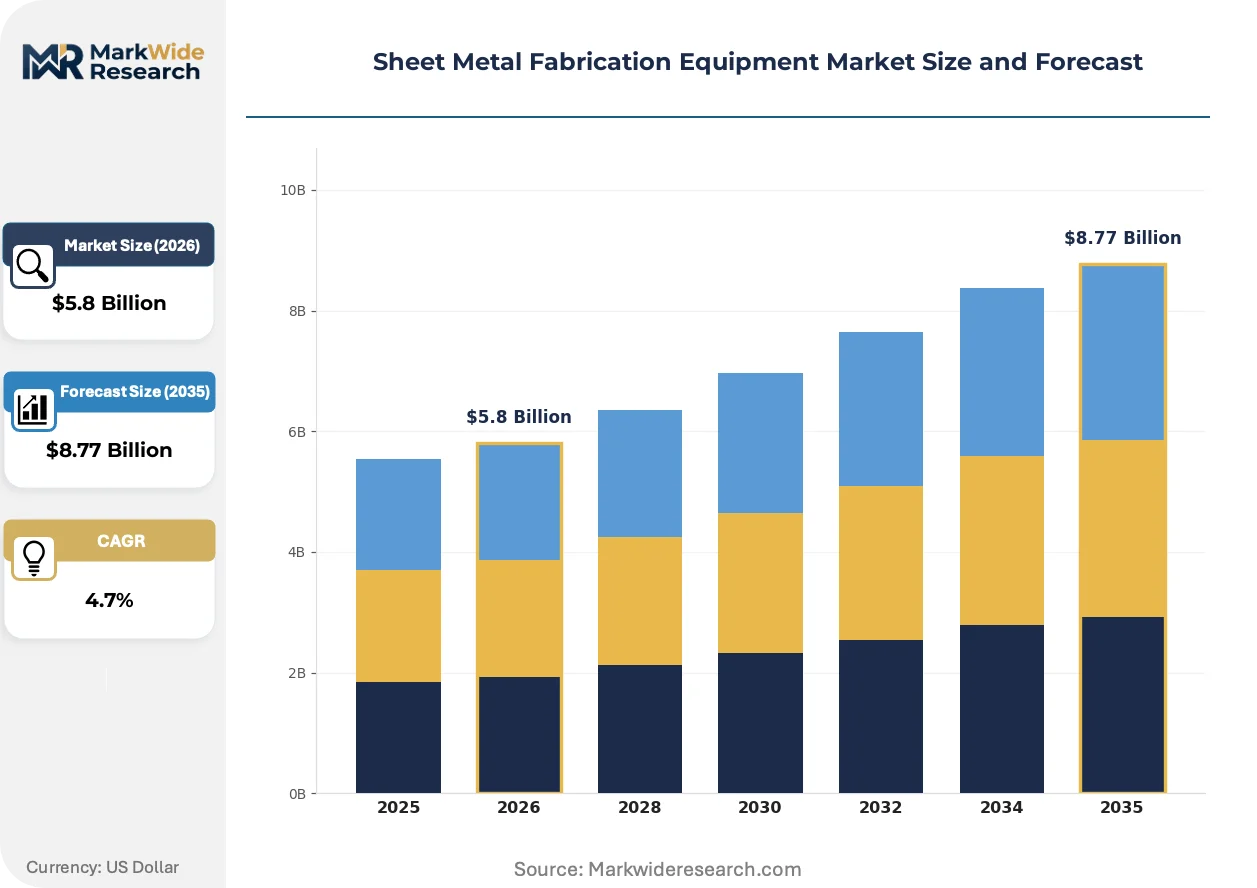
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutting Machines, Press Brakes, Shearing Machines, Milling Machines, Punching Machines Technology: CNC, Hydraulic, Servo Electric, Mechanical, Plasma Application: Construction, Aerospace Manufacturing, Shipbuilding, Appliance Manufacturing, Heavy Machinery Production End User: OEMs, Contract Manufacturers, Fabrication Workshops, Tier-1 Suppliers, Maintenance Providers |
| Companies Covered | Yamazaki Mazak Corporation, Okuma Corporation, Amada Corporation, Sandvik AB, DMG Mori, TRUMPF Group, Mitsubishi Electric Corporation, Prima Industrie, Bystronic Laser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Metal Fabrication Equipment Market Trends and Innovations
Automation architectures are converging with subscription software models, compressing how fabricators acquire capability and how OEMs capture lifetime value from installed equipment.
Fiber laser technology is integrating with automated material handling and real-time beam monitoring systems to sustain cutting consistency across reflective metals. Aerospace suppliers in Germany and the United States are adopting these configurations to maintain throughput on titanium and aluminum alloys. The technology is integrating nesting optimization directly into machine control architectures, reducing programming overhead and compressing job-to-job changeover intervals.
REACH compliance and the EU Machinery Directive are mandating light-curtain safety systems and interlocked access panels as baseline configurations rather than optional upgrades. Fabricators face redesign costs to meet these specifications for equipment sold into European markets. Servo-electric press brake manufacturers are responding fastest, embedding safety-certified control systems that satisfy both OSHA and EU conformance requirements.
Service unbundling is separating hardware ownership from performance guarantees, with uptime-based contracts displacing traditional break-fix arrangements. High-mix, low-volume fabricators in the United States are adopting these models to convert fixed maintenance costs into variable operational expenditures. Germany shows parallel adoption among precision component specialists seeking to minimize unplanned downtime on multi-shift operations.
Sheet Metal Fabrication Equipment Market Segmentation
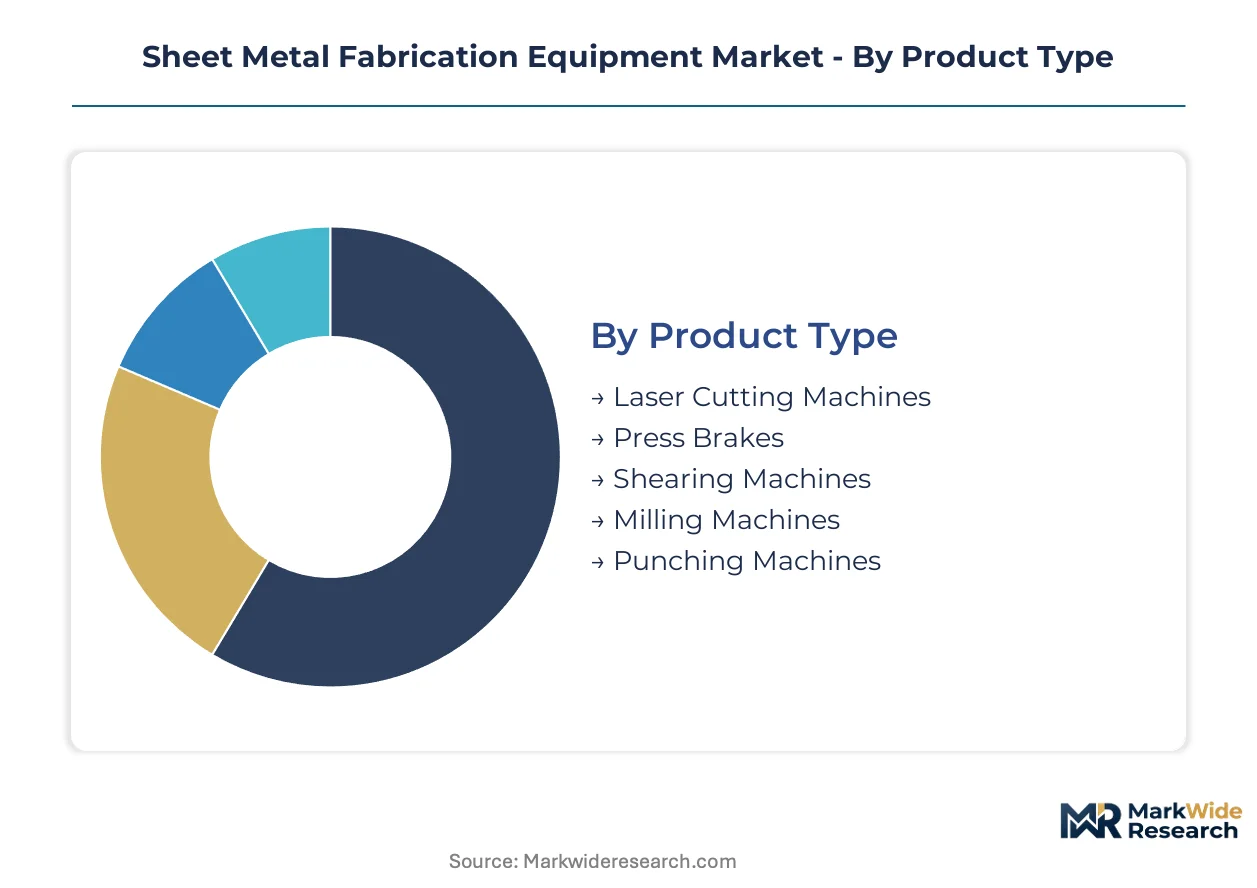
Segmentation in sheet metal fabrication equipment reveals how technology choices, customer scale, and application requirements reshape procurement patterns. Equipment buyers balance throughput demands against energy costs, regulatory compliance, and workforce capabilities when selecting across these dimensions.
Product Type:
Customization intensity varies sharply across this category, from standardized press brakes for general fabrication to highly configured laser systems for aerospace-grade materials.
- Laser Cutting Machines:Fiber and CO2 configurations dominate high-value procurement, with power ratings from 2kW to 12kW enabling precision cutting of reflective metals. Demand concentrates in Germany and the United States where aerospace suppliers process titanium and aluminum sheet for airframe programs, driven by throughput requirements that exceed mechanical cutting limits.
- Press Brakes:Servo-electric and hydraulic variants form the backbone of general fabrication, with bed lengths from 1m to 8m accommodating diverse part geometries. Germany's precision component clusters anchor procurement for CNC units with ±0.01 mm repeatability, compelled by EU F-Gas Regulation mandates to displace older hydraulic systems.
- Shearing Machines:Guillotine and swing-beam designs serve high-volume straight-line cutting for construction and appliance manufacturing.
- Milling Machines:Integrated machining centers handle complex contouring and edge preparation for thick-plate applications.
- Punching Machines:Turret and single-station configurations execute hole patterns and formed features in medium-volume production runs.
Most installed capacity flows through press brakes. Expansion is steepest in laser cutting machines.
Technology:
Cost tier stratification separates premium servo-electric and fiber laser systems from legacy mechanical and hydraulic alternatives.
- CNC:Computer numerical control architectures dominate value capture across cutting, forming, and punching equipment, integrating CAD/CAM nesting software directly into machine controllers. Germany, China, and the United States concentrate demand where multi-shift operations justify programming automation to compress job changeover intervals.
- Servo Electric:Brushless motor and ball-screw drive systems displace hydraulic power packs in press brake applications, cutting energy consumption and eliminating oil maintenance. Procurement accelerates in the United States and Germany as fabricators respond to EPA thresholds and EU Machinery Directive efficiency mandates.
- Hydraulic:Fluid-power actuation retains installed base dominance in heavy-gauge forming where tonnage requirements exceed electric drive limits.
- Mechanical:Flywheel and clutch mechanisms persist in high-speed punching for appliance manufacturing volume runs.
- Plasma:Thermal arc cutting systems defend thick-plate shipbuilding applications where edge quality tolerances remain less stringent than aerospace requirements.
Legacy hydraulic and mechanical systems retain the largest installed base. Servo-electric configurations are gaining share fastest.
Application:
Customer type differentiation separates capital-intensive OEM captive shops from price-sensitive contract fabrication services.
- Aerospace Manufacturing:Airframe and engine component production demands fiber laser and precision press brake systems certified for aluminum, titanium, and nickel alloy processing. Germany and the United States concentrate procurement where Boeing and Airbus supply chains enforce material traceability and dimensional tolerances.
- Shipbuilding:Thick-plate hull and superstructure fabrication drives plasma and oxy-fuel cutting system deployment with gantry-mounted configurations. Chinese and South Korean yards anchor regional demand for heavy-duty equipment handling plates exceeding 25mm thickness.
- Construction:Structural steel and architectural metalwork procurement favors cost-optimized shearing and punching systems for standardized profiles.
- Appliance Manufacturing:High-volume sheet steel processing for refrigeration and HVAC enclosures employs mechanical punching and blanking lines.
- Heavy Machinery Production:Earthmoving and agricultural equipment fabricators specify robust press brakes and milling centers for thick-gauge components.
Aerospace manufacturing commands the highest equipment specifications. Shipbuilding sustains the largest unit volumes.
End User:
Volume concentration and margin structure separate integrated OEM operations from fragmented fabrication workshop tiers.
- OEMs:Captive fabrication facilities at automotive, aerospace, and appliance manufacturers specify integrated automation cells with robotic loading and real-time production monitoring. Germany and the United States concentrate investment where vertical integration controls quality for safety-critical components.
- Contract Manufacturers:High-mix, low-volume specialists serving multiple industries prioritize flexible CNC systems with rapid tool-change capabilities and subscription-based software updates. United States-based job shops are adopting service-unbundled contracts to convert fixed maintenance costs into operational expenditures.
- Fabrication Workshops:Independent metal service centers balance equipment versatility against capital constraints in competitive regional markets.
- Tier-1 Suppliers:Automotive and aerospace subsystem producers configure dedicated lines for long-term program contracts with volume guarantees.
- Maintenance Providers:Repair and overhaul specialists deploy portable and compact equipment for on-site structural restoration.
OEMs control the premium equipment tier. Contract manufacturers are expanding capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision component clusters sustain equipment specifications that exceed China's volume-driven procurement, while the United States anchors aerospace-grade demand through Boeing and Airbus supply chain mandates.
United States
Aerospace manufacturing in Washington State and Texas drives fiber laser procurement for titanium and aluminum airframe processing. OSHA machine guarding standards and EPA air-emission thresholds for metal cutting coolants shape capital-equipment specifications. Boeing suppliers in the Pacific Northwest and Gulf Coast fabrication workshops sustain multi-shift operations demanding CNC press brakes with ±0.01 mm repeatability.
Germany
Automotive and aerospace subsystem producers in Baden-Württemberg and Bavaria specify integrated automation cells with robotic loading capabilities. EU F-Gas Regulation and REACH compliance accelerate displacement of hydraulic press brakes by servo-electric systems. Stuttgart's precision engineering corridor concentrates demand for certified equipment handling nickel alloys and titanium sheet.
China
Shipbuilding yards in Dalian and Shanghai anchor plasma cutting system deployment for thick-plate hull fabrication exceeding 25mm thickness. MIIT efficiency standards and dual carbon goals compel domestic fabricators toward fiber laser and electric servo configurations. Yangtze River Delta electronics manufacturers are emerging as first-movers for automated nesting software in high-mix production environments.
Japan
Automotive captive fabrication facilities in Aichi Prefecture and Kansai region specify multi-process machining centers for safety-critical component production. METI energy efficiency directives and JIS standards certification requirements favor servo-electric press brake adoption. Nagoya's industrial machinery corridor sustains demand for equipment integrating real-time production monitoring systems.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive gantry-mounted plasma system procurement in Ulsan and Geoje shipbuilding complexes. MFDS-equivalent industrial safety frameworks and national carbon neutrality targets reshape equipment specifications. Busan-Ulsan manufacturing belt concentrates thick-plate processing demand where edge quality tolerances remain less stringent than aerospace requirements.
Sheet Metal Fabrication Equipment Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated automation and software-defined service models, while mid-tier specialists compete on cost-optimized mechanical systems. The vendor base stratifies across three archetypes: full-solution OEMs with captive software ecosystems, component specialists controlling laser source or drive system supply, and regional fabricators serving price-sensitive construction markets. Consolidation pressures concentrate in fiber laser source production, while servo-electric press brake manufacturing retains fragmented regional competition. Dominant competitive moves include M&A targeting automated material handling capabilities and strategic partnerships nesting software vendors with machine control architectures.
Among Japanese-headquartered fabricators, Yamazaki Mazak Corporation and Amada Corporation exemplify full-solution OEM archetypes with deep software-hardware integration. TRUMPF Group represents German-origin premium-tier positioning through service-unbundled contracts and remote diagnostics capabilities. Okuma Corporation and DMG Mori occupy positions bridging precision machining with sheet metal process integration, while Bystronic Laser AG exemplifies laser-specialist positioning within European markets. Mitsubishi Electric Corporation anchors Japanese electric drive system supply for servo-electric press brake manufacturers seeking to displace hydraulic alternatives.
| Leading Market Players |
|---|
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Amada Corporation |
| Sandvik AB |
| DMG Mori |
| TRUMPF Group |
| Mitsubishi Electric Corporation |
| Prima Industrie |
| Bystronic Laser AG |
| Others |
Pricing and Supply Chain Analysis
Family-owned German and Japanese mid-caps anchor premium-tier pricing discipline through captive service networks and long-term customer relationships, while Chinese state-backed producers compress price floors in fiber laser sources through scale-driven capacity additions. This ownership bifurcation shapes how supply concentration in critical components translates into pricing power asymmetries across equipment tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for fiber laser cutting systems, forcing incumbent OEMs to unbundle hardware from subscription software to defend margins. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified systems with ±0.01 mm repeatability guarantees from general fabrication units. Cost compression in mid-tier servo-electric press brakes intensifies because rare earth magnet input volatility squeezes manufacturer margins. Contract manufacturers exhibit highest price sensitivity due to capex constraints, while aerospace OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from Boeing and Airbus suppliers are reshaping procurement patterns for fiber laser sources and servo-electric drive systems. Production concentrates in China, Germany, and Japan for laser resonators and rare earth magnets, with South Korean and Taiwanese suppliers anchoring secondary qualification. Equipment manufacturing draws from aluminum and titanium sheet feedstock, precision ball-screw assemblies, and CNC control architectures. Single-source vulnerability in Chinese fiber laser source production exposes buyers to geopolitical disruption. Distribution runs through authorized dealer networks with factory-direct service contracts for large OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sheet metal fabrication equipment functions as a stable compounder anchored by aerospace program longevity and regulatory-driven replacement cycles. EU F-Gas Regulation and REACH compliance create predictable demand tailwinds for energy-efficient system upgrades.
For Market Incumbents: Anchor defensive positioning through backward integration into automated material handling capabilities and certified service network expansion. Chinese fiber laser source producers threaten margin capture in core cutting systems; respond by deepening software-hardware integration and uptime-guarantee contracts that convert capital sales into recurring revenue streams.
For New Entrants and Emerging Players: AI-driven nesting optimization algorithms offer technology-first wedge positioning against legacy control architectures. Vietnam's electronics manufacturing base presents the most penetrable geography for automated software vendors. Target contract manufacturers with SaaS-tiered pricing that eliminates upfront programming costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional servo-electric press brake specialists lacking software ecosystems. Long-term viability centers on equipment suppliers with installed base scale sufficient to support subscription service transitions. Watch for EU AI Act certification announcements as inflection indicators for autonomous system differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Source Production | Reduces dependency on Chinese and German suppliers for fiber resonator supply security. |
| Subscription Software Platform Launch | Converts one-time hardware margins into recurring revenue from predictive maintenance services. |
| EU AI Act Certification Investment | Creates regulatory moat for autonomous nesting systems in European aerospace supply chains. |
| Automated Material Handling Acquisition | Integrates robotic loading capabilities that compress job changeover intervals for high-mix fabricators. |
| Vietnam Market Entry Partnership | Positions first-mover advantage in electronics manufacturing automation before competitor saturation. |
Research Methodology
Bottom-up aerospace and automotive demand modeling reconciled against top-down fiber laser and press brake production tracking forms the analytical core. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from SEC filings, customs trade data, MIIT efficiency disclosures, and EU Machinery Directive compliance databases. Triangulation across stakeholder inputs and production statistics ensures dimensional accuracy.
Input-output matrices map equipment shipments against end-use capacity expansion across the projection horizon. Segmentation dimensions include product type, technology tier, application intensity, and end-user scale. CAGRs derive from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-out schedules and aerospace program delivery timelines.
The model holds under stable regulatory enforcement and continued aerospace production rates; deviation in rare earth supply disruptions or tariff escalation on Chinese laser sources would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Industrial Dryers Market