
 Timber Frame Construction Market | 2026-2036
Timber Frame Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Frame Construction Market Outlook
Project finance tied to green bonds and sustainability-linked loans is reshaping capital access for timber frame developers. Bensonwood leverages its design-build integration to control project timelines from engineered specification through on-site assembly. Stora Enso Oyj anchors European supply with its vertically integrated forest-to-frame operations across Nordic mills. Boise Cascade Company dominates North American distribution through its extensive dealer network for engineered wood products.
Timber frame construction employs precisely cut and joined structural members, typically using mortise-and-tenon or steel-connector joinery, to create load-bearing skeletons for buildings ranging from single-family residences to multi-story commercial structures. The method transfers vertical and lateral loads through wooden posts and beams, often enclosing the frame with structural insulated panels or cross-laminated timber sheathing for thermal and acoustic performance. Structural systems command premium margins due to engineering complexity and turnkey delivery requirements, while prefabricated wall and floor frames scale fastest as housing developers seek factory-controlled quality and compressed on-site schedules. Engineered wood materials, including laminated veneer lumber and glued-laminated timber, are displacing traditional solid-sawn dimensions in commercial applications where span capabilities and dimensional stability determine specification.
US building codes governed by the International Code Council and state-level amendments increasingly recognize mass timber construction types, directly expanding permissible building heights and square footage for timber frame assemblies. The EU Green Deal and national implementations of the Energy Performance of Buildings Directive in Germany and France mandate embodied carbon disclosures that favor timber over steel and concrete structural alternatives. Stakeholders must monitor evolving fire-resistance testing protocols and insurance underwriting frameworks as these determine whether timber frame solutions penetrate high-rise and institutional segments currently reserved for mineral-based construction.
Market Dynamics
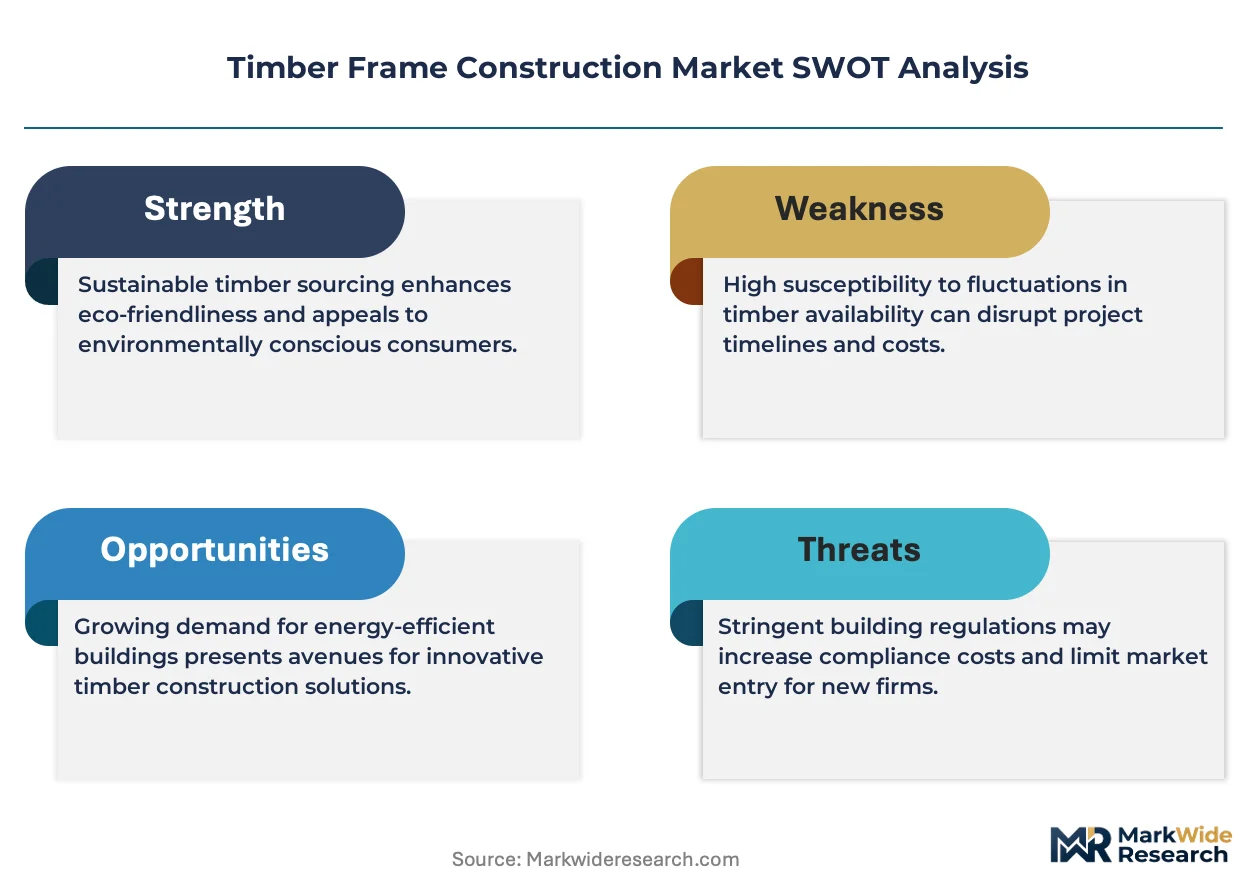
Cross-laminated timber fire-rating upgrades are rewriting structural code tables, compressing approval timelines for mid-rise timber assemblies and pulling capital from concrete toward engineered wood systems.
Growth Catalysts
- EU Green Deal embodied carbon mandates:France and Germany now require lifecycle carbon disclosures for public procurement, tilting specification toward timber frame alternatives.
- Mass timber engineering advances:Enhanced CLT fire-resistance testing protocols are unlocking height allowances previously reserved for steel and concrete.
- Institutional ESG capital flows:Green bond frameworks from the European Investment Bank and US municipal issuers prioritize low-carbon structural materials in project finance.
Market Restraints
- Softwood lumber price volatility:North American sawmill capacity constraints and tariff exposure create input cost instability for frame fabricators.
- Insurance underwriting conservatism:Property casualty carriers in high-rise markets apply elevated premiums to timber structures pending updated actuarial data.
- Steel-frame substitution in seismic zones:California and Japan building codes still favor ductile steel moment frames for earthquake resilience above six stories.
Strategic Opportunities
- Mid-rise commercial in Australia:National Construction Code amendments permitting 12-story timber buildings open institutional office and student housing segments.
- Prefabrication-to-site logistics platforms:Digital twin coordination between factory CNC cutting and crane scheduling compresses on-site assembly windows.
- Carbon credit monetization:Verified carbon standard methodologies for biogenic carbon storage create incremental revenue streams for certified forest-to-frame supply chains.
Industry Challenges
- Mass timber design engineering capacity:Qualified structural engineers familiar with CLT and glulam connection detailing remain concentrated in Nordic and Alpine markets.
- Multi-jurisdictional type approval:Divergent fire-testing protocols between ICC-ES in the US and ETA routes in Europe force redundant certification spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Frame Construction Market |
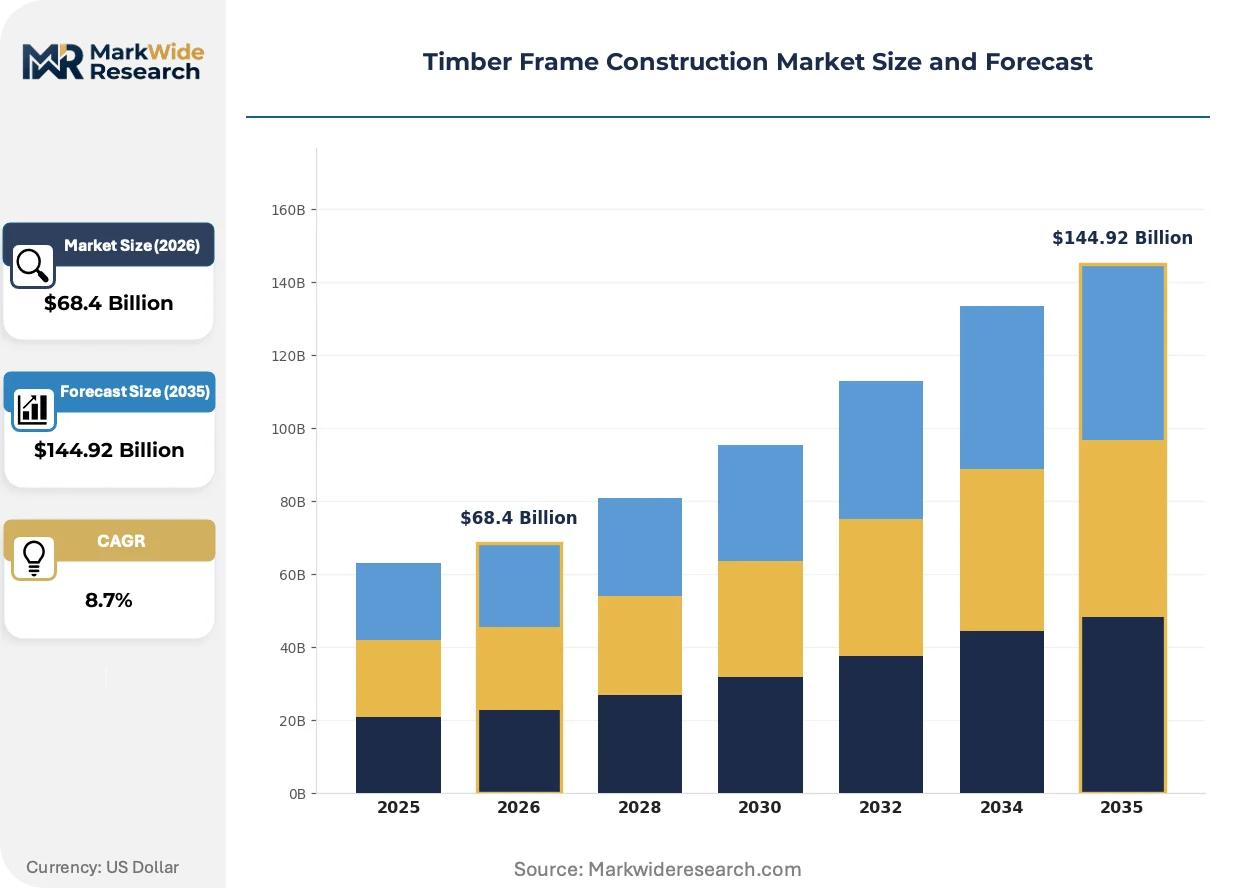
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Frames, Roof Frames, Floor Frames, Structural Systems Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Recreational Structures Construction Method: Prefabricated, Modular, On-site Fabrication, Hybrid Material: Softwood, Hardwood, Engineered Wood, Laminated Veneer |
| Companies Covered | Custom Timber Frames, Malmquist Construction, Bensonwood, Stora Enso Oyj, New Energy Works, Blue Ribbon Builders, Hugh Lofting Timber Framing, Boise Cascade Company, BOWA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Frame Construction Market Strategic Shifts
Digital fabrication and biogenic carbon accounting are converging to reposition timber frame construction from craft-based building toward precision-manufactured infrastructure.
Cross-laminated timber is migrating from single-family residential floors and roofs toward primary structural frames for 8-to-12 story commercial buildings. US and Canadian developers are specifying CLT core walls and floor plates for office and mixed-use projects that previously required cast-in-place concrete. The technology is migrating from demonstration pilots toward standardized design-build delivery, compressing preconstruction engineering cycles by half.
The EU Energy Performance of Buildings Directive is mandating whole-life carbon declarations for new construction across member states. This regulatory pressure forces structural engineers to model embodied carbon alongside operational energy, elevating timber frame systems in competitive bid evaluations. German and French public housing authorities are now excluding steel and concrete alternatives from low-carbon tender categories.
Design-assist contracting is replacing traditional design-bid-award sequences for complex timber structures. Timber frame specialists are embedding fabrication expertise during schematic design, capturing value that architects previously delegated to general contractors. This pattern is most visible in UK and Scandinavian commercial projects where Building Information Modeling coordination determines constructability.
Timber Frame Construction Market Segmentation
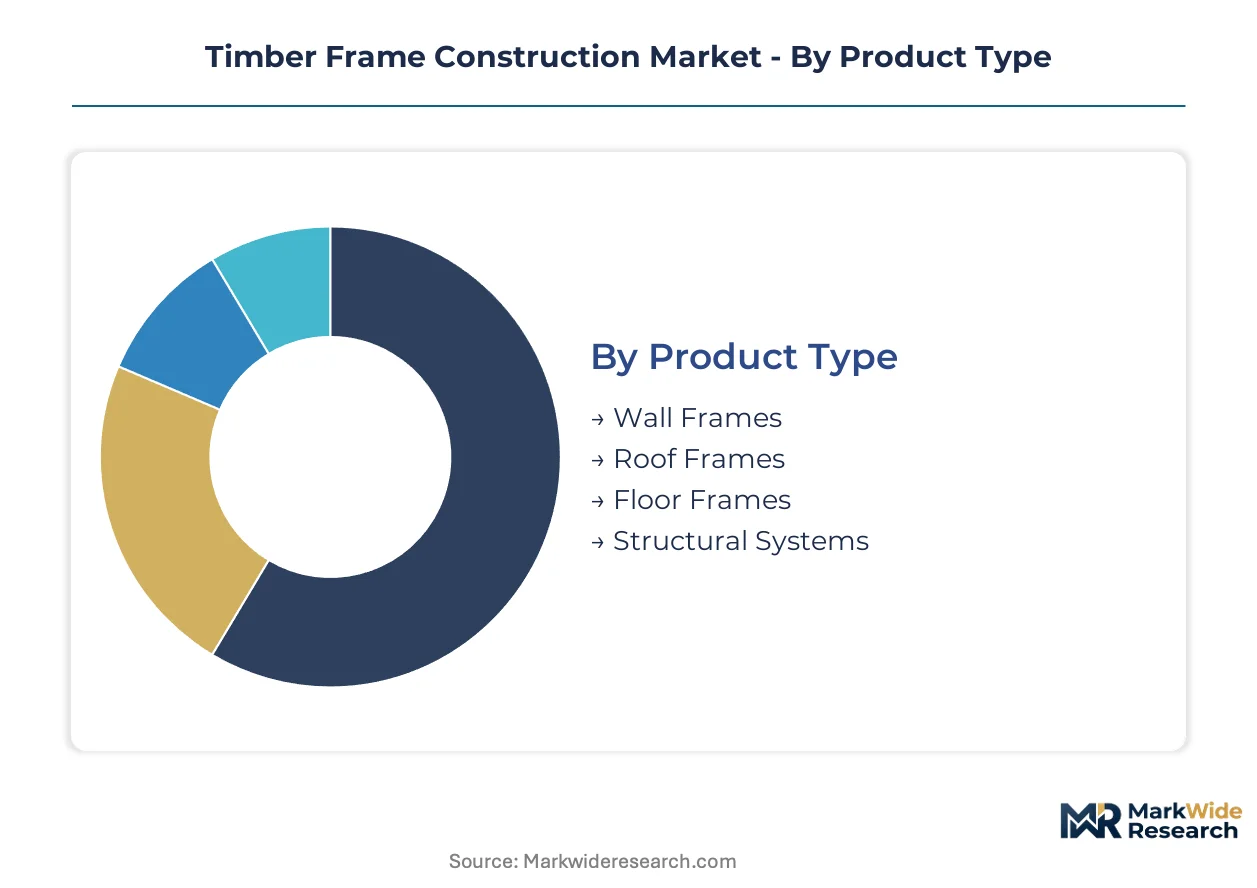
Segmentation in timber frame construction reveals how engineering complexity, procurement methods, and material specifications determine margin structures and capital deployment across residential, commercial, and institutional projects.
Product Type:
Mature framing components dominate volume, while integrated structural systems command premium positioning through turnkey engineering liability.
- Wall Frames:Factory-built stud assemblies with structural insulated panel integration deliver thermal performance ratings required by German EnEV and French RE2020 regulations. German housing associations and US multifamily developers specify these for mid-rise residential compression of on-site labor schedules.
- Structural Systems:Turnkey post-and-beam skeletons with engineered connection hardware transfer full design liability to fabricators. UK commercial developers and Scandinavian institutional clients procure these for 6-to-12 story office buildings where Building Information Modeling coordination determines constructability outcomes.
- Roof Frames:Prefabricated truss and purlin assemblies reduce crane time for residential developers in Canada and the Pacific Northwest.
- Floor Frames:I-joist and cross-laminated timber decking systems span longer distances without intermediate bearing walls.
Wall frames handle the majority of throughput; structural systems are climbing the fastest on share as mid-rise commercial codes relax height restrictions.
Application:
Cost tier stratification separates commodity residential volume from engineered commercial premiums where embodied carbon accounting drives specification.
- Residential Buildings:Single-family and multifamily housing consumes standardized dimension lumber and prefabricated panel systems. US and Canadian production builders source these through Boise Cascade distribution networks to meet International Code Council prescriptive path requirements.
- Commercial Buildings:Office, retail, and hospitality structures specify mass timber columns, beams, and CLT floor plates. French and German public procurement frameworks now exclude steel and concrete alternatives from low-carbon tender categories.
- Industrial Facilities:Warehousing and light manufacturing employ timber frame shells for speed-to-market delivery in Nordic markets.
- Recreational Structures:Campuses, visitor centers, and athletic facilities showcase exposed timber architecture for institutional donor visibility.
Residential buildings absorb the greatest volume; commercial buildings are expanding most quickly as EU Green Deal mandates harden.
Construction Method:
Customer type divides between factory-controlled quality seekers and site-adapted craft builders with divergent risk appetites for weather exposure and labor coordination.
- Prefabricated:CNC-cut components produced in climate-controlled mills ship to site for crane-assisted assembly. Australian developers exploit National Construction Code amendments permitting 12-story timber buildings through this method for student housing and institutional office.
- Modular:Volumetric units complete with MEP rough-in arrive as sealed building segments. UK and Scandinavian contractors deploy these for hotel and healthcare projects where repetitive bay dimensions compress program duration.
- On-site Fabrication:Traditional timber framers cut and raise heavy timber bents using mortise-and-tenon joinery for custom residential clients.
- Hybrid:Steel or concrete cores paired with timber gravity and lateral systems resolve seismic and fire-rating constraints in California and Japan high-rises.
Prefabricated methods carry the bulk of current throughput; modular construction is gaining share fastest as hospitality developers chase speed-to-revenue metrics.
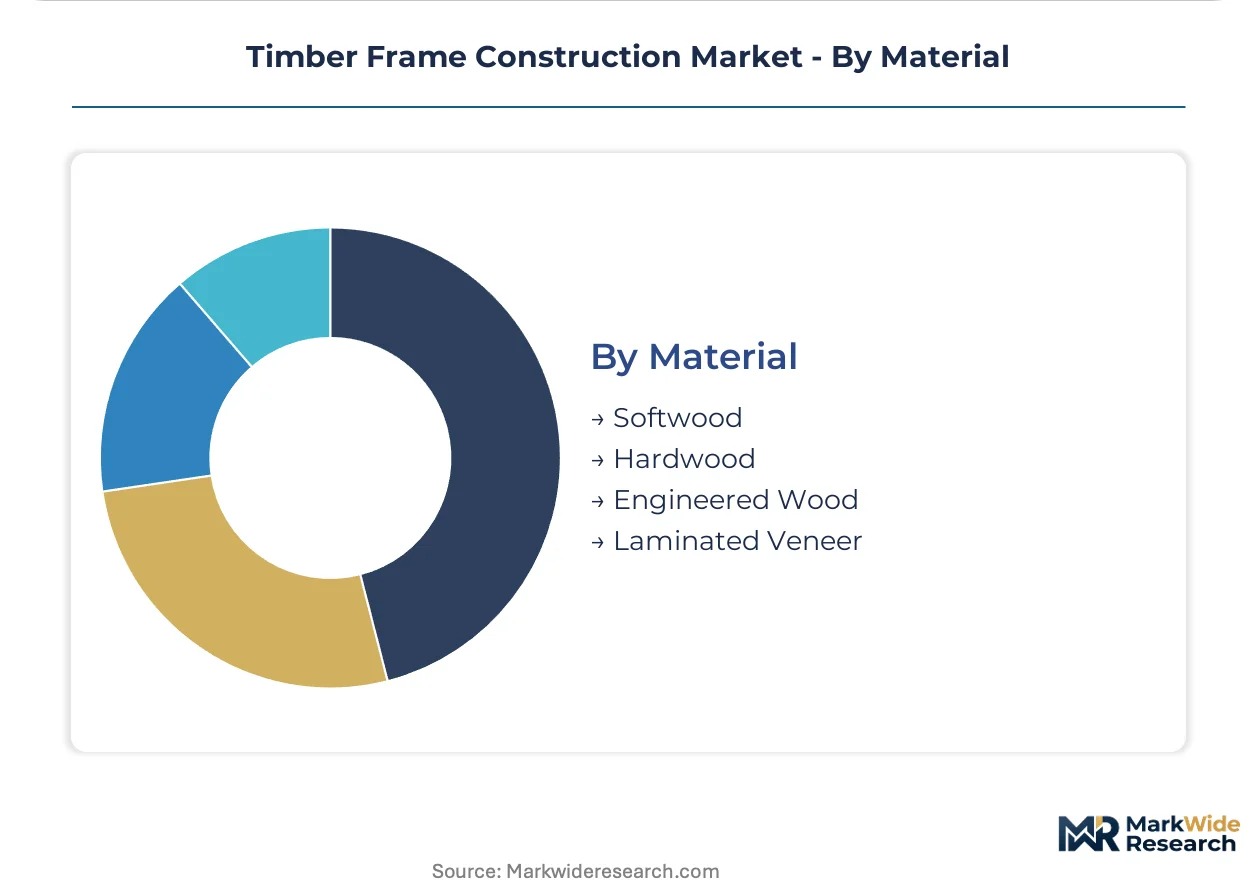
Material:
Supply concentration in Nordic and Pacific Northwest forest basins shapes availability and certification pathways for structural specifications.
- Engineered Wood:Glued-laminated timber, laminated veneer lumber, and oriented strand board deliver predictable strength properties and dimensional stability. German and Austrian mills supply these for commercial spans exceeding solid-sawn capability limits.
- Softwood:Spruce-pine-fir dimensional lumber from Canadian and US Pacific Northwest sawmills feeds residential framing demand. Stora Enso Oyj anchors European supply through vertically integrated forest-to-frame operations.
- Hardwood:Oak, beech, and tropical species serve exposed architectural applications and specialty connection hardware.
- Laminated Veneer:Thin veneer layers bonded in parallel grain orientation produce deep beams for long-span commercial floors and roofs.
Softwood maintains volume leadership; engineered wood shows the steepest expansion trajectory as commercial height allowances extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Timber frame construction flows along distinct trade corridors. Nordic and Pacific Northwest forest basins supply engineered wood to import-dependent markets in Asia-Pacific and Western Europe. Cross-border certification alignment and shipping cost differentials determine where prefabricated systems achieve price competitiveness against regional concrete and steel alternatives.
United States
Multifamily housing developers in Texas and the Southeast specify prefabricated wall frames to compress construction schedules. The International Code Council mass timber provisions adopted by jurisdictions including Oregon and Washington expand permissible building heights. Seattle and Portland anchor Pacific Northwest production clusters where glulam and CLT capacity serves West Coast commercial projects.
Germany
Public housing associations in Bavaria and North Rhine-Westphalia procure timber systems for EnEV-compliant mid-rise residential. The EU Green Deal national implementation mandates lifecycle carbon disclosures that exclude steel and concrete from low-carbon tender categories. Baden-Württemberg engineering firms coordinate design-build delivery for institutional clients seeking turnkey structural liability transfer.
Canada
British Columbia and Quebec sawmills feed North American softwood demand while developing captive mass timber fabrication capacity. The country's national building code amendments align with ICC provisions on tall wood construction. Vancouver and Montreal clusters specialize in hybrid steel-timber systems for seismic and fire-rated commercial applications.
Australia
Student housing and institutional office developers exploit National Construction Code amendments permitting 12-story timber buildings. Sydney and Melbourne contractors deploy prefabricated methods for speed-to-revenue compression on compressed urban sites. Queensland and New South Wales forestry operations expand engineered wood output to reduce import dependence on Nordic supply.
France
Public procurement frameworks under RE2020 regulations mandate embodied carbon thresholds that favor timber frame alternatives for social housing. Auvergne-Rhône-Alpes and Île-de-France regions concentrate design-assist contracting expertise for complex commercial structures. Lyon and Paris engineering clusters advance BIM coordination protocols that determine constructability outcomes for mid-rise office projects.
Timber Frame Construction Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying engineered wood and connection hardware. The vendor base stratifies between turnkey design-build operators and materials-focused mills with fabrication capabilities. Three archetypes dominate: forest-to-frame vertically integrated suppliers, regional prefabrication specialists with CNC manufacturing assets, and custom craft builders serving architectural residential niches. Capacity expansion and strategic partnerships represent the primary competitive vectors as developers seek supply security for multi-project commitments.
Among Nordic forest products groups, Stora Enso Oyj exemplifies the vertically integrated archetype with captive timber supply and engineered wood manufacturing. US-based fabricators including Bensonwood occupy positions within the design-build integration tier, controlling project timelines from specification through assembly. Boise Cascade Company anchors North American distribution density for engineered wood products through extensive dealer networks. Custom Timber Frames and Malmquist Construction represent regional specialists serving residential and light commercial segments with factory-controlled prefabrication systems.
| Leading Market Players |
|---|
| Custom Timber Frames |
| Malmquist Construction |
| Bensonwood |
| Stora Enso Oyj |
| New Energy Works |
| Blue Ribbon Builders |
| Hugh Lofting Timber Framing |
| Boise Cascade Company |
| BOWA |
| Others |
Value Chain & Pricing Dynamics
Baltic Sea freight corridors linking Nordic sawmills to German fabrication centers transmit softwood lumber price volatility directly into downstream structural system premiums. These logistics cost dynamics concentrate pricing power with vertically integrated forest-to-frame operators while forcing project-based buyers into long-term offtake negotiations.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing for engineered wood systems, with three-tier pricing structure across premium, standard, and economy levels differentiating by fire-rating certification and BIM coordination depth. Price compression in standard-grade wall frames intensifies as Canadian and US Pacific Northwest sawmill capacity constraints ease, while premium structural systems command insulation from spot market swings. Residential developers exhibit highest price sensitivity due to thin margins on volume housing, whereas institutional clients absorb premiums for turnkey liability transfer.
Supply Chain Analysis
Export-control regimes on advanced CNC fabrication equipment limit technology transfer to emerging mass timber markets, concentrating precision manufacturing capacity in Germany, Austria, and Canada. Supply chains draw from Nordic spruce-pine-fir feedstock, laminated veneer lumber beams, and steel connection hardware, with single-source vulnerability in CLT press equipment creating bottleneck exposure. Distribution runs through regional prefabrication specialists with captive CNC assets serving project-specific delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for CLT and glulam connection detailing constrains market expansion, with qualified structural engineers concentrated in Nordic and Alpine markets limiting design-build capacity elsewhere.
For Market Incumbents: Pre-empt emerging prefabrication competitors by securing captive softwood supply through backward integration into British Columbia and Quebec forest tenures. Invest in ICC-ES and ETA dual certification capabilities to capture cross-border commercial projects before multi-jurisdictional type approval costs escalate. For New Entrants and Emerging Players: Build out design-assist contracting capabilities targeting Australian student housing and institutional office segments opened by National Construction Code amendments permitting 12-story timber buildings. Exploit digital twin coordination platforms as differentiated entry wedge against established craft builders. For Investors and Strategic Acquirers: Regional prefabrication specialists with CNC manufacturing assets and established architect relationships present optimal acquisition targets for platform consolidation. Long-term viability hinges on carbon credit monetization infrastructure maturity; monitor Verified Carbon Standard methodology adoption rates for biogenic carbon storage as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Tenures | Captive softwood supply from British Columbia and Quebec mills insulates margin compression from spot market volatility. |
| Dual Certification Investment | ICC-ES and ETA parallel approval paths unlock US and EU commercial projects without redundant engineering spend. |
| Design-Assist Contracting Capability | BIM coordination expertise embedded during schematic design captures value previously delegated to general contractors. |
| Digital Twin Logistics Platform | Factory CNC cutting synchronization with crane scheduling compresses on-site assembly windows for urban infill projects. |
| Carbon Credit Infrastructure Development | Verified Carbon Standard methodologies for biogenic carbon storage create incremental revenue streams on certified supply chains. |
Study Parameters
Cross-validation between primary interviews with timber frame fabricators, structural engineering consultants, and multifamily housing developers and secondary sources including ICC code amendment records, EU Energy Performance of Buildings Directive national implementations, and forest products trade data anchors the qualitative findings. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts across residential, commercial, and institutional segments.
Calibration against historical mass timber adoption curves in Germany, Austria, and the Pacific Northwest informs projection parameters across the analysis window. Segmentation dimensions span product type, application, construction method, and material specification, with CAGRs derived from structural code evolution timelines and green bond issuance patterns for low-carbon building materials.
Stress conditions across softwood lumber price volatility bands, insurance underwriting framework revisions, and fire-resistance testing protocol changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in ICC mass timber height allowance amendments or EU Green Deal enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Canada Composite Repair Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Supported Scaffolding Market
Structural Construction
South Korea Construction Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
H Beam Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Girder Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Steel Beam Market