
 Global Steel Sections Market | 2026-2036
Global Steel Sections Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steel Sections Market Foresight
Subscription-based steel procurement platforms is repositioning how mills and fabricators contract for long products. ArcelorMittal SA leverages its integrated European production network to secure rolling capacity for complex beam profiles. Nucor Corp anchors its position through electric-arc-furnace flexibility and regional distribution density across the US Southeast. Tata Steel competes on specialized high-strength sections serving bridge and power-transmission tower fabricators.
Steel sections are hot-rolled or cold-formed structural profiles with standardized cross-sectional geometries, typically produced in grades ranging from S235 to S960 under EN standards, designed to carry axial, bending, and torsional loads in framed structures. Beams and columns dominate volume due to their irreplaceable role in multi-story building frames and industrial shed construction, while angles and channels capture margin in custom fabrication and equipment skids where dimensional precision commands premium pricing. The construction application absorbs the largest share of output, though transportation infrastructure—rail bridges, metro viaducts, and port cranes—is accelerating fastest as governments prioritize resilient logistics networks.
China's SAMR enforces GB/T 706 and GB/T 11263 dimensional tolerances that exclude non-compliant imports from state-backed projects. India's BIS certification mandate for structural steel under IS 2062 creates a compliance barrier for unapproved foreign mills. The EU's CSRD disclosure requirements are pressing European fabricators to document embodied carbon in their section procurement. Stakeholders must monitor how carbon-border adjustments and green-steel premiums reshape supplier qualification criteria before committing to long-term mill contracts.
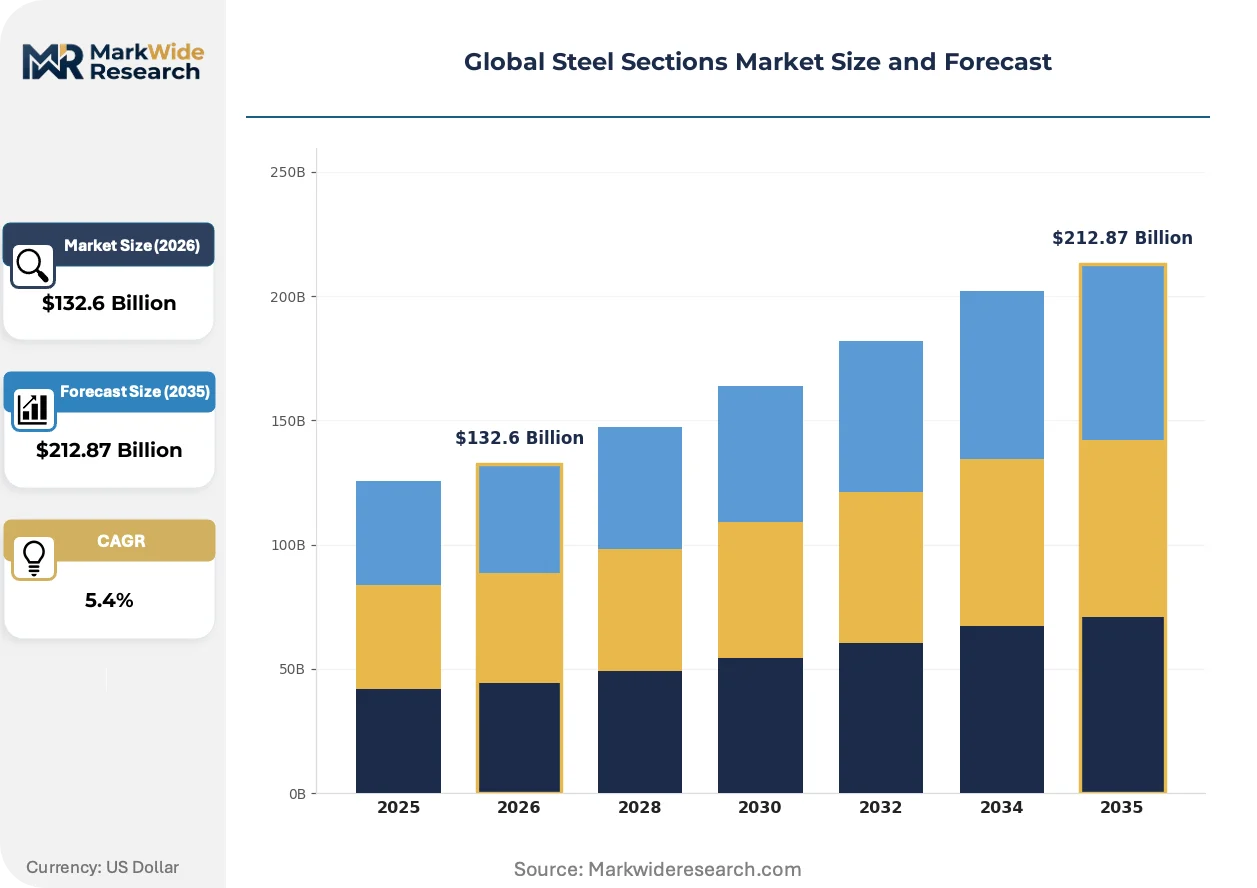
Market Dynamics
Carbon-border adjustments are restructuring supplier qualification across the Global Steel Sections Market, forcing fabricators to document embodied carbon before locking in multi-year mill contracts.
Growth Catalysts
- India's Delhi-Mumbai Infrastructure Corridor:Massive steel-intensive projects spanning high-speed rail, industrial parks, and logistics hubs are absorbing record volumes of structural beams and columns.
- EU CSRD Disclosure Mandate:European fabricators must now track and report embodied carbon in section procurement, creating certified demand for low-carbon production methods.
- Hot-rolling Process Efficiency Gains:Continuous casting and direct rolling technologies are reducing energy intensity per ton, improving margins for complex beam profiles.
Market Restraints
- Iron Ore Price Volatility:Input cost swings for blast furnace operators compress rolling margins and destabilize long-term contracting.
- China Supply Concentration:Domestic GB/T 706 and GB/T 11263 standards enforced by SAMR exclude non-compliant imports, limiting foreign mill access to state-backed projects.
- Aluminum Substitution in Lightweight Structures:Transportation and facade applications are adopting extruded aluminum for corrosion-critical environments.
Strategic Opportunities
- Vietnam and Indonesia Construction Boom:Southeast Asian commercial and industrial building codes are upgrading to require certified structural steel, opening markets previously served by informal supply.
- Bridge and Power Transmission Fabrication:Specialized high-strength sections in S690 and S960 grades command premium pricing from engineering procurement units seeking reduced dead-load designs.
- Subscription Procurement Platforms:Digital contracting interfaces between mills and fabricators are enabling dynamic pricing, volume flexibility, and inventory pooling.
Industry Challenges
- Welding Certification Bottlenecks:Fabricators face 12-18 month delays securing qualified welders for high-strength grade applications under EN 1090 execution classes.
- Legacy ERP Integration:Mill scheduling systems struggle to synchronize with new carbon-accounting modules required for EU CSRD compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steel Sections Market |
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $212.87 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angles, Channels, Beams, Columns Application: Construction, Infrastructure, Transportation, Manufacturing End User: Building Contractors, Fabricators, Engineers, Industrial Users Sales Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Nippon Steel Corp, Baoshan Iron & Steel Co Ltd, ArcelorMittal SA, Steel Dynamics, Inc., Vallourec, Tata Steel, Nucor Corp, Yuantai Derun Group, POSCO Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steel Sections Market Shifts & Advancements
Digital traceability and low-carbon production methods are converging to redefine how structural steel is specified, contracted, and delivered across construction and infrastructure value chains.
High-strength low-alloy grades are consolidating market share in heavy civil engineering. S690 and S960 sections enable longer spans and lighter superstructures for bridge and transmission tower fabricators. European and Indian engineering procurement units are specifying these grades for metro viaducts and power grid expansion, compressing demand for conventional S355 profiles in premium applications.
REACH and the EU Green Deal are forcing integrated mills to disclose Scope 3 emissions or lose access to public infrastructure tenders. Fabricators must now attach environmental product declarations to every section delivery. German and Dutch port authorities are rejecting uncertified steel for crane and warehouse construction, accelerating investment in electric-arc-furnace and hydrogen-direct-reduction routes.
Buyers are consolidating purchase decisions through mill-direct platforms that bypass traditional distributor networks. Large construction consortia in India and Southeast Asia are negotiating frame contracts with rolling mills for guaranteed volume and indexed pricing. This disintermediation is most visible in India's infrastructure corridor, where project developers are sourcing beams and columns directly from Tata Steel and JSW mills to secure certification compliance and delivery priority.
Global Steel Sections Market Segmentation
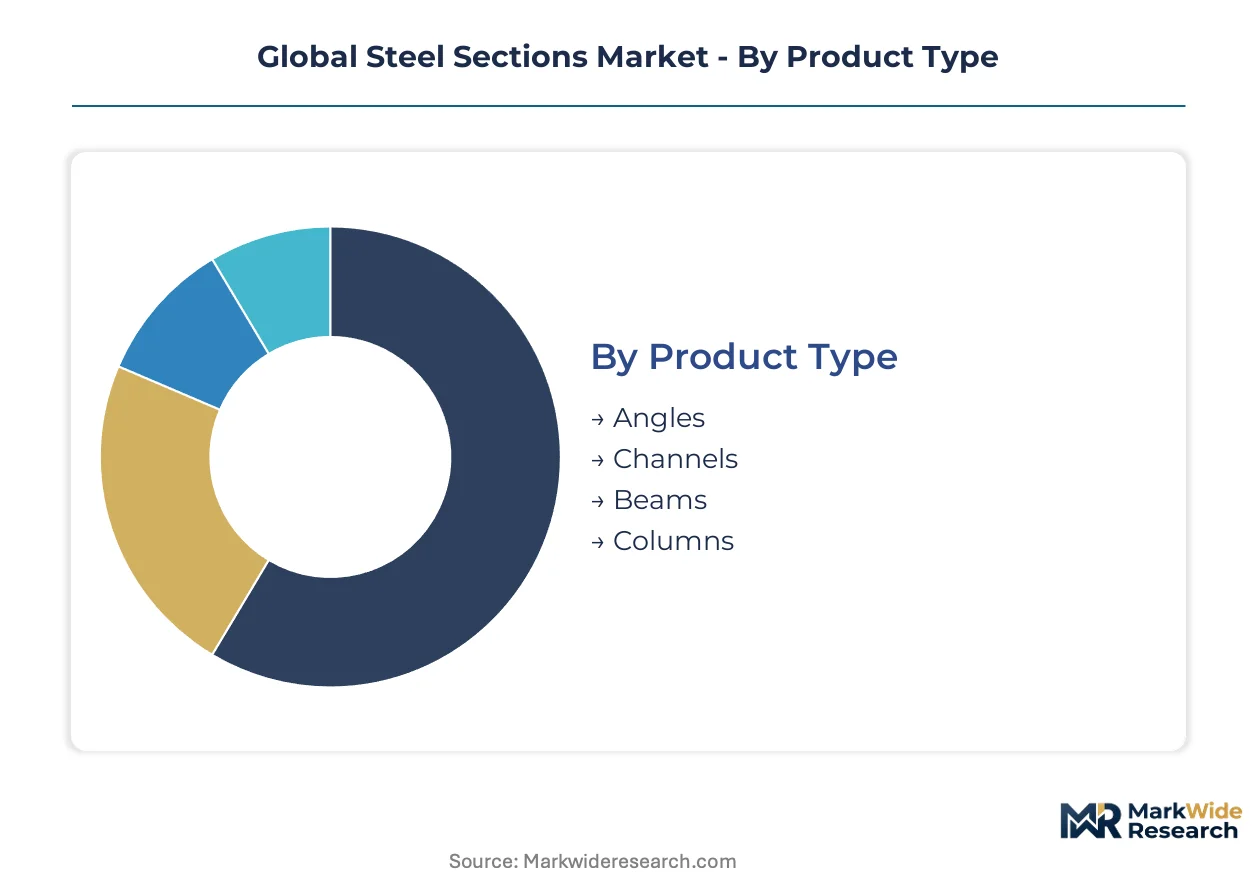
Steel sections markets fragment across product geometries, application intensity, and procurement relationships. Each dimension shapes margin structure, certification requirements, and supplier qualification criteria differently.
Product Type:
Beams and columns dominate tonnage while angles and channels extract premium through customization flexibility.
- Beams:I-shaped and H-shaped profiles engineered for flexural resistance in multi-story frames. India's Delhi-Mumbai corridor is absorbing record volumes for high-speed rail viaducts and station superstructures, with fabricators specifying S355 and S690 grades for span optimization.
- Columns:Square hollow and wide-flange sections designed for axial compression in vertical load paths. Southeast Asian commercial towers are driving adoption of high-strength grades as building codes tighten seismic requirements.
- Angles:L-shaped sections for bracing connections and equipment skids where dimensional precision commands pricing premiums.
- Channels:U-shaped profiles serving conveyor supports and secondary framing in industrial sheds.
Today's leader: Beams. Tomorrow's challenger: Columns.
Application:
Construction absorbs baseline volume while infrastructure applications accelerate fastest on government resilience spending.
- Infrastructure:Bridge decks, metro viaducts, port cranes, and power transmission towers requiring certified high-strength sections. European engineering procurement units under EU Green Deal mandates are specifying S960 grades for reduced dead-load designs on long-span crossings.
- Transportation:Rail bridges, airport terminals, and logistics hubs where fatigue resistance governs material selection. China's SAMR-enforced GB/T standards are excluding non-compliant imports from state-backed rail projects.
- Construction:Commercial and residential building frames representing the foundational demand layer.
- Manufacturing:Equipment skids, machinery bases, and process structures where standard grades suffice.
Construction holds current volume leadership. Infrastructure is climbing the fastest on public procurement acceleration.
End User:
Fabricators intermediate between mills and projects while contractors consolidate purchase power through direct mill relationships.
- Fabricators:Specialized shops cutting, welding, and surface-treating sections for engineered structures. EN 1090 execution class certification requirements are creating 12-18 month welding qualification bottlenecks for high-strength grade applications.
- Building Contractors:Large construction consortia negotiating frame contracts directly with rolling mills for guaranteed volume and indexed pricing.
- Engineers:Design firms specifying grade and tolerance requirements that flow through to mill procurement criteria.
- Industrial Users:Manufacturing firms sourcing standard sections for in-house structures and maintenance.
Fabricators currently intermediate most volume. Building contractors are gaining procurement leverage through disintermediation.
Sales Channel:
Direct mill relationships are displacing traditional distributor networks for large project developers.
- Direct Sales:Mill-to-fabricator contracting with frame agreements, volume commitments, and carbon-accounting documentation. Subscription-based procurement platforms are enabling dynamic pricing and inventory pooling between Indian mills and Southeast Asian developers.
- Distributors:Regional stockists serving fragmented demand with shorter lead times and cutting services.
- Online Platforms:Digital marketplaces aggregating spot demand for standard grades.
- Retailers:Local merchants serving maintenance and small-project demand.
Direct sales command premium project volume. Distributors retain fragmented spot demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs more structural steel tonnage than India and the United States combined, yet India's infrastructure build-out is narrowing the per-capita consumption gap faster than any major economy.
China
SAMR-enforced GB/T 706 and GB/T 11263 standards exclude non-compliant imports from state-backed rail and metro projects. The Yangtze River Delta cluster around Shanghai anchors rolling capacity for complex H-beam profiles serving high-speed rail viaducts. Domestic mills are consolidating to meet tightening dimensional tolerance requirements.
India
BIS certification under IS 2062 creates a compliance barrier for unapproved foreign suppliers targeting the Delhi-Mumbai Infrastructure Corridor. The corridor itself is absorbing record beam and column volumes for high-speed rail stations and logistics hubs. JSW and Tata mills in Maharashtra and Gujarat are securing direct frame contracts with project developers.
United States
Nucor anchors regional supply through electric-arc-furnace flexibility across the Southeast. The country's Buy America provisions for federally funded infrastructure are redirecting procurement toward domestic rolling mills. Texas and Gulf Coast petrochemical expansion is driving demand for heavy wide-flange columns.
Germany
EU CSRD disclosure requirements are pressing fabricators to document embodied carbon in section procurement. The Ruhr industrial corridor maintains specialized rolling capacity for bridge-grade S690 and S960 profiles. Port authorities in Hamburg and Rotterdam are rejecting uncertified steel for crane construction.
Vietnam
Commercial construction in Ho Chi Minh City and Hanoi is upgrading to certified structural steel under revised building codes. The country's national standards body is aligning tolerance requirements with ASEAN harmonization frameworks. Korean and Japanese mills are establishing local distribution partnerships to bypass informal supply channels.
Global Steel Sections Market Competitive Landscape
Top-tier vendors anchor integrated production networks, while regional electric-arc-furnace operators capture flexibility premiums. The market structures around three tiers: global integrated mills with captive iron ore, regional minimill clusters serving construction demand, and specialized fabricators focused on high-strength grades. Strategic moves concentrate on backward integration into scrap processing and carbon-accounting certification for EU public tenders.
Within the integrated mill tier, ArcelorMittal SA and Nippon Steel Corp exemplify scale-driven positioning across multiple continental markets. Tata Steel occupies a specialist position serving bridge and power-transmission fabricators with certified high-strength sections. These three entities represent contrasting geographic and technological archetypes: European network integration, East Asian coastal export capacity, and Indian domestic infrastructure alignment.
| Leading Market Players |
|---|
| Nippon Steel Corp |
| Baoshan Iron & Steel Co Ltd |
| ArcelorMittal SA |
| Steel Dynamics, Inc. |
| Vallourec |
| Tata Steel |
| Nucor Corp |
| Yuantai Derun Group |
| POSCO Holdings Inc |
| Others |
Supply & Pricing Matrix
Horizontal integration among Chinese state-owned mills anchors both supply security and pricing leverage across the Global Steel Sections Market. SAMR-enforced GB standards tighten dimensional tolerances while locking out non-compliant imports, compressing margin pressure onto foreign suppliers competing for state-backed infrastructure tenders.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard-grade beams across Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels separates S960 bridge-grade certified sections from S355 commercial construction stock and uncertified informal supply. Cost compression in standard grades intensifies because Indonesian mills are commissioning new rolling capacity with ASEAN-harmonized tolerance standards. Building contractors negotiating direct frame contracts exhibit lowest price sensitivity due to volume commitments and carbon-accounting documentation requirements, while small fabricators purchasing through regional distributors face highest sensitivity to spot price volatility.
Supply Chain Analysis
India's BIS certification mandate under IS 2062 is reshaping sourcing patterns for the Delhi-Mumbai Infrastructure Corridor, forcing project developers toward approved domestic mills. Geographic supply concentrates in China, India, and Japan, with the Yangtze River Delta cluster anchoring complex H-beam capacity for high-speed rail applications. Raw material flows draw from Australian iron ore, Mongolian coking coal, and domestic scrap pools feeding electric-arc-furnace operators. Single-source vulnerability runs through concentrated rolling mill capacity for specialized S690 and S960 grades. Distribution runs through mill-direct frame contracts for large infrastructure consortia, bypassing traditional stockist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Steel Sections Market compounds on regulatory density, with EU CSRD disclosure mandates creating certified demand premiums for low-carbon production methods across public infrastructure procurement.
For Market Incumbents: Deepen backward integration into scrap processing and hydrogen-direct-reduction routes to secure carbon-accounting documentation for EU tender eligibility. Aluminum substitution in lightweight transportation structures threatens margin compression in facade and corrosion-critical applications. Investment in EN 1090 welding certification pipelines addresses 12-18 month qualification bottlenecks for high-strength grade fabrication. For New Entrants and Emerging Players: Southeast Asian commercial contractors upgrading to certified structural steel under revised building codes represent the most penetrable buyer archetype. Vietnam's national standards body alignment with ASEAN harmonization frameworks opens formal supply channels previously captured by informal imports. Korean and Japanese mills are establishing local distribution partnerships as a proven go-to-market template for bypassing unregulated competition. For Investors and Strategic Acquirers: Roll-up economics work for regional electric-arc-furnace operators because carbon-border adjustments are restructuring supplier qualification criteria across European public tenders. Mid-scale minimill clusters with scrap-processing captive supply and CSRD-compliant carbon accounting offer strongest 5-10 year positioning. Watch for BIS certification expansion beyond IS 2062 into additional specialty grades as the inflection signal for Indian market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Processing | Captive feedstock secures electric-arc-furnace margins against iron ore volatility. |
| Hydrogen-Direct-Reduction Route Investment | German and Dutch port authorities now reject uncertified steel for crane construction. |
| EN 1090 Welding Certification Pipeline | Execution class qualification bottlenecks constrain high-strength grade fabrication capacity. |
| Mill-Direct Procurement Platform Launch | Subscription interfaces enable dynamic pricing between Indian mills and Southeast Asian developers. |
| BIS Certification Acquisition | IS 2062 approval creates compliance barrier protecting Delhi-Mumbai corridor supply share. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates for the Global Steel Sections Market. Primary engagement covered rolling mill operations directors, structural steel procurement managers at EPC contractors, EN 1090 certification body auditors, and carbon-accounting software vendors serving EU fabricators. Secondary validation drew from customs trade databases, BIS certification registries, SEC filings of listed steel producers, and EU Tender Electronic Daily procurement notices. Bottom-up project pipeline analysis triangulated against top-down apparent consumption estimates across the analysis window.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product geometry, application intensity, grade certification tier, and procurement relationship type. CAGRs derived from slope-log regression across disaggregated segment trajectories, incorporating steel intensity coefficients for infrastructure project typologies and building code evolution timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; certified high-strength grades carry tighter precision than informal economy supply. Forecasts embed assumptions around regulatory enforcement consistency for GB, BIS, and EU CSRD frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Plumbing Components Market