
 Self-Consolidating Concrete (SCC) Market | 2026-2036
Self-Consolidating Concrete (SCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Consolidating Concrete (SCC) Market Analytics
Multi-source procurement for polycarboxylate-based superplasticizers is broadening as contractors seek supply resilience against raw material volatility. Sika AG leverages its integrated admixture platform to sustain technical service density across European project corridors. Heidelberg Materials anchors volume through captive cement-to-concrete logistics, while UltraTech Cement Limited dominates South Asian SCC supply with slag-optimized blends for marine precast.
Self-consolidating concrete is a highly flowable, non-segregating concrete that achieves full compaction under its own weight, typically incorporating viscosity-modifying admixtures to maintain homogeneity in heavily reinforced sections. Its primary purpose is enabling complex architectural geometries and accelerated construction schedules without mechanical vibration. High performance SCC commands premium positioning in infrastructure bids where durability specifications exceed standard grade, while precast application segments absorb the fastest volume growth due to factory-controlled curing conditions. Fiber reinforced variants compete on seismic performance in high-rise cores, though standard grades still occupy the bulk residential margin pool.
US EPA stormwater regulations and OSHA silica exposure limits shape admixture selection and jobsite handling protocols across North American projects. European ECHA REACH registration requirements for synthetic polymers constrain formulation flexibility while creating compliance barriers for non-EU suppliers. Stakeholders must monitor evolving embodied carbon thresholds in public procurement standards, as these will determine which grade categories retain specification access in infrastructure tenders.
Market Dynamics
Specification pressure from megaproject durability requirements is compressing the acceptable performance envelope for SCC formulations, forcing simultaneous optimization of flow retention, segregation resistance, and chloride permeability metrics that previously traded off against each other.
Growth Catalysts
- Bridge deck rehabilitation mandates:Aging infrastructure inventories in the United States and Germany are triggering blanket SCC specifications for cathodic protection compatibility and extended service life targets.
- REACH polymer registration completion:ECHA's full registration of polycarboxylate ether superplasticizers has removed formulation uncertainty for European producers, stabilizing admixture supply chains.
- Slag-blend optimization:Supplementary cementitious material advances are reducing binder carbon intensity while maintaining rheology, opening public procurement doors previously closed to conventional concrete.
Market Restraints
- Naphtha-cracker derivative volatility:Ethylene oxide and propylene oxide feedstock costs for superplasticizer synthesis swing with crude oil benchmarks, compressing margin predictability for admixture suppliers.
- High-purity limestone concentration:Quality aggregate for SCC rheology control clusters in specific geological formations, creating transport-cost penalties for projects distant from extraction sites.
- Shotcrete substitution in tunnel linings:Wet-mix sprayed concrete with accelerators is displacing SCC in certain underground applications where immediate early strength outweighs surface finish requirements.
Strategic Opportunities
- Carbon-capture concrete integration:CO2 mineralization technologies are converging with SCC production workflows, enabling negative-emission precast claims that command green procurement premiums.
- Modular hospital construction:Healthcare infrastructure acceleration programs in Saudi Arabia and the UAE are specifying factory-cured SCC modules for infection-control wall assemblies.
- Digital concrete passport mandates:The EU Green Deal's embodied carbon disclosure requirements are creating first-mover advantage for suppliers with batch-to-batch traceability systems.
Industry Challenges
- Rheology technician scarcity:SCC mix design and quality control demand specialized expertise in viscometry and thixotropy modeling that outpaces vocational training pipeline output.
- Multi-jurisdictional certification lag:Cross-border projects face incompatible national concrete standards requiring redundant testing protocols and extended approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Consolidating Concrete (SCC) Market |
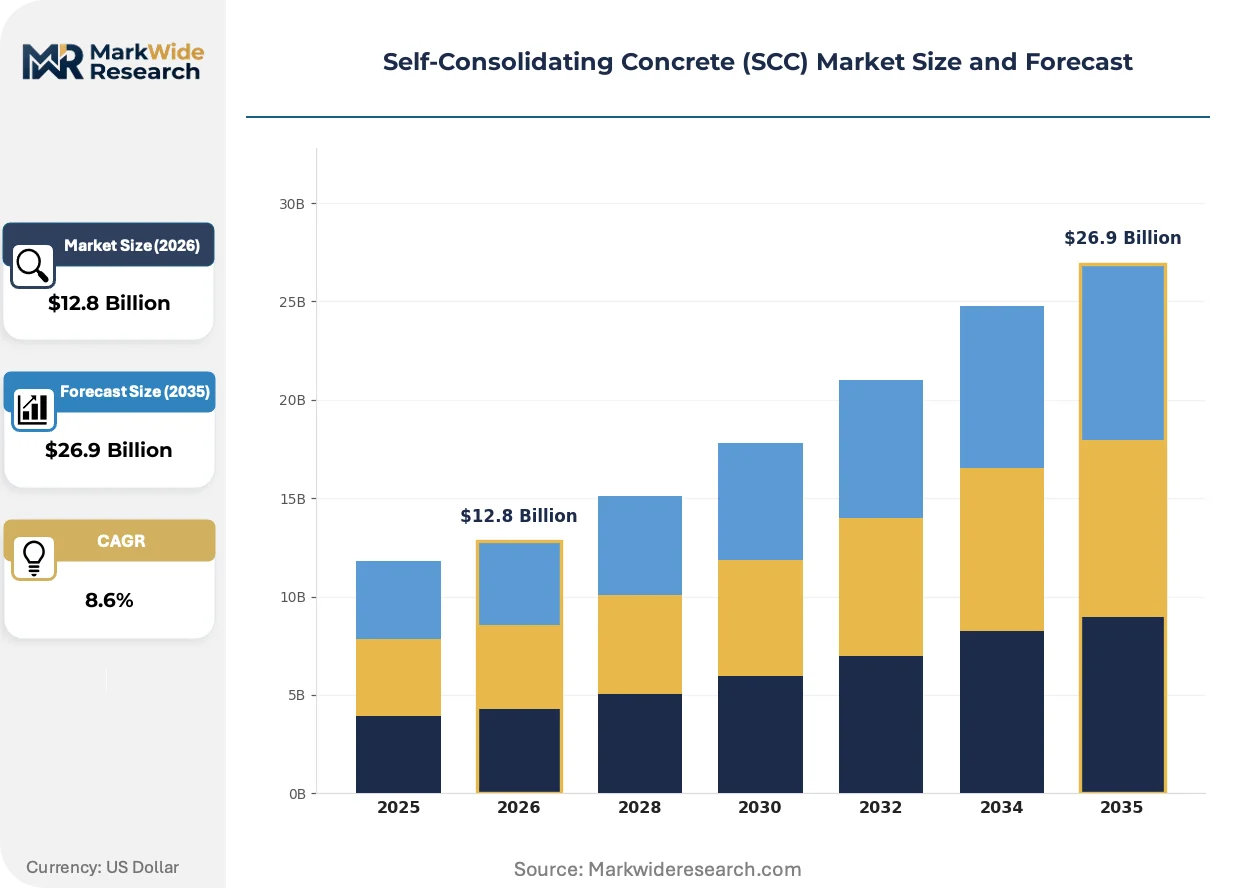
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Performance, Fiber Reinforced, Lightweight, Standard Application: Residential, Commercial, Infrastructure, Precast End User: Contractors, Construction Companies, Architects, Engineers Grade: Normal Strength, High Strength, Ultra High Strength, Specialty |
| Companies Covered | Sika AG, BASF SE, CEMEX S.A.B. de C.V., Holcim, ACC Limited, UltraTech Cement Limited, Heidelberg Materials, CRH, Buzzi Unicem S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Consolidating Concrete (SCC) Market Evolving Landscape
Formulation science is advancing faster than jobsite execution capabilities, creating a persistent gap between laboratory-optimized SCC performance and field-realized outcomes that technology providers are racing to close.
Cellulose-based viscosity modifiers are expanding into high-temperature concreting applications where synthetic alternatives degrade. Contractors in the Arabian Peninsula and Australia's Pilbara region are specifying these biopolymers for pours exceeding 40°C ambient conditions. The shift is compressing the seasonal construction window advantage previously held by temperate-climate competitors.
OSHA's updated silica permissible exposure limit is tightening jobsite handling protocols for powdered admixtures across United States infrastructure projects. Ready-mix producers are responding with liquid-delivery system investments and enclosed silo configurations. The regulatory pressure falls heaviest on smaller batch plants lacking capital for pneumatic system upgrades.
Pre-qualification bundling is consolidating specification authority into fewer engineering-procurement-construction firms with captive concrete testing laboratories. Tier-one contractors in China's Yangtze River Delta and India's Mumbai-Pune corridor are internalizing mix design validation previously outsourced to independent facilities. The concentration shifts risk allocation and margin capture toward integrated project delivery structures.
Self-Consolidating Concrete (SCC) Market Segmentation
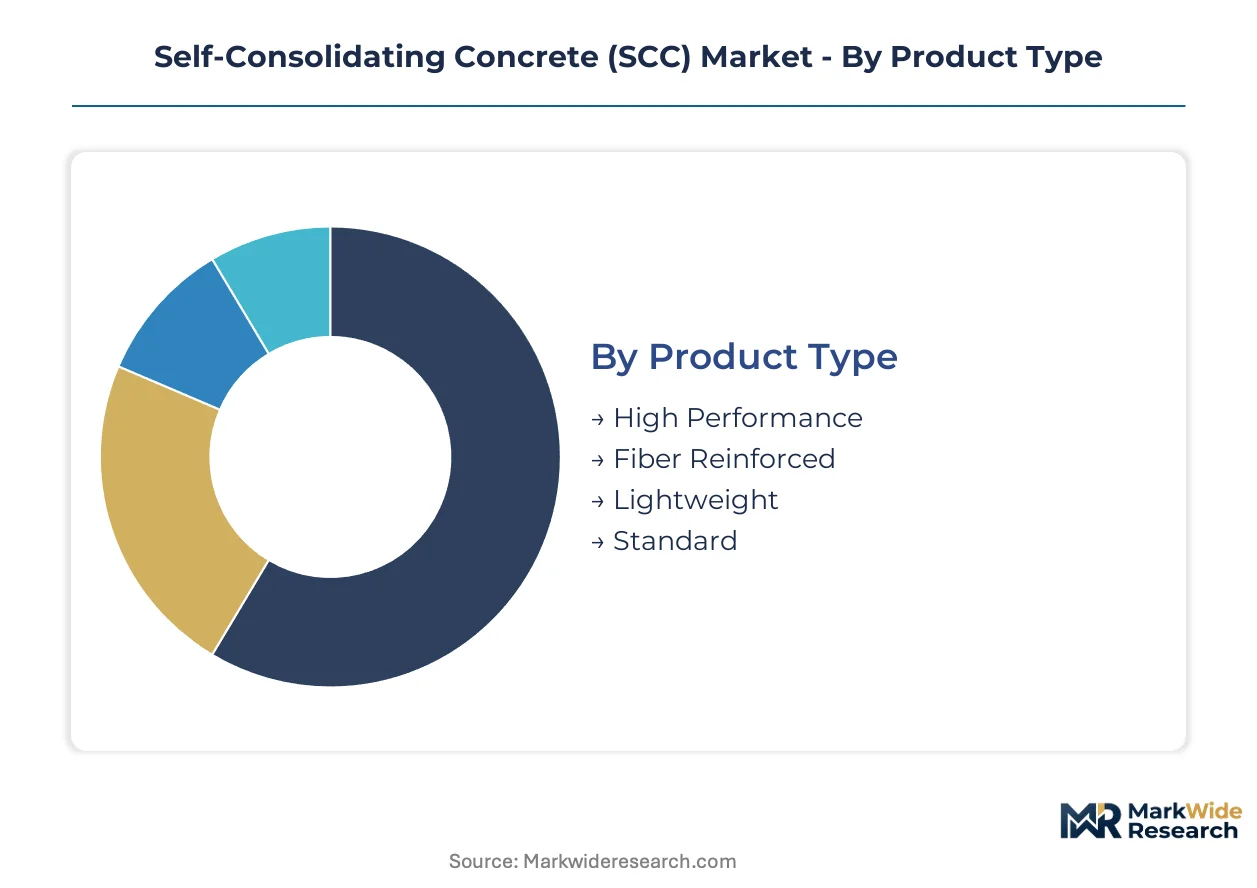
SCC formulations diverge sharply across performance tiers, with specification authority consolidating around durability-driven infrastructure grades while cost-optimized variants compete on volume in residential construction. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressure dominates procurement decisions.
Product Type:
Volume concentrates in standard formulations, while premium positioning clusters around performance-engineered variants with specialized rheology control.
- High Performance:Formulations achieve chloride permeability below 1000 coulombs and compressive strength exceeding 60 MPa through optimized paste content and polycarboxylate superplasticizer dosing. Demand clusters in German autobahn bridge decks and Japan's seismic-resistant high-rise cores where 100-year service life specifications command material premiums.
- Fiber Reinforced:Polypropylene or steel fiber incorporation enhances post-crack ductility and impact resistance for tunnel lining and blast-resistant structures. Saudi Arabia's Riyadh Metro extensions and Singapore's underground utilities corridors specify these variants for crack width control under dynamic loading.
- Lightweight:Expanded shale or pumice aggregate substitution reduces dead load for long-span precast elements.
- Standard:Baseline flowable concrete for architectural fair-faced walls and lightly reinforced slabs where vibration elimination drives specification rather than extreme durability.
Mature deployment sits with Standard. Newer deployment is concentrated in Fiber Reinforced.
Application:
Precast factory conditions enable tightest quality control, while infrastructure field pours demand highest rheology retention windows.
- Precast:Controlled curing environments permit extended flow retention requirements and automated placement without segregation risk. China's Pearl River Delta precast plants and India's Ahmedabad-Mumbai industrial corridor absorb volume for modular building components and precast bridge girders.
- Infrastructure:Bridge decks, tunnel linings, and marine structures specify SCC for dense reinforcement congestion and accelerated construction schedules. German federal highway rehabilitation programs and US state DOT maintenance contracts drive specification depth for cathodic protection compatibility.
- Commercial:High-rise cores and complex architectural geometries in UAE commercial towers and Australian mixed-use developments.
- Residential:Foundation walls and slab-on-grade applications where labor savings from vibration elimination outweigh material cost premiums.
Margin capture concentrates in Precast. Volume expansion is climbing the fastest in Infrastructure.
End User:
Specification authority is consolidating into integrated engineering-procurement-construction firms with captive testing capabilities.
- Contractors:Tier-one construction groups in China's Yangtze River Delta and India's Mumbai-Pune corridor internalize mix design validation and batch-to-batch quality control, shifting risk allocation from independent laboratories.
- Construction Companies:Mid-scale regional builders specify SCC for labor productivity gains in repetitive structural elements.
- Architects:Exposed concrete aesthetic requirements in Nordic public buildings and Brazilian cultural institutions drive fair-faced finish specifications.
- Engineers:Structural consultants mandate SCC for seismic performance in Japan's high-rise cores and Chile's subduction zone infrastructure.
Technical authority rests with Engineers. Procurement volume aggregates through Contractors.
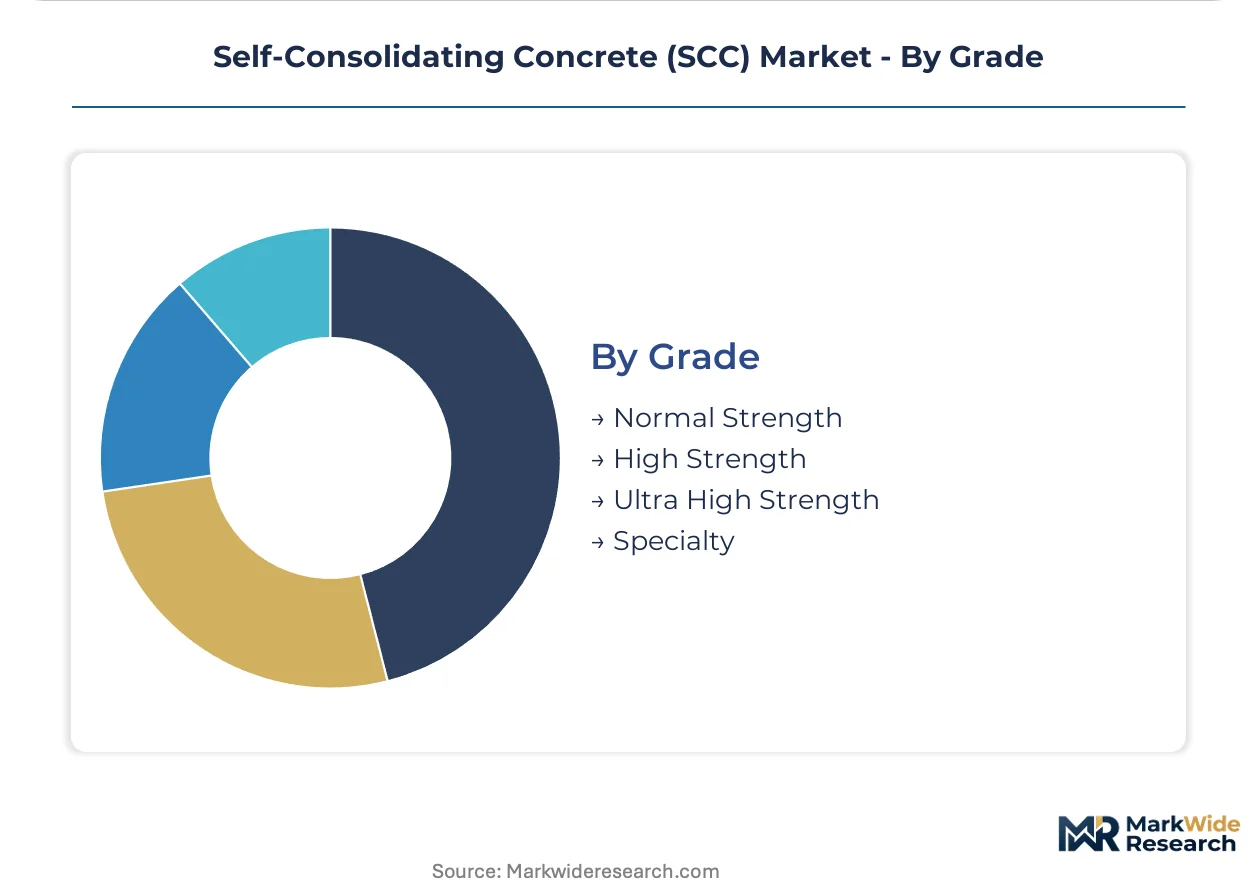
Grade:
Strength classification determines admixture intensity and cementitious binder content, directly mapping to carbon intensity and public procurement eligibility.
- Ultra High Strength:Compressive capacity exceeding 100 MPa with silica fume and metakaolin densification for thin structural elements and high-strength precast connections. Norway's coastal highway bridges and South Korea's Incheon Airport expansion specify these grades for durability in chloride exposure.
- High Strength:60-100 MPa range balancing rheology retention with structural efficiency for high-rise columns and long-span elements.
- Normal Strength:30-60 MPa formulations for general architectural and structural applications where flow characteristics outweigh strength premium.
- Specialty:Custom rheology for temperature extremes, underwater placement, or radiation shielding with project-specific qualification protocols.
Carbon regulation pressure weighs heaviest on Normal Strength. Technical differentiation is expanding most quickly in Specialty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity limestone deposits in the Jura Mountains anchor European SCC formulation quality, while polycarboxylate superplasticizer production clusters along the US Gulf Coast ethylene corridor. Bridge rehabilitation mandates and megaproject durability specifications are compressing regional supply chains toward integrated admixture-to-concrete platforms.
United States
State DOT bridge deck rehabilitation programs in California, Texas, and New York specify SCC for cathodic protection compatibility and 75-year service life targets. OSHA's updated silica permissible exposure limit tightens jobsite handling protocols for powdered admixtures, accelerating liquid-delivery system investments. The Gulf Coast petrochemical corridor from Houston to Baton Rouge concentrates superplasticizer synthesis capacity near ethylene oxide feedstock sources.
Germany
Federal autobahn bridge rehabilitation contracts mandate chloride permeability below 1000 coulombs, forcing high-performance SCC specifications across Bavaria and North Rhine-Westphalia. ECHA REACH registration of polycarboxylate ether superplasticizers has removed formulation uncertainty, stabilizing admixture supply chains for domestic producers. The Rhine-Ruhr industrial corridor anchors captive cement-to-concrete logistics for infrastructure project density.
China
The megacity corridor from Shanghai to Guangzhou absorbs the fastest SCC volume growth for precast modular construction and high-speed rail bridge components. MIIT dual carbon goals and GB standards on embodied carbon are tightening public procurement eligibility for conventional concrete grades. The Yangtze River Delta precast plant network internalizes mix design validation previously outsourced to independent laboratories.
India
Marine precast specifications for Mumbai coastal road and Gujarat port infrastructure drive slag-optimized SCC blend demand. BIS certification requirements for high-performance concrete create compliance barriers for non-domestic admixture suppliers. The Mumbai-Pune corridor concentrates tier-one contractor captive testing capabilities, shifting risk allocation from independent facilities.
Saudi Arabia
Healthcare infrastructure acceleration programs specify factory-cured SCC modules for infection-control wall assemblies in Riyadh and Jeddah medical cities. SFDA building material regulations align with EU REACH polymer standards, creating formulation continuity for European admixture suppliers. The Riyadh Metro extensions and NEOM linear city project specify fiber-reinforced variants for crack width control under dynamic loading.
Self-Consolidating Concrete (SCC) Market Competitive Landscape
Global majors compete with regional champions across integrated admixture-to-concrete platforms and captive logistics networks. The market structure tiers between multinational chemical conglomerates with polymer synthesis capabilities and regional cement producers with backward integration into aggregate and slag supply. Three archetypes dominate: integrated chemical-admixture platforms, captive cement-to-concrete logistics operators, and slag-optimized blend specialists. Consolidation pressure is accelerating through strategic partnerships between admixture technology licensors and ready-mix volume aggregators.
Within the integrated platform tier, Sika AG and BASF SE exemplify the chemical-admixture-to-technical-service model, anchoring formulation science density across European project corridors. Among cement-producer champions, Heidelberg Materials occupies a position representing captive vertical control over clinker, slag, and ready-mix logistics. UltraTech Cement Limited sits within the slag-optimization archetype, commanding South Asian marine precast specifications through blended binder expertise.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| CEMEX S.A.B. de C.V. |
| Holcim |
| ACC Limited |
| UltraTech Cement Limited |
| Heidelberg Materials |
| CRH |
| Buzzi Unicem S.p.A. |
| Others |
Value Network & Pricing Analysis
Ethylene oxide feedstock volatility cascades from Gulf Coast petrochemical clusters through polycarboxylate superplasticizer synthesis costs, compressing margin pools for standard-grade SCC while performance-tier suppliers absorb fluctuations through technical-service bundling.
Pricing Analysis
Warranty-backed rheology retention guarantees separate premium SCC suppliers from commodity-grade competitors in infrastructure tender evaluations. Three-tier pricing structure across high-performance, fiber-reinforced, and standard levels tracks certification grade and volume scale, with German autobahn specifications commanding material premiums over residential foundation applications. Price erosion runs through standard-grade residential segments as regional ready-mix producers compete on labor-cost savings from vibration elimination. Contractors in China's Yangtze River Delta exhibit lowest price sensitivity due to captive testing capabilities and specification authority consolidation.
Supply Chain Analysis
Pre-qualification certification requirements for ECHA REACH polymer registration gate European SCC admixture supply, favoring established chemical platforms over import-dependent challengers. Production gravity centers on Germany's Rhine-Ruhr corridor, the US Gulf Coast ethylene belt, and China's Yangtze River Delta petrochemical hubs. Formulation science draws from high-purity limestone deposits in the Jura Mountains, ethylene oxide derivatives from naphtha crackers, and viscosity-modifying biopolymers from cellulose processors. Single-source vulnerability concentrates in polycarboxylate ether superplasticizer synthesis where ethylene oxide supply disruptions propagate rapidly. Distribution runs through captive cement-to-concrete logistics networks anchored by Heidelberg Materials and integrated ready-mix platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH compliance on synthetic polymer admixtures erects a cost-of-compliance barrier that entrenches registered European suppliers while excluding non-EU formulation competitors from public infrastructure tenders.
For Market Incumbents: Lock in specification authority by internalizing rheology technician training pipelines and pre-qualification bundling with tier-one EPC firms. Shotcrete substitution in tunnel linings threatens SCC volume in underground applications; counter through carbon-capture concrete integration claims that secure green procurement premiums in European public tenders. For New Entrants and Emerging Players: Modular hospital construction programs in Saudi Arabia and the UAE represent an underserved buyer archetype with factory-cured SCC module demand outpacing domestic supply capacity. Target healthcare infrastructure acceleration corridors with infection-control wall assembly specifications, entering through European admixture technology licensing partnerships that satisfy SFDA building material regulations. For Investors and Strategic Acquirers: Completion of ECHA REACH polymer registration for polycarboxylate ether superplasticizers is the leading indicator that formulation uncertainty has stabilized and European supply chains are de-risked for consolidation plays. The analysis window favors integrated chemical-admixture platforms with backward integration into ethylene oxide feedstock over pure-play ready-mix volume aggregators. Monitor digital concrete passport mandate implementation across EU member states as the signal for batch-to-batch traceability system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Capture Concrete Integration | CO2 mineralization convergence with SCC workflows enables negative-emission precast claims commanding green procurement premiums in German federal tenders. |
| Rheology Technician Training Pipeline | Specialized viscometry expertise scarcity outpaces vocational output; captive training locks in quality control differentiation against regional competitors. |
| Digital Concrete Passport Compliance | EU Green Deal embodied carbon disclosure mandates create first-mover advantage for suppliers with batch-to-batch traceability systems in infrastructure bids. |
| Slag-Blend Optimization Scale-Up | Supplementary cementitious material advances reduce binder carbon intensity while maintaining rheology, opening public procurement doors previously closed to conventional concrete. |
| Cellulose-Based Viscosity Modifier Sourcing | Biopolymer specification expansion for high-temperature concreting in Arabian Peninsula projects compresses seasonal construction window advantages held by temperate-climate competitors. |
Research Methodology
Independent corroboration across admixture supplier technical directors, ready-mix plant managers, and state DOT materials engineers underwrites the qualitative findings on specification pressure dynamics. Primary fieldwork with EPC procurement leads, concrete testing laboratory supervisors, and bridge deck rehabilitation contractors combined with secondary validation through ECHA REACH registration databases, US EPA stormwater compliance filings, and MIIT dual carbon policy directives. Bottom-up volume aggregation across precast plant networks and top-down demand estimation from infrastructure tender pipelines established convergent baseline figures.
Rate-of-change decomposition across product type tiers, application segments, and regional regulatory clusters structured the analytical framework over the projection horizon. Segmentation dimensions modeled include performance grade classification, end-use application intensity, and embodied carbon threshold compliance status. CAGRs derived from historical specification rate trajectories in bridge rehabilitation programs and megaproject durability mandates, cross-referenced with polycarboxylate superplasticizer production capacity expansion announcements and slag supply availability curves.
Revisions become necessary when ECHA polymer registration timelines shift, OSHA silica exposure limits tighten further, or embodied carbon thresholds in public procurement standards drop below current SCC grade capabilities. A model refresh is warranted upon material change in crude oil benchmark volatility affecting ethylene oxide feedstock economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Bridge Bearings Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Timber Frame Construction Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
H Beam Market