
 Supported Scaffolding Market | 2026-2036
Supported Scaffolding Market Size, Share, and Industry Trends Forecast 2026-2036
Supported Scaffolding Market Analytics
Preventive maintenance subscriptions and digital inspection services is decoupling equipment ownership from site readiness obligations. PERI GmbH leverages its engineering-led rental model to anchor long-term contracts across German-speaking Europe. BrandSafway sustains its position through vertical integration into engineered access solutions for complex industrial turnarounds. ULMA Construction differentiates via aluminum system specialization in markets where weight reduction commands premium positioning.
Supported scaffolding comprises temporary elevated work platforms constructed from modular frames, braces, and planks engineered to bear specified live loads, typically fabricated from galvanized steel or extruded aluminum with load ratings governed by EN 12811 and OSHA 1926 Subpart L. Its primary commercial purpose is to provide safe personnel access during construction, maintenance, and industrial activities at height. Frame and system product types dominate volume in mature markets where standardized configurations reduce erection labor, while modular aluminum segments capture expanding share in power generation and events end-use categories where rapid assembly and corrosion resistance offset higher unit costs. Steel material platforms still occupy the bulk of construction demand, though composite alternatives are penetrating offshore and chemical manufacturing environments where spark resistance and reduced dead load justify material substitution.
OSHA enforces fall-protection and scaffold-specific training mandates that directly shape product selection and rental documentation requirements in the United States, while the EU's EN 12811 and EN 12812 standards govern load testing and design verification across European member states. China's SAMR and GB standards for construction equipment impose type-testing protocols that filter market access for imported systems. Stakeholders must monitor regulatory divergence between performance-based European norms and prescriptive North American rules when configuring transnational product portfolios and certification budgets.
Market Dynamics
Equipment-as-a-service models are decoupling ownership from site readiness, forcing rental providers to absorb inspection and compliance burdens while capturing long-term contract value through engineering-led service bundling.
Growth Catalysts
- OSHA 1926 Subpart L enforcement:Fall-protection mandates tighten certification documentation, expanding rental penetration as contractors outsource compliance liability.
- Offshore wind installation:Corrosion-resistant aluminum systems capture demand from marine contractors replacing steel in North Sea and Baltic projects.
- China's tier-one mega-projects:Beijing and Shanghai infrastructure density sustains volume for modular frame configurations in high-rise commercial construction.
Market Restraints
- Galvanized steel input volatility:Zinc price swings compress rental margin predictability for fleet operators with fixed-rate annual contracts.
- Fabrication concentration in Hebei Province:Supply disruption risk from single-region dependence for standardized frame production.
- Composite material substitution ceiling:Glass-reinforced polymer planks face load-rating limitations under EN 12811 for heavy masonry applications.
Strategic Opportunities
- India's smart city pipeline:Tier-2 urban clusters lack established rental infrastructure, creating first-mover terrain for system providers.
- Drone-integrated inspection protocols:Automated defect detection converges with digital twin platforms to enable predictive maintenance subscriptions.
- EU Green Deal embodied carbon rules:Aluminum recycling credentials and lifecycle assessments become procurement differentiators for public sector tenders.
Industry Challenges
- Qualified erection supervisor scarcity:OSHA competent person certification bottlenecks constrain fleet deployment velocity during peak construction windows.
- Multi-standard certification burden:EN 12811, OSHA 1926, and GB standard divergence forces redundant testing budgets for transnational product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supported Scaffolding Market |
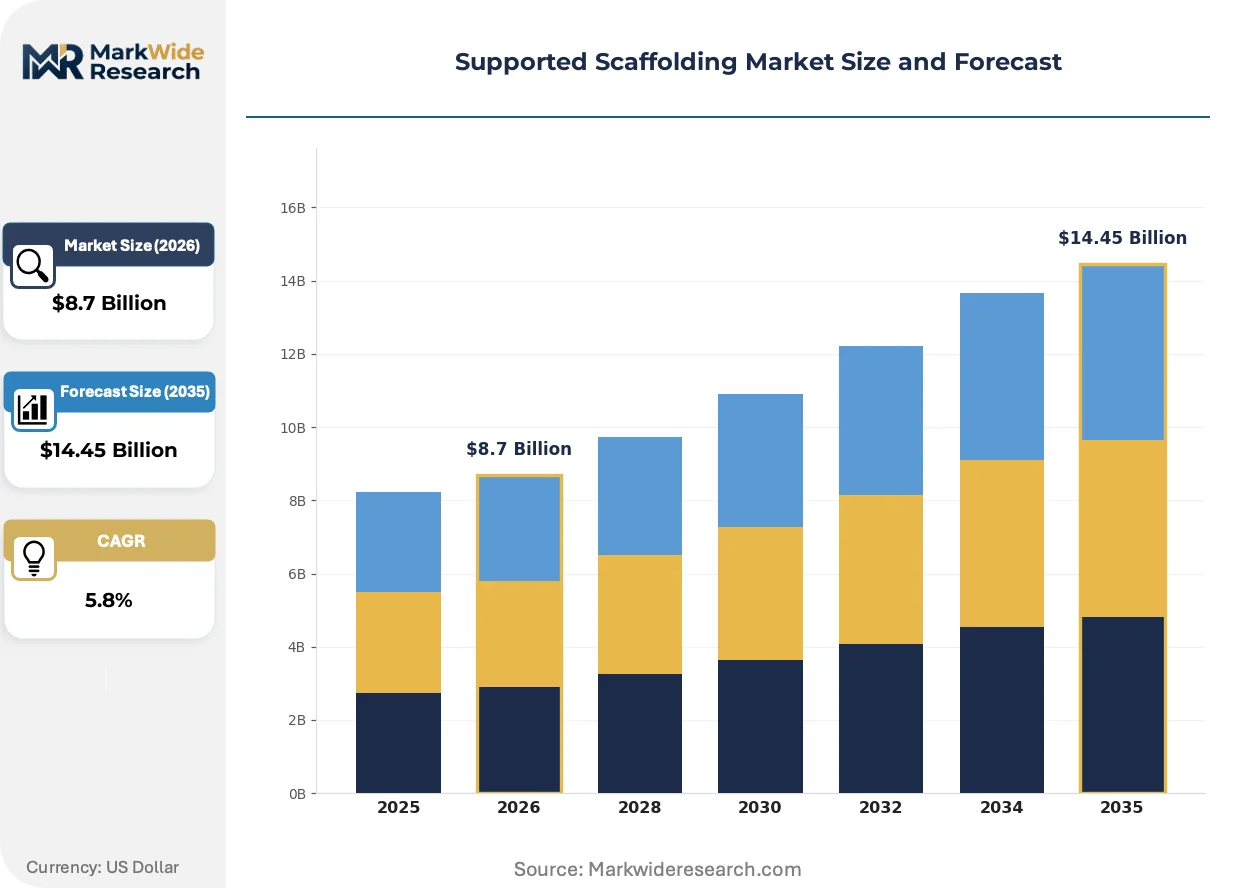
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame, Modular, System, Rolling End User: Construction, Manufacturing, Power Generation, Events Material: Steel, Aluminum, Wood, Composite Design Type: Adjustable, Fixed, Custom, Mobile |
| Companies Covered | Wellmade Scaffold Co. Ltd., Rapid Scaffolding (Engineering) Co. Ltd., Waco Kwikform Ltd., Turbo Scaffolding, SB Scaffolding India Pvt. Ltd., BrandSafway, PERI GmbH, ULMA Construction, ADTO Industrial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supported Scaffolding Market Evolving Landscape
Digital inspection platforms and predictive maintenance algorithms are compressing traditional asset management cycles, while material science advances unlock weight-performance tradeoffs previously unavailable to height-access engineering.
Modular aluminum ringlock systems are rewriting erection economics for power generation maintenance. Utilities in Germany and Texas adopt these configurations for turbine overhaul windows where assembly speed determines outage cost. The technology is rewriting contractor procurement criteria, compressing steel frame preference in favor of corrosion-resistant rapid-deployment alternatives.
REACH chemical restriction expansions are tightening coating formulation standards for galvanized components. European manufacturers face reformulation costs for zinc-aluminum-magnesium surface treatments. The regulation most affects exporters to EU member states, who are accelerating in-house plating capacity to retain market access.
Rental-first procurement is displacing capital purchase in North American commercial construction. General contractors in California and New York now specify equipment availability over ownership, channeling volume toward vertically integrated providers with captive engineering services. This pattern concentrates most visibly in healthcare and data center verticals where project continuity premiums override first-cost considerations.
Supported Scaffolding Market Segmentation
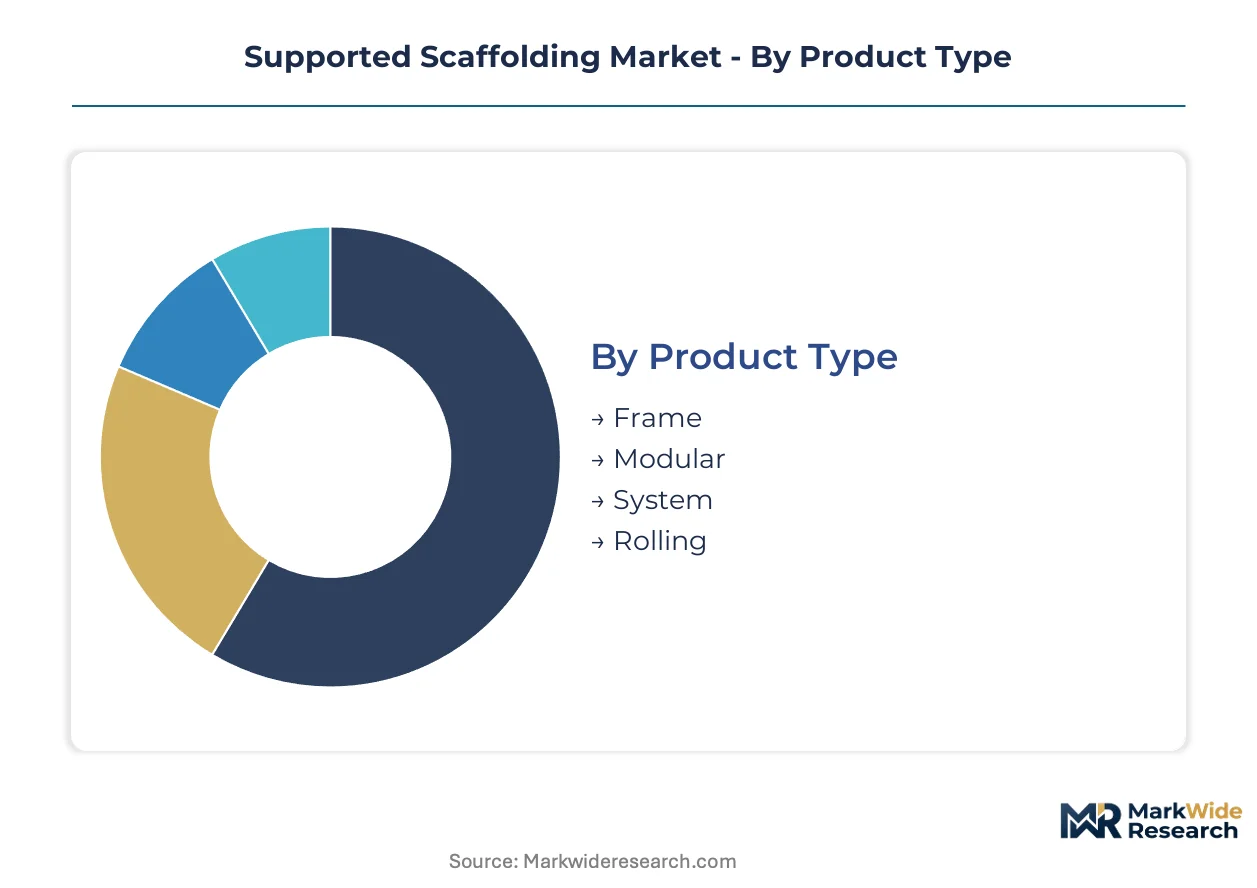
Segmentation in supported scaffolding reveals how procurement priorities diverge across project economics, regulatory exposure, and site-specific engineering constraints. Buyers weight material durability against assembly speed, while rental providers optimize fleet composition around utilization rates and cross-border certification portability.
Product Type:
Contractors select configurations based on erection labor costs versus project duration, with standardized systems dominating recurring commercial work and specialized formats capturing premium turnaround applications.
- Frame:Galvanized steel ladder and walk-through frames with pinned connections dominate North American commercial construction. Demand concentrates in California and Texas healthcare verticals where OSHA documentation requirements favor familiar configurations with established inspection protocols.
- System:Ringlock and cuplock modular systems with rosette node connections enable rapid assembly without loose fittings. German utilities and Texas power generators specify these for turbine maintenance windows where outage duration determines contract profitability.
- Modular:Component-based platforms with standardized vertical and horizontal members adapt to irregular facades. Bridge rehabilitation contractors in Pennsylvania and Ohio favor these for variable-height pier access.
- Rolling:Castor-mounted towers with internal stair access serve maintenance crews in warehouse and retail environments. Facility managers in Illinois and Michigan procurement specifications prioritize mobility over load capacity for interior work.
Volume sits with Frame configurations; growth tilts toward System products as power generation maintenance contracts expand.
End User:
End-use concentration determines rental fleet specialization, with industrial turnarounds requiring corrosion-resistant aluminum and commercial construction tolerating heavier steel platforms.
- Construction:General contractors erect temporary access for facade installation, concrete placement, and finishing trades. High-rise developers in Shanghai and Beijing sustain demand for modular frame configurations in dense urban cores.
- Manufacturing:Chemical processors and automotive plants specify spark-resistant aluminum for confined-space maintenance. Louisiana and Texas Gulf Coast refineries drive specification for EN 12811-certified systems with documented load testing.
- Power Generation:Utilities contract specialized erection crews for scheduled turbine and boiler outages. Offshore wind developers in the North Sea and Baltic markets specify marine-grade aluminum to withstand salt corrosion.
- Events:Temporary staging for concerts and sporting venues demands rapid deployment with minimal ground penetration. Event production companies in Nevada and Florida prioritize lightweight aluminum towers with quick-release connections.
Construction commands the largest installed base; Power Generation delivers the steepest expansion trajectory as renewable infrastructure accelerates.
Material:
Material selection trades acquisition cost against lifecycle performance, with corrosion environments and weight restrictions overriding first-cost considerations in specification decisions.
- Steel:Hot-dip galvanized tubular sections with zinc coating weights of 600-900 g/m² provide standard-duty platforms. Commercial contractors in Florida and coastal California face accelerated replacement cycles due to salt-air degradation.
- Aluminum:Extruded 6061-T6 alloy sections with anodized or mill finishes reduce dead load by 50-60% versus steel equivalents. Offshore wind contractors in Germany and Denmark specify these for marine installation vessels where crane capacity limits platform weight.
- Wood:Laminated timber planks and solid sawn boards serve temporary access in heritage restoration where metal spark risk is prohibited. Historic preservation contractors in Massachusetts and Virginia specify pressure-treated southern pine for compatibility with traditional construction methods.
- Composite:Glass-reinforced polymer planks and pultruded sections eliminate corrosion and electrical conductivity. Chemical manufacturers in New Jersey and Delaware specify these for explosive atmosphere zones where OSHA mandates non-sparking surfaces.
Steel retains volume leadership; aluminum captures share fastest as power generation and offshore applications expand.
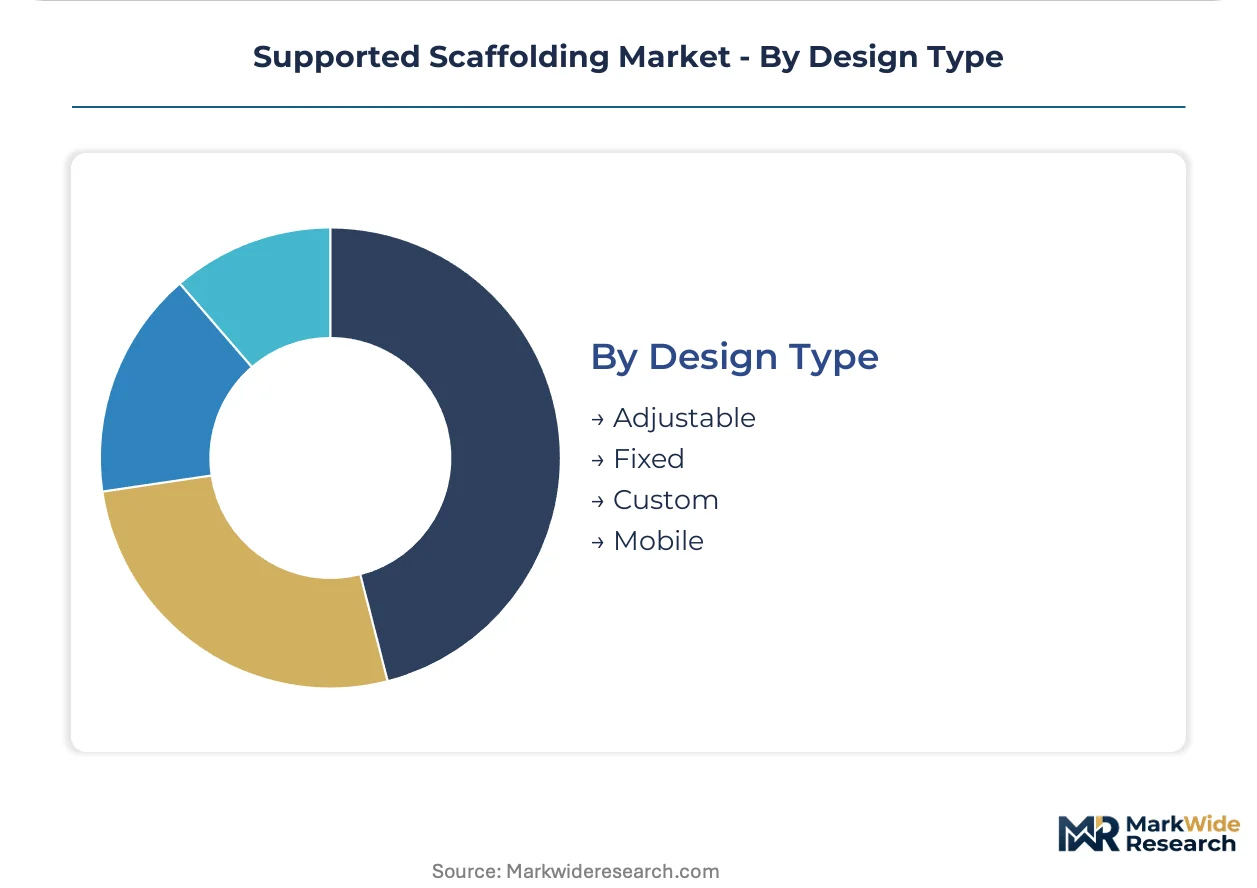
Design Type:
Design flexibility determines reuse economics across project portfolios, with adjustable formats commanding rental premiums and fixed configurations minimizing initial capital outlay.
- Adjustable:Screw-jack bases and telescoping verticals accommodate uneven terrain without supplementary shimming. Foundation contractors in Colorado and Arizona specify these for sloped commercial sites where grade variation exceeds 300mm.
- Fixed:Predetermined frame heights with integral bracing minimize erection decisions for repetitive commercial work. Multi-family developers in Georgia and North Carolina specify standardized bay sizes to accelerate cycle times across portfolio projects.
- Custom:Engineered configurations for irregular structures, curved facades, or confined industrial spaces. Petrochemical turnarounds in Texas and Louisiana require these for vessel access where standard modular systems cannot conform to equipment geometry.
- Mobile:Self-propelled or towable platforms with integrated lifting mechanisms for single-operator positioning. Facility maintenance departments in Ohio and Indiana procurement specifications favor these for interior atrium work where fixed scaffold erection disrupts operations.
Fixed designs dominate fleet utilization; adjustable formats expand most quickly as site conditions become less predictable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China fabricates the majority of standardized steel frames while consumption concentrates in North American refurbishment markets and European power generation corridors. This production-consumption divide shapes logistics costs and certification requirements across trade lanes.
United States
Healthcare verticals in California and Texas sustain demand for OSHA-compliant frame configurations with documented inspection trails. The Department of Labor enforces Subpart L training mandates that channel contractors toward rental providers with captive engineering services. Gulf Coast petrochemical clusters in Louisiana and Texas specify corrosion-resistant aluminum for turnaround maintenance in salt-air environments.
Germany
Utilities in Bavaria and North Rhine-Westphalia contract ringlock systems for turbine overhaul windows where outage duration determines profitability. The EU Green Deal embodied carbon rules favor aluminum recycling credentials in public sector tenders. Offshore wind developers in the North Sea specify marine-grade configurations for installation vessels with strict crane capacity limits.
China
Beijing and Shanghai infrastructure density sustains volume for modular frame systems in high-rise commercial construction. SAMR type-testing protocols filter market access for imported systems, protecting domestic fabricators in Hebei Province. Tier-one mega-projects absorb standardized production despite zinc price volatility compressing export margins.
India
Tier-2 urban clusters in Maharashtra and Gujarat lack established rental infrastructure, creating first-mover terrain for system providers. BIS construction equipment standards impose certification requirements that foreign entrants must navigate through local partnerships. Mumbai and Delhi commercial developers specify rapid-assembly configurations for constrained urban sites.
Australia
Mining maintenance crews in Western Australia specify mobile towers for remote site access where fixed scaffold erection proves impractical. WorkSafe Australia fall-protection mandates align with ISO standards, simplifying certification for European and North American exporters. Perth and Brisbane infrastructure projects absorb aluminum systems for coastal corrosion resistance.
Supported Scaffolding Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the supported scaffolding market, with fabrication-intensive players absorbing zinc price volatility while engineering-led specialists capture service premiums. The structure tilts toward consolidation at the premium tier where rental bundling and inspection capabilities create switching costs. Three archetypes dominate: vertically integrated rental providers with captive engineering, aluminum system specialists, and scale-driven frame fabricators. Competitive moves concentrate on geographic expansion into underpenetrated tier-2 markets and backward integration into coating capacity to manage REACH compliance costs.
Among German-speaking engineering-led providers, PERI GmbH exemplifies the rental-model archetype with long-term contract anchoring across European utilities. BrandSafway occupies a position within the vertically integrated tier, spanning engineered access solutions for complex industrial turnarounds. ULMA Construction represents the aluminum specialization vector, differentiating via weight-reduction credentials in markets where corrosion resistance commands premium positioning.
| Leading Market Players |
|---|
| Wellmade Scaffold Co. Ltd. |
| Rapid Scaffolding (Engineering) Co. Ltd. |
| Waco Kwikform Ltd. |
| Turbo Scaffolding |
| SB Scaffolding India Pvt. Ltd. |
| BrandSafway |
| PERI GmbH |
| ULMA Construction |
| ADTO Industrial Group |
| Others |
Value Network & Pricing Analysis
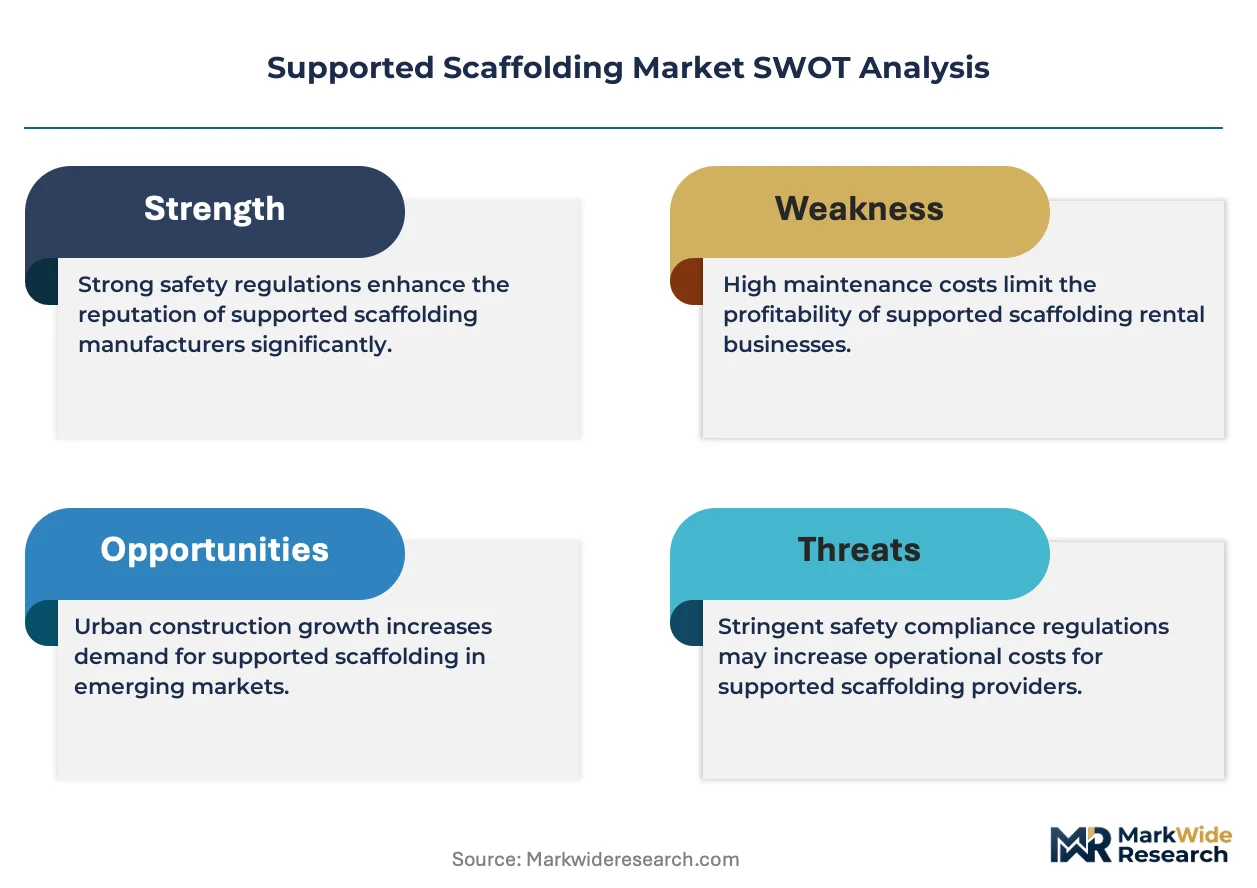
OSHA fall-protection mandates and EN 12811 certification requirements are forcing contractors toward rental providers with captive engineering services, concentrating procurement power among vertically integrated players and compressing margins for standalone fabricators.
Pricing Analysis
Margin tightening in standardized steel frame tiers reflects zinc price volatility and fixed-rate annual contract structures. Three-tier pricing structure across premium, standard, and economy levels separates EN 12811-certified aluminum systems from OSHA-compliant steel configurations and uncertified economy imports. Cost compression accelerates in steel segments because galvanization input costs swing unpredictably. Commercial construction contractors in California and Texas exhibit highest price sensitivity, while power generation utilities in Germany and Texas accept premiums for rapid-assembly aluminum systems.
Supply Chain Analysis
Freight cost escalation from Hebei Province fabrication clusters to North American consumption markets is reshaping fleet deployment economics. Supply concentrates in China for standardized steel frames, Germany for engineered aluminum systems, and India for emerging tier-2 market penetration. Raw material dependencies span zinc for galvanization, 6061-T6 aluminum extrusions, and glass-reinforced polymer resins. Single-region vulnerability in Hebei Province exposes fleet operators to disruption risk. Distribution runs through rental-first providers with regional depot networks rather than direct manufacturer-to-site models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as engineering-led service bundling and captive coating capacity determine who captures long-term contract value.
For Market Incumbents: Hedge against zinc price volatility through backward integration into plating capacity or long-term offtake agreements with Hebei fabricators. Defend market position by accelerating digital inspection platform deployment before drone-integrated protocols become table stakes. Reinforce certification portability across OSHA, EN 12811, and GB standards to reduce redundant testing burdens for transnational fleet operators. For New Entrants and Emerging Players: Begin with India's tier-2 urban clusters in Maharashtra and Gujarat where rental infrastructure remains underdeveloped. White-space opportunity exists in predictive maintenance subscriptions converging with digital twin platforms. Target power generation maintenance contractors seeking corrosion-resistant aluminum alternatives for offshore wind installation vessels. For Investors and Strategic Acquirers: The window for entry favors aluminum system specialists with marine-grade certifications and established utility relationships. Long-term viability hinges on exposure to renewable infrastructure buildout rather than cyclical commercial construction. Watch offshore wind installation tender awards in the North Sea and Baltic markets as inflection indicators for fleet utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Capacity | REACH compliance costs and zinc price volatility favor captive plating operations in European markets. |
| Drone-Integrated Inspection Platform Launch | Automated defect detection enables predictive maintenance subscriptions that decouple ownership from site readiness. |
| Marine-Grade Aluminum Certification Investment | Offshore wind developers in Germany and Denmark specify corrosion-resistant systems for crane-limited installation vessels. |
| Geographic Expansion into Tier-2 Indian Markets | Maharashtra and Gujarat smart city pipelines lack established rental infrastructure, creating first-mover terrain. |
| Multi-Standard Certification Harmonization | Redundant testing budgets across OSHA, EN 12811, and GB standards compress margins for transnational portfolios. |
Research Methodology
Independent corroboration across rental fleet operators, scaffolding erection contractors, and utility procurement officers underwrites the qualitative findings. Primary fieldwork engaged maintenance directors at Gulf Coast petrochemical facilities, plant engineers in German power generation corridors, and OEM procurement teams at European aluminum system manufacturers. Secondary validation drew from OSHA enforcement records, EU construction equipment customs data, and SAMR type-testing registries. Bottom-up fleet utilization modeling triangulates against top-down infrastructure spending projections.
Rate-of-change decomposition segments volume trajectories across material type, end-use vertical, and regional regulatory cluster throughout the forecast period. The analytical framework models frame, system, modular, and rolling product configurations alongside steel, aluminum, wood, and composite material splits. CAGRs derive from weighted average of historical fleet replacement cycles and projected infrastructure refurbishment intensity. Forecast inputs incorporate zinc price correlation coefficients and offshore wind installation vessel deployment schedules.
Underlying measurement precision varies by segment; standardized steel frame configurations carry tighter precision than custom engineered solutions due to homogeneous product definitions. Forecasts reflect assumptions about regulatory enforcement continuity and raw material price regimes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Steel Beam Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Global Rebar Splice Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
South Korea Construction Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
H Beam Market
Structural Construction
Bridge Construction Market
Structural Construction
Girder Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Global Concrete Contractor Market