
 Satellite Communication (SATCOM) Market | 2026-2036
Satellite Communication (SATCOM) Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication (SATCOM) Market Analysis
Asset-light leasing models for satellite capacity are reshaping competitive entry barriers for new operators. Starlink leverages its vertically integrated launch-to-terminal stack to control end-to-end service delivery. Intelsat anchors geostationary revenue through long-term media and government contracts. Viasat Inc. differentiates via high-throughput Ka-band architectures for aviation and maritime mobility.
Satellite Communication encompasses the transmission, relay, and reception of data via artificial orbital platforms operating across microwave frequency allocations from L-band through Ka-band, typically at altitudes ranging from low-Earth orbit to geostationary positions. These systems enable ubiquitous connectivity for remote sensing, navigation augmentation, broadband distribution, and mission-critical command networks where terrestrial infrastructure proves unavailable or vulnerable. Fixed Satellite Services dominates current revenue generation through stable broadcast and enterprise backhaul contracts, while Mobile Satellite Services captures expanding margin pools from connected vehicle and maritime IoT applications. Defense and Aviation applications within the Application segment are experiencing the fastest structural growth as NATO allies and commercial carriers modernize resilient beyond-line-of-sight communications.
The FCC governs spectrum allocation and orbital slot coordination within the United States, directly shaping operator licensing timelines and capital deployment schedules. EASA and national aviation regulators including the FAA mandate SATCOM redundancy standards for transoceanic flight corridors, embedding satellite links into mandatory safety architecture. Stakeholders must monitor evolving debris mitigation rules from the FCC and emerging ITU spectrum harmonization frameworks to anticipate orbital access constraints and frequency priority disputes.
Market Dynamics
Low-Earth orbit constellation density is compressing launch cost curves and forcing geostationary operators to defend contract renewals through hybrid service bundles rather than standalone capacity leases.
Growth Catalysts
- Space Force infrastructure procurement:United States military spending on tactical battlefield networks is pulling dedicated MILSATCOM capacity into multi-year service agreements.
- FCC Ka-band auction rules:Updated spectrum licensing frameworks are accelerating operator capital deployment timelines and reducing regulatory uncertainty for next-generation deployments.
- Aviation safety mandates:EASA and FAA redundancy requirements for transoceanic corridors are embedding SATCOM into mandatory flight architecture.
Market Restraints
- Launch capacity concentration:Heavy reliance on a narrow supplier base for ride-share and dedicated orbital insertion creates scheduling bottlenecks.
- Spectrum coordination friction:ITU filing backlogs and priority disputes between LEO and GEO operators delay service activation.
- Debris mitigation compliance:FCC disposal requirements and post-mission deorbiting standards extend satellite design cycles and raise insurance premiums.
Strategic Opportunities
- Maritime IoT underpenetration:Container fleet tracking and engine monitoring applications remain underserved by current Ku-band offerings.
- Optical inter-satellite links:Laser-based cross-connects between orbital planes are reducing ground station dependency for polar coverage.
- India's IN-SPACe framework:Private sector participation rules are opening domestic launch and ground segment opportunities for foreign operators.
Industry Challenges
- RF engineering talent scarcity:Microwave systems design and phased array antenna expertise pools are thinning as commercial demand outpaces university pipeline output.
- Legacy gateway integration:GEO hub equipment refresh cycles conflict with LEO terminal form factor requirements, forcing dual-track maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication (SATCOM) Market |
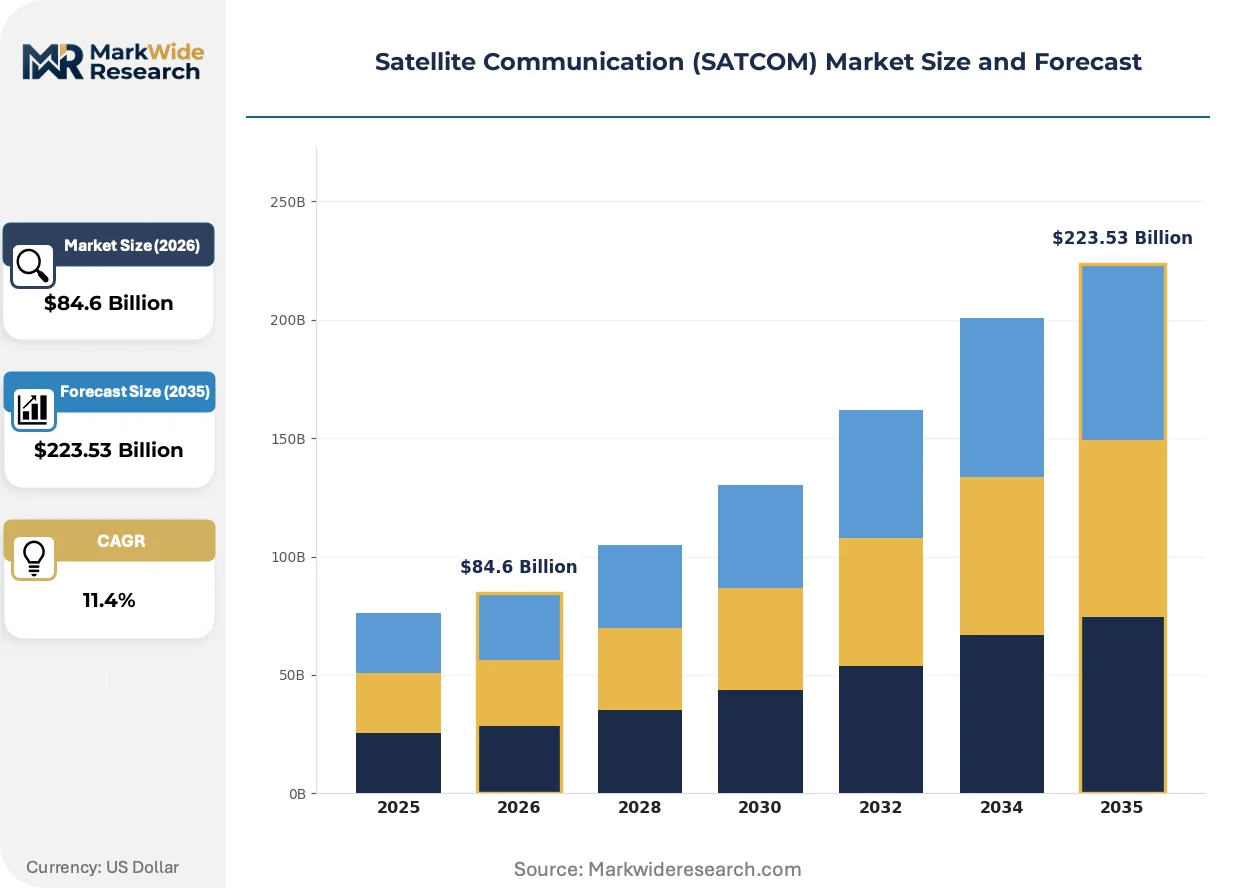
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $223.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed Satellite Services, Mobile Satellite Services, Broadcasting Satellite Services, Interactive Satellite Services Technology: C Band, Ku Band, Ka Band, L Band Application: Defense, Maritime, Aviation, Disaster Management Customer Type: Government, Enterprise, Residential, Media |
| Companies Covered | Starlink, Gilat Satellite Networks, Intelsat, Astranis, AST SpaceMobile, Viasat Inc., Globalstar Inc., SKY Perfect JSAT, Telesat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication (SATCOM) Market Emerging Trajectories
Orbital architecture is fragmenting across altitude bands and frequency allocations, with operators blending legacy geostationary assets with proliferated low-Earth systems to preserve service continuity.
Multi-orbit ground terminals is hybridizing reception paths by combining parabolic dishes with electronically steered flat panels. Maritime integrators and business aviation retrofitters are adopting these hybrid systems to maintain connectivity across oceanic and polar routes. The technology is compressing the addressable market for single-band hardware while expanding total available service hours per vessel.
REACH chemical restrictions and EU Green Deal procurement criteria are mandating sustainable satellite manufacturing and deorbiting protocols. European operators must now document supply chain carbon intensity and end-of-life disposal plans to qualify for institutional contracts. Defense and public safety segments across Germany, France, and Italy are prioritizing vendors with verified sustainability credentials.
Service unbundling is separating bandwidth provision from terminal hardware, with airlines and shipping lines opting for bring-your-own-device models. Traditional integrated service providers are losing terminal margin capture to third-party electronics distributors. This pattern is most pronounced in North American and Middle Eastern aviation retrofit programs.
Satellite Communication (SATCOM) Market Segmentation
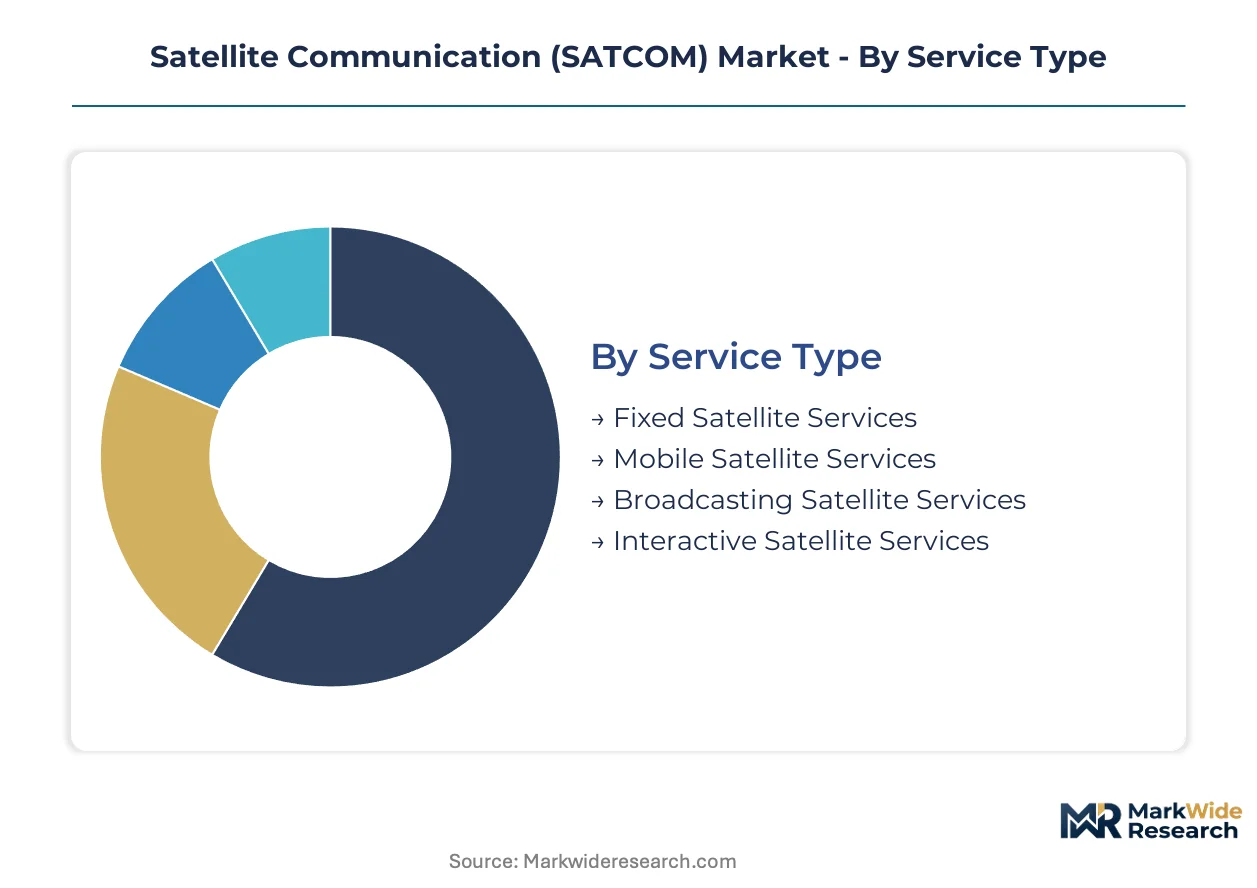
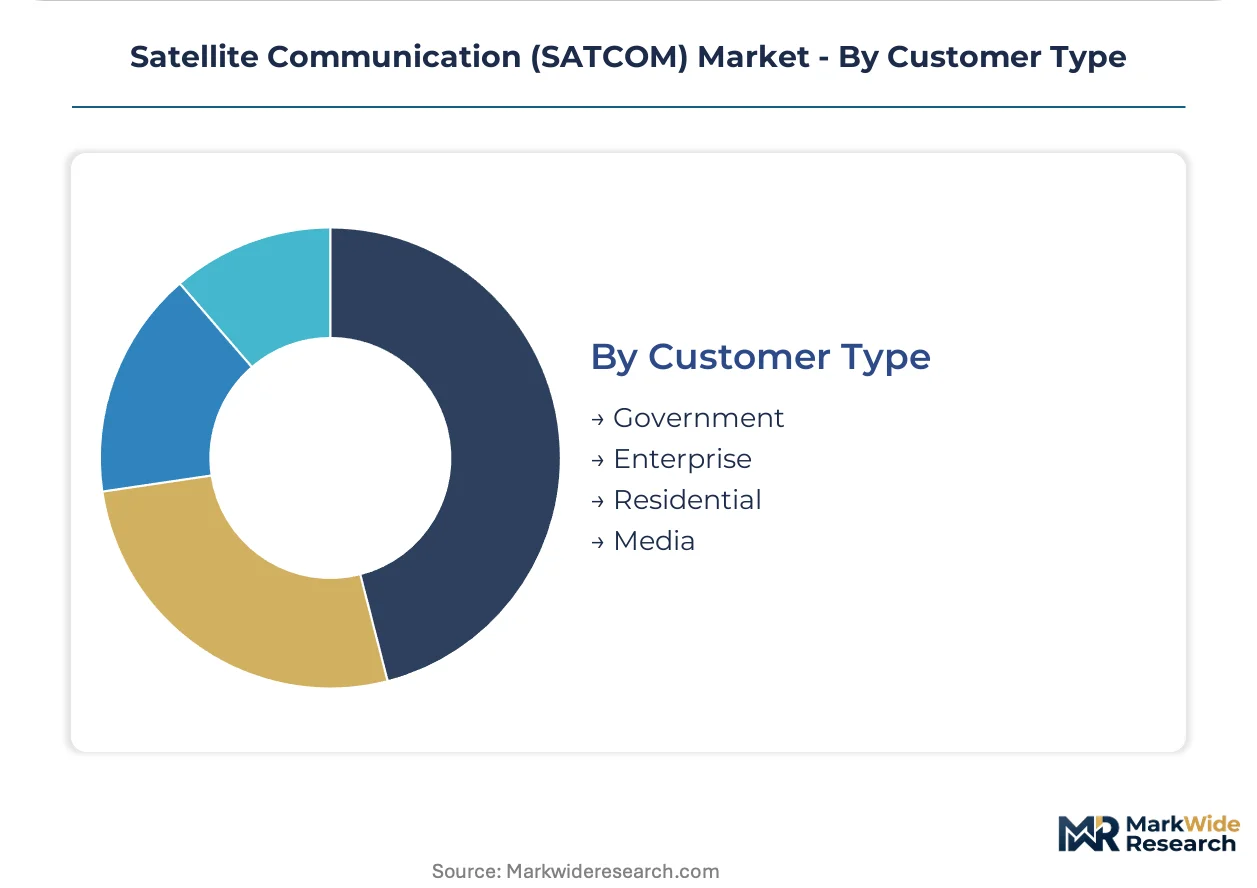
SATCOM market segmentation reveals distinct service architectures, frequency deployments, and customer procurement patterns that shape operator investment priorities. Each dimension carries unique margin profiles, technical barriers, and regulatory exposure that determine competitive positioning across orbital service tiers.
Service Type:
After-sales service intensity varies sharply across service models, with long-term managed network contracts demanding dedicated orbital support teams while broadcast services require minimal ongoing technical intervention.
- Fixed Satellite Services:Geostationary capacity leases for broadcast backhaul and enterprise trunking dominate current revenue streams. United States government contracts through Space Force infrastructure programs anchor demand for dedicated transponder agreements with guaranteed availability clauses.
- Mobile Satellite Services:Narrowband and broadband connectivity for moving platforms including vessels, aircraft, and ground vehicles. NATO battlefield network modernization and commercial aviation retrofit programs in the United States are pulling capacity into multi-year service agreements with stringent latency requirements.
- Broadcasting Satellite Services:Direct-to-home television distribution and radio relay across continental footprints.
- Interactive Satellite Services:Two-way data exchange for consumer broadband and enterprise VPN applications.
Fixed Satellite Services holds the largest share; momentum sits with Mobile Satellite Services.
Technology:
Frequency band selection determines terminal cost structures, regulatory licensing timelines, and atmospheric resilience characteristics across deployment scenarios.
- Ka Band:High-throughput spot beam architectures enabling 100+ Mbps consumer broadband and mobility applications. FCC spectrum auction rules for these frequencies are accelerating operator capital deployment timelines in the United States while reducing regulatory uncertainty.
- Ku Band:Established frequency allocation for maritime and enterprise VSAT networks with proven rain fade mitigation. European maritime integrators favor this band for container fleet installations due to mature terminal ecosystems and lower insurance premiums.
- C Band:Legacy broadcast distribution with superior rain penetration but limited spectrum availability.
- L Band:Narrowband IoT and safety-of-life communications including distress signaling and asset tracking.
Ku Band maintains the largest installed base; Ka Band is expanding most quickly.
Application:
End-use verticals impose divergent certification requirements, with defense and aviation segments demanding hardened security architectures and redundant failover protocols.
- Defense:Military-grade encrypted communications for tactical battlefield networks and strategic command infrastructure. NATO member states are expanding procurement for beyond-line-of-sight connectivity with anti-jamming and low-probability-of-intercept capabilities.
- Aviation:In-flight connectivity and cockpit safety communications for commercial and business aircraft. EASA and FAA mandates for transoceanic corridor redundancy are embedding SATCOM into mandatory flight architecture across European and United States airspace.
- Maritime:Fleet management, crew welfare, and engine monitoring for commercial shipping.
- Disaster Management:Emergency response coordination and temporary infrastructure restoration.
Defense commands the highest revenue per terminal; aviation offers the steepest expansion trajectory.
Customer Type:
Procurement authority and contract duration differ substantially across buyer categories, with government segments favoring decade-long service agreements and residential customers accepting standard terms.
- Government:Federal agencies and defense departments requiring dedicated MILSATCOM capacity with sovereign control provisions. United States Space Force infrastructure spending is creating dense procurement clusters with multi-year budget visibility.
- Enterprise:Mining, energy, and financial institutions operating in connectivity-deprived regions. Remote site backhaul demand from Permian Basin oil operations and Australian mining corridors drives VSAT terminal deployments.
- Residential:Consumer broadband subscribers in rural and underserved areas.
- Media:Broadcasters and content distributors requiring occasional-use and full-time satellite newsgathering capacity.
Government holds the largest contract value; enterprise is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum auctions and Space Force procurement are concentrating capital deployment in the United States. India's IN-SPACe reforms and European sustainability mandates are creating divergent regulatory environments for orbital service providers.
United States
Space Force infrastructure spending and commercial LEO constellation deployments anchor demand for tactical battlefield networks and broadband distribution. FCC Ka-band auction rules are compressing licensing timelines and reducing regulatory uncertainty for next-generation operators. The California-Colorado orbital services cluster hosts dense concentrations of launch integration facilities and ground segment engineering centers.
India
IN-SPACe framework liberalization is opening domestic launch and ground segment opportunities for foreign operators seeking market entry. The national space regulator is streamlining private sector participation rules for satellite manufacturing and earth station licensing. Bengaluru and Ahmedabad host emerging clusters of spacecraft component fabricators and antenna systems integrators.
Germany
Defense procurement for NATO secure communications is pulling dedicated MILSATCOM capacity into multi-year service agreements with anti-jamming requirements. EU Green Deal procurement criteria mandate documented supply chain carbon intensity for institutional satellite contracts. Munich and Bremen concentrate spacecraft bus manufacturing and optical inter-satellite link development facilities.
Japan
Maritime IoT demand from container fleet operators is expanding Ku-band terminal deployments across Pacific shipping corridors. METI spectrum coordination frameworks are harmonizing Ka-band allocations for high-throughput mobility applications. Tokyo and Nagoya host concentrated ground systems engineering and phased array antenna manufacturing operations.
United Arab Emirates
Government-led space initiatives and sovereign wealth deployment are accelerating domestic satellite manufacturing and launch service capabilities. National telecommunications regulators are licensing foreign operators for regional gateway establishment and earth station coordination. Dubai and Abu Dhabi host emerging clusters of satellite operations centers and ground segment integration facilities.
Satellite Communication (SATCOM) Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated launch-to-service stacks and specialized component tier suppliers. Three strategic archetypes dominate: constellation operators controlling end-to-end orbital infrastructure, geostationary incumbents defending long-term media and government contracts, and ground systems specialists supplying terminal hardware and network management platforms. Dominant competitive moves include spectrum portfolio accumulation through FCC auctions and strategic partnerships between LEO operators and maritime aviation integrators.
Within the vertically integrated constellation tier, Starlink exemplifies the launch-captive service model through its Falcon-integrated deployment architecture. Among geostationary incumbents, Intelsat and Viasat Inc. occupy positions anchored by long-term transponder agreements and high-throughput Ka-band mobility specialization. These three entities represent contrasting strategic postures: proprietary orbital infrastructure ownership, legacy contract renewal defense, and frequency-architecture differentiation.
| Leading Market Players |
|---|
| Starlink |
| Gilat Satellite Networks |
| Intelsat |
| Astranis |
| AST SpaceMobile |
| Viasat Inc. |
| Globalstar Inc. |
| SKY Perfect JSAT |
| Telesat |
| Others |
Supply Flow & Price Mechanics
Launch vehicle manufacturing concentrates in the United States and China, anchoring upstream margin capture for ride-share and dedicated orbital insertion services while downstream satellite operators absorb capacity premiums through long-term service agreements.
Pricing Analysis
Service bundling creates the primary spread between asset-heavy and asset-light operators. Three-tier pricing structure across premium, standard, and economy levels segments government MILSATCOM contracts, enterprise managed networks, and consumer broadband subscriptions. Pricing pressure stems from LEO constellation overcapacity in consumer broadband as Starlink and emerging operators compress retail rates. Government buyers exhibit lowest price sensitivity due to sovereign control requirements, while maritime shipping lines negotiate aggressively on terminal hardware costs.
Supply Chain Analysis
Export control regimes under ITAR and EAR restrictions limit flows of phased array antenna technology and encryption modules to foreign integrators. Satellite bus manufacturing concentrates in the United States, France, and Japan; payload fabrication draws from specialized foundries in Germany and South Korea. Supply chain risk centers on single-source vulnerability for radiation-hardened semiconductors. Distribution runs through prime contractors for defense segments and direct-to-operator channels for commercial maritime and aviation retrofitters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against terrestrial fiber and 5G backhaul expansion, which threatens fixed satellite service margins in enterprise trunking applications.
For Market Incumbents: Build regulatory moats through spectrum portfolio accumulation at FCC auctions and ITU filings. Incumbents should anchor long-term media and government contracts with guaranteed availability clauses while refreshing GEO hub equipment to support hybrid LEO-GEO terminal architectures. Capacity addition in the United States through Space Force infrastructure programs offers budget visibility against terrestrial substitution threats. For New Entrants and Emerging Players: Establish a beachhead in maritime IoT container fleet tracking, where current Ku-band offerings remain underpenetrated for engine monitoring applications. New entrants should target India's IN-SPACe framework liberalization for domestic ground segment partnerships, leveraging streamlined private sector participation rules to bypass entrenched orbital slot holdings. Go-to-market positioning as bring-your-own-device bandwidth providers to airlines captures unbundling momentum from integrated service providers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ground systems specialists holding phased array antenna manufacturing capabilities. Long-term viability favors operators with multi-orbit architectures spanning geostationary and low-Earth assets. The signal to watch is FCC debris mitigation rule enforcement, which would accelerate insurance cost burdens for legacy satellite operators and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Portfolio Accumulation | FCC Ka-band auction participation secures priority licensing timelines for next-generation deployments. |
| Multi-Orbit Terminal Integration | Hybrid parabolic and flat-panel systems expand addressable service hours for maritime and aviation routes. |
| Optical Inter-Satellite Link Deployment | Laser cross-connects reduce ground station dependency for polar coverage and defense applications. |
| Sustainability Certification Investment | EU Green Deal compliance unlocks institutional procurement from German and French defense segments. |
| Maritime IoT Platform Partnership | Container fleet engine monitoring integrations capture underserved margin pools beyond basic connectivity. |
Methodological Framework
The analysis maps fixed satellite services, mobile satellite services, and broadcasting satellite services, each validated through constellation operators, ground systems integrators, defense procurement officers, and maritime fleet managers. Primary interviews with satellite bus manufacturers, phased array antenna engineers, and aviation retrofit program directors combined with secondary validation from FCC licensing databases, ITU filing records, SEC 10-K disclosures, and EASA regulatory bulletins. Bottom-up capacity deployment tracking and top-down service revenue estimates underwent triangulation against orbital launch manifests and transponder lease announcements.
Assumptions held fixed include current ITU spectrum coordination timelines, FCC debris mitigation compliance schedules, and NATO defense procurement budget trajectories; varied assumptions included LEO constellation deployment rates and terrestrial 5G backhaul expansion pace. Segmentation dimensions modeled span service type, frequency band, application vertical, and customer procurement authority across the analysis window. CAGRs derived from orbital capacity supply curves and pricing elasticity estimates for government, enterprise, and residential buyer segments. Forecast inputs incorporated Space Force infrastructure spending commitments and EASA aviation safety mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocations, launch cost inflation, or spectrum auction participation rates would shift the trajectory. Forecasts reflect these documented assumptions without claiming predictive certainty. Material shifts in ITU priority dispute resolution frameworks or FCC orbital slot licensing reforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Satellite Communication System Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Satellite Sensor Market
Satellite
United States Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
North America Satellite IoT Market
Satellite
Communication Satellite Launch Services Market
Satellite
Canada Satellite Connectivity Market
Satellite
Satellite Amplifier Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Advanced Satellite Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Global Dish Antennas Market