
 Satellite Sensor Market | 2026-2036
Satellite Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Sensor Market Analytics
Radiometric resolution upgrades is reorganizing competitive dynamics in satellite sensing. Honeywell International Inc. leverages its heritage in spacecraft avionics to anchor high-reliability optical payload contracts. Teledyne Technologies Incorporated differentiates through deep vertical integration in focal plane arrays and infrared detector manufacturing. Airbus competes on dual-use civil-military platforms, sustaining market position across European institutional programs.
Satellite sensors are electro-optical or radio-frequency instruments engineered to detect, measure, and transmit electromagnetic radiation data from orbital altitudes, typically operating across spectral bands from ultraviolet through thermal infrared with spatial resolutions reaching sub-meter precision for Earth observation missions. Their primary commercial and industrial purpose centers on generating actionable geospatial intelligence for weather prediction, resource monitoring, and national security applications. Optical Sensors and Radar Sensors represent the dominant technology categories, with radar payloads capturing disproportionate investment due to all-weather imaging requirements and defense prioritization of synthetic aperture radar constellations. Defense Surveillance leads application segmentation, while Weather Monitoring and Environmental Assessment segments attract sustained government funding through climate monitoring mandates.
Regulatory oversight from the FCC governs U.S. orbital licensing and spectrum allocation, while ESA debris mitigation standards shape European payload durability requirements, and ISO 24113 establishes baseline space sustainability protocols that constrain sensor mass and power budgets. These frameworks collectively elevate barriers for new entrants lacking heritage compliance documentation and certified space-grade manufacturing processes. Stakeholders must monitor evolving export control classifications under ITAR and emerging EU space traffic management rules that could fragment procurement standards across Atlantic supplier bases.
Market Dynamics
Defense procurement concentration around synthetic aperture radar payloads is compressing supplier margins while elevating technical barriers for optical sensor specialists lacking all-weather imaging heritage. NATO member state budgets are tilting procurement toward dual-use platforms that satisfy both civilian climate mandates and classified intelligence requirements.
Growth Catalysts
- Space Force classified programs:United States intelligence community procurement anchors demand for high-reliability electro-optical payloads with sub-meter resolution capabilities.
- ESA debris mitigation standards:European payload durability requirements are extending operational lifespans and creating aftermarket sensor upgrade cycles.
- Synthetic aperture radar constellations:All-weather imaging requirements from defense surveillance agencies are displacing traditional optical-only procurement patterns.
Market Restraints
- Indium gallium arsenide focal plane costs:Short-wave infrared detector material prices constrain mid-tier supplier participation in high-resolution thermal imaging segments.
- ITAR export classification friction:United States munitions list restrictions fragment supplier bases and extend procurement timelines for non-US NATO partners.
- Launch capacity bottlenecks:Concentrated heavy-lift provider schedules delay constellation deployment and compress revenue recognition windows.
Strategic Opportunities
- India ISRO commercialization:Polar satellite launch vehicle cost advantages and emerging private space participation create payload integration openings for foreign sensor suppliers.
- Hyperspectral-agriculture convergence:Precision crop monitoring applications in Brazilian soy and Australian wheat belts expand addressable market beyond defense and weather verticals.
- EU space traffic management rules:Emerging collision avoidance mandates for low-Earth orbit constellations create demand for onboard autonomous navigation sensors.
Industry Challenges
- Space-grade electronics talent scarcity:Radiation-hardened component design expertise concentrates among aging workforce cohorts at heritage defense contractors.
- ISO 24113 compliance documentation:Baseline space sustainability certification timelines extend eighteen to twenty-four months for new entrants lacking heritage manufacturing processes.
- Legacy ground station integration:Downlink compatibility requirements with existing military and civilian reception infrastructure constrain waveform and compression innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Sensor Market |
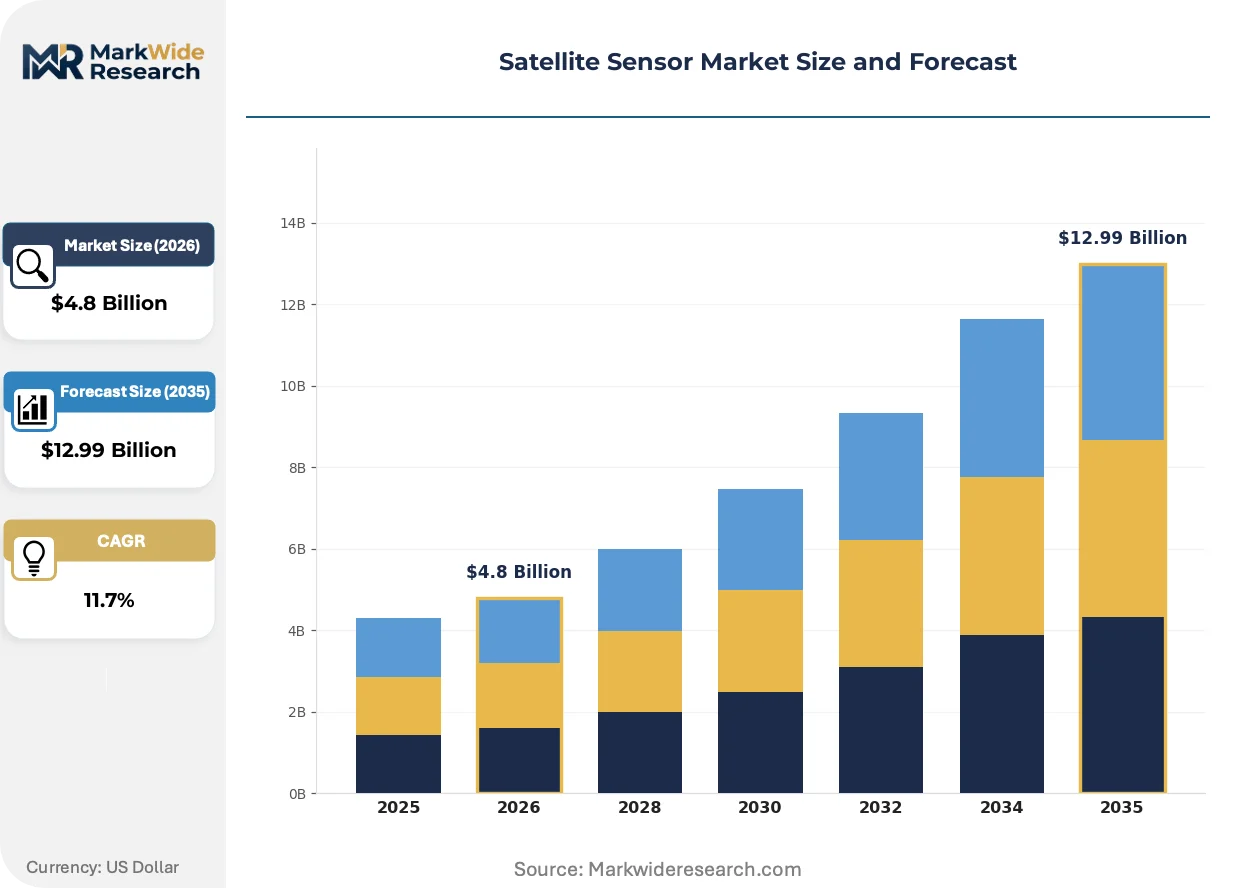
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Weather Monitoring, Environmental Assessment, Disaster Management, Defense Surveillance Technology: Optical Sensors, Radar Sensors, Infrared Sensors, Lidar Sensors End User: Aerospace, Agriculture, Marine, Government Deployment Model: Managed Services, On-Premises, Hybrid, Satellite-as-a-Service |
| Companies Covered | Honeywell International Inc., Teledyne Technologies Incorporated, Airbus, L3Harris Technologies Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, Maxar Technologies, Safran, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Sensor Market Evolving Landscape
Active electronically scanned array architectures are fragmenting traditional synthetic aperture radar supply structures. Three convergent developments are compressing development cycles and redistributing competitive advantage across the value chain.
Digital beamforming is fragmenting conventional analog radar payload architectures. SpaceX Starshield and commercial Earth observation operators are adopting software-defined waveform generation at accelerating procurement velocity. This technology is fragmenting heritage hardware-centric supplier relationships and enabling rapid frequency reconfiguration without physical antenna replacement.
FCC orbital debris mitigation guidelines are mandating post-mission disposal reliability demonstrations for all new licensing applications. United States commercial remote sensing operators must now prove ninety-five percent probability of successful deorbit or graveyard orbit placement. Small satellite constellation developers are responding by integrating propulsion miniaturization and autonomous collision avoidance systems into baseline sensor platform designs.
Defense procurement officers are unbundling sensor manufacturing from full satellite integration contracts. United States Space Development Agency and allied European defense ministries are awarding standalone payload development agreements to specialized electro-optical houses. This pattern is most visible in United Kingdom and German sovereign Earth observation programs, where national industrial policy mandates domestic sensor fabrication while permitting foreign platform integration.
Satellite Sensor Market Segmentation
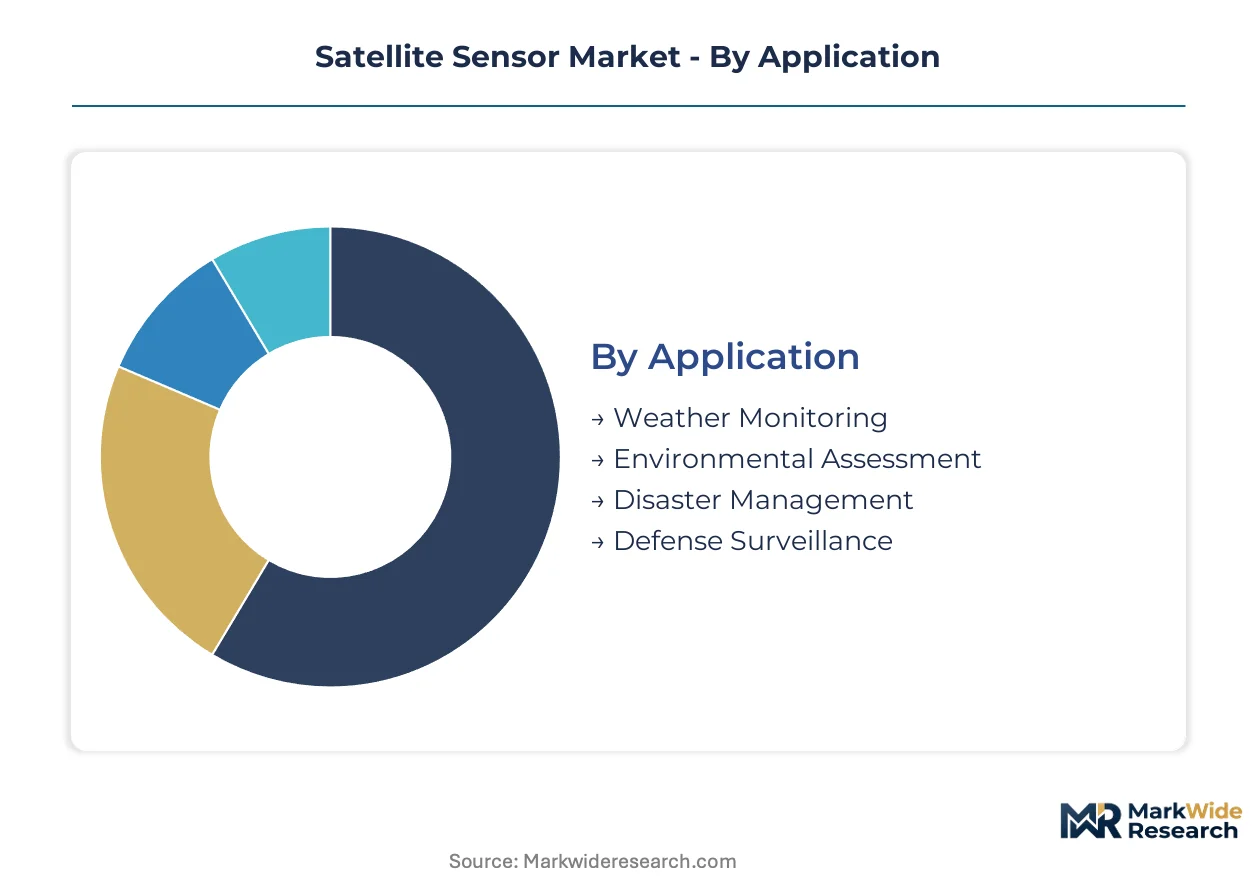
Satellite sensor procurement patterns diverge sharply across mission profiles, with defense agencies prioritizing all-weather radar capabilities while civilian programs optimize for spectral resolution. Regulatory frameworks from the FCC, ESA, and ISO 24113 impose distinct compliance burdens that reshape segment economics and supplier qualification pathways.
Application:
FCC orbital debris mitigation rules and ESA durability standards create divergent compliance costs across mission types, tilting procurement toward platforms with demonstrated end-of-life reliability.
- Defense Surveillance:Synthetic aperture radar payloads dominate classified intelligence programs, with NATO member states mandating sub-meter resolution and all-weather imaging. United States Space Force contracts anchor procurement volume, though ITAR restrictions fragment supplier access for allied partners.
- Weather Monitoring:Geostationary and polar-orbiting meteorological satellites require radiometric stability across thermal infrared bands. EUMETSAT and NOAA procurement sustain long-term demand, with climate monitoring mandates extending operational lifespan requirements.
- Environmental Assessment:Hyperspectral imaging for deforestation and ocean health monitoring attracts sustained government funding.
- Disaster Management:Rapid-revisit constellations for flood and wildfire response prioritize data latency over absolute resolution.
Defense Surveillance handles the majority of throughput; Environmental Assessment is gaining share fastest on climate mandate expansion.
Technology:
Cost tiers separate heritage defense contractors from commercial entrants, with focal plane array manufacturing scale determining competitive viability.
- Radar Sensors:Active electronically scanned array architectures displace analog hardware through software-defined waveform generation. Digital beamforming enables rapid frequency reconfiguration without physical antenna replacement, compressing development cycles for synthetic aperture radar constellations.
- Optical Sensors:Electro-optical payloads with sub-meter resolution serve dual-use civil-military platforms. Radiation-hardened focal plane integration concentrates among heritage suppliers with certified space-grade manufacturing processes.
- Infrared Sensors:Short-wave and thermal bands support night imaging and temperature differential detection.
- Lidar Sensors:Topographic mapping and atmospheric profiling applications drive specialized procurement.
Radar Sensors command the dominant revenue position; Lidar Sensors show the steepest expansion trajectory on autonomous navigation demand.
End User:
Customer type determines procurement velocity, with government programs extending development timelines while commercial agriculture accelerates sensor refresh cycles.
- Government:Classified intelligence programs and sovereign Earth observation initiatives mandate domestic sensor fabrication under national industrial policy. United Kingdom and German programs permit foreign platform integration while requiring indigenous payload development.
- Agriculture:Precision crop monitoring in Brazilian soy and Australian wheat belts expands addressable market beyond traditional defense and weather verticals. Hyperspectral imaging enables nitrogen stress detection and yield prediction at field scale.
- Aerospace:Satellite manufacturers integrate sensors into full spacecraft systems or procure standalone payloads.
- Marine:Ocean color monitoring and vessel tracking applications sustain specialized demand.
Government end users dominate absolute procurement value; Agriculture is climbing fastest on commercial remote sensing platform proliferation.
Deployment Model:
Supply concentration among heavy-lift launch providers shapes deployment economics, with constellation scale determining optimal service architecture.
- Satellite-as-a-Service:Operators provision data products without customer payload ownership, lowering capital barriers for agriculture and environmental monitoring users. SpaceX Starshield and commercial Earth observation ventures accelerate this model through standardized sensor configurations.
- Managed Services:Full mission operations including ground segment and data processing appeal to government agencies lacking in-house space expertise.
- On-Premises:Dedicated satellite ownership persists in classified defense programs requiring air-gapped data chains.
- Hybrid:Mixed ownership structures balance sovereignty requirements with cost efficiency.
Satellite-as-a-Service captures expanding commercial volume; Managed Services retain anchor position in institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentration in the United States drives the majority of sensor development investment, with FCC orbital licensing requirements and Space Force classified programs establishing technical benchmarks that ripple through allied supply chains.
United States
Space Force contracts and intelligence community programs anchor demand for sub-meter resolution electro-optical payloads. FCC debris mitigation guidelines mandate ninety-five percent deorbit reliability for new licensing applications. Los Angeles and Denver aerospace clusters concentrate payload integration facilities serving classified programs.
Germany
Sovereign Earth observation initiatives under national industrial policy mandate domestic sensor fabrication for government programs. ESA debris mitigation standards shape payload durability requirements across European procurement. Munich and Bremen host specialized electro-optical houses developing dual-use civil-military platforms.
United Kingdom
Defense procurement officers award standalone payload development agreements to specialized manufacturers under unbundled contracting trends. National security classifications restrict foreign supplier access for certain programs. Harwell Space Cluster and Glasgow satellite manufacturing facilities concentrate sensor integration expertise.
France
Dual-use platform development sustains market position across European institutional programs under ESA and national space agency coordination. REACH and RoHS compliance requirements constrain material selection for space-grade electronics. Toulouse aerospace hub anchors radar payload development for defense surveillance applications.
India
ISRO commercialization and Polar Satellite Launch Vehicle cost advantages create payload integration openings for foreign sensor suppliers. BIS certification requirements and DGFT export procedures govern component import for space programs. Bengaluru and Hyderabad space technology clusters expand private participation in sensor platform development.
Satellite Sensor Market Competitive Landscape
Concentration sits with heritage defense contractors possessing certified space-grade manufacturing processes and ITAR compliance documentation. The supplier base stratifies across three tiers: prime integrators with full satellite capabilities, specialized electro-optical houses focused on payload development, and component manufacturers supplying focal plane arrays and radiation-hardened electronics. Strategic moves center on unbundling sensor manufacturing from platform integration and backward integration into focal plane array production.
Within the heritage defense contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify prime integrators with full-spectrum capabilities. L3Harris Technologies Inc. occupies a specialized position among electro-optical houses benefiting from standalone payload contracting trends. Airbus represents the European dual-use platform anchor competing across institutional programs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| Airbus |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Maxar Technologies |
| Safran |
| Moog Inc. |
| Others |
Value Network & Pricing Analysis
ITAR export classification documentation gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where heritage contractors command premiums for certified space-grade manufacturing while commercial entrants face extended compliance timelines that compress their pricing flexibility.
Pricing Analysis
ITAR export controls dictate the pricing tier structure across the satellite sensor market, separating ITAR-compliant heritage suppliers from non-US alternatives. Three-tier pricing stratifies across radiation-hardened premium payloads, dual-use standard platforms, and commercial economy sensors. Price differentiation rests on certification level and volume scale, with Space Force classified programs showing least price sensitivity while commercial agriculture end users drive hardest negotiation. Cost compression in mid-tier optical segments is intensifying because indium gallium arsenide focal plane shortages constrain supplier participation.
Supply Chain Analysis
Lead times for space-grade focal plane arrays now stretch eighteen to twenty-four months, constraining constellation deployment schedules across the value chain. Manufacturing concentrates in the United States, Germany, and France, with radiation-hardened component fabrication anchored in Los Angeles and Denver aerospace clusters. Raw material dependencies center on indium gallium arsenide substrates, germanium infrared optics, and specialized ceramic packaging. Single-source vulnerability runs through qualified focal plane array suppliers. Distribution runs through prime integrators and specialized electro-optical houses serving defense and commercial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation-hardened component design expertise concentrates among aging workforce cohorts at heritage defense contractors, creating a capability bottleneck that will reshape competitive dynamics as experienced engineers retire without sufficient replacement pipelines.
For Market Incumbents: Secure captive supply of indium gallium arsenide focal plane arrays through backward integration or long-term offtake agreements to defend margins against emerging electro-optical houses. Accelerate knowledge transfer programs to mitigate workforce attrition risk in radiation-hardened electronics design. Prioritize certification investment in EU space traffic management compliance to preempt regulatory fragmentation. For New Entrants and Emerging Players: ISO 24113 fast-track certification programs offer the most viable entry pathway for commercial remote sensing suppliers lacking heritage defense relationships. Target precision agriculture applications in Brazilian soy and Australian wheat belts as the most penetrable segment, where data latency requirements are less stringent than defense surveillance. Pursue satellite-as-a-service business models to bypass capital-intensive full spacecraft integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across standalone payload development as unbundled contracting trends separate sensor manufacturing from platform integration. Long-term viability favors specialized electro-optical houses with demonstrated dual-use civil-military platform heritage. Watch for ESA debris mitigation standard revisions as the key signal for aftermarket sensor upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Focal Plane Arrays | Captive supply of indium gallium arsenide substrates mitigates single-source vulnerability and compresses lead times. |
| Dual-Use Platform Certification | ESA and FCC compliance documentation opens procurement pathways across NATO member state defense programs. |
| Satellite-as-a-Service Launch | Standardized sensor configurations lower capital barriers for agriculture and environmental monitoring end users. |
| Workforce Knowledge Transfer Programs | Systematic capture of radiation-hardened design expertise addresses aging cohort retirement risk. |
| EU Space Traffic Management Pre-Certification | Early compliance with emerging collision avoidance mandates positions suppliers for institutional procurement preference. |
Research Methodology
Initial hypotheses were tested against primary input from payload integration engineers, defense procurement officers, commercial remote sensing operators, and focal plane array manufacturing specialists and refined through secondary validation. Primary fieldwork combined structured interviews with satellite system architects at heritage contractors and emerging electro-optical houses. Secondary sources encompassed FCC licensing databases, ESA procurement records, Space Force budget justification materials, and ISO 24113 certification registries. Bottom-up unit economics from individual sensor programs were triangulated against top-down defense and civilian space budget allocations.
Variance decomposition across technology segments, application verticals, and end-user categories shaped the analytical framework over the projection horizon. Modeled dimensions included sensor technology type, mission profile classification, deployment model, and regional regulatory cluster. CAGRs were derived from segment-level demand build-ups anchored in announced constellation programs and sovereign Earth observation procurement pipelines. Forecast inputs incorporated synthetic aperture radar constellation deployment schedules and polar satellite launch vehicle capacity expansion from ISRO commercialization.
Underlying assumptions cover sustained Space Force classified program funding, stable indium gallium arsenide substrate supply, and gradual ESA debris mitigation standard adoption, with deviation risk concentrated in ITAR export classification revisions and launch capacity bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Military Satellite Market
Satellite
Satellite Backhaul Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
UK Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
North America Satellite Bus Market
Satellite
Satellite GPS Receivers Market
Satellite
Electric Propulsion Satellite Market
Satellite
Global Satellite Modem Market
Satellite
Satellite Broadband Market
Satellite
Global LEO Satellite Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Satellite Communications Service Market
Satellite
Tactical Satellite Market
Satellite
Healthcare Satellite Connectivity Market