
 Military GNSS Anti-Jamming Systems Market | 2026-2036
Military GNSS Anti-Jamming Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military GNSS Anti-Jamming Systems Market Analysis
Israeli defense electronics manufacturers is repositioning supply chains toward dual-use beamforming architectures. Lockheed Martin leverages captive semiconductor fabrication to sustain anti-jam module output for fighter and bomber programs. Raytheon Technologies anchors naval platform integration through its proprietary null-steering arrays. Thales Group competes on European sovereignty credentials, specializing in Galileo-compatible military receivers.
Military GNSS anti-jamming systems are electronic warfare subsystems that employ controlled reception pattern antennas and digital signal processing to suppress intentional interference across L1, L2, and L5 frequency bands, maintaining position-navigation-timing integrity for weapon guidance and command networks. These systems filter, null, or geographically mask jamming sources through real-time adaptive algorithms executed on radiation-hardened processors. Integrated systems now dominate procurement budgets as platforms demand embedded rather than bolt-on resilience. Digital beamforming represents the fastest-expanding technology segment due to its software-defined adaptability against dynamic threat libraries. Ground-based installations retain the largest volume share, though airborne and naval segments command premium pricing for size-weight-power-constrained implementations.
The US DoD's PNT executive directive and NATO's STANAG 4694 establish mandatory resilience thresholds for allied platforms, while the EU's Galileo Public Regulated Service framework shapes European procurement specifications. FCC equipment authorization rules for military transmitters and the UK's Defence Equipment and Support agency certification gates further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving electronic warfare threat libraries and corresponding standards refresh cycles to align R&D roadmaps with operational test requirements.
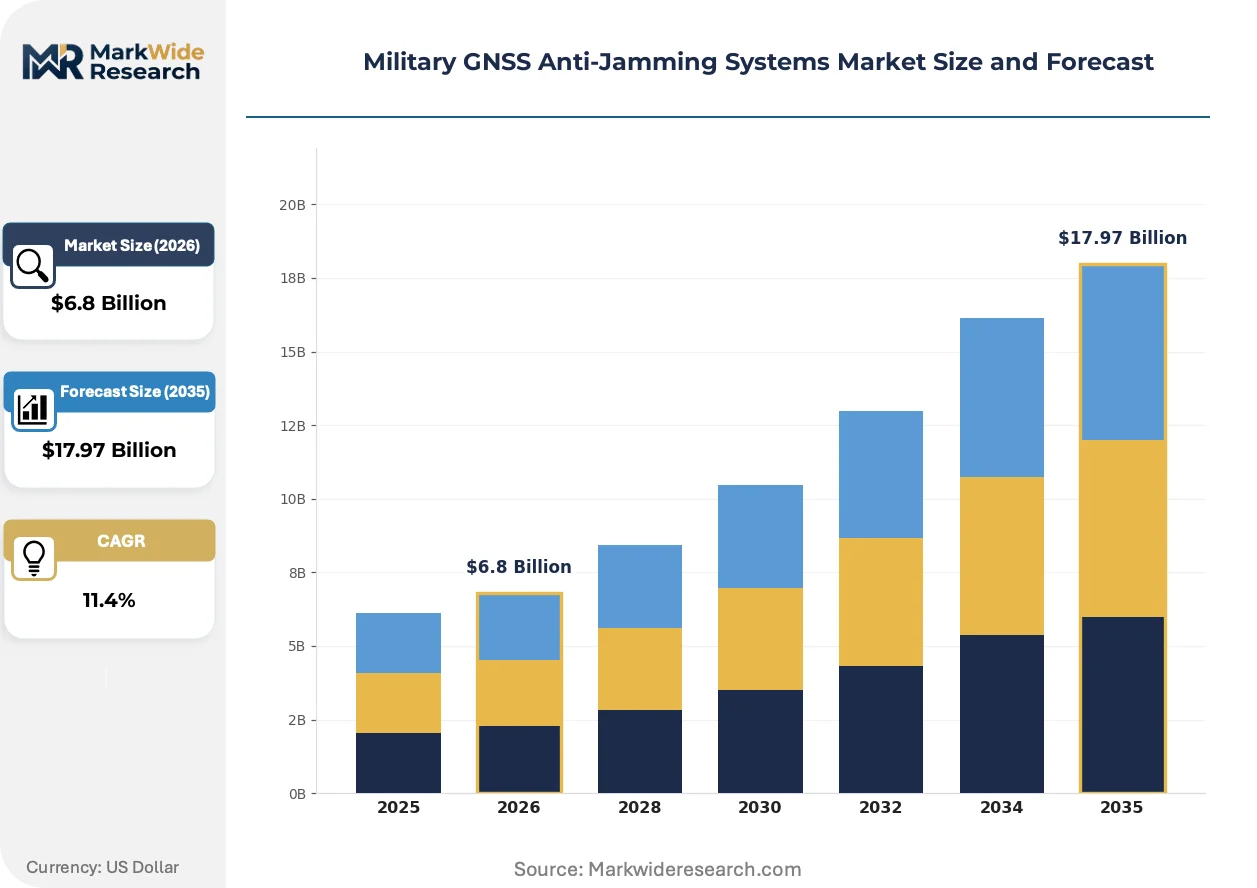
Market Dynamics
Platform modernization cycles across NATO allied forces are compressing as contested-electromagnetic-environment readiness becomes mandatory rather than aspirational, forcing anti-jamming subsystem integration into core avionics and naval combat system architectures rather than retrofit programs.
Growth Catalysts
- PNT Executive Directives:The US Department of Defense's renewed GPS resilience mandates accelerate fighter and bomber platform upgrades, embedding controlled reception pattern antennas into original equipment specifications.
- STANAG 4694 Harmonization:NATO standardization creates procurement alignment across member states, enabling economies of scale for radiation-hardened processor suppliers serving multiple allied programs.
- Airborne Segment Concentration:Size-weight-power-constrained implementations for tactical aircraft command premium pricing and drive digital beamforming adoption rates faster than ground-based alternatives.
Market Restraints
- Semiconductor Supply Concentration:Captive fabrication capabilities at major prime contractors limit accessible foundry capacity for mid-tier suppliers seeking radiation-hardened process nodes.
- Galileo PRS Access Friction:European Public Regulated Service framework creates certification gates that delay non-EU component suppliers from accessing military receiver specifications.
- Legacy Platform Interoperability:Analog antenna architectures in fielded naval vessels constrain null-steering algorithm deployment without complete mast electronics replacement.
Strategic Opportunities
- Australian Contested Environment Investment:The AUKUS security pact drives submarine and maritime patrol aircraft programs requiring sovereign anti-jamming capability development with technology transfer provisions.
- Dual-Use Beamforming Architectures:Israeli defense electronics manufacturers are repositioning supply chains to serve civilian autonomous vehicle markets while maintaining military-grade processing throughput.
- Software-Defined Adaptability:Digital signal processing convergence with threat library updates enables real-time algorithm refresh without hardware swap-outs, opening recurring revenue streams for cybersecurity-hardened firmware distribution.
Industry Challenges
- Radiation-Hardened Design Talent Scarcity:Specialized integrated circuit layout expertise for space-qualified and nuclear-event-tolerant processors remains concentrated at a handful of national laboratories and captive prime contractor divisions.
- Operational Test Timeline Compression:Accelerated fielding mandates under emergency procurement authorities compress electromagnetic environmental effects validation cycles, increasing technical risk for pre-production systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military GNSS Anti-Jamming Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Integrated Systems, Backup Systems Technology: Digital Beamforming, Analog Beamforming, Frequency Hopping, Null Steering End User: Military Applications, Aerospace, Government Agencies, Defense Contractors Installation: Ground-Based, Airborne, Naval, Mobile |
| Companies Covered | Cobham, Lockheed Martin, Raytheon Technologies, Chemring Group, NovAtel, Thales Group, L3Harris Technologies, Rockwell Collins, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military GNSS Anti-Jamming Systems Market Emerging Trajectories
Adaptive null-steering algorithms are migrating from hardware-defined to software-defined implementations, compressing the boundary between electronic warfare and signal intelligence functions while demanding new processor architectures.
Digital beamforming is integrating field-programmable gate array clusters with machine-learning inference engines to execute real-time jammer geolocation and adaptive antenna pattern synthesis. Fighter platform prime contractors are adopting this architecture for sixth-generation combat aircraft sensor fusion backbones. The technology is integrating previously separate electronic protection and electronic support measures into unified aperture management systems.
EU CSRD disclosure requirements are extending supply chain visibility mandates to military subsystem tiers, compelling component manufacturers to document conflict mineral sourcing and carbon intensity for anti-jam module assemblies. Prime contractors serving European defense ministries must now validate tier-three supplier compliance. Naval platform integrators face the steepest documentation burden due to extended supply chains spanning rare earth magnet processors.
Consolidated platform procurement offices are unbundling anti-jamming subsystems from complete avionics packages, enabling competitive sourcing of controlled reception pattern antennas independent of mission computer vendors. This disintermediation fragments previously captive supply relationships. The United Kingdom's Defence Equipment and Support agency demonstrates this most visibly through separate competition phases for antenna hardware and signal processing firmware.
Military GNSS Anti-Jamming Systems Market Segmentation
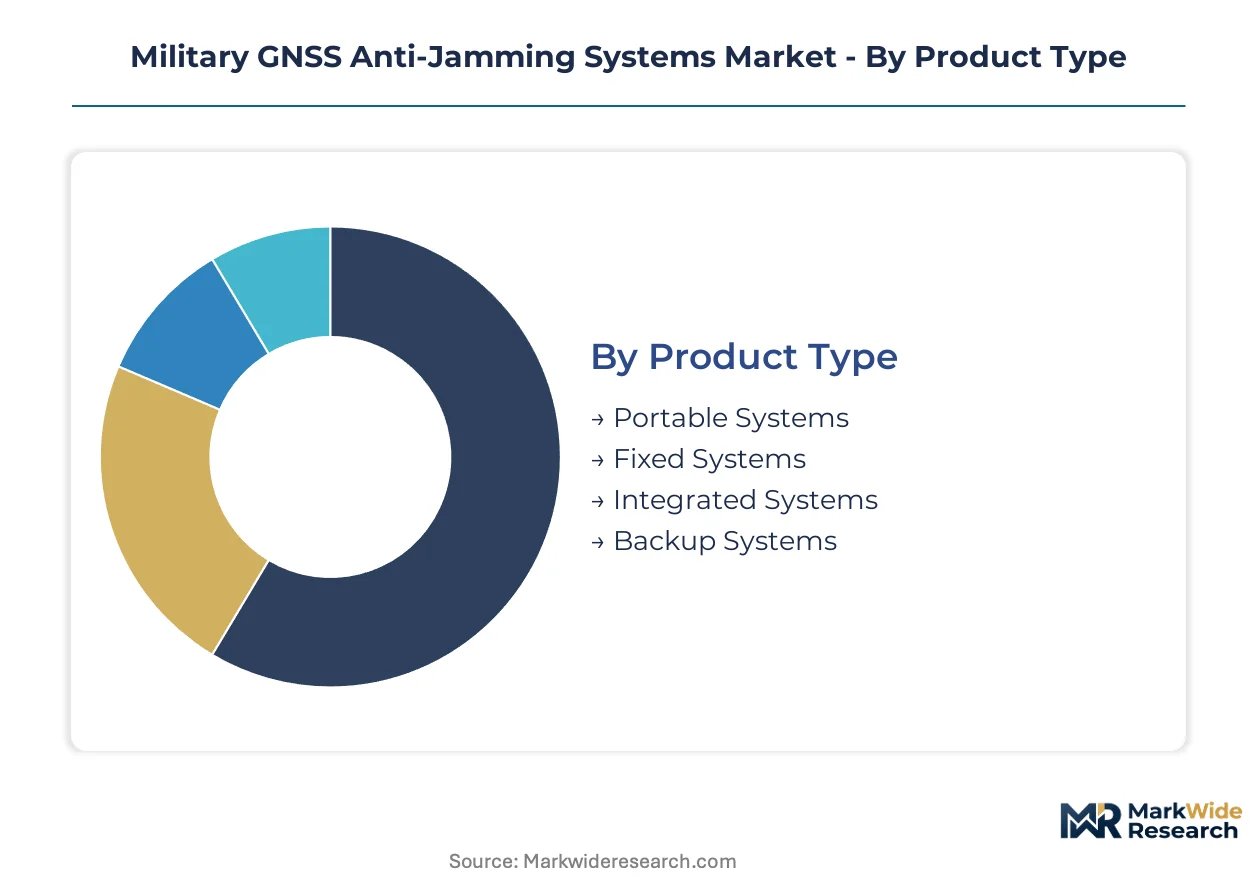
Segmentation in military GNSS anti-jamming systems reveals how procurement priorities diverge across platform constraints, threat environments, and integration complexity. Buyers select architectures based on electromagnetic contested-environment readiness requirements rather than cost optimization alone.
Product Type:
Platform integrators differentiate procurement strategies based on retrofit feasibility versus original equipment specification cycles.
- Integrated Systems:Embedded architectures fuse controlled reception pattern antennas with mission computers through radiation-hardened backplanes. Fighter and bomber programs across the United States, the United Kingdom, and Australia mandate these configurations under PNT executive directives, compressing subsystem procurement into airframe development timelines.
- Fixed Systems:Permanent installations anchor ground-based command centers and naval combat information centers with hardened antenna farms and redundant signal processing chains. NATO STANAG 4694 compliance requirements drive standardization across allied ground stations.
- Portable Systems:Man-portable units serve expeditionary forces requiring rapid electromagnetic spectrum resilience deployment.
- Backup Systems:Secondary receivers maintain position-navigation-timing integrity during primary system degradation.
Volume sits with Fixed Systems; growth tilts toward Integrated Systems.
Technology:
Signal processing architectures separate suppliers capable of software-defined adaptability from those locked into hardware-defined implementations.
- Digital Beamforming:Field-programmable gate array clusters execute real-time adaptive algorithms against dynamic threat libraries. Sixth-generation combat aircraft programs in the United States and United Kingdom specify these architectures for unified aperture management, displacing analog alternatives in size-weight-power-constrained implementations.
- Null Steering:Proprietary array geometries suppress jammer energy through spatial filtering without frequency domain switching. Raytheon Technologies anchors naval platform integration through advanced null-steering implementations for mast-mounted installations.
- Analog Beamforming:Phase-shifter networks provide cost-efficient resilience for legacy platform retrofits.
- Frequency Hopping:Spread-spectrum techniques complement spatial anti-jamming for layered protection.
Procurement concentrates in Digital Beamforming; steepest expansion trajectory belongs to Null Steering as naval modernization accelerates.
End User:
Budget authority and operational test requirements create distinct qualification pathways across defense procurement hierarchies.
- Military Applications:Service branch laboratories validate electromagnetic environmental effects under accelerated fielding mandates. The US Department of Defense's GPS resilience directives compress test cycles for fighter, bomber, and naval platforms.
- Aerospace:Prime contractors integrate anti-jam modules into airframe sensor fusion backbones. Lockheed Martin leverages captive semiconductor fabrication to sustain output for classified programs.
- Government Agencies:National laboratories specify radiation-hardened processors for nuclear-event-tolerant architectures.
- Defense Contractors:Subsystem suppliers compete for unbundled antenna and firmware procurement phases.
Revenue concentrates in Military Applications; fastest share gain occurs in Aerospace as platform integration deepens.
Installation:
Physical operating environments dictate size-weight-power constraints and threat exposure profiles.
- Ground-Based:Fixed installations at command centers and communications nodes retain largest procurement volume. Extended supply chains spanning rare earth magnet processors create documentation burdens under EU CSRD disclosure requirements.
- Airborne:Tactical aircraft implementations command premium pricing for constrained avionics bays. The AUKUS security pact drives Australian investment in sovereign airborne anti-jamming capability with technology transfer provisions.
- Naval:Mast-mounted arrays face salt corrosion and electromagnetic interference from shipboard radars.
- Mobile:Vehicle-mounted units support expeditionary maneuver forces.
Ground-Based installations dominate volume; Airborne segments gain share fastest as contested-electromagnetic-environment readiness becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing clusters in Mountain Pass, California, and Australian heavy mineral sands deposits anchor the upstream material base for radiation-hardened processor fabrication. Defense procurement authorities across NATO member states source finished anti-jam modules through nationally qualified assembly facilities.
United States
The Department of Defense's GPS resilience mandates under PNT executive directives compress platform modernization cycles for fighter and bomber programs. FCC equipment authorization rules for military transmitters establish electromagnetic compatibility thresholds that subsystem suppliers must satisfy before operational test. Lockheed Martin's captive semiconductor fabrication in Sunnyvale, California, sustains classified program output for airborne implementations.
United Kingdom
The Defence Equipment and Support agency unbundles anti-jamming subsystem procurement from complete avionics packages, enabling competitive antenna sourcing independent of mission computer vendors. STANAG 4694 harmonization creates procurement alignment with allied NATO forces, standardizing radiation-hardened processor specifications. Thales Group's Glasgow facility specializes in Galileo-compatible military receiver development for European sovereignty requirements.
Australia
The AUKUS security pact drives submarine and maritime patrol aircraft programs requiring sovereign anti-jamming capability with technology transfer provisions. The country's defense procurement office mandates contested-electromagnetic-environment readiness as mandatory rather than aspirational for all new platform acquisitions. Canberra-based system integrators partner with US primes for digital beamforming technology insertion into airborne implementations.
Israel
Israeli defense electronics manufacturers reposition supply chains toward dual-use beamforming architectures serving civilian autonomous vehicle markets while maintaining military-grade processing throughput. The country's national security establishment classifies electromagnetic warfare threat libraries, constraining foreign supplier access to operational test data. Tel Aviv-area design houses concentrate field-programmable gate array expertise for real-time adaptive algorithm development.
Germany
The Bundeswehr's platform modernization programs prioritize STANAG 4694 compliance for ground-based command center installations across NATO's eastern flank. EU CSRD disclosure requirements extend supply chain visibility mandates to military subsystem tiers, compelling documentation of conflict mineral sourcing for anti-jam module assemblies. Bavaria-based electronics clusters specialize in radiation-hardened integrated circuit layout for nuclear-event-tolerant processor architectures.
Military GNSS Anti-Jamming Systems Market Vendor Landscape
Global majors compete with regional champions across technology licensing and captive fabrication capabilities, producing a tiered structure where prime contractors control radiation-hardened process nodes while mid-tier suppliers compete for unbundled antenna procurement. The vendor base separates into three strategic archetypes: vertically integrated platform primes with captive semiconductor foundries, specialized subsystem suppliers with proprietary null-steering intellectual property, and dual-use technology developers bridging military and commercial autonomous navigation markets. Competitive moves concentrate on strategic partnerships for threat library access and geographic expansion through national qualification pathways.
Among US-based platform integrators, Lockheed Martin and Raytheon Technologies exemplify the vertically integrated prime archetype, anchoring fighter and naval platform segments respectively through controlled reception pattern antenna development. Thales Group occupies a position within the European sovereignty tier, leveraging Galileo Public Regulated Service framework access to compete on military receiver specifications compliant with EU defense procurement preferences.
| Leading Market Players |
|---|
| Cobham |
| Lockheed Martin |
| Raytheon Technologies |
| Chemring Group |
| NovAtel |
| Thales Group |
| L3Harris Technologies |
| Rockwell Collins |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
A pronounced bifurcation between radiation-hardened integrated systems and commodity analog retrofits shapes both procurement economics and supplier network configurations across the military GNSS anti-jamming landscape. This tier divergence concentrates pricing power with captive semiconductor foundries serving classified programs while fragmenting margins among mid-tier antenna suppliers competing for unbundled procurement phases.
Pricing Analysis
Warranty and firmware update bundling separates premium tier suppliers from commodity competitors in military GNSS anti-jamming procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under STANAG 4694 and FCC equipment authorization rules. Cost compression in the economy tier intensifies because Israeli and Australian suppliers are repositioning toward dual-use civilian markets. Defense procurement offices exhibit lowest price sensitivity for airborne size-weight-power-constrained implementations, while ground-based fixed installations face steepest budget scrutiny.
Supply Chain Analysis
Reverse-logistics flows for radiation-hardened processor refurbishment center on Mountain Pass, California, and Tel Aviv-area facilities handling field-programmable gate array recovery. Upstream supply draws from Australian heavy mineral sands deposits and Mountain Pass rare earth magnet processing for radiation-hardened fabrication inputs. Single-source vulnerability concentrates in captive foundry capacity at major prime contractors, constraining accessible process nodes for mid-tier suppliers. Distribution runs through nationally qualified assembly facilities across the United States, United Kingdom, and Germany, with NATO STANAG harmonization enabling cross-border component qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as accelerated operational test timelines under emergency procurement authorities force weaker subsystem suppliers toward acquisition or exit. Radiation-hardened design talent scarcity and compressed electromagnetic environmental effects validation cycles favor scaled incumbents with captive fabrication and threat library access.
For Market Incumbents: Anchor market position through backward integration into field-programmable gate array design houses and exclusive threat library licensing agreements with national security establishments. Lockheed Martin's captive Sunnyvale fabrication demonstrates how in-house production of radiation-hardened processors insulates against foundry capacity constraints. Incumbents should consolidate null-steering intellectual property through targeted acquisition of specialized naval subsystem suppliers facing margin pressure from unbundled procurement mandates. For New Entrants and Emerging Players: The price-point gap between sixth-generation combat aircraft integrated systems and legacy naval analog retrofits offers white-space entry for digital beamforming specialists with software-defined adaptability credentials. Australian AUKUS-related submarine and maritime patrol aircraft programs present the most penetrable geography given explicit technology transfer provisions and sovereign capability development mandates. New entrants should pursue competitive antenna sourcing phases separated from mission computer procurement, as demonstrated by the United Kingdom's Defence Equipment and Support agency unbundling strategy. For Investors and Strategic Acquirers: Re-rating potential sits with dual-use beamforming developers given civilian autonomous vehicle market expansion and military-grade processing throughput maintenance. Long-term viability across the analysis window favors suppliers with Galileo Public Regulated Service framework access and EU CSRD disclosure compliance infrastructure. Acquisition targets should display field-programmable gate array expertise for real-time adaptive algorithms and established relationships with national laboratories specifying nuclear-event-tolerant architectures. Investors should monitor AUKUS technology transfer implementation velocity and EU defense procurement preference enforcement as inflection indicators for market access and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication Expansion | Lockheed Martin's Sunnyvale facility sustains classified program output independent of external foundry constraints. |
| Dual-Use Beamforming Architecture Development | Israeli suppliers bridge military and civilian autonomous navigation markets while maintaining processing throughput. |
| Threat Library Cybersecurity Hardening | Real-time algorithm refresh capabilities open recurring revenue streams for firmware distribution networks. |
| Galileo PRS Certification Investment | Thales Group leverages European sovereignty credentials to compete on military receiver specifications. |
| AUKUS Technology Transfer Partnership | Canberra-based integrators access US digital beamforming expertise for sovereign airborne implementations. |
Methodological Framework
Document review covered defense procurement databases, FCC equipment authorization filings, and NATO standardization records, complemented by interviews with prime contractor platform engineers, radiation-hardened processor design specialists, and Defence Equipment and Supply agency procurement officers. Secondary validation drew from US Department of Defense PNT executive directive disclosures, EU CSRD supply chain visibility mandates, and AUKUS security pact implementation documentation. Bottom-up segment sizing across product type, technology, and installation categories was triangulated against top-down defense budget allocation analysis.
Segment-level demand projections across the analysis window incorporated platform modernization cycle compression, contested-electromagnetic-environment readiness mandate expansion, and unbundled procurement phase proliferation. The analytical framework modeled technology adoption trajectories for digital beamforming versus analog alternatives, end-user budget authority hierarchies, and geographic qualification pathway constraints. CAGRs were derived from defense procurement commitment trajectories and subsystem integration timeline elasticity, with specific inputs including fighter and bomber platform production schedules and naval combat system upgrade sequencing.
Inputs from national security establishment threat library classifications were available through the study window; gaps in operational test data from classified programs introduce uncertainty bands around airborne segment penetration assumptions. Forecasts reflect documented procurement authority commitments and electromagnetic environmental effects validation timelines. Practitioners should monitor STANAG 4694 refresh cycles, EU defense procurement preference enforcement, and AUKUS technology transfer velocity for early signals of market access and competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Inertial Navigation System Market