
 Europe Naval Vessels Market | 2026-2036
Europe Naval Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Naval Vessels Market Foresight
Export-credit-backed leasing and multi-year framework contracts is fragmenting the traditional prime-contractor landscape in European naval procurement. Naval Group leverages its sovereign design heritage to dominate France's nuclear submarine pipeline. BAE Systems plc sustains its position through the Type 26 frigate program and UK carrier ecosystem integration. Damen Shipyards Group competes across corvette and offshore patrol vessel tiers with modular build strategies.
Europe naval vessels encompass surface combatants and submarines built to NATO interoperability standards, typically displacing 1,500 to 70,000 tonnes with integrated combat management systems and signature-reduction architectures. Their primary purpose is power projection, sea-lane security, and deterrence within collective defense frameworks. Frigates command the largest share of newbuild capital allocation due to multi-mission flexibility requirements. Submarines represent the fastest-growing technology segment as Baltic and Mediterranean states prioritize undersea domain awareness. Stealth integration across hull forms and propulsion signatures now determines platform competitiveness in NATO tender evaluations.
EU Green Deal emission benchmarks and REACH material compliance are tightening hull-coating and powertrain specifications for yards across the continent. The EU AI Act and MDR certification pathways increasingly govern autonomous navigation and combat-system software deployed aboard European naval platforms. Stakeholders must monitor how PESCO project consolidation and national sovereignty clauses interact in upcoming fleet replacement cycles.
Market Dynamics
PESCO project consolidation is fragmenting traditional national procurement sovereignty across European naval yards, forcing cross-border consortium structures and shared hull designs that reshape competitive positioning.
Growth Catalysts
- NATO Capability Targets:Alliance defense spending benchmarks compel member states to accelerate fleet replacement cycles, particularly for anti-submarine warfare platforms in the Baltic corridor.
- REACH Material Compliance:ECHA regulations on hazardous substances are mandating next-generation hull coatings and composite materials that extend vessel service intervals while reducing dry-dock maintenance.
- Undersea Domain Awareness:Mediterranean and Baltic navies prioritize submarine procurement and seabed sensor networks, creating sustained demand for air-independent propulsion systems.
Market Restraints
- Steel and Rare Earth Volatility:Nickel-molybdenum alloy prices fluctuate with energy market instability, compressing yard margins on fixed-price frigate contracts.
- Propulsion System Concentration:Marine gas turbine supply depends on a narrow supplier base in Germany and the United Kingdom, creating single-source vulnerability for combatant programs.
- EU AI Act Certification Friction:Combat management system software faces extended validation timelines under MDR-equivalent pathways, delaying platform commissioning.
Strategic Opportunities
- Polish Naval Expansion:Warsaw's Miecznik frigate program and Orka submarine procurement create entry points for non-traditional suppliers into previously closed markets.
- Modular Corvette Platforms:Standardized mission-module architectures enable yards to serve multiple NATO navies with hull variants adapted to littoral patrol, mine countermeasures, or anti-surface warfare.
- EU Green Deal Shipyard Funding:Horizon Europe and EIB financing instruments subsidize hydrogen fuel cell and hybrid-electric propulsion retrofits for existing patrol vessels.
Industry Challenges
- Naval Architect Talent Scarcity:Retiring workforce cohorts in France, Italy, and the Netherlands outpace university pipeline output for combat system integration specialists.
- Legacy Combat System Integration:New platforms must interoperate with national C4ISR networks built on 1990s architectures, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Naval Vessels Market |
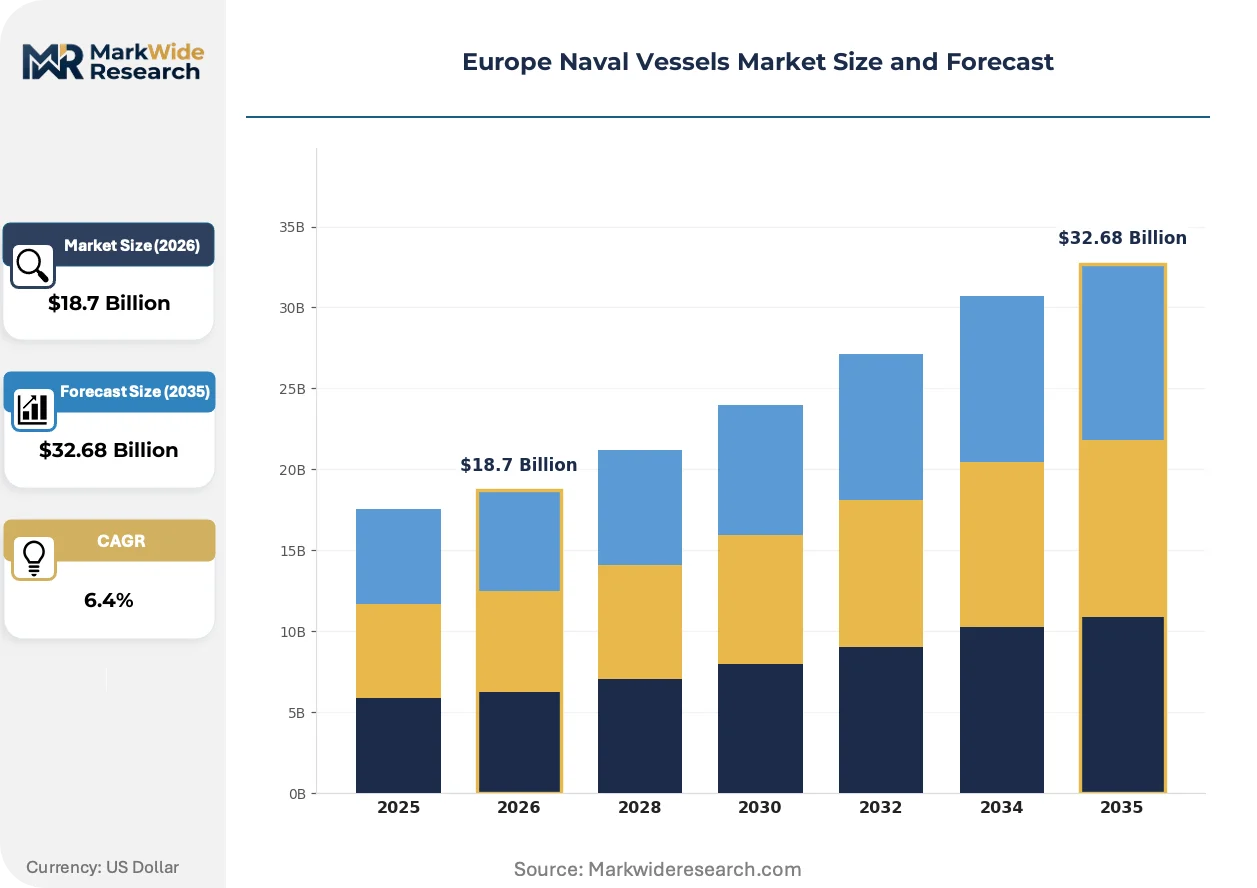
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Corvettes, Frigates, Submarines, Destroyers End User: Navies, Coast Guards, Research Institutions, Contractors Technology: Stealth, Automation, Propulsion Systems, Navigation Systems Service Type: Maintenance, Repair, Modernization, Training |
| Companies Covered | Naval Group, FINCANTIERI S.p.A., BAE Systems plc, Navantia S.A. SM.E, ThyssenKrupp AG, Lürssen Werft GmbH & Co. KG, Damen Shipyards Group, SAAB Kockums, German Naval Yards Kiel GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Naval Vessels Market Shifts & Advancements
Digital twin architectures and autonomous payload systems are compressing design-to-commission cycles while redefining crew complement requirements across European surface combatant programs.
Integrated platform management systems are digitizing vessel-wide propulsion, electrical, and damage control functions into unified software layers. French and Italian yards deploy these architectures on FREMM derivatives and PPA offshore patrol vessels. This convergence is digitizing maintenance scheduling from calendar-based to condition-predictive models, compressing through-life support costs.
EU AI Act liability frameworks now govern autonomous navigation and combat decision-support algorithms aboard European naval platforms. EMA-equivalent certification pathways for military software extend development timelines but create competitive moats for yards with established regulatory navigation capabilities. Surface combatant programs in Germany and Spain face the steepest compliance cost absorption.
Multi-year framework agreements with sovereign lease-back provisions are displacing traditional single-ship procurement. Nordic and Baltic navies now contract operational availability rather than hull ownership, transferring platform risk to yard consortia. This model concentrates most visibly in Dutch and Belgian mine countermeasures programs.
Europe Naval Vessels Market Segmentation
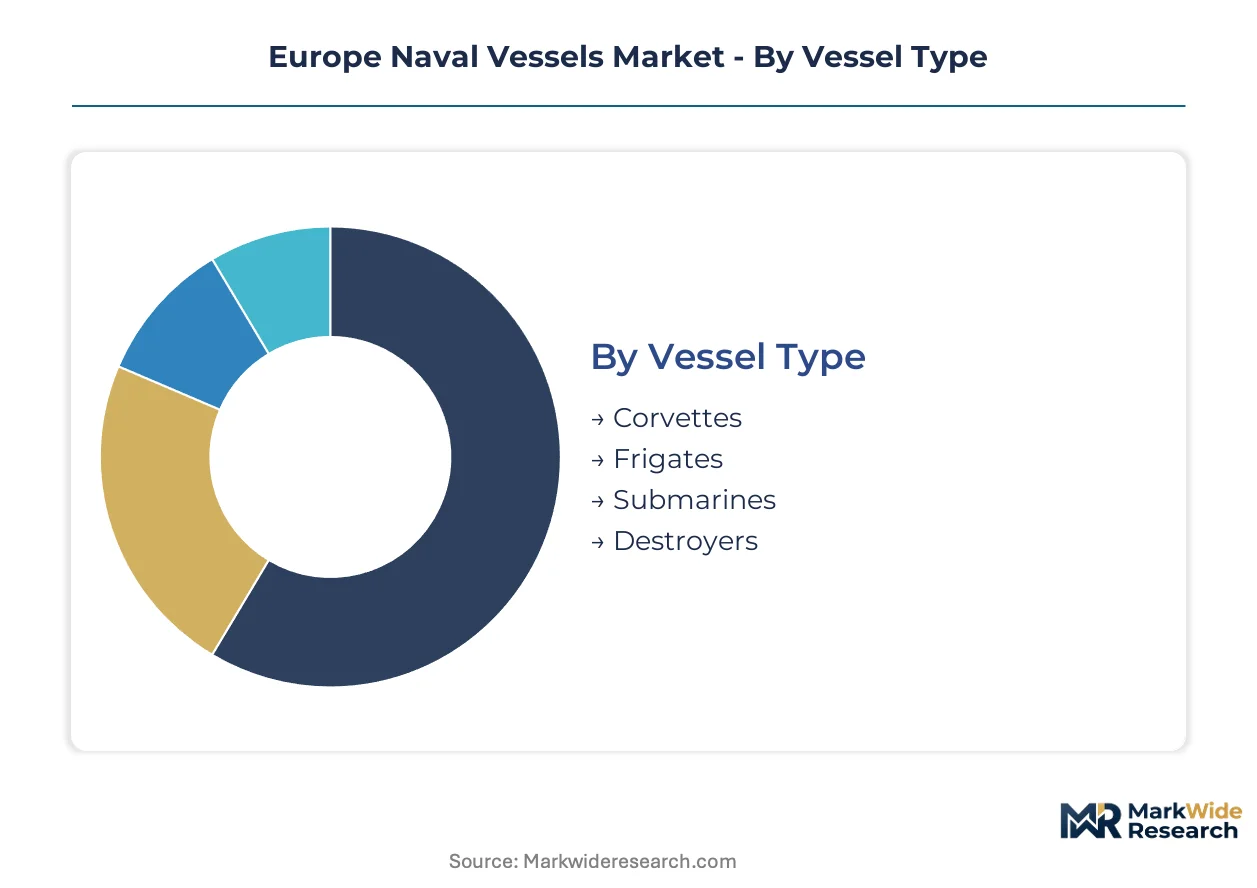
European naval procurement operates through distinct capability tiers that determine platform specifications, NATO interoperability requirements, and national sovereignty considerations. Understanding these segment boundaries reveals where defense budgets concentrate and where technology gaps create entry opportunities for specialized suppliers.
Vessel Type:
Mature hull categories dominate capital allocation while emerging designs reshape fleet architectures across NATO's eastern flank.
- Frigates:Multi-mission surface combatants displacing 3,000 to 7,000 tonnes with integrated anti-air, anti-submarine, and land-attack capabilities. French, German, and Italian navies anchor demand through FREMM derivatives and next-generation programs, driven by NATO's requirement for escort vessels protecting carrier strike groups and amphibious task forces in the Mediterranean and Baltic corridors.
- Submarines:Diesel-electric and air-independent propulsion hulls ranging from 1,500 to 2,500 tonnes submerged displacement. Poland's Orka program and Swedish A26 procurement signal accelerating Baltic and Mediterranean demand for undersea domain awareness platforms, constrained by restricted supplier bases for combat management systems and propulsion technology.
- Corvettes:Littoral combatants under 3,000 tonnes optimized for exclusive economic zone patrol and mine countermeasures. Modular mission architectures enable Scandinavian and Baltic navies to swap payloads between anti-surface and mine warfare configurations.
- Destroyers:Large surface combatants exceeding 7,000 tonnes with area air defense and command-and-control functions. Limited to France, the United Kingdom, and Italy due to procurement cost and crew complement requirements.
Frigates handle the majority of throughput; Submarines are the fastest mover on share.
End User:
Customer type determines procurement sovereignty rules, funding mechanisms, and operational availability requirements across European defense frameworks.
- Navies:National fleet commands operating under ministry of defense authority with sovereign procurement rights. French, German, British, and Italian naval staffs command the largest capital allocations, though PESCO frameworks increasingly mandate cross-border consortium structures for major combatant programs.
- Coast Guards:Maritime law enforcement agencies with constabulary rather than combatant missions. Italian Guardia Costiera and Spanish Salvamento Maritimo drive offshore patrol vessel demand for search-and-rescue and fisheries protection.
- Research Institutions:National oceanographic organizations and defense research agencies. NATO Centre for Maritime Research and Experimentation contracts specialized survey vessels and autonomous platform testing.
- Contractors:Private fleet operators delivering operational availability through sovereign lease-back arrangements. Dutch-Belgian mine countermeasures consortia exemplify this emerging procurement model.
Navies absorb the dominant share of platform investment; Contractors are expanding most quickly as availability-based contracting displaces hull ownership.
Technology:
Capability differentiation increasingly concentrates in signature management and autonomous system integration rather than raw platform performance.
- Stealth:Radar cross-section reduction through hull shaping, composite superstructures, and infrared signature suppression. French and Swedish yards lead integration of angled faceting and radar-absorbent materials on surface combatants.
- Automation:Reduced crew complement through integrated platform management and unmanned systems control. Italian PPAs and German F126 frigates demonstrate this trajectory with sub-100 core crew requirements.
- Propulsion Systems:Combined diesel-electric and gas turbine architectures, plus emerging fuel cell and hybrid-electric options. German MTU and British Rolls-Royce marine gas turbines face concentration risk as primary suppliers.
- Navigation Systems:Inertial and satellite-based positioning with EU GNSS Galileo integration. Cyber-resilient navigation increasingly mandated under EU defense procurement directives.
Propulsion Systems claim the largest technology spend; Automation is climbing the fastest as manpower costs and recruitment constraints intensify.
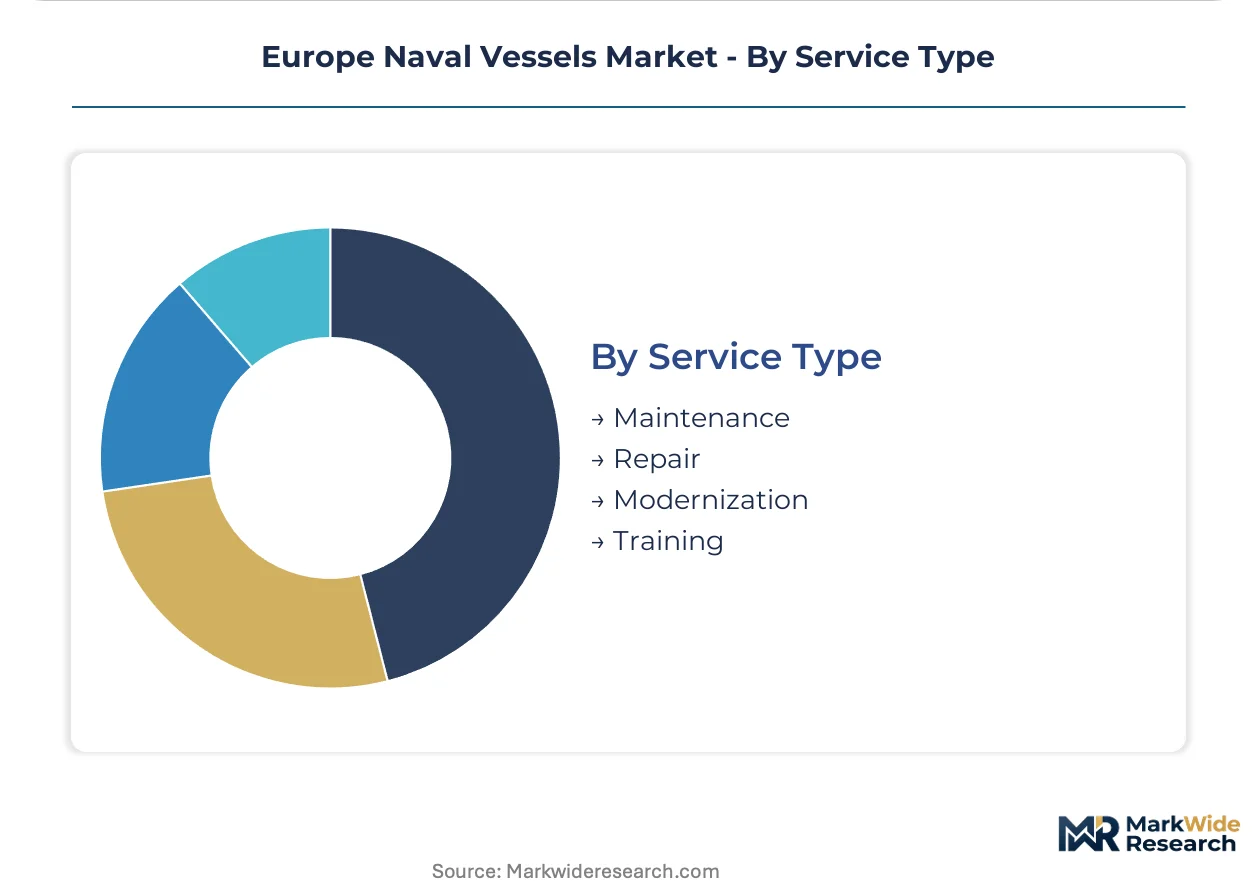
Service Type:
Through-life support economics now rival acquisition costs in total ownership calculations, reshaping yard business models toward availability contracting.
- Maintenance:Scheduled preventive servicing and corrective repair during operational cycles. Calendar-based intervals are shifting to condition-monitoring approaches using digital twin architectures.
- Repair:Unscheduled corrective work following damage, defect, or combat casualty. Baltic and Mediterranean yards compete for NATO damage repair certification.
- Modernization:Mid-life upgrades to combat systems, sensors, and weapon interfaces. Legacy platform obsolescence drives sustained demand as 1990s-era hulls approach capability limits.
- Training:Crew certification and simulator-based mission rehearsal. Synthetic training environments reduce at-sea operating costs while maintaining operational readiness.
Maintenance captures the dominant service volume; Modernization is gaining share fastest as fleet replacement cycles lag behind technology refresh rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet modernization contracts concentrate in NATO's northern and Mediterranean members, with procurement sovereignty clauses creating distinct national market access patterns across European yards.
France
Naval Group's nuclear submarine pipeline and FREMM frigate derivatives anchor sustained capital allocation through 2035. The EU AI Act certification pathways govern combat management software deployment on next-generation platforms. Toulon and Cherbourg harbor clusters specialize in nuclear propulsion integration and signature-reduction architectures.
Germany
ThyssenKrupp Marine Systems and German Naval Yards Kiel drive submarine and surface combatant demand under NATO's Baltic ASW requirements. REACH material compliance mandates next-generation hull coatings across all newbuild programs. The Kiel shipbuilding corridor concentrates air-independent propulsion technology development and fuel cell integration expertise.
United Kingdom
BAE Systems plc sustains demand through Type 26 frigate production and carrier ecosystem integration. Ministry of Defence availability-based contracting shifts procurement risk to yard consortia. The Clyde and Rosyth clusters manage complex combat system integration with legacy C4ISR network interoperability requirements.
Italy
FINCANTIERI S.p.A. leverages FREMM and PPA programs to capture multi-mission surface combatant demand. PESCO framework participation mandates cross-border consortium structures for major programs. The Riva Trigoso and Muggiano yards specialize in reduced-crew automation architectures and integrated platform management systems.
Poland
Warsaw's Miecznik frigate and Orka submarine procurement programs create entry opportunities for non-traditional suppliers into previously closed markets. NATO capability targets accelerate fleet replacement timelines. The Gdynia and Świnoujście naval bases drive requirements for littoral combatants with modular mission architectures.
Europe Naval Vessels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. Sovereign design heritage and NATO interoperability certification create defensive moats for established yards. Three archetypes dominate: state-linked primes with nuclear credentials, modular-build specialists in corvette and OPV tiers, and consortium-structured entities serving PESCO frameworks. Competitive moves concentrate on cross-border joint ventures and availability-based contracting models that transfer operational risk.
Among France-based state-linked primes, Naval Group exemplifies sovereign nuclear submarine capabilities. FINCANTIERI S.p.A. and BAE Systems plc occupy positions within the multi-national surface combatant tier, with Italian and British structures respectively. Damen Shipyards Group represents the modular-build specialist archetype across corvette and offshore patrol vessel segments.
| Leading Market Players |
|---|
| Naval Group |
| FINCANTIERI S.p.A. |
| BAE Systems plc |
| Navantia S.A. SM.E |
| ThyssenKrupp AG |
| Lürssen Werft GmbH & Co. KG |
| Damen Shipyards Group |
| SAAB Kockums |
| German Naval Yards Kiel GmbH |
| Others |
Supply & Pricing Matrix
Overcapacity in Baltic and Mediterranean shipbuilding corridors compresses yard pricing power while forcing consolidation into consortium structures that pool procurement leverage. This utilization dynamic tightens margins on fixed-price frigate contracts and accelerates availability-based contracting models that transfer platform risk to builders.
Pricing Analysis
Certification level under NATO interoperability standards creates the primary spread between premium and standard tiers, with EU AI Act and MDR-equivalent software validation extending lead times for combat management systems. Project-based long-term contracting dominates major surface combatant programs, while sovereign lease-back arrangements with operational availability clauses reshape submarine procurement economics. Price differentiation intensifies around air-independent propulsion technology and signature-reduction architectures, with Polish and Baltic navies exhibiting highest sensitivity due to accelerated fleet replacement timelines and budget constraints.
Supply Chain Analysis
Tariff exposure between Germany and France on marine gas turbine components dominates supply chain risk planning for surface combatant programs. Propulsion system manufacturing concentrates in Germany, the United Kingdom, and Italy, with nickel-molybdenum alloy sourcing tethered to energy market volatility. Critical dependencies include radar-absorbent composite materials, air-independent propulsion fuel cells, and integrated combat management software stacks. Single-source vulnerability in German MTU and British Rolls-Royce marine turbine supply creates concentration risk. Distribution runs through national ministry of defense procurement channels with increasing PESCO-mandated cross-border consortium structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe naval vessels represent a high-growth disruption as NATO capability targets and EU Green Deal emission benchmarks simultaneously reshape fleet architectures and propulsion technology roadmaps.
For Market Incumbents: Build regulatory navigation moats around EU AI Act and MDR-equivalent certification pathways for autonomous combat systems. Naval Group and FINCANTIERI S.p.A. should deepen backward integration into air-independent propulsion fuel cell technology to capture Polish Orka submarine demand. BAE Systems plc must anchor capacity in the Clyde cluster to secure Type 26 derivative export positioning against modular-build specialists.
For New Entrants and Emerging Players: Establish a beachhead in Polish Miecznik frigate and Orka submarine programs where procurement sovereignty clauses have loosened previously closed markets. Modular corvette platforms with standardized mission-module architectures offer the most penetrable entry point, particularly for Scandinavian and Baltic littoral combatant requirements. A go-to-market angle through Horizon Europe and EIB Green Deal financing instruments for hydrogen fuel cell retrofits bypasses traditional prime-contractor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among yards with availability-based contracting and sovereign lease-back provisions in Dutch-Belgian mine countermeasures programs. Long-term viability over the next decade rests on positioning against EU defense procurement directives and PESCO consolidation mandates. Acquisition targets should emphasize yards with established NATO interoperability certification and digital twin architecture capabilities. The signal to watch is Polish procurement committee decisions on non-traditional supplier qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| PESCO Consortium Formation | Cross-border joint ventures pool R&D costs for FREMM-derived frigate programs across France, Italy, and Greece. |
| Air-Independent Propulsion Scale-Up | Fuel cell technology investment captures accelerating Baltic submarine demand under NATO ASW benchmarks. |
| Digital Twin Architecture Deployment | Condition-predictive maintenance models compress through-life support costs for Italian PPA offshore patrol vessels. |
| Green Deal Retrofit Financing | Horizon Europe subsidies enable hydrogen fuel cell conversion of existing patrol vessels in Spanish and Portuguese fleets. |
| Modular Mission Module Standardization | Swappable payload architectures allow Damen Shipyards Group to serve multiple NATO navies from single hull platforms. |
Research Methodology
A spread of perspectives from naval procurement officers at ministry of defense level, shipyard program managers, combat system integration engineers, and EIB defense financing specialists converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against NATO capability target documentation, EU defense procurement directive filings, and national fleet modernization white papers. Bottom-up vessel program tracking across France, Germany, the United Kingdom, Italy, and Poland triangulated against top-down defense budget allocation analysis.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning vessel type, end-user authority, propulsion technology tier, and service contract structure. CAGRs derived from program-level contract value aggregation and announced fleet replacement timelines. Industry-specific forecast inputs included PESCO project consolidation schedules and REACH material compliance phase-in requirements for hull coating specifications.
Macroeconomic conditions sit as an overlay; deviation in nickel-molybdenum alloy prices, energy market stability, or NATO defense spending benchmarks would shift the trajectory of yard margin compression and availability-based contracting adoption. Forecasts reflect documented assumptions on program award timing and cross-border consortium formation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Marine Radar Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Military Frigate Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Radar Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Sea Skimmer Missile Market