
 Asia-Pacific Satellite IoT Market | 2026-2036
Asia-Pacific Satellite IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite IoT Market Insights
Enterprise-grade connectivity specifications are redrawing competitive boundaries in satellite IoT procurement across the Asia-Pacific. ORBCOMM Inc. leverages its legacy asset-tracking protocols to sustain logistics customer retention in Japanese port systems. Thales Group anchors defense-adjacent maritime contracts through hardened terminal designs that meet NATO-equivalent resilience standards. China Aerospace Science and Technology Corporation dominates domestic constellation deployment, operating government-backed LEO infrastructure that controls spectrum access for mainland IoT providers.
Satellite IoT denotes machine-to-machine data exchange relayed through orbiting transponders, typically operating in L-band or S-band frequencies below 2.5 GHz to penetrate vegetation and weather layers for remote telemetry collection. The architecture serves industrial users requiring uninterrupted monitoring across oceanic, desert, or mountainous zones where fiber and terrestrial towers cannot reach. LPWAN satellite hybrids currently lead commercial uptake by combining low-power endpoint economics with orbital backhaul for agricultural sensor grids across Indonesia and Vietnam. Maritime applications represent the fastest-expanding segment as flag-state mandates for automatic identification and emissions reporting force fleet retrofits. Cloud-based deployment models concentrate margin pools among platform aggregators that normalize multi-constellation data streams for enterprise software integration.
TRAI in India, MIIT in China, and Japan's MIC collectively shape market access through national spectrum licensing regimes that determine which satellite operators may serve domestic IoT endpoints. Australia's ACMA enforces device certification standards that filter non-compliant terminal imports, protecting incumbent service quality but raising barriers for new constellation entrants. Stakeholders must monitor evolving orbital debris mitigation rules and cross-border data localization requirements that could fragment previously seamless satellite coverage architectures.
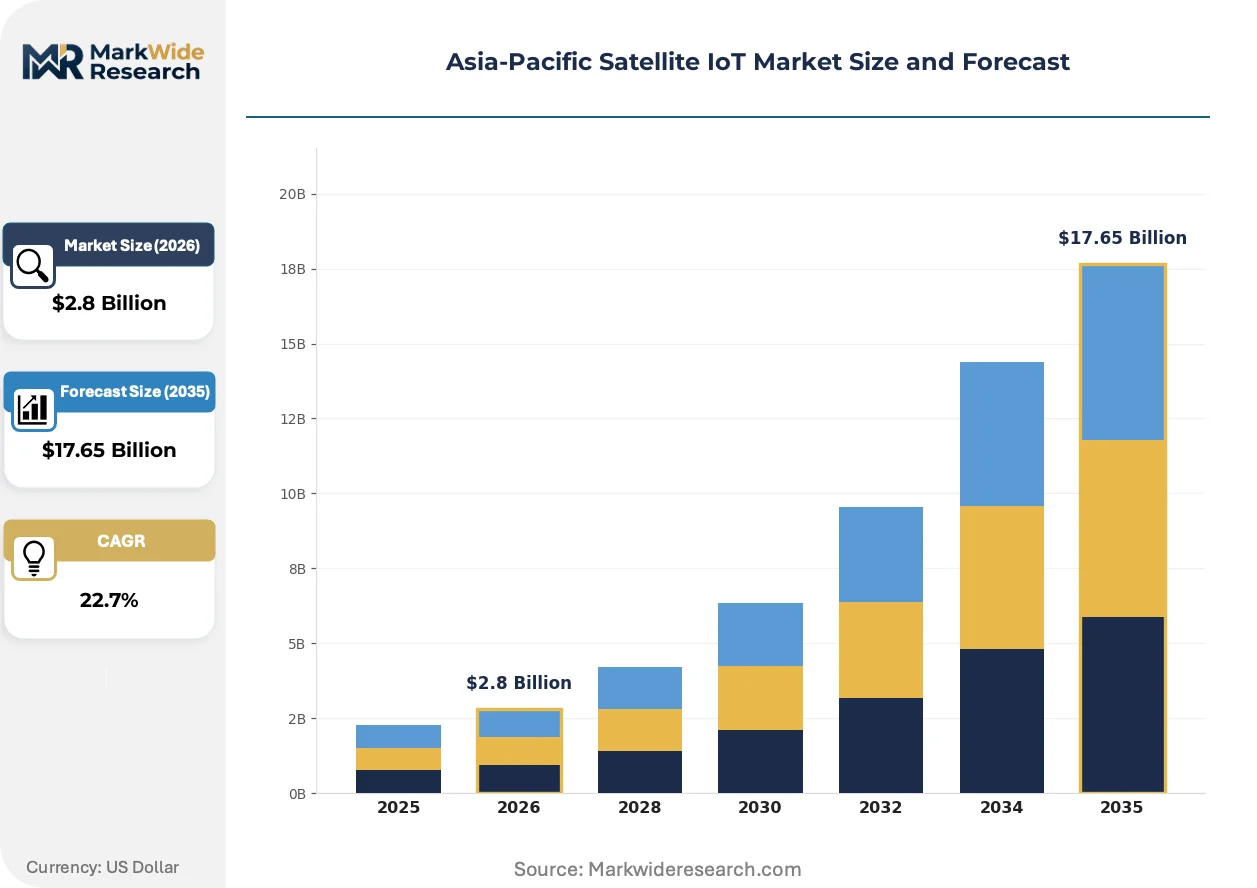
Market Dynamics
Maritime flag-state mandates for automatic identification and emissions reporting are forcing fleet retrofits across Southeast Asian shipping lanes, compressing procurement cycles and elevating terminal resilience specifications.
Growth Catalysts
- TRAI spectrum allocation framework:India's licensed operator entry rules for satellite-based narrowband services accelerate domestic constellation deployment and spectrum access for mainland IoT providers.
- Agricultural sensor grids:LPWAN satellite hybrids combine low-power endpoint economics with orbital backhaul across Indonesia and Vietnam, penetrating vegetation layers for remote telemetry collection.
- Remote mining corridors:Australia's ACMA device certification standards protect service quality in uneconomical terrestrial zones, concentrating demand in Pilbara and Queensland agricultural belts.
Market Restraints
- Orbital debris mitigation compliance:Cross-border data localization requirements fragment seamless coverage architectures, forcing constellation operators to replicate ground segment infrastructure.
- Terminal import barriers:Australia's ACMA certification filters non-compliant hardware, raising capital requirements for new LEO entrants seeking market access.
- Terrestrial cellular substitution:Expanding 4G/5G tower deployment along coastal Vietnam and Philippines shipping routes threatens maritime satellite attach rates on short-haul routes.
Strategic Opportunities
- Cloud-based platform aggregation:Multi-constellation data normalization creates margin concentration among software integrators serving Japanese port logistics systems.
- Defense-adjacent maritime contracts:NATO-equivalent resilience specifications open hardened terminal procurement channels across Australian and Japanese coastal surveillance networks.
- LPWAN-Satellite convergence:Low-power endpoint economics married to L-band backhaul unlock agricultural monitoring in Myanmar and Cambodia where fiber remains uneconomical.
Industry Challenges
- Multi-constellation integration complexity:Enterprise software systems struggle to normalize disparate data streams from government-backed LEO infrastructure and commercial operators.
- Certification timeline compression:ACMA and MIC device approval cycles lag constellation deployment schedules, delaying revenue recognition for new terminal designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite IoT Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.65 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LPWAN, Cellular, Satellite Communication, Mesh Network Application: Agriculture, Maritime, Environmental Monitoring, Asset Tracking End User: Smart Cities, Logistics, Healthcare, Energy Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | ORBCOMM Inc., Eutelsat Communications S.A., Iridium Communications Inc., Myriota Pty Ltd, Thales Group, Inmarsat Global Limited, SES S.A., China Aerospace Science and Technology Corporation, Globalstar, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite IoT Market Trends and Innovations
Satellite IoT architecture is compressing around three vectors: terminal form factor reduction, spectrum licensing fragmentation, and procurement model unbundling. Each vector reshapes competitive positioning differently.
LEO terminal hardware is miniaturizing through advanced gallium nitride power amplifiers and phased-array antenna designs. Australian mining operators now deploy palm-sized transponders on autonomous haul trucks previously requiring rack-mounted equipment. This compression is miniaturizing the addressable market for traditional VSAT integrators while expanding endpoint density per satellite beam.
MIIT in China and Japan's MIC are tightening national spectrum licensing regimes that determine which satellite operators may serve domestic IoT endpoints. These rules force constellation providers to establish in-country ground stations and data processing facilities. Defense and maritime segments absorb the compliance costs fastest, passing terminal premiums through to government contract pricing.
Enterprise buyers are unbundling hardware procurement from connectivity subscriptions, pressuring platform aggregators to compete on software integration depth. Japanese logistics conglomerates now source terminals directly from manufacturers while negotiating data plans through separate cloud-based aggregators. This bifurcation concentrates margin pressure on full-stack operators unable to demonstrate API normalization superiority.
Asia-Pacific Satellite IoT Market Segmentation
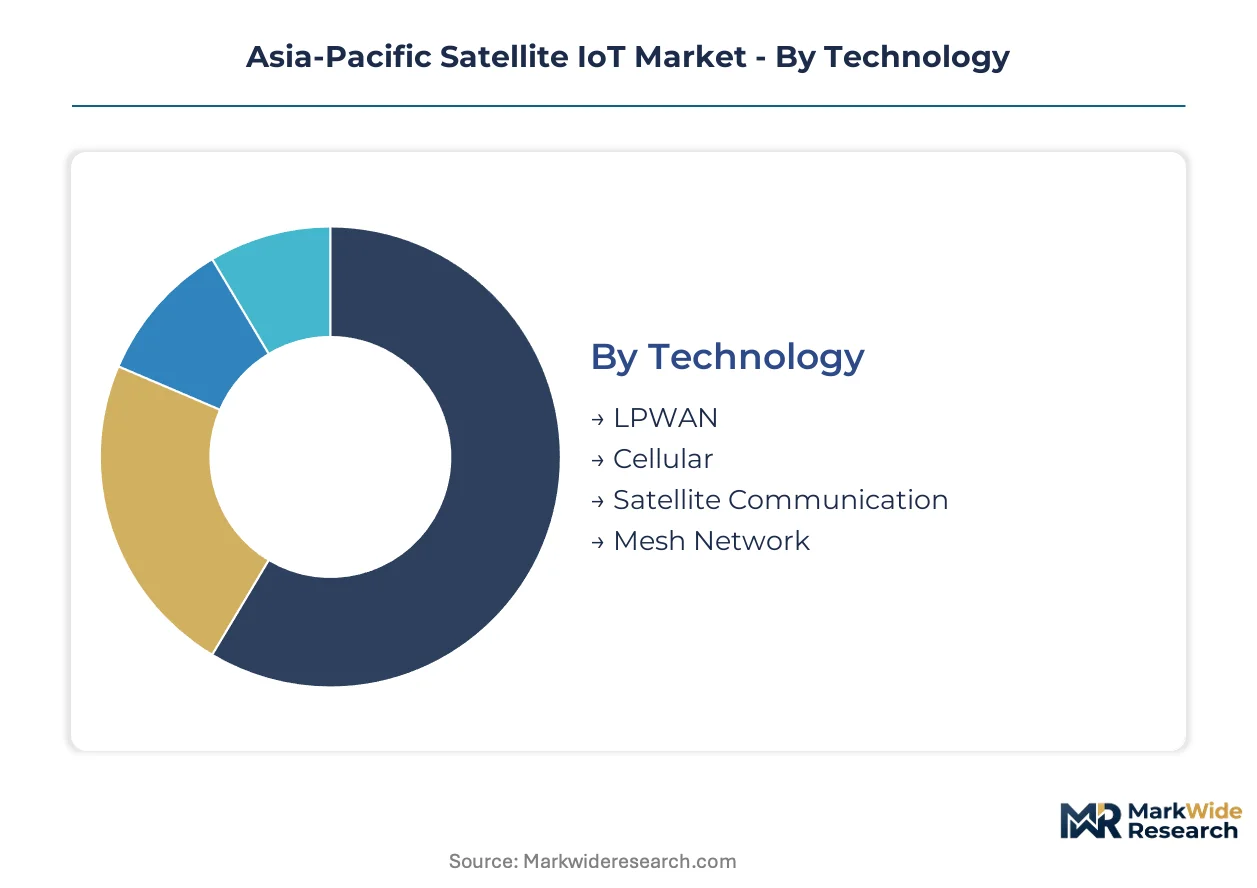
Technology substitution pressures reshape procurement patterns across Asia-Pacific satellite IoT deployments. Fleet operators and agricultural enterprises select connectivity architectures based on terrain penetration requirements, power budgets, and regulatory compliance costs rather than legacy compatibility.
Technology:
Cellular expansion along coastal Vietnam and Philippines shipping routes intensifies substitution pressure on satellite-dependent segments, forcing L-band providers to defend attach rates through hardened reliability guarantees.
- LPWAN:Low-power wide-area protocols combine sub-gigahertz unlicensed spectrum with satellite backhaul for agricultural sensor grids across Indonesia and Vietnam. Demand concentrates in palm oil plantations and rice paddies where cellular towers remain uneconomical and vegetation penetration dictates sub-1 GHz propagation.
- Satellite Communication:L-band and S-band transponders below 2.5 GHz deliver uninterrupted telemetry across oceanic, desert, and mountainous zones. Maritime fleet operators across Southeast Asian shipping lanes anchor procurement volume as flag-state mandates for automatic identification and emissions reporting compress retrofit cycles.
- Cellular:Terrestrial 4G/5G modules threaten short-haul maritime routes and coastal logistics corridors where tower density permits.
- Mesh Network:Self-healing node architectures extend coverage in underground mining operations across Australia's Pilbara region.
Satellite Communication anchors the volume base while LPWAN gains share at the steepest rate.
Application:
Cost tier differentiation separates premium defense-adjacent deployments from economy-grade agricultural monitoring, with maritime applications absorbing the widest pricing spread.
- Maritime:Vessel tracking and fuel optimization systems dominate Southeast Asian shipping lane deployments. Thai and Indonesian flag-state compliance deadlines force terminal upgrades on aging fleets operating Malacca Strait routes.
- Agriculture:Remote telemetry for soil moisture and livestock location concentrates in Australia's Queensland belts and Myanmar's delta regions where fiber deployment remains commercially unviable.
- Asset Tracking:Container and heavy equipment monitoring spreads through Japanese port logistics systems demanding API normalization across multi-constellation data streams.
- Environmental Monitoring:Bushfire and flood sensors deploy across Australia's Northern Territory under ACMA device certification frameworks that filter non-compliant terminal imports.
Maritime commands the premium pricing tier while Agriculture expands most quickly across previously unserved territories.
End User:
Customer type fragmentation concentrates procurement authority among platform aggregators serving conglomerates with multi-site monitoring requirements.
- Logistics:Japanese port systems and Southeast Asian freight corridors drive unbundled hardware and connectivity procurement, with enterprises sourcing terminals directly while negotiating data plans through cloud-based aggregators.
- Energy:Remote pipeline and wellhead monitoring across Australia's Cooper Basin and Indonesia's Natuna Sea fields demands NATO-equivalent resilience specifications for offshore platform safety systems.
- Smart Cities:Municipal sensor networks in Singapore and Seoul integrate satellite failover for critical infrastructure monitoring.
- Healthcare:Remote clinic connectivity and cold-chain pharmaceutical tracking spread through India's northeastern states under TRAI spectrum allocation frameworks.
Logistics anchors enterprise spending while Energy climbs the fastest on defense-adjacent contract premiums.
Deployment:
Margin concentration shifts toward software integrators as enterprise buyers unbundle hardware from connectivity subscriptions.
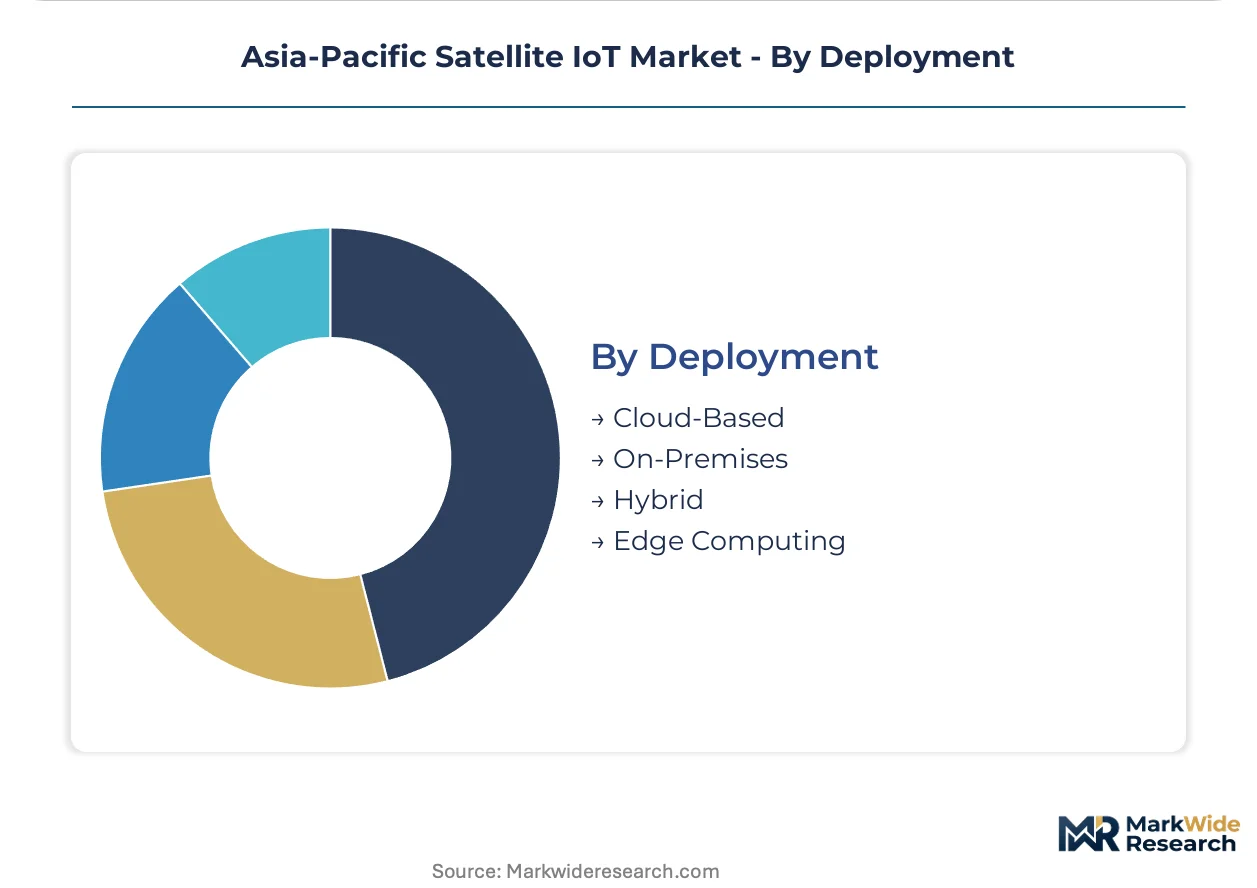
- Cloud-Based:Multi-constellation data normalization platforms aggregate disparate LEO and geostationary streams for enterprise software integration. Japanese logistics conglomerates favor this model for API-driven fleet management dashboards.
- Hybrid:Edge preprocessing with orbital backhaul suits Australian mining corridors where latency-sensitive autonomous haul truck operations coexist with batch telemetry uploads.
- On-Premises:Dedicated ground stations serve defense and coastal surveillance networks in Japan and Australia requiring data sovereignty guarantees.
- Edge Computing:Phased-array terminals with onboard processing reduce backhaul costs for high-frequency agricultural sensor grids.
Cloud-Based deployment captures the widest customer base while Hybrid architectures gain traction fastest in latency-critical industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground segment infrastructure concentrates in China, Japan, and Australia, where constellation operators maintain licensed earth stations and data processing facilities. National spectrum regimes fragment previously seamless orbital coverage across the region.
China
Domestic LEO constellation deployment accelerates under MIIT spectrum licensing frameworks that reserve S-band and L-band frequencies for government-backed operators. China Aerospace Science and Technology Corporation controls orbital slot access for mainland IoT providers. Yangtze River Delta manufacturing clusters produce miniaturized terminal hardware for agricultural sensor networks.
Japan
Defense-adjacent maritime contracts drive hardened terminal procurement across coastal surveillance networks. METI and MIC enforce national spectrum licensing that requires in-country ground stations for foreign constellation operators. Kanto region logistics conglomerates unbundle hardware sourcing from connectivity subscriptions through cloud-based aggregators.
India
TRAI spectrum allocation frameworks for satellite-based narrowband services accelerate licensed operator entry into remote clinic connectivity and cold-chain pharmaceutical tracking. Northeastern states deploy agricultural sensor grids where terrestrial fiber remains uneconomical. Delhi-NCR serves as the regulatory coordination hub for domestic constellation licensing.
Australia
ACMA device certification standards filter non-compliant terminal imports, protecting incumbent service quality in Pilbara mining corridors and Queensland agricultural belts. Remote telemetry demand concentrates where autonomous haul truck operations require hybrid edge-orbital architectures. Perth anchors ground segment infrastructure for Indian Ocean coverage.
Vietnam
Coastal 4G/5G tower deployment intensifies substitution pressure on satellite-dependent maritime routes. LPWAN-satellite hybrids penetrate Mekong Delta rice paddies for soil moisture monitoring. Ho Chi Minh City logistics operators retrofit fleets for flag-state emissions reporting compliance.
Asia-Pacific Satellite IoT Market Competitive Landscape
Concentration sits with full-stack constellation operators and defense-integrated terminal manufacturers. The vendor base spans three tiers: government-backed LEO infrastructure controllers, commercial satellite service providers with legacy maritime protocols, and cloud-native platform aggregators normalizing multi-constellation data streams. Strategic differentiation hinges on spectrum license depth, terminal certification velocity, and API integration sophistication. Competitive moves center on national ground station partnerships and unbundled procurement model adoption.
Among defense-integrated manufacturers, Thales Group exemplifies NATO-equivalent resilience specification anchoring. Within commercial satellite services, ORBCOMM Inc. and Iridium Communications Inc. occupy positions shaped by legacy asset-tracking protocol retention and global LEO constellation coverage. Myriota Pty Ltd represents the cloud-native platform archetype, sitting within the Australian ecosystem where low-power endpoint economics merge with orbital backhaul specialization.
| Leading Market Players |
|---|
| ORBCOMM Inc. |
| Eutelsat Communications S.A. |
| Iridium Communications Inc. |
| Myriota Pty Ltd |
| Thales Group |
| Inmarsat Global Limited |
| SES S.A. |
| China Aerospace Science and Technology Corporation |
| Globalstar, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cellular substitution along Vietnam and Philippines coastal corridors simultaneously compresses L-band satellite pricing premiums and redirects supply chain investment toward miniaturized terminal fabrication in Yangtze River Delta clusters. This substitution dynamic forces constellation operators to absorb certification costs while passing residual hardware premiums through defense-adjacent maritime contracts.
Pricing Analysis
ACMA and MIC device certification frameworks dictate the pricing tier structure across Australian and Japanese deployments. Three-tier pricing structure across premium, standard, and economy levels separates NATO-equivalent hardened terminals from commercial-grade maritime units and agricultural sensor endpoints. Price differentiation rests on certification velocity and spectrum license depth rather than hardware performance alone. Pricing pressure stems from cloud-based platform aggregators unbundling connectivity from hardware procurement. Agricultural sensor grid operators in Indonesia and Vietnam exhibit the highest price sensitivity, while Japanese defense-adjacent maritime buyers absorb terminal premiums with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of gallium nitride power amplifiers and phased-array components dominates inventory strategy as lead times for satellite-grade semiconductors extend. Manufacturing concentrates in China, Japan, and South Korea, with Yangtze River Delta fabs producing miniaturized LEO transponders and Kanto-region facilities handling defense-grade terminal assembly. Raw material dependencies include rare earth elements for antenna substrates, gallium nitride for power amplification, and specialized ceramics for thermal management. Single-source vulnerability in MIIT-licensed spectrum access creates structural risk for foreign constellation operators seeking mainland China market entry. Distribution runs through licensed ground station operators and cloud-based platform aggregators serving enterprise fleet management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around unbundled procurement models as Japanese logistics conglomerates separate terminal sourcing from connectivity subscriptions, creating niches for specialized hardware manufacturers and independent data aggregators.
For Market Incumbents: Secure national spectrum licenses through in-country ground station partnerships before MIIT and MIC tighten foreign operator access rules. Deepen backward integration into gallium nitride power amplifier supply chains to defend margin position against Yangtze River Delta cost competition. Lock long-term terminal certification contracts with ACMA and MIC to delay new LEO entrant revenue recognition. For New Entrants and Emerging Players: Differentiate on API normalization depth for multi-constellation data streams serving Japanese port logistics systems. Target Myanmar and Cambodian agricultural corridors where LPWAN-satellite hybrids face minimal cellular substitution pressure. Pursue cloud-native platform aggregation partnerships with Australian mining operators seeking hybrid edge-orbital architectures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial satellite service providers holding legacy maritime protocols but lacking cloud integration capabilities. Five-to-ten year viability hinges on successful unbundling transition from full-stack operators to platform-agnostic data aggregators. Watch for inflection when ACMA and MIC certification timelines compress below eighteen months, signaling new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum License Acquisition | MIIT and MIC national licensing reserves L-band access for government-backed operators controlling mainland market entry. |
| Terminal Miniaturization Investment | Gallium nitride power amplifiers enable palm-sized transponders for Australian autonomous haul truck deployments. |
| Cloud Platform Integration | API normalization across ORBCOMM and Iridium data streams serves Japanese logistics conglomerate procurement requirements. |
| Defense-Adjacent Certification | NATO-equivalent resilience specifications open hardened terminal procurement channels across Australian coastal surveillance networks. |
| Ground Station Partnership | In-country data processing facilities satisfy TRAI spectrum allocation requirements for Indian remote clinic connectivity deployments. |
Research Methodology
A standing panel of constellation operations directors, maritime fleet procurement managers, ACMA certification engineers, and cloud platform integration specialists provided ongoing calibration across the study period. Primary interviews with terminal manufacturers in Yangtze River Delta clusters and logistics procurement leads in Kanto region conglomerates combined with secondary validation from MIIT spectrum filings, TRAI licensing announcements, and ACMA device certification databases. Bottom-up endpoint deployment estimates triangulated against top-down constellation capacity models derived from orbital slot filings and transponder specifications.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology substitution dynamics, application tier pricing spreads, end-user procurement authority fragmentation, and deployment architecture margin concentration. CAGRs were derived from fitted growth curves applied to segment-level endpoint penetration rates and average revenue per unit trajectories. Industry-specific forecast inputs included maritime flag-state compliance deadline clustering and agricultural sensor grid payback period sensitivity.
Material uncertainties — orbital debris mitigation rule tightening, cross-border data localization enforcement, and terrestrial cellular tower expansion along coastal shipping routes — sit outside the modeled envelope. Forecasts reflect assumptions regarding spectrum license continuity and certification timeline stability. Revision becomes warranted when cellular substitution rates on short-haul maritime routes exceed modeled thresholds or when national ground station establishment requirements fragment previously seamless coverage architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
United States Satellite Communications Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Satellite Imaging Market
Satellite
Tactical Satellite Market
Satellite
Global Broadband Satellite Services Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Russia Satellite Communications Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
UAE Satellite Communication Market
Satellite
Earth Observation Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Japan Satellite-Based Earth Observation Market