
 Italy Satellite Imagery Services Market | 2026-2036
Italy Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Satellite Imagery Services Market Insights
Market Context with Strategic Players
Multi-source procurement is recalibrating how Italian government and commercial buyers acquire geospatial intelligence. e-GEOS leverages its COSMO-SkyMed constellation access to dominate domestic radar imagery supply. Planetek Italia s.r.l. specializes in value-added analytics for environmental and infrastructure monitoring. Leonardo S.p.A. anchors the defense segment through integrated satellite communications and Earth observation systems.
Technical Definition and Structural Segments
Italy satellite imagery services encompass the acquisition, processing, and distribution of Earth observation data from orbiting platforms, spanning spatial resolutions from sub-meter panchromatic to multispectral bands at 10-30 meter ground sample distance, primarily serving precision agriculture, infrastructure integrity assessment, and territorial security applications. Optical and radar product types capture divergent margin profiles, with synthetic aperture radar sustaining premium pricing for all-weather, day-night operational continuity while hyperspectral remains nascent in commercial uptake. Cloud-based delivery mode is displacing on-premise installations among mid-tier agricultural users, though defense and critical infrastructure accounts retain hybrid architectures for data sovereignty compliance.
Regulatory Framework and Forward Outlook
The EU Space Programme and Italy's National Recovery and Resilience Plan shape procurement frameworks, while ESA Earth observation directives and national security classifications govern data dissemination tiers. GDPR provisions intersect with geospatial privacy, constraining street-level and property-specific imagery commercialization without explicit consent protocols. Stakeholders must monitor Copernicus downstream service mandates and evolving military-civil dual-use export controls to anticipate access restrictions and funding eligibility shifts.
Market Dynamics
EU Space Programme mandates are compressing procurement timelines for Italian government buyers while Copernicus downstream service obligations force domestic commercialization of satellite data assets.
Growth Catalysts
- Copernicus downstream mandates:EU regulations require member states to commercialize Earth observation data, creating structured revenue pathways for Italian service providers.
- Precision agriculture digitization:Northern Italy's Po Valley farming cooperatives are integrating sub-meter optical imagery with variable-rate application equipment.
- Maritime domain awareness:Italian Navy and Coast Guard procurement of synthetic aperture radar sustains demand for all-weather surveillance capabilities.
Market Restraints
- Launch cost volatility:Ariane and SpaceX pricing fluctuations compress margins for constellation-dependent service providers.
- GDPR geospatial constraints:Italian data protection authority interpretations limit street-level imagery commercialization without explicit property owner consent.
- Optical weather dependency:Persistent cloud cover over Alpine and Apennine regions degrades optical product reliability for infrastructure monitoring clients.
Strategic Opportunities
- Southern Italy agricultural extension:Puglia and Sicily farming regions remain underpenetrated for precision agriculture analytics services.
- AI-EO convergence:Machine learning pipelines for automated change detection are opening subscription-based analytics tiers for mid-market infrastructure operators.
- Green Deal carbon monitoring:EU funding mechanisms for land-use verification create new revenue streams for forest and soil carbon assessment services.
Industry Challenges
- Geospatial data science talent scarcity:Italian universities produce insufficient remote sensing specialists to match service provider hiring needs.
- Dual-use export licensing:Military-civil classification ambiguities delay international contract execution for radar imagery with sub-meter resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Satellite Imagery Services Market |
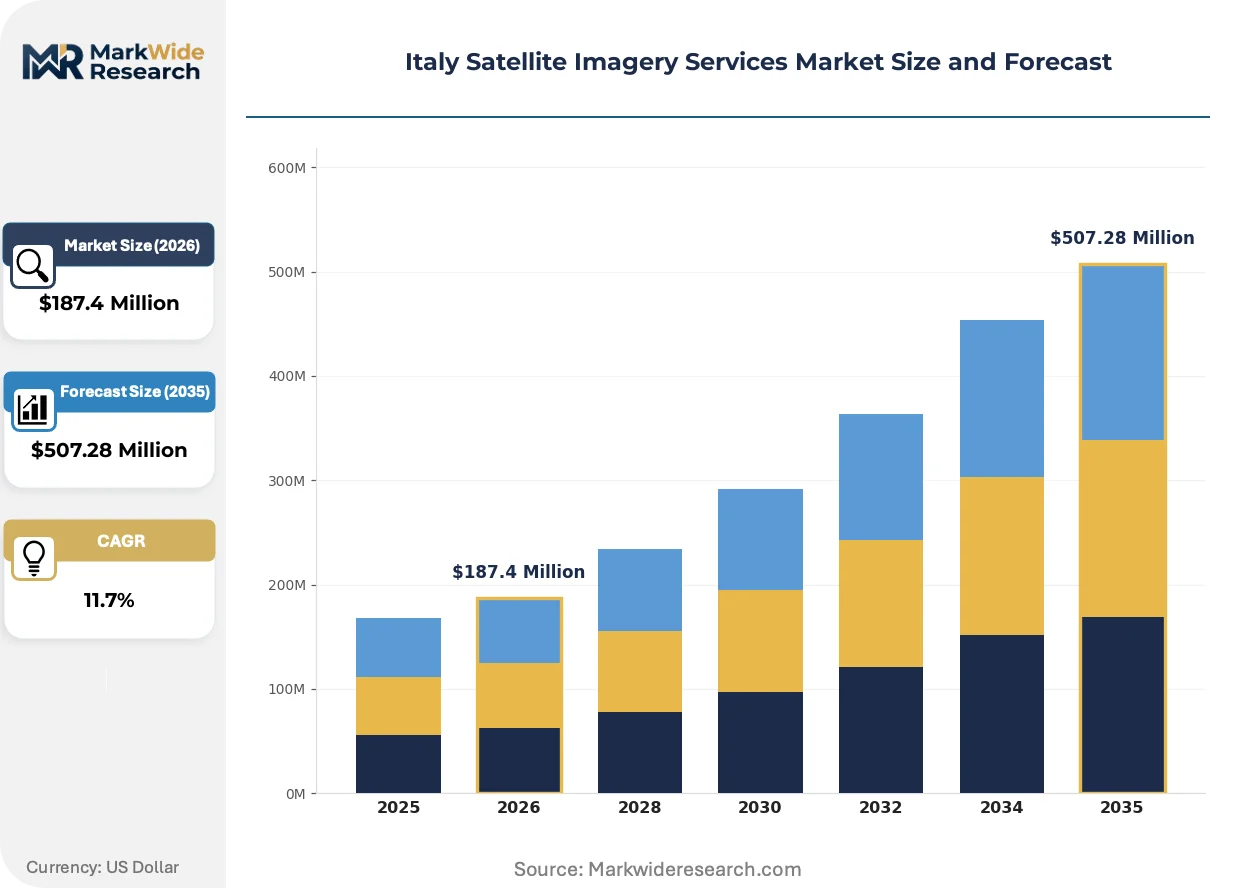
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Radar, Hyperspectral, 3D Mapping End User: Agriculture, Environmental Monitoring, Urban Planning, Defense Delivery Mode: Cloud-based, On-premise, Hybrid, API Access Application: Disaster Management, Infrastructure Monitoring, Land Use Analysis, Climate Research |
| Companies Covered | Thales Alenia Space, e-GEOS, Airbus, Maxar Technologies, Viasat Group S.p.A, Planetek Italia s.r.l, OHB-Italia S.p.A, L3Harris Technologies, Leonardo S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Satellite Imagery Services Market Trends and Innovations
Cloud-native architectures are compressing delivery timelines while AI inference at the edge is redistributing computational workloads across the value chain.
Sensor fusion platforms are unifying optical, radar, and AIS maritime tracking data into single-workflow analytics products. Port authorities and logistics operators in Genoa and Trieste are adopting these integrated feeds for supply chain visibility. This convergence is unifying previously separate procurement budgets for imagery and vessel tracking into consolidated service contracts.
Italy's National Recovery and Resilience Plan allocates dedicated funding streams for Earth observation infrastructure modernization. Public research institutions must now partner with commercial entities for data processing and distribution. The defense and environmental monitoring segments are restructuring procurement specifications to align with these co-funding eligibility requirements.
Subscription-based API access is displacing traditional scene-based purchasing for agricultural technology vendors. Drone imagery providers in Emilia-Romagna are bundling satellite feeds into precision farming software packages. This bundling behavior concentrates most visibly among mid-scale cooperatives managing 500-2,000 hectare operations.
Italy Satellite Imagery Services Market Segmentation
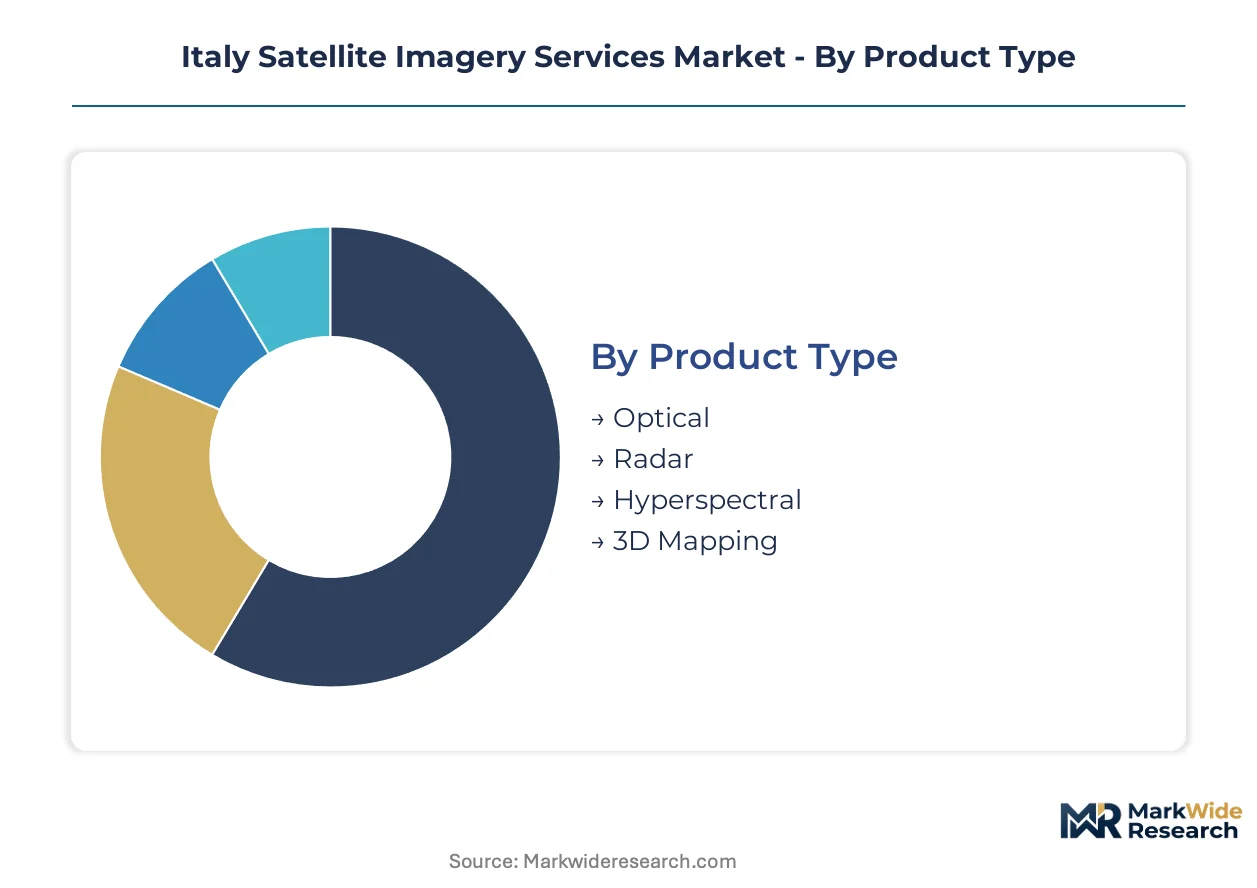
Segmentation reveals how capital requirements and procurement patterns diverge across Italy's satellite imagery value chain. Defense and environmental agencies drive premium-tier spending while agricultural cooperatives reshape mid-market delivery economics.
Product Type:
Capital intensity varies sharply across sensor technologies, with radar constellation ownership demanding sustained investment versus optical licensing arrangements.
- Optical:Panchromatic and multispectral sensors capture reflected sunlight across visible to near-infrared wavelengths, achieving sub-meter resolution for infrastructure inspection. Northern Italy's Po Valley precision agriculture cooperatives absorb the bulk of commercial demand, though persistent Alpine cloud cover constrains operational reliability.
- Radar:Synthetic aperture radar transmits microwave pulses enabling all-weather, day-night imaging regardless of atmospheric conditions. Italian Navy and Coast Guard procurement for maritime domain awareness in the Mediterranean sustains premium pricing, while dual-use export licensing under EU regulations complicates international contract execution.
- Hyperspectral:Narrow spectral band imaging detects subtle biochemical signatures for vegetation stress and mineral identification.
- 3D Mapping:Stereo pair and interferometric processing generates digital elevation models for infrastructure engineering and flood risk assessment.
Radar absorbs the bulk of installed capacity for defense applications; optical is expanding most quickly through agricultural technology vendor partnerships.
End User:
Customer procurement sophistication determines service tier access, with defense accounts commanding dedicated ground segment infrastructure versus standardized agricultural subscriptions.
- Agriculture:Variable-rate application equipment integration drives demand for sub-meter optical imagery across Northern Italy's farming heartland. Emilia-Romagna cooperatives managing 500-2,000 hectare operations are consolidating procurement through bundled drone-satellite software packages.
- Environmental Monitoring:EU Green Deal carbon verification mandates and forest health surveillance create structured funding pathways through Italy's National Recovery and Resilience Plan.
- Urban Planning:Municipal authorities in Rome and Milan utilize medium-resolution archives for land-use change detection and informal settlement monitoring.
- Defense:Border surveillance and maritime domain awareness requirements sustain classified procurement channels with stringent data sovereignty protocols.
Defense commands the highest per-contract value; agriculture is gaining share fastest through cooperative digitization initiatives.
Delivery Mode:
Deployment architecture choices reflect data sovereignty requirements and computational resource constraints across customer segments.
- Cloud-based:Scalable storage and processing infrastructure enables mid-tier agricultural users to access historical archives without capital expenditure. GDPR compliance frameworks govern Italian data residency requirements for sensitive territorial imagery.
- On-premise:Dedicated ground stations and local processing hardware serve defense and critical infrastructure operators with classified or commercially sensitive workflows.
- Hybrid:Tiered architectures route routine processing to cloud infrastructure while retaining sensitive analytics on sovereign hardware.
- API Access:Programmatic data retrieval interfaces enable precision agriculture software vendors to embed satellite feeds within existing farm management platforms.
Cloud-based deployment holds the majority of new contract volume; API access is climbing the fastest through agricultural technology integration partnerships.
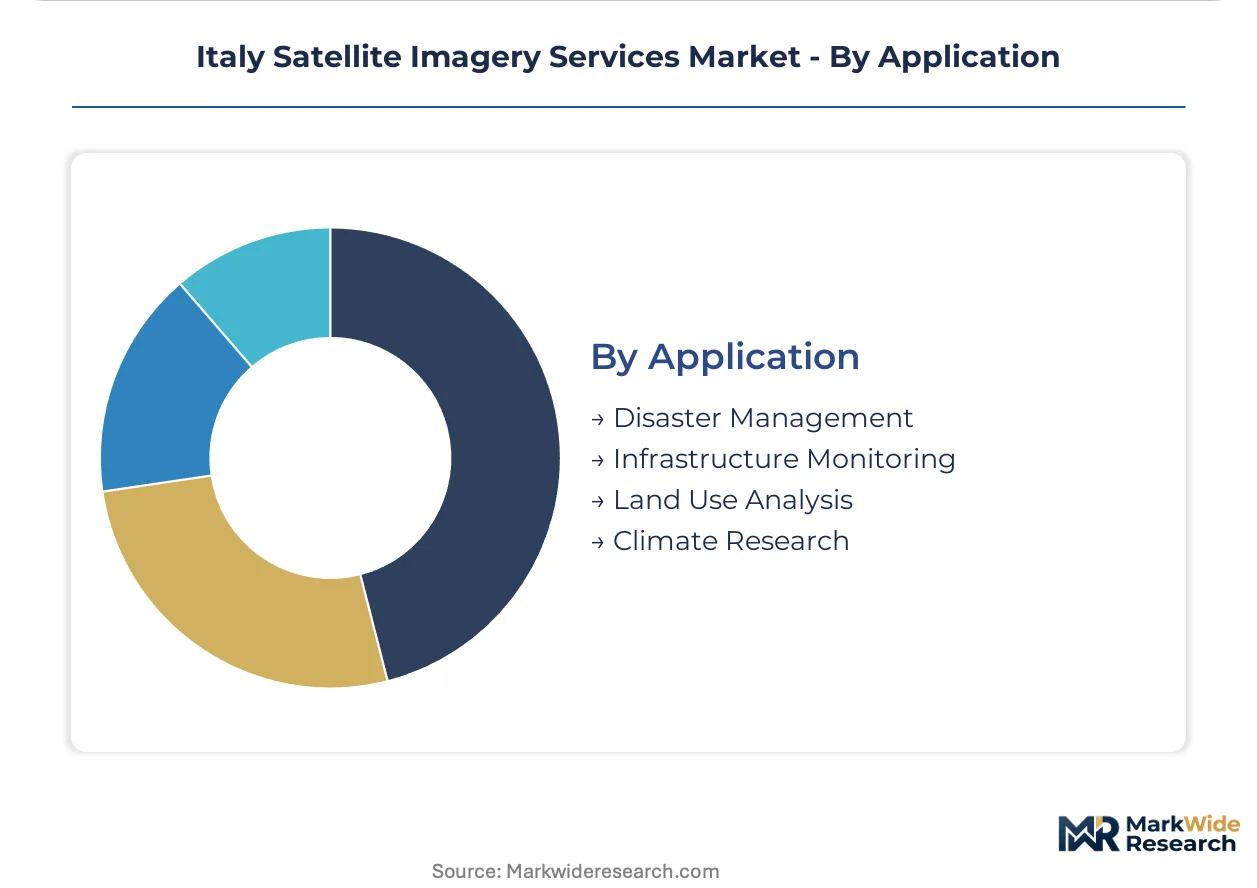
Application:
Use case complexity determines analytics depth requirements, from automated change detection to multi-source sensor fusion.
- Disaster Management:Rapid damage assessment following seismic events and flooding demands all-weather radar availability plus pre-event baseline archives. Italy's civil protection agency maintains standing contracts with domestic providers for Mediterranean earthquake and landslide response.
- Infrastructure Monitoring:Bridge deformation, railway settlement, and pipeline integrity assessment utilize interferometric SAR for millimetric displacement measurement. Alpine tunnel construction projects in Piedmont and Lombardy generate sustained demand for subsidence tracking.
- Land Use Analysis:Agricultural subsidy verification and urban sprawl monitoring leverage medium-resolution multispectral time series.
- Climate Research:Long-term glacier retreat and coastal erosion studies require calibrated archival continuity across satellite generations.
Infrastructure monitoring captures the largest dedicated budget allocation; disaster management is expanding most quickly through civil protection procurement modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Po Valley's agricultural heartland and Rome's aerospace cluster anchor Italy's satellite imagery demand geography, with procurement patterns diverging sharply between Northern precision farming cooperatives and Central government defense installations.
Lombardy
Milan's financial services sector drives commercial geospatial analytics adoption for real estate portfolio risk assessment. Italy's National Recovery and Resilience Plan directs Earth observation infrastructure funding through Lombardy-based research consortia. The Alpine corridor between Bergamo and Brescia concentrates interferometric SAR demand for tunnel construction subsidence monitoring.
Emilia-Romagna
Agricultural cooperatives managing 500-2,000 hectare operations in the Po Delta integrate sub-meter optical imagery with variable-rate fertilizer equipment. The region's drone imagery providers bundle satellite feeds into precision farming software under EU Common Agricultural Policy digitization mandates. Bologna's aerospace engineering cluster supports downstream analytics development for environmental monitoring applications.
Lazio
Rome hosts Italy's civil protection agency and defense procurement headquarters, sustaining classified contracts for Mediterranean maritime domain awareness. The EU Space Programme's Copernicus downstream service obligations channel commercialization requirements through Lazio-based public-private partnerships. Frascati's ESRIN facility anchors European Space Agency Earth observation data processing infrastructure serving Italian government buyers.
Piedmont
Turin's automotive supply chain generates infrastructure monitoring demand for factory site expansion and logistics corridor planning. Alpine tunnel projects through the Mont Blanc and Frejus corridors require millimetric displacement tracking via persistent radar coverage. The region's polytechnic university produces remote sensing specialists for national service provider hiring pipelines.
Sicily
Puglia and Sicily farming regions remain underpenetrated for precision agriculture analytics, presenting extension opportunities for subscription-based API services. The Italian Navy's Augusta naval base sustains synthetic aperture radar procurement for Mediterranean surveillance operations. Catania's space technology incubator hosts startups developing AI-EO convergence applications for volcanic risk assessment.
Italy Satellite Imagery Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as domestic providers secure constellation access agreements and foreign operators establish Italian distribution channels. The vendor base stratifies across three tiers: constellation owners with direct sensor control, licensed resellers with value-added processing capabilities, and pure-play analytics firms. Two archetypes define competitive positioning — radar specialists leveraging COSMO-SkyMed access and optical aggregators bundling multi-source archives. Partnership formation and API-based service integration represent the dominant competitive vectors reshaping procurement relationships.
Among Italy-based service providers, e-GEOS occupies a position representing constellation-access archetypes through its COSMO-SkyMed ground segment control, while Planetek Italia s.r.l. exemplifies the value-added analytics tier specializing in environmental and infrastructure monitoring applications. Leonardo S.p.A. anchors the defense-integrated systems segment. Foreign operators including Thales Alenia Space and Airbus represent pan-European satellite manufacturing and service provision, with Thales Alenia Space's Italian origins situating it within domestic procurement preference frameworks. These named entities collectively illustrate how competitive positioning depends on sensor access depth, processing specialization, and defense-civil market straddling capability.
| Leading Market Players |
|---|
| Thales Alenia Space |
| e-GEOS |
| Airbus |
| Maxar Technologies |
| Viasat Group S.p.A |
| Planetek Italia s.r.l |
| OHB-Italia S.p.A |
| L3Harris Technologies |
| Leonardo S.p.A. |
| Others |
Pricing and Supply Chain Analysis
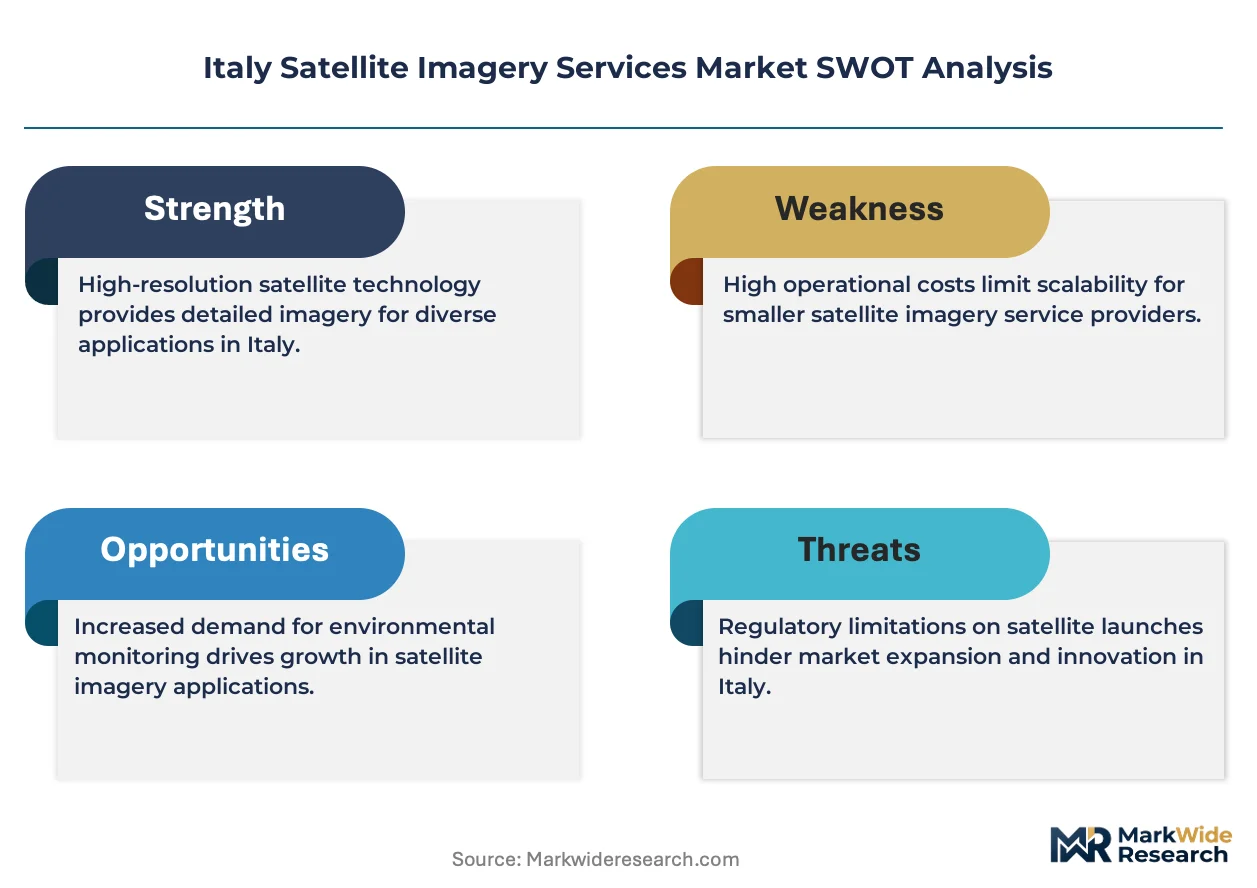
Sovereign-backed satellite operators and defense-integrated conglomerates anchor Italy's imagery supply base, compressing pricing discipline through captive constellation access while private analytics specialists compete on value-added processing margins.
Pricing Analysis
Ground segment maintenance and data processing warranties bundle into premium radar subscriptions, while unbundled optical scene purchases expose buyers to weather-cancellation risk. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade sub-meter SAR with dedicated ground stations from agricultural API access and archival browse products. Price differentiation rests on resolution grade and sovereign data residency certification. Cost compression in optical licensing intensifies as foreign operators flood Italian distribution channels. Agricultural cooperatives exhibit highest price sensitivity; defense accounts accept premium tiers for classification-compliant infrastructure.
Supply Chain Analysis
Direct-to-defense channels handle classified procurement through Rome's aerospace cluster, while API aggregators serve mid-tier agricultural technology vendors. Satellite manufacturing concentrates in France, Germany, and Italy through Thales Alenia Space and OHB-Italia facilities. Raw material dependencies span gallium arsenide semiconductors, specialized optical glass, and radiation-hardened electronics. Single-source vulnerability in synthetic aperture radar componentry from German suppliers exposes domestic providers to export licensing delays. Distribution runs through constellation owners, licensed resellers, and pure-play analytics firms in stratified downstream tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's satellite imagery services sector is consolidating as EU Copernicus commercialization mandates and defense procurement centralization squeeze sub-scale analytics providers without constellation access or AI-EO development pipelines.
For Market Incumbents: Deploy API-first platform architecture to lock in agricultural technology vendor partnerships before foreign operators establish Italian distribution dominance. Secure exclusive COSMO-SkyMed ground segment expansion rights through Telespazio shareholder structures. Counter emerging hyperspectral specialists by integrating sensor fusion capabilities for port authority and logistics operator contracts in Genoa and Trieste. For New Entrants and Emerging Players: Capture Southern Italy precision agriculture extension opportunities in Puglia and Sicily farming regions where subscription penetration lags Northern cooperatives by several adoption cycles. Target carbon verification analytics under EU Green Deal land-use verification mandates, where public funding eligibility creates structured procurement pathways. Pursue white-label AI-EO convergence partnerships with Emilia-Romagna drone imagery providers seeking satellite feed bundling capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor value-added analytics specialists with established environmental monitoring contracts and National Recovery and Resilience Plan co-funding eligibility in Lazio and Emilia-Romagna. Long-term viability hinges on AI inference pipeline ownership and defense-civil dual-use licensing clearance. Watch for Copernicus downstream service obligation enforcement intensity as inflection indicator for domestic commercialization revenue quality.| Strategic Initiative | Industry Significance |
|---|---|
| Constellation Access Partnership | e-GEOS leverages Telespazio shareholder ties to secure COSMO-SkyMed ground segment exclusivity for Italian defense contracts. |
| AI-EO Convergence Development | Automated change detection pipelines open subscription tiers for mid-market infrastructure operators in Alpine tunnel projects. |
| API Platform Integration | Programmatic data retrieval embeds satellite feeds within Emilia-Romagna precision farming software packages. |
| Sensor Fusion Capability Buildout | Unified optical-radar-AIS feeds consolidate procurement budgets for Genoa and Trieste port authorities. |
| Green Deal Carbon Verification Positioning | Forest and soil carbon assessment services tap EU funding mechanisms for land-use verification mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Italy satellite imagery services assessment. Primary interviews with Earth observation procurement officers at defense agencies, precision agriculture technology vendors, and environmental monitoring consortium directors combined with ESA Earth observation directives, EU Space Programme documentation, and Italy's National Recovery and Resilience Plan implementation reports. Bottom-up segment sizing across radar, optical, and hyperspectral product categories triangulated against top-down market value reconstruction from constellation operator revenue disclosures and licensed reseller distribution estimates.
Granularity-level modeling distinguished defense-classified, environmental monitoring, and agricultural end-use segments across cloud-based, on-premise, hybrid, and API delivery architectures. CAGRs derived from historical procurement trend extrapolation adjusted for Copernicus downstream mandate enforcement timelines and dual-use export licensing processing delays. Synthetic aperture radar capacity expansion schedules, optical weather-dependency degradation factors for Alpine regions, and AI-EO convergence adoption curves in precision agriculture informed projection sensitivity ranges across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU defense procurement centralization pace and GDPR geospatial privacy interpretation shifts. Periodic stress-testing of base assumptions is recommended given launch cost volatility from Ariane and SpaceX pricing fluctuations and emerging hyperspectral commercialization trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite IoT Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Russia Satellite Communications Market
Satellite
Satellite Signal Meter Market
Satellite
Tactical Satellite Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Europe Small Satellite Market
Satellite
France Satellite Connectivity Market
Satellite
4K Satellite Broadcasting Market
Satellite
Satellite Communications Service Market
Satellite
Canada Satellite Connectivity Market
Satellite
Satellite Transponder Market
Satellite
Europe Satellite Attitude and Orbit Control System Market