
 GCC Aircraft MRO Market | 2026-2036
GCC Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Aircraft MRO Market Foresight
Saudi Arabia's aviation infrastructure expansion is rewriting regional MRO capacity maps as the Kingdom develops King Salman International Airport into a maintenance hub. Emirates Engineering leverages its Dubai facilities to dominate wide-body base maintenance across the Gulf. Saudia Aerospace Engineering Industries anchors engine overhaul demand from Riyadh's expanding fleet base. Lufthansa Technik Middle East competes through specialized component repair for European-registered aircraft operating GCC routes.
GCC Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and avionics systems to maintain regulatory airworthiness and operational reliability, typically requiring adherence to 4,000-6,000 flight hour cycle limits for heavy maintenance checks. The primary purpose is ensuring continuous fleet availability while extending asset economic life through certified restoration processes. Engine overhaul commands premium margin pools due to specialized tooling requirements and OEM intellectual property constraints. Base maintenance absorbs the largest volume share as aging regional and commercial jet fleets require structural inspections and corrosion prevention programs. Component repair exhibits the fastest trajectory as airlines outsource non-core capabilities to third-party specialists.
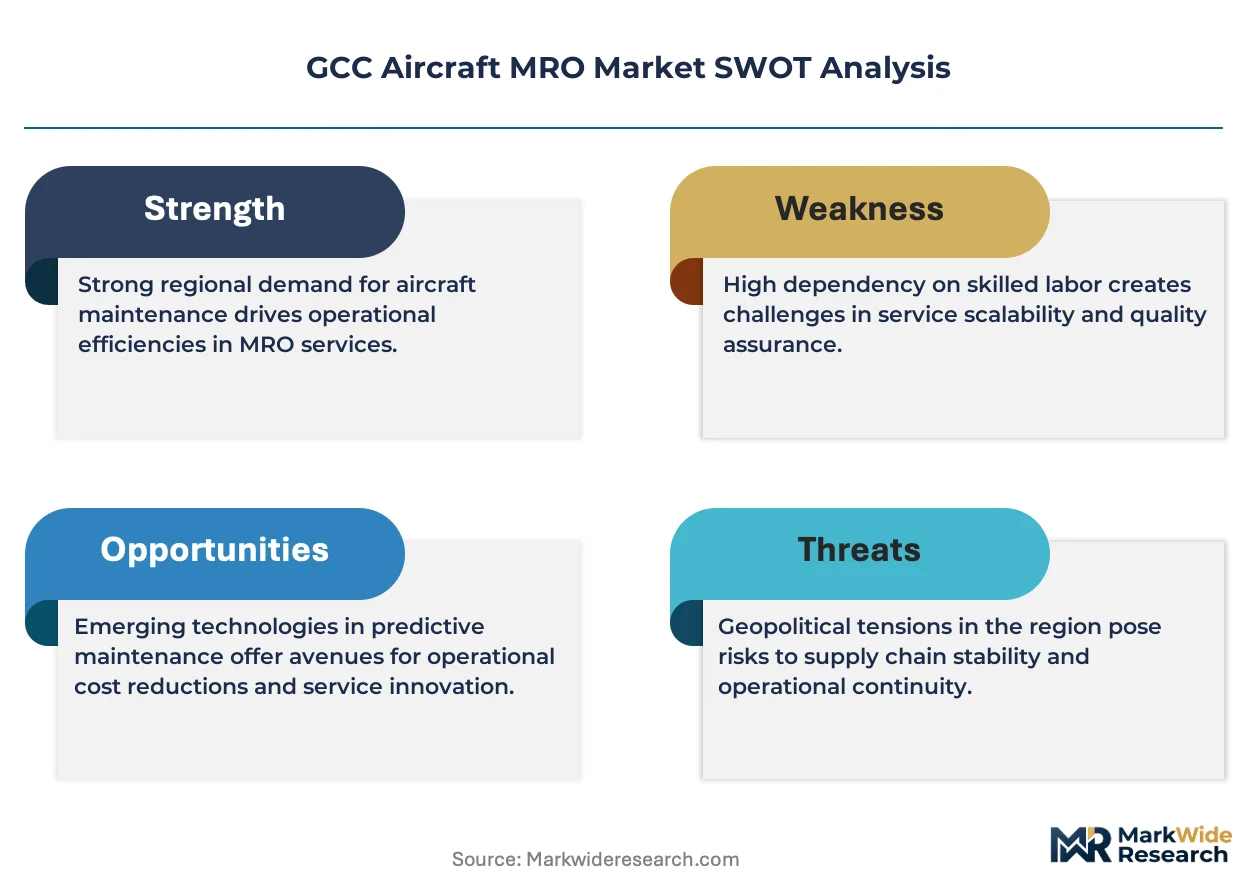
GCAA, GACA, and QCAA airworthiness frameworks mandate continuous compliance with ICAO Annex 6 standards, forcing MRO providers to invest in digital record-keeping and technician certification programs. EASA and FAA bilateral recognition agreements shape market access for European and American-registered aircraft undergoing maintenance in Gulf facilities. Stakeholders must monitor predictive maintenance technology maturation and regulatory convergence decisions that will determine whether integrated MRO solutions displace fragmented service models across the six Gulf states.
Market Dynamics
Regulatory harmonization across GCAA, GACA, and QCAA frameworks is compressing certification timelines and forcing MRO providers to consolidate digital compliance infrastructure around unified airworthiness standards.
Growth Catalysts
- Wide-body fleet accumulation:Saudi Arabia, the UAE, and Qatar are absorbing new aircraft deliveries that trigger mandatory heavy maintenance cycles at 4,000-6,000 flight hour intervals.
- Predictive maintenance platforms:ICAO Annex 6 compliance mandates are accelerating sensor-based health monitoring adoption across engine overhaul and base maintenance operations.
- Airport zone clustering:Dubai, Jeddah, and Doha maintenance corridors concentrate specialized tooling infrastructure and certified technician pools within bonded logistics perimeters.
Market Restraints
- OEM intellectual property lock-in:Engine overhaul providers face restricted access to proprietary diagnostic protocols and specialized tooling controlled by original equipment manufacturers.
- Specialized labor scarcity:EASA and FAA bilateral certification requirements limit the pool of qualified airframe and powerplant technicians eligible for Gulf facility employment.
- Input cost volatility:Aerospace-grade alloys and avionics component sourcing exposes MRO margins to commodity price fluctuations and extended procurement lead times.
Strategic Opportunities
- Component repair specialization:Airlines are outsourcing non-core capabilities to third-party specialists, creating white space for independent shops focused on avionics and landing gear systems.
- Corrosion prevention programs:Aging regional jet fleets in Kuwait and Bahrain require accelerated structural inspection protocols that base maintenance providers can capture.
- Digital record-keeping convergence:Unified compliance platforms across GCAA, GACA, and QCAA jurisdictions enable integrated MRO solutions to displace fragmented service models.
Industry Challenges
- Technician certification pipeline:EASA Part-66 and FAA Airframe & Powerplant credentialing programs face throughput constraints that lag behind facility expansion timelines.
- Legacy system integration:Predictive maintenance platforms must interface with existing maintenance management software, creating data standardization and API compatibility friction.
- Heavy maintenance hangar utilization:Wide-body base maintenance requires extended aircraft downtime that strains slot allocation and revenue per square meter metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Aircraft MRO Market |
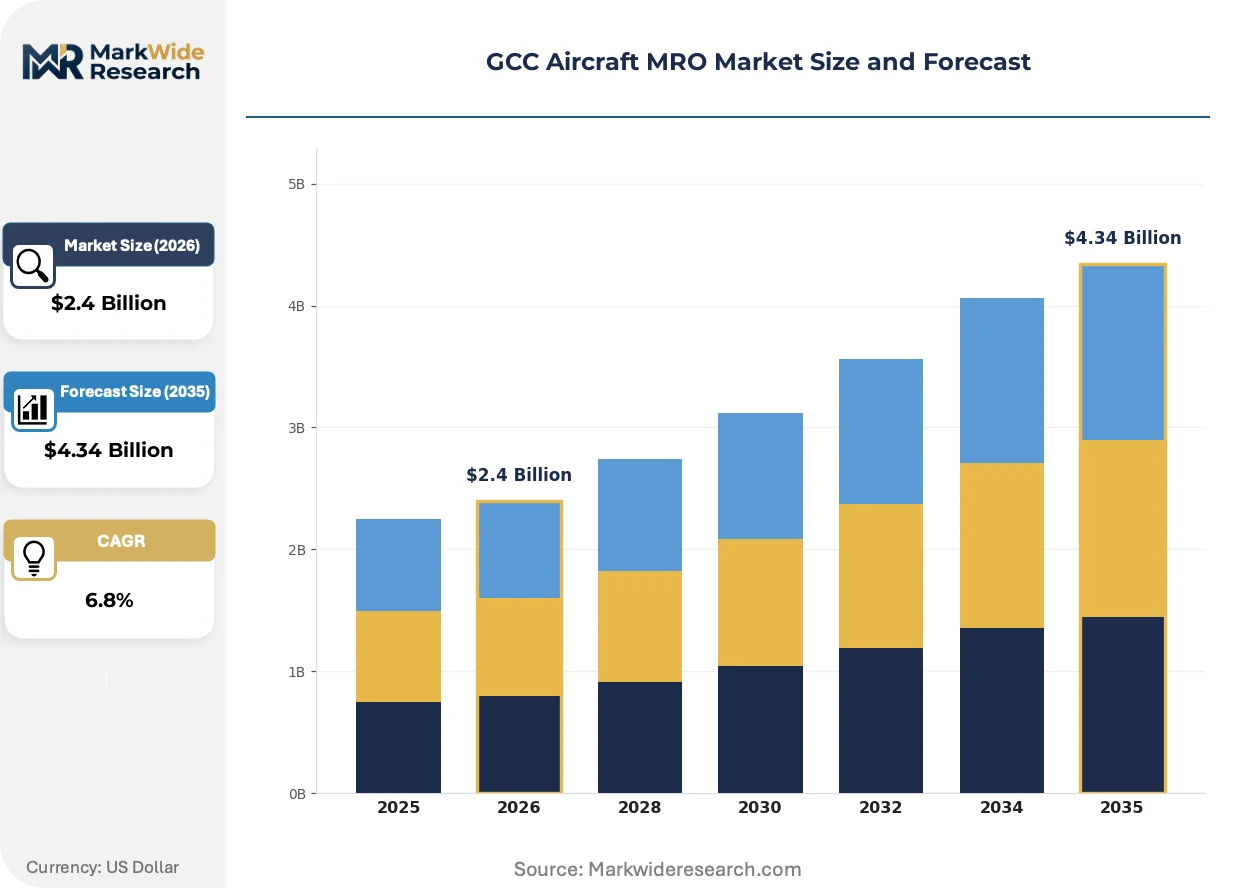
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Base Maintenance, Component Repair, Engine Overhaul, Avionics Upgrade, Modifications Aircraft Type: Commercial Jets, Regional Aircraft, Business Jets, Military Aircraft, Helicopters, Cargo Planes Customer Type: Airlines, Leasing Companies, Charter Operators, Military Entities, Cargo Operators, Helicopter Operators Delivery Model: In-House MRO, Third-Party MRO, Outsourced Services, Integrated MRO Solutions, On-site Support |
| Companies Covered | Emirates Engineering, Etihad Airways Engineering, Saudia Aerospace Engineering Industries, Qatar Airways Maintenance, Gulf Aircraft Maintenance Company, Lufthansa Technik Middle East, Abu Dhabi Aircraft Technologies, Bahrain Airport Services, ST Aerospace Gulf, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Aircraft MRO Market Shifts & Advancements
Digital thread technologies are rewiring how MRO providers capture, analyze, and act upon aircraft health data across distributed supply chains.
Predictive analytics platforms are migrating from scheduled interval maintenance to condition-based intervention models. Emirates Engineering and Saudia Aerospace Engineering Industries are deploying sensor-fed algorithms that flag component degradation before hard-time limits trigger. This shift is compressing unplanned aircraft-on-ground events and reallocating technician labor from reactive troubleshooting to pre-positioned restoration.
EASA bilateral recognition agreements with GCAA and GACA are streamlining cross-border maintenance approvals for European-registered aircraft operating GCC routes. The regulatory convergence reduces duplicate inspection requirements and certificate validation delays. Component repair specialists in Dubai and Jeddah are capturing expanded work scopes previously routed to European facilities.
Airline procurement departments are unbundling engine overhaul from integrated power-by-the-hour contracts. Carriers now source base maintenance, line maintenance, and component repair from distinct providers rather than single-source OEM-affiliated networks. This fragmentation is most visible among Saudi-based low-cost carriers building multi-vendor rosters to defend negotiating leverage.
GCC Aircraft MRO Market Segmentation
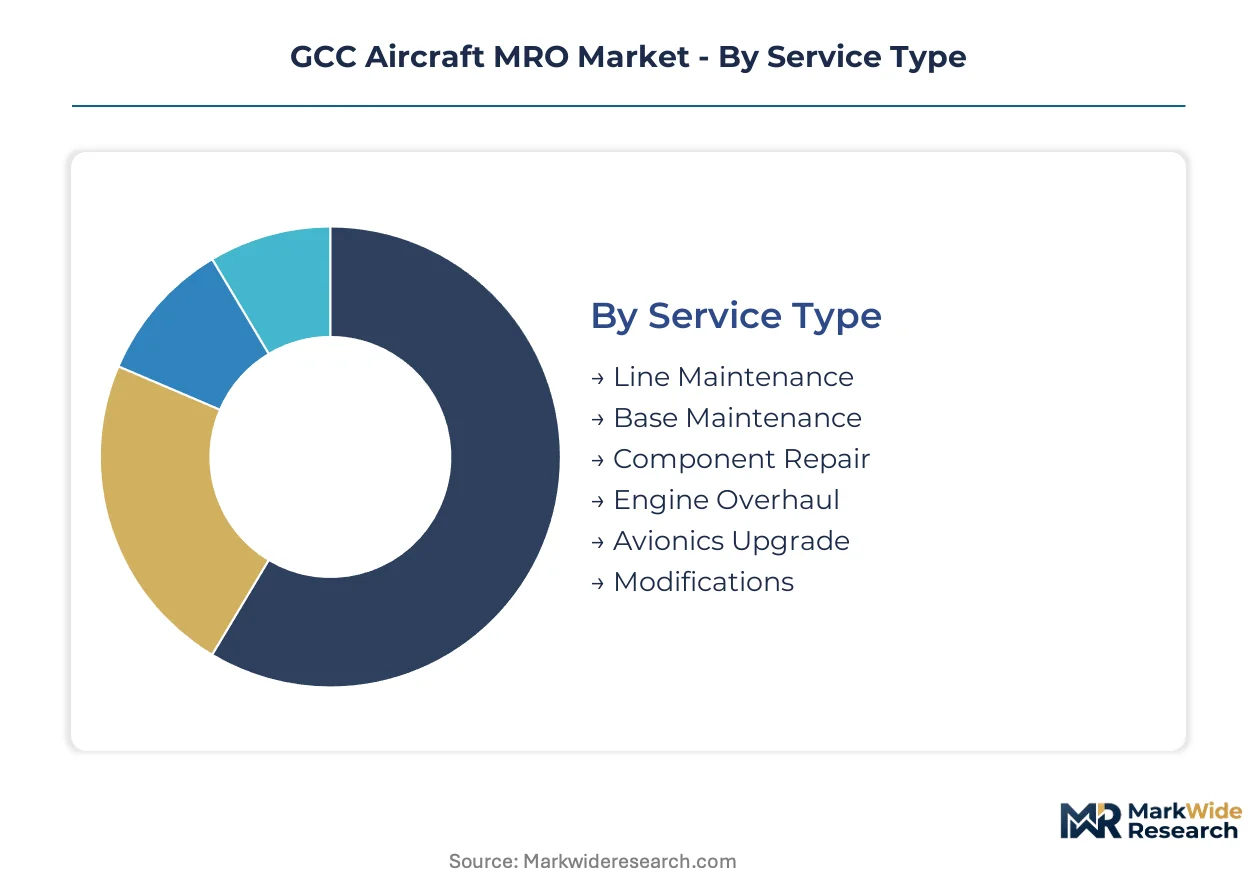
GCC Aircraft MRO providers configure service portfolios around four intersecting dimensions that determine contract value, margin profile, and facility investment requirements. Understanding these segment boundaries clarifies where specialized capabilities command premium positioning versus commoditized execution.
Service Type:
Mature overhaul services coexist with emerging digital-enabled categories, creating a bifurcated capability landscape across Gulf facilities.
- Engine Overhaul:Disassembly, inspection, and restoration of turbine modules to OEM performance specifications using proprietary borescope protocols and blade replacement techniques. Demand concentrates at Saudia Aerospace Engineering Industries and Emirates Engineering facilities in Riyadh and Dubai, where wide-body fleet accumulation triggers mandatory shop visits at prescribed cycle limits. OEM intellectual property constraints restrict independent provider participation.
- Base Maintenance:Heavy structural inspections, corrosion treatment, and airframe restoration requiring enclosed hangar environments and extended aircraft downtime. Dubai, Jeddah, and Doha airport zones absorb the largest volume as aging regional and commercial jet fleets require C-check and D-check interventions at 4,000-6,000 flight hour intervals.
- Component Repair:Specialized restoration of avionics, landing gear, and hydraulic systems by third-party specialists outside OEM networks.
- Line Maintenance:Routine pre-flight and transit checks performed at airport gates without hangar requirements.
- Avionics Upgrade:Cockpit modernization and connectivity retrofits driven by GCAA and GACA navigation mandate compliance.
- Modifications:Cabin reconfiguration and freighter conversion programs for lease return preparation.
Base Maintenance handles the majority of throughput; Component Repair is gaining share fastest as airlines unbundle non-core capabilities.
Aircraft Type:
Volume distribution follows the commercial fleet deployment patterns of Saudi Arabia, the UAE, and Qatar's hub carriers.
- Commercial Jets:Wide-body and narrow-body aircraft operated by Emirates, Saudia, Qatar Airways, and flydubai demanding scheduled heavy maintenance and engine overhaul services. King Salman International Airport development in Jeddah and Dubai's Al Maktoum expansion are scaling dedicated hangar capacity for this segment.
- Regional Aircraft:Turboprops and small jets serving domestic and short-haul routes across the six Gulf states. Kuwait and Bahrain operators accelerate structural inspection protocols as corrosion prevention programs become critical for aging fleet segments.
- Business Jets:Private and corporate aviation assets requiring specialized line maintenance at executive terminals.
- Military Aircraft:Fighter, transport, and surveillance platforms maintained through sovereign facilities with restricted commercial access.
- Helicopters:Offshore oil and gas transport plus emergency medical services demanding rotor system overhaul.
- Cargo Planes:Dedicated freighter fleets and converted passenger aircraft serving e-commerce and perishable logistics routes.
Commercial Jets absorb the dominant maintenance spend; Regional Aircraft show the steepest expansion trajectory as secondary city connectivity deepens.
Customer Type:
Procurement authority varies sharply between asset owners and operators, reshaping contract structures and pricing leverage.
- Airlines:Full-service and low-cost carriers with direct fleet responsibility negotiating multi-year maintenance agreements. Saudi-based low-cost carriers are fragmenting vendor rosters to defend negotiating leverage against integrated OEM-affiliated networks.
- Leasing Companies:Asset owners mandating return condition compliance and residual value preservation through prescribed maintenance programs.
- Charter Operators:Ad-hoc maintenance purchasers with irregular demand patterns and limited volume commitment.
- Military Entities:Sovereign defense departments with classified requirements and captive facility preferences.
- Cargo Operators:Dedicated freighter airlines and express integrators with overnight maintenance windows.
- Helicopter Operators:Offshore energy and medical service providers with specialized rotorcraft expertise needs.
Airlines command the largest contract value; Leasing Companies are expanding their maintenance specification authority fastest as operating lease penetration rises.
Delivery Model:
Supply configuration spans captive, outsourced, and hybrid arrangements that determine provider selection criteria and margin capture.
- Third-Party MRO:Independent specialists competing on turnaround time and cost against OEM-affiliated facilities. Lufthansa Technik Middle East captures European-registered aircraft work through EASA bilateral recognition with GCAA and GACA.
- In-House MRO:Carrier-owned maintenance divisions like Emirates Engineering and Saudia Aerospace Engineering Industries retaining core capabilities for fleet control.
- Outsourced Services:Discrete function contracting for component repair and line maintenance by airlines shedding non-core operations.
- Integrated MRO Solutions:Single-source power-by-the-hour contracts bundling engine, base, and line maintenance.
- On-site Support:Embedded technician teams at airline hubs providing immediate response capability.
Third-Party MRO handles the majority of externalized volume; Outsourced Services are climbing fastest as procurement departments unbundle previously integrated contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maintenance capacity across the Gulf Cooperation Council clusters around sovereign carrier facilities and airport-adjacent industrial zones, with regulatory convergence between GCAA, GACA, and QCAA accelerating cross-border work flows.
United Arab Emirates
Dubai International Airport and Al Maktoum International anchor the region's largest base maintenance footprint, where Emirates Engineering operates dedicated wide-body hangars. GCAA airworthiness directives mandate digital record-keeping compliance that favors integrated providers with unified compliance infrastructure. Dubai South's aviation district concentrates specialized tooling pools and EASA-certified technician training centers serving European-registered aircraft.
Saudi Arabia
King Salman International Airport development in Jeddah is scaling dedicated MRO infrastructure to capture engine overhaul demand from Saudia's expanding fleet base. GACA regulatory harmonization with GCAA and QCAA frameworks compresses certification timelines for cross-border maintenance approvals. Riyadh's King Khalid International Airport zone hosts Saudia Aerospace Engineering Industries facilities performing heavy structural checks on accumulating wide-body flight hours.
Qatar
Hamad International Airport's maintenance corridor serves Qatar Airways' hub operations with specialized hangar capacity for A350 and 787 base maintenance cycles. QCAA adoption of ICAO Annex 6 standards aligns inspection protocols with UAE and Saudi frameworks, enabling technician mobility across Gulf facilities. Doha's Aviation District concentrates component repair specialists capturing unbundled airline procurement from previously integrated power-by-the-hour contracts.
Kuwait
Kuwait International Airport maintenance facilities address aging regional jet fleets requiring accelerated corrosion prevention programs and structural inspection protocols. The country's civil aviation regulator enforces continuous airworthiness management organization standards that mirror GCAA and GACA digital compliance requirements. Shuwaikh's industrial zone hosts third-party component repair shops serving low-cost carriers outsourcing non-core capabilities.
Bahrain
Bahrain International Airport's MRO infrastructure supports Gulf Air's narrow-body fleet and third-party charter operators with line maintenance and limited base check capability. The national aviation authority maintains bilateral recognition agreements with EASA that facilitate European-registered aircraft maintenance approvals. Muharraq's airport-adjacent zones concentrate specialized avionics repair capacity serving smaller Gulf carriers with irregular demand patterns.
GCC Aircraft MRO Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The GCC Aircraft MRO structure concentrates around sovereign carrier-owned facilities and OEM-affiliated technical divisions, with independent third-party providers competing on turnaround time and cost efficiency. Three archetypes dominate: integrated airline engineering divisions, OEM-authorized service centers, and independent component repair specialists. Competitive dynamics center on hangar slot allocation efficiency and technician certification pipeline development rather than price-based rivalry.
Among integrated airline engineering divisions, Emirates Engineering, Saudia Aerospace Engineering Industries, and Qatar Airways Maintenance exemplify the captive-capability model where hub carriers retain core maintenance functions for fleet control. These facilities occupy positions as default service providers for their parent airline's heavy maintenance cycles, with excess capacity marketed to third-party operators. Lufthansa Technik Middle East represents the OEM-authorized tier, leveraging EASA bilateral recognition to capture European-registered aircraft work. Independent specialists including Gulf Aircraft Maintenance Company and ST Aerospace Gulf sit within the third-party segment, competing for unbundled component repair and line maintenance contracts as airlines fragment vendor rosters.
| Leading Market Players |
|---|
| Emirates Engineering |
| Etihad Airways Engineering |
| Saudia Aerospace Engineering Industries |
| Qatar Airways Maintenance |
| Gulf Aircraft Maintenance Company |
| Lufthansa Technik Middle East |
| Abu Dhabi Aircraft Technologies |
| Bahrain Airport Services |
| ST Aerospace Gulf |
| Others |
Supply & Pricing Matrix
Single-source dependency on aerospace-grade titanium and nickel-based superalloy suppliers from the United States, Russia, and China compresses margin buffers while forcing tiered pricing stratification across OEM-authorized, airline-captive, and independent MRO facilities. This input concentration simultaneously elevates premium tier spreads for engine overhaul services and fragments procurement leverage among smaller component repair specialists.
Pricing Analysis
EASA and FAA bilateral recognition agreements with GCAA, GACA, and QCAA dictate the pricing tier structure across Gulf MRO facilities. Three-tier pricing separates OEM-authorized engine overhaul from airline-captive base maintenance from independent component repair, with certification grade and technician credential density as primary differentiation drivers. Cost compression in independent component repair is intensifying because airlines unbundle previously integrated power-by-the-hour contracts. Low-cost carriers exhibit highest price sensitivity, while sovereign carriers prioritize fleet availability over unit cost.
Supply Chain Analysis
Specialized aerospace foundries in the United States, United Kingdom, and Japan hold concentrated capacity for turbine blade casting and precision-machined engine components. MRO providers draw from aerospace-grade alloy feedstock, avionics semiconductor modules, and hydraulic system seals as critical inputs. Single-source vulnerability around OEM-proprietary diagnostic protocols creates supply chain fragility for independent engine overhaul shops. Distribution runs through bonded logistics corridors at Dubai, Jeddah, and Doha airport zones to minimize aircraft-on-ground downtime.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC Aircraft MRO market sits in a cyclical recovery phase as wide-body fleet accumulation across Saudi Arabia, the UAE, and Qatar triggers mandatory heavy maintenance cycles at prescribed flight hour intervals.
For Market Incumbents: Entrench dominance through backward integration into specialized tooling manufacturing and captive technician certification pipelines that EASA Part-66 and FAA Airframe & Powerplant standards require. Emirates Engineering and Saudia Aerospace Engineering Industries should expand hangar capacity at Dubai South and King Salman International Airport before independent specialists capture excess demand. Defend against unbundling pressure from low-cost carrier procurement departments by bundling predictive maintenance platform subscriptions with base maintenance contracts. For New Entrants and Emerging Players: Kuwait and Bahrain's aging regional jet fleets present geographic underpenetration for corrosion prevention program specialists. Component repair shops targeting avionics and landing gear systems face lower OEM intellectual property barriers than engine overhaul entrants. Independent providers should pursue EASA bilateral recognition with GCAA and GACA to unlock European-registered aircraft work scopes previously routed to incumbent facilities. For Investors and Strategic Acquirers: QCAA adoption of unified ICAO Annex 6 standards reshapes the acquisition landscape by enabling cross-border technician mobility and consolidated compliance platform scalability. Long-term viability centers on facilities with digital record-keeping infrastructure that spans multiple Gulf regulatory jurisdictions. Target independent component repair specialists with EASA-certified technician pools. Monitor GCAA-GACA-QCAA regulatory convergence announcements as the primary inflection signal for integrated MRO solution displacement of fragmented service models.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Sensor-fed algorithms at Emirates Engineering and Saudia Aerospace Engineering Industries compress unplanned aircraft-on-ground events. |
| Technician Certification Pipeline Expansion | EASA Part-66 and FAA Airframe & Powerplant programs at Dubai South training centers address specialized labor scarcity. |
| Corrosion Prevention Program Specialization | Kuwait and Bahrain facilities capture aging regional jet structural inspection demand outside OEM-affiliated networks. |
| Digital Record-Keeping Convergence | Unified compliance platforms across GCAA, GACA, and QCAA jurisdictions enable integrated MRO solution scalability. |
| Component Repair Capability Buildout | Independent shops in Doha's Aviation District capture unbundled airline procurement from power-by-the-hour contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MRO facility directors, airline fleet managers, regulatory compliance officers at GCAA and GACA, and procurement leads at low-cost carriers. Secondary validation drew from ICAO Annex 6 implementation documentation, EASA bilateral recognition agreements with Gulf regulators, customs data on aerospace alloy imports, and facility capacity disclosures from Dubai South and King Salman International Airport development authorities. Bottom-up technician certification throughput estimates were triangulated against top-down hangar capacity expansion timelines.
Calibration against historical maintenance cycle intervals and fleet delivery schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, aircraft category, customer procurement authority, and delivery model configuration. CAGRs were derived from flight hour accumulation curves and mandatory inspection interval regulations. Forecast inputs incorporated wide-body delivery pipelines from Boeing and Airbus, plus regulatory harmonization milestones between GCAA, GACA, and QCAA.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by independent third-party specialists or accelerated regulatory convergence would shift outcomes beyond modeled ranges. Forecasts reflect documented assumptions regarding technician certification pipeline throughput, OEM intellectual property licensing terms, and aerospace alloy price stability. Quarterly review of GCAA-GACA-QCAA regulatory alignment announcements and wide-body fleet utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market