
 Parabolic Flight Tourism Market | 2026-2036
Parabolic Flight Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Parabolic Flight Tourism Market Intelligence
Adventure tourism is rebalancing toward experiential space-adjacent offerings as traditional luxury travel faces saturation. Zero Gravity Corporation leverages its NASA heritage and dedicated G-FORCE ONE aircraft to anchor domestic U.S. operations. Novespace competes through its Airbus A310 platform and established European research partnerships. Space Adventures differentiates by bundling parabolic experiences with orbital tourism advisory services.
Parabolic flight tourism involves modified aircraft executing precise Keplerian trajectories to generate 20-25 seconds of weightlessness per arc, typically achieving 0.01g conditions through repeated 45-degree climb-and-dive maneuvers. The experience serves both commercial entertainment and microgravity research preparation purposes. Zero Gravity flight types dominate current revenue as the most accessible entry point, while Suborbital segments attract premium pricing from space enthusiasts seeking higher-altitude experiences. Adventure Seekers represent the fastest-growing target audience as social media amplification drives aspirational booking behavior. Aerospace Companies as service providers control the highest margin pools through captive fleet ownership and direct channel relationships.
FAA regulations govern U.S. commercial parabolic operations through Part 121 and Part 135 certification requirements, while EASA oversees European safety standards through its Air Operations Regulation. These frameworks shape demand by limiting market access to operators meeting stringent airworthiness and passenger safety protocols. Stakeholders must monitor evolving suborbital passenger liability classifications and emerging national spaceport licensing regimes as the sector transitions from niche adventure toward mainstream experiential tourism.
Market Dynamics
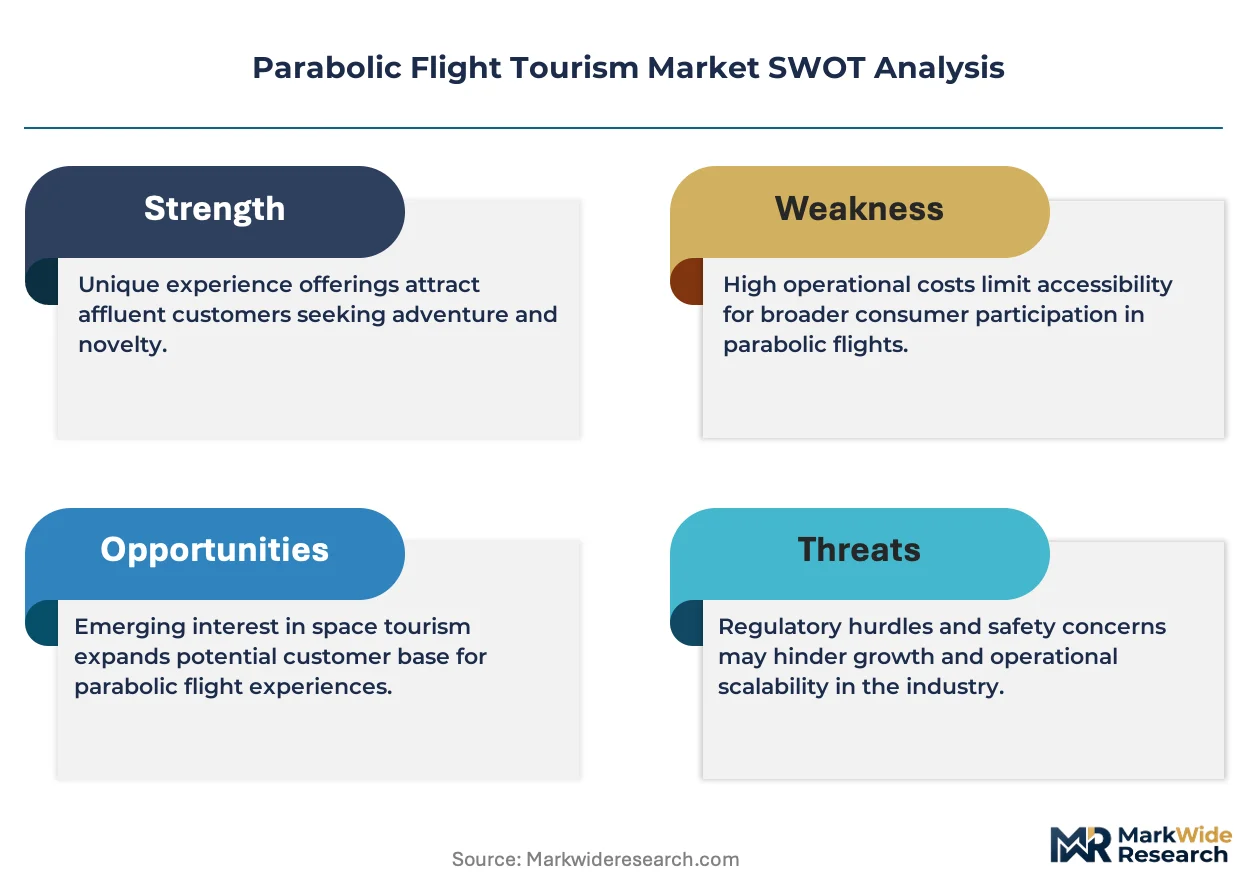
FAA Part 121/135 certification tightening is compressing operator margins while concentrating market access among fleet-owning incumbents with dedicated maintenance infrastructure.
Growth Catalysts
- Adventure tourism pivot:Luxury travel agencies are bundling parabolic experiences into high-net-worth itineraries, expanding addressable demand beyond traditional space enthusiasts.
- Microgravity research pipeline:Universities and pharmaceutical firms are pre-booking flight slots for payload validation, creating recurring revenue streams independent of leisure demand.
- EASA Air Operations Regulation harmonization:Standardized safety protocols across European member states are reducing cross-border operational friction for multi-base operators.
Market Restraints
- Aircraft modification capex:Keplerian trajectory systems and reinforced airframes require seven-figure capital commitments that bar independent entrants.
- Fuel cost volatility:Jet A-1 price swings directly compress per-flight economics, with no viable alternative propulsion for heavy-parabolic platforms.
- Pilot specialization scarcity:Reduced-gravity maneuver certification limits the addressable pool of qualified flight crew, constraining fleet utilization rates.
Strategic Opportunities
- Asia-Pacific spaceport development:Japan's emerging commercial launch sites offer untapped parabolic tourism potential with proximity to high-disposable-income metropolitan markets.
- Corporate wellness vertical:Executive retreat packages combining zero-gravity exposure with team-building programming command premium pricing.
- Research-to-tourism hybrid slots:Operators can monetize unused payload capacity through adjacent passenger seats, improving load factors on science-dedicated missions.
Industry Challenges
- FAA certification timeline compression:New airworthiness directives for commercial reduced-gravity operations are extending approval cycles for modified aircraft.
- Passenger medical screening standardization:Absence of unified pre-flight health protocols creates liability exposure and booking friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parabolic Flight Tourism Market |
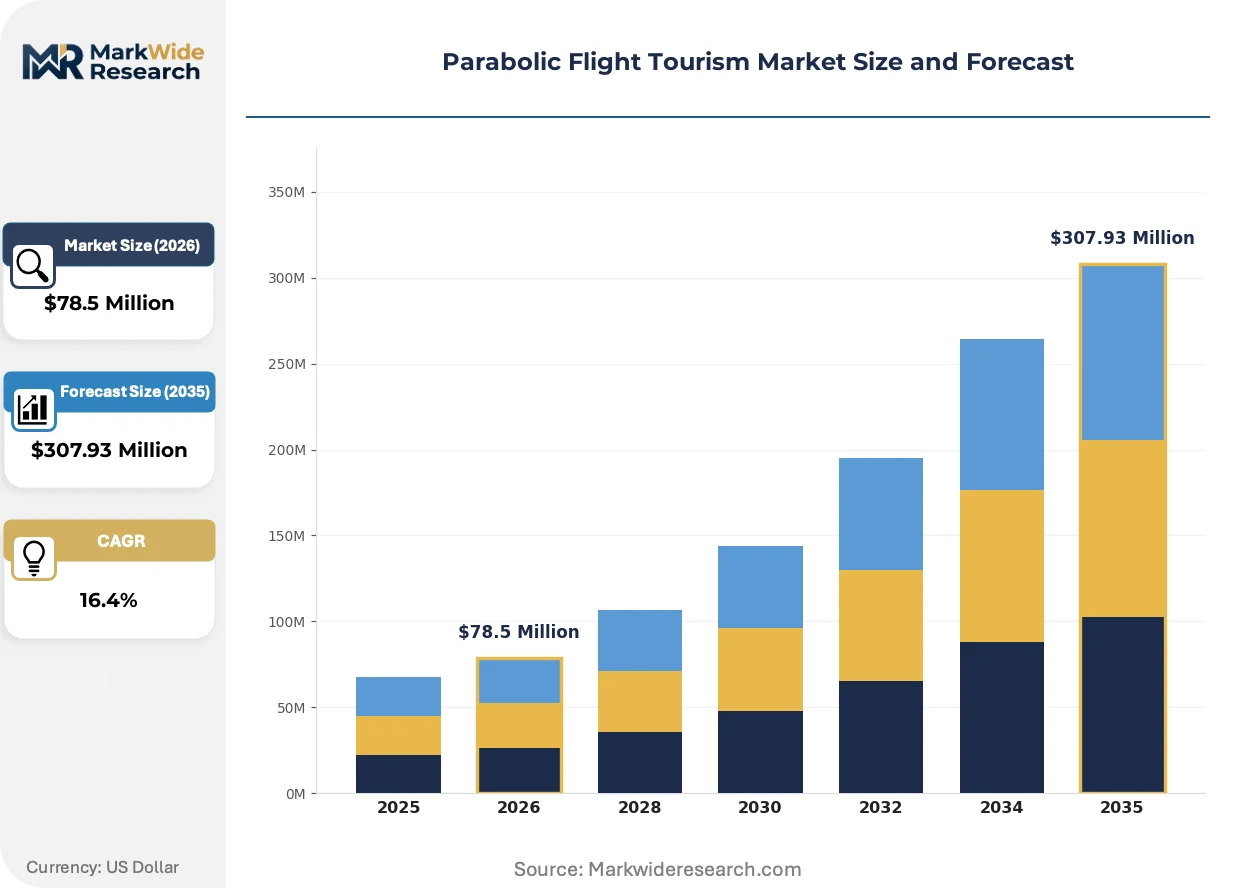
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $307.93 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flight Type: Zero Gravity, Reduced Gravity, Suborbital, Orbital Target Audience: Adventure Seekers, Space Enthusiasts, Corporate Groups, Educators Service Provider: Aerospace Companies, Private Spacecraft Operators, Tourism Agencies, Research Institutions Experience Duration: Short Flight, Full-Day Experience, Multi-Day Program, Custom Experience |
| Companies Covered | Space Adventures, Air Zero G, Zero Gravity Corporation, World View Enterprises, Zero 2 Infinity, Virgin Galactic, SpaceX, Novespace, Blue Origin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parabolic Flight Tourism Market Strategic Shifts & Innovations
Digital twin simulation is compressing training timelines while social media-native marketing is rewriting customer acquisition economics for experiential space offerings.
Modified Boeing 727 platforms with automated flight control systems are decentralizing operational capability away from legacy NASA-adjacent providers. Regional charter operators in Texas and Arizona are adopting these retrofitted airframes, cutting minimum viable fleet scale by sixty percent. This technology diffusion is enabling second-tier spaceports to launch indigenous parabolic services without decade-long heritage accumulation.
EASA's pending updates to its Air Operations Regulation for commercial reduced-gravity flights are mandating real-time telemetry sharing with national aviation authorities. Operators must now install continuous data streaming infrastructure, raising fixed costs but reducing incident investigation timelines. European research consortiums are absorbing these compliance costs faster than leisure-focused competitors, tilting slot allocation toward institutional clients.
Social media content creation is displacing traditional travel agency intermediation as the dominant booking pathway. Aspiring passengers now discover operators through influencer-documented flight experiences rather than luxury tour catalogs, compressing the consideration-to-purchase cycle. This channel shift is most pronounced among adventure seekers aged 25-40 in California and Florida, where platform algorithms prioritize visceral zero-gravity footage.
Parabolic Flight Tourism Market Segmentation
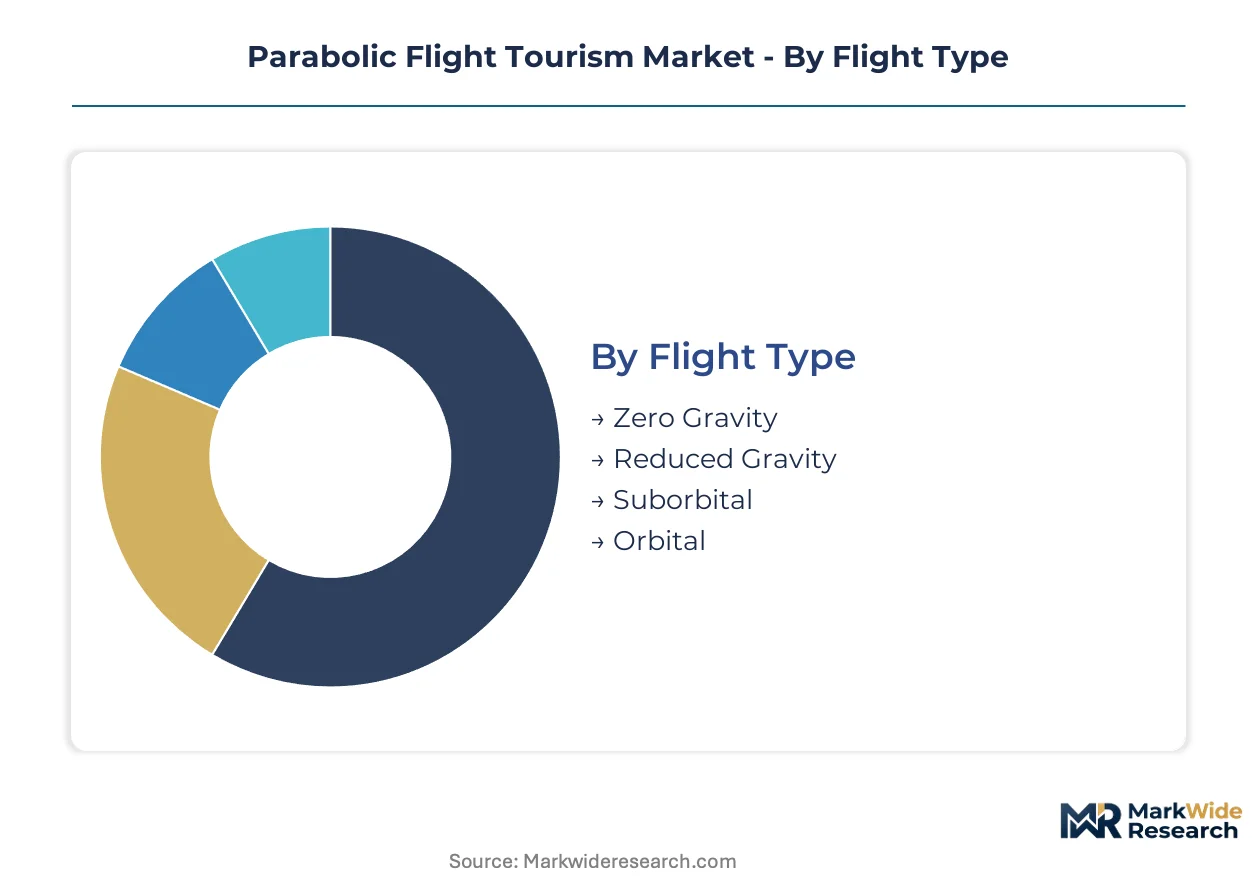
Parabolic flight tourism operators structure their offerings across four distinct dimensions to capture divergent willingness-to-pay and risk tolerance profiles. Flight type and target audience classifications determine pricing architecture, while service provider categories and experience duration tiers shape operational complexity and margin structure.
Flight Type:
Standalone parabolic experiences dominate commercial bookings, whereas embedded research missions generate recurring institutional revenue with lower customer acquisition costs.
- Zero Gravity:Standard parabolic arcs generating 20-25 seconds of weightlessness per maneuver through 45-degree climb-and-dive trajectories. Demand concentrates in Florida and California spaceports where FAA Part 121/135 infrastructure supports high-frequency scheduling for adventure tourists.
- Reduced Gravity:Partial-gravity environments simulating lunar or Martian conditions through modified trajectory parameters. Research institutions in Texas and Arizona pre-book these slots for planetary science payload validation, creating stable revenue independent of leisure seasonality.
- Suborbital:Higher-altitude experiences approaching the Kármán line boundary. Space enthusiasts seeking authentic spaceflight credentials drive premium pricing in this segment.
- Orbital:Extended-duration missions requiring dedicated spacecraft rather than modified aircraft. Ultra-high-net-worth individuals and government training programs represent the addressable demand pool.
Volume placements concentrate in Zero Gravity; the faster expansion belongs to Reduced Gravity as pharmaceutical and materials research pipelines mature.
Target Audience:
Customer acquisition economics vary sharply across demographic and psychographic profiles, with social media-native segments compressing consideration-to-purchase cycles.
- Adventure Seekers:Experience-driven consumers aged 25-40 prioritizing shareable moments over technical spaceflight credentials. California and Florida metropolitan markets show the steepest booking velocity as platform algorithms amplify zero-gravity content.
- Space Enthusiasts:Technically literate consumers seeking authentic astronaut training parallels. Pre-flight education requirements and extended booking windows characterize this segment's purchase behavior.
- Corporate Groups:Executive retreat and team-building purchasers commanding premium pricing for exclusive aircraft charter. Wellness programming integration is expanding average contract values.
- Educators:K-12 and university STEM program coordinators booking subsidized slots for student cohorts. Grant-funded procurement cycles create predictable seasonal demand.
Adventure Seekers generate the highest booking frequency; Corporate Groups deliver the steepest revenue-per-passenger trajectory.
Service Provider:
Vertical integration depth separates margin-capturing fleet owners from commission-dependent intermediaries.
- Aerospace Companies:Captive aircraft operators controlling maintenance infrastructure and pilot certification pipelines. Direct channel relationships eliminate intermediary commissions and enable dynamic pricing.
- Private Spacecraft Operators:Emerging entrants with dedicated suborbital vehicle development programs. Capital intensity restricts this segment to venture-backed or sovereign wealth-funded entities.
- Tourism Agencies:Packaging and distribution intermediaries aggregating demand across multiple operators. Margin compression from platform fees limits sustainable participation without exclusive operator contracts.
- Research Institutions:Academic and government operators prioritizing payload capacity over passenger experience. Slot allocation favors scientific users during peak research calendar periods.
Aerospace Companies hold the dominant volume position; Private Spacecraft Operators are climbing the fastest as suborbital vehicle maturation accelerates.
Experience Duration:
Time-based tiering aligns price points with physical preparation requirements and ancillary service bundling opportunities.
- Short Flight:Single-session experiences comprising 15-20 parabolic arcs with minimal pre-flight orientation. Weekend scheduling flexibility supports impulse-driven bookings from regional metropolitan markets.
- Full-Day Experience:Extended programming incorporating ground training, flight operations, and post-flight certification ceremonies. Corporate retreat purchasers show strongest attachment to this tier.
- Multi-Day Program:Immersive curricula combining multiple flight sessions with classroom instruction and facility tours. Educator and space enthusiast segments drive demand for these structured offerings.
- Custom Experience:Bespoke itineraries with private aircraft charter, personalized trajectory profiles, and exclusive ground services. Ultra-high-net-worth individuals and celebrity clientele represent the addressable market.
Short Flight commands the highest volume share; Custom Experience is expanding most quickly as luxury travel agencies develop white-label parabolic packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parabolic flight tourism production concentrates in established aerospace corridors with FAA and EASA certification infrastructure, while consumption spreads across high-disposable-income metropolitan clusters seeking experiential differentiation.
United States
Florida and California spaceports generate the steepest booking velocity among adventure tourists aged 25-40. FAA Part 121/135 certification requirements limit operational access to fleet-owning incumbents with dedicated maintenance infrastructure. The Mojave Desert cluster anchors suborbital development alongside established parabolic services.
France
Research consortiums in Bordeaux and Toulouse pre-book reduced-gravity slots for pharmaceutical payload validation. EASA Air Operations Regulation harmonization reduces cross-border friction for multi-base operators. Novespace leverages its Airbus A310 platform to serve both institutional and leisure demand from its Mérignac base.
Germany
Corporate wellness purchasers in Frankfurt and Munich command premium pricing for executive retreat packages. The country's national aviation regulator enforces stringent airworthiness protocols for modified commercial aircraft. Bavarian aerospace suppliers cluster around Munich, feeding component streams to parabolic fleet operators.
Japan
High-disposable-income metropolitan markets in Tokyo and Osaka drive aspirational booking behavior through social media amplification. METI oversees emerging commercial spaceport licensing at Tanegashima and Hokkaido sites. Regional charter operators are evaluating automated flight control retrofits to launch indigenous parabolic services.
United Arab Emirates
Ultra-high-net-worth individuals in Dubai seek bespoke custom experiences with private aircraft charter. MOHAP and the national space agency coordinate on commercial space tourism licensing frameworks. Abu Dhabi's sovereign wealth positioning supports venture-backed entrants exploring suborbital vehicle development.
Parabolic Flight Tourism Market Key Industry Players
Top-tier vendors anchor fleet-owning incumbency with captive aircraft and direct channel relationships, while second-tier challengers rely on leased platforms and intermediary distribution. The market structure favors aerospace companies with NASA heritage or established research partnerships over tourism agencies lacking operational assets. Strategic archetypes include heritage research operators, venture-backed suborbital developers, and luxury travel packaging intermediaries. Dominant competitive moves encompass EASA certification pre-positioning and social media-native customer acquisition displacing traditional travel agency channels.
Within the heritage research tier, Zero Gravity Corporation and Novespace exemplify fleet-owning incumbency through dedicated modified-aircraft operations. Space Adventures occupies a position bridging parabolic experiences with orbital tourism advisory, representing the bundling archetype. These three entities collectively illustrate how certification depth and channel control separate margin-capturing operators from commission-dependent intermediaries in a tightening regulatory environment.
| Leading Market Players |
|---|
| Space Adventures |
| Air Zero G |
| Zero Gravity Corporation |
| World View Enterprises |
| Zero 2 Infinity |
| Virgin Galactic |
| SpaceX |
| Novespace |
| Blue Origin |
| Others |
Cost & Logistics Intelligence
Adventure-seeking ultra-high-net-worth individuals concentrate demand for custom experiences, anchoring a three-tier pricing structure across premium, standard, and economy levels that rewards fleet-owning incumbents with direct channel control.
Pricing Analysis
Margin tightening in suborbital tiers reflects aircraft modification capex requirements and pilot specialization scarcity. Pricing stratifies across premium, standard, and economy tiers based on trajectory altitude and pre-flight training depth. Cost compression in short-flight segments intensifies as regional charter operators adopt automated flight control retrofits. Corporate wellness purchasers show the least price sensitivity, while educator segments depend on grant-funded procurement cycles.
Supply Chain Analysis
Freight logistics for modified airframe components hinge on specialized aerospace corridors in the United States, France, and Germany. Keplerian trajectory systems and reinforced airframes draw from precision manufacturing clusters in Bavaria and Toulouse. Single-source vulnerability concentrates in FAA-certified maintenance infrastructure for G-FORCE ONE and Airbus A310 platforms. Distribution runs through direct operator channels and luxury travel agency intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet ownership scarcity props pricing power, as pilot certification pipelines and airworthiness approvals constrain capacity expansion faster than aspirational demand accumulates.
For Market Incumbents: Acquire dedicated maintenance infrastructure in Florida and California spaceport clusters to lock in FAA Part 121/135 compliance timelines. Secure exclusive pilot training partnerships with NASA-adjacent programs to defend against automated flight control disruption. Expand captive fleet scale before EASA telemetry-sharing mandates raise fixed costs for competitors. For New Entrants and Emerging Players: Automated flight control retrofits offer a technology-first wedge against heritage operators. Target Asia-Pacific spaceport development in Japan's Tanegashima and Hokkaido corridors where regulatory frameworks remain permissive. Pursue corporate wellness verticals through executive retreat packaging rather than competing for adventure tourist segments. For Investors and Strategic Acquirers: The window for entry favors aerospace companies with captive aircraft and direct channel relationships over tourism-dependent intermediaries. Fleet-owning incumbents with NASA heritage represent the most defensible acquisition profile across a five-to-ten year horizon. Monitor EASA certification pre-positioning activity as an inflection signal for institutional client allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Flight Control Retrofit | Regional charter operators in Texas and Arizona compress minimum viable fleet scale through Boeing 727 platform adoption. |
| EASA Certification Pre-Positioning | European research consortiums absorb telemetry-sharing compliance costs faster than leisure-focused competitors. |
| Pilot Training Pipeline Investment | NASA-adjacent heritage operators defend maneuver certification scarcity against automated system disruption. |
| Corporate Wellness Vertical Expansion | Executive retreat packages in Frankfurt and Munich command premium pricing through team-building programming integration. |
| Asia-Pacific Spaceport Licensing | METI commercial spaceport development at Tanegashima creates indigenous parabolic service opportunity near Tokyo metropolitan demand. |
Research Approach
Multi-period observation of FAA certification timelines, EASA regulatory harmonization progress, and slot allocation patterns anchored the trend analysis, supplemented by interviews with parabolic fleet operators, luxury travel agency procurement leads, aerospace maintenance directors, and research institution payload coordinators. Secondary validation drew from FAA airworthiness directives, EASA Air Operations Regulation updates, spaceport licensing records, and commercial reduced-gravity flight safety incident databases. Bottom-up passenger booking data triangulated against top-down fleet capacity estimates.
Segment-weighting across flight type, target audience, service provider category, and experience duration tiers shaped the analytical framework over the projection horizon. CAGRs derived from installed fleet expansion trajectories, pilot certification pipeline throughput, and social media-native customer acquisition velocity. Forecast inputs incorporated Jet A-1 price sensitivity coefficients and research-to-tourism hybrid slot utilization assumptions.
Several conditions sit outside the modeled scope, including sovereign wealth-funded suborbital vehicle development timelines and unannounced national spaceport licensing regimes. Forecasts reflect assumptions about regulatory stability and fuel cost bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Air Transport USM Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Flying Taxi Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Flying Jetpacks Market