
 Satellite Amplifier Market | 2026-2036
Satellite Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Amplifier Market Analysis
Defense and broadband verticals is recalibrating procurement volumes across the satellite amplifier supply base. Qorvo leverages its compound semiconductor foundry capacity to anchor defense-grade GaN amplifier production. Almagest Space specializes in small-satellite optimized form factors that compete with legacy aerospace suppliers on mass and thermal efficiency. AmpliTech Group sustains its position through precision low-noise block designs for ground segment applications.
A satellite amplifier is an active RF device that boosts weak received signals or elevates transmitted power in satellite communication links, typically operating across C-band, Ku-band, Ka-band, and emerging Q/V-band frequencies with noise figures below 1 dB for low-noise applications and power-added efficiencies exceeding 60 percent in advanced GaN implementations. Solid-state technology leads volume shipments due to reliability and thermal management advantages in compact payloads, while power amplifiers command the dominant margin pool owing to materials intensity and qualification barriers. Vacuum tube amplifiers retain niche positions in very high-power broadcast and certain military uplink segments where efficiency and raw output power outweigh size constraints.
The US Federal Communications Commission governs spectrum allocation and orbital debris mitigation rules that shape amplifier efficiency mandates, while the Department of Defense's MIL-STD-883 qualification requirements filter market access for non-domestic suppliers. Europe's ETSI standards and the EU Space Programme Agency's secure connectivity objectives are tightening electromagnetic compatibility thresholds for constellation-grade hardware. Stakeholders must monitor gallium substrate supply concentration and evolving export control classifications for wide-bandgap semiconductors when evaluating manufacturing footprint decisions.
Market Dynamics
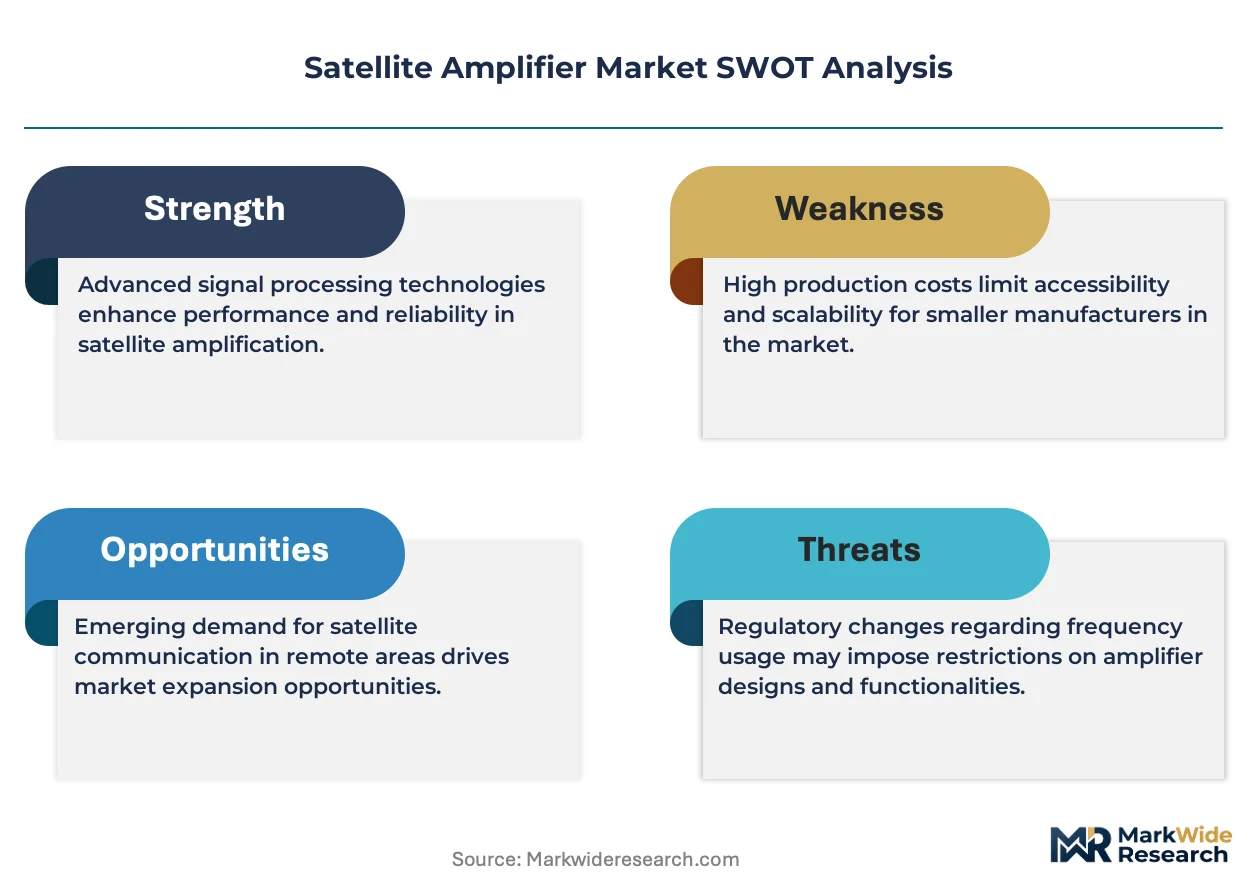
The Satellite Amplifier Market is experiencing a fundamental recalibration as gallium nitride technology displaces legacy gallium arsenide designs across high-power defense and broadband applications. This materials transition is compressing supplier lead times while elevating qualification barriers for compound semiconductor foundries serving orbital and ground segment customers.
Growth Catalysts
- Defense Procurement Realignment:US Space Force contracts are redirecting supplier capacity toward radiation-hardened GaN amplifiers. MIL-STD-883 qualification requirements filter access for domestic foundries.
- Spectrum Efficiency Mandates:The US Federal Communications Commission's orbital debris mitigation rules are forcing amplifier efficiency improvements in C-band and Ka-band payloads.
- Constellation Deployment Density:Low Earth orbit broadband networks in California's satellite manufacturing corridor are consuming volume-optimized solid-state power amplifiers.
Market Restraints
- Gallium Substrate Concentration:Wide-bandgap semiconductor feedstock supply clusters in East Asian refining operations create single-source vulnerability for GaN epitaxial wafer production.
- Export Control Friction:US Department of Commerce restrictions on wide-bandgap semiconductor manufacturing equipment complicate technology transfer to allied foundry partners.
- Vacuum Tube Substitution Ceiling:Traveling-wave tube amplifiers retain cost and efficiency advantages in very high-power broadcast uplinks above 500 watts.
Strategic Opportunities
- Q/V-Band Frequency Expansion:Emerging spectrum allocations above 40 GHz enable higher data-rate inter-satellite links for next-generation relay constellations.
- Ground Station Cluster Proximity:Colorado's dense concentration of telemetry, tracking and command facilities creates localized demand for precision low-noise block downconverters.
- European Secure Connectivity Mandate:The EU Space Programme Agency's IRIS² constellation specifications are tightening electromagnetic compatibility thresholds for qualified amplifier suppliers.
Industry Challenges
- Compound Semiconductor Talent Scarcity:GaN device physics expertise concentrates in legacy defense contractors, constraining foundry expansion for commercial constellation suppliers.
- Qualification Timeline Compression:MIL-STD-883 radiation testing and thermal cycling protocols extend product development cycles beyond commercial satellite production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Amplifier Market |
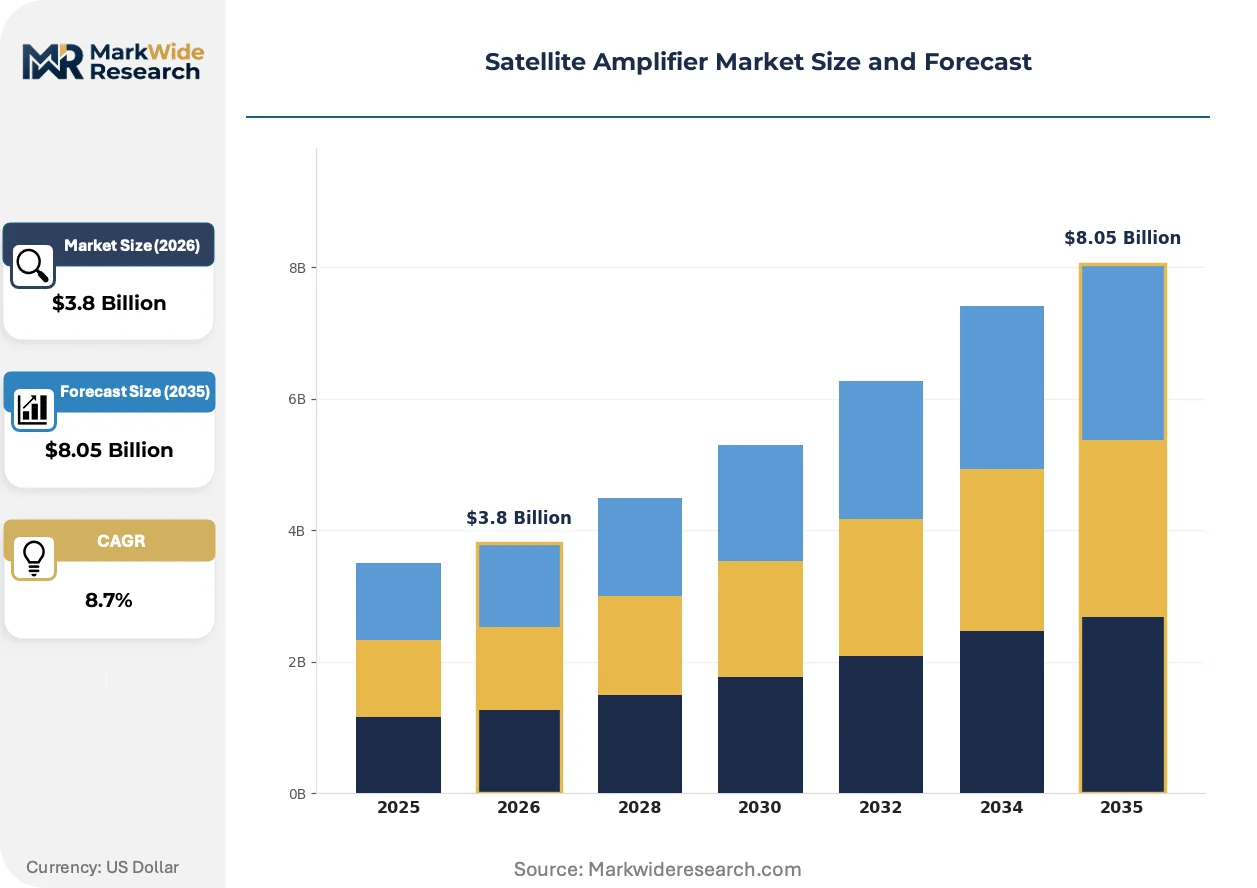
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Noise Block, Gain Block, RF Amplifier, Power Amplifier End User: Telecom Operators, Satellite Service Providers, Broadcasters, Aerospace & Defense Installation Type: Indoor, Outdoor, Pole-Mounted, Rack-Mounted Technology: Solid-State, Vacuum Tube, Integrated Circuit, Hybrid |
| Companies Covered | mmTron, Almagest Space, AmpliTech Group, Astranis, Morpheus Space, Qorvo, Astrome Technologies, Impulse Space, Akash Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Amplifier Market Emerging Trajectories
Active materials science breakthroughs and procurement model evolution are compressing traditional amplifier design cycles while fragmenting the supplier base between defense-captive and commercial-flexible production lines.
GaN-on-diamond thermal management substrates are integrating into high-reliability space-qualified power amplifiers. Defense prime contractors are qualifying these devices for geostationary orbit missions requiring decade-plus operational lifespans. The technology is integrating radiation-hardened driver circuits with diamond heat spreaders, collapsing thermal resistance specifications that previously required liquid cooling architectures.
REACH substance restrictions in Europe are phasing out hexavalent chromium plating in amplifier housing manufacturing. Suppliers serving ESA-qualified programs must transition to trivalent chromium or ceramic coating alternatives. Ka-band block upconverters for maritime mobility terminals face the tightest compliance timelines under the EU Green Deal's extended producer responsibility frameworks.
Constellation operators are unbundling amplifier procurement from satellite prime contracts, creating direct purchasing relationships with compound semiconductor foundries. This disintermediation collapses traditional aerospace supply chain markups. Small-satellite builders in California are most aggressively pursuing this model, negotiating volume commitments for standardized S-band and X-band amplifier modules.
Satellite Amplifier Market Segmentation
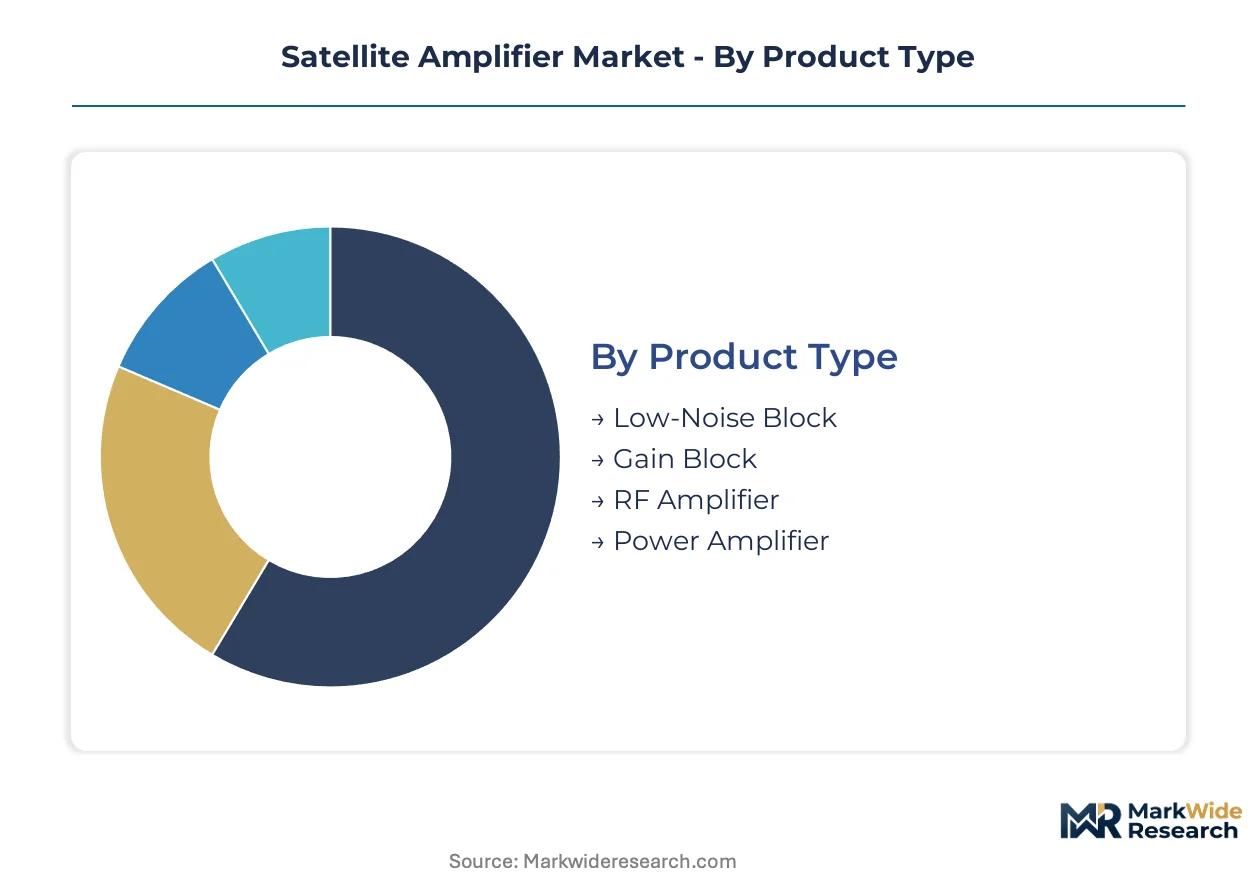
Satellite amplifier procurement splits across four distinct axes: signal chain position, customer mission profile, environmental mounting requirements, and underlying device physics. Each axis carries different qualification burdens and margin structures that reshape supplier priorities.
Product Type:
Capital intensity peaks in power amplification stages where wide-bandgap semiconductor foundry access and thermal management systems dominate upfront investment requirements.
- Power Amplifier:GaN and GaAs compound semiconductor implementations deliver output power exceeding 100 watts with power-added efficiencies above 60 percent. Defense procurement from the US Space Force concentrates demand for radiation-hardened variants qualified to MIL-STD-883 protocols.
- Low-Noise Block:Cryogenic and room-temperature low-noise amplifiers achieve noise figures below 0.5 dB in Ka-band ground segment applications. Colorado's telemetry cluster drives precision manufacturing requirements for block downconverters in satellite tracking facilities.
- Gain Block:Intermediate amplification stages buffer signal integrity across multi-stage RF chains. Standardized S-band and X-band modules serve small-satellite builders in California's manufacturing corridor.
- RF Amplifier:Broadband amplification covers C-band through Q/V-band with flexible gain profiles. Broadcast uplink stations favor these devices for multi-frequency service flexibility.
Most installed capacity flows through Power Amplifier segments. Expansion is steepest in Low-Noise Block configurations for ground station densification.
End User:
Customer mission profiles range from commercial broadband constellations requiring volume-optimized units to defense programs demanding decade-plus operational lifespans.
- Aerospace & Defense:Radiation-hardened GaN amplifiers for geostationary and medium Earth orbit missions command qualification timelines exceeding 24 months. The US Space Force's Protected Tactical Enterprise Service drives secure waveform amplification requirements.
- Telecom Operators:Constellation operators unbundle amplifier procurement from prime satellite contracts, negotiating direct volume commitments with compound semiconductor foundries.
- Satellite Service Providers:Maritime and aero mobility terminals require Ka-band block upconverters with integrated frequency conversion. REACH substance restrictions in Europe accelerate housing material transitions away from hexavalent chromium plating.
- Broadcasters:Very high-power uplink stations above 500 watts retain traveling-wave tube amplifiers for raw output efficiency. Solid-state alternatives penetrate below this threshold.
Aerospace & Defense absorbs the highest unit economics. Telecom Operators are gaining share fastest through disintermediated procurement models.
Installation Type:
Environmental exposure ratings determine enclosure sealing, thermal dissipation architecture, and remote monitoring integration requirements.
- Outdoor:IP67-rated enclosures with integrated heating elements prevent condensation in polar ground station deployments. Colorado's high-altitude facilities stress-test thermal cycling durability.
- Rack-Mounted:Standard 19-inch chassis configurations dominate telemetry, tracking and command facilities with centralized climate control. N+1 redundancy architectures predominate in gateway installations.
- Pole-Mounted:Compact form factors for remote broadcast contribution links minimize wind loading and foundation requirements. Integrated bias-tee powering reduces cabling complexity.
- Indoor:Laboratory and clean-room amplification stages for satellite integration and test facilities prioritize electromagnetic interference shielding over weatherization.
Rack-Mounted configurations carry the largest installed base. Outdoor installations are climbing the fastest with ground station cluster densification.
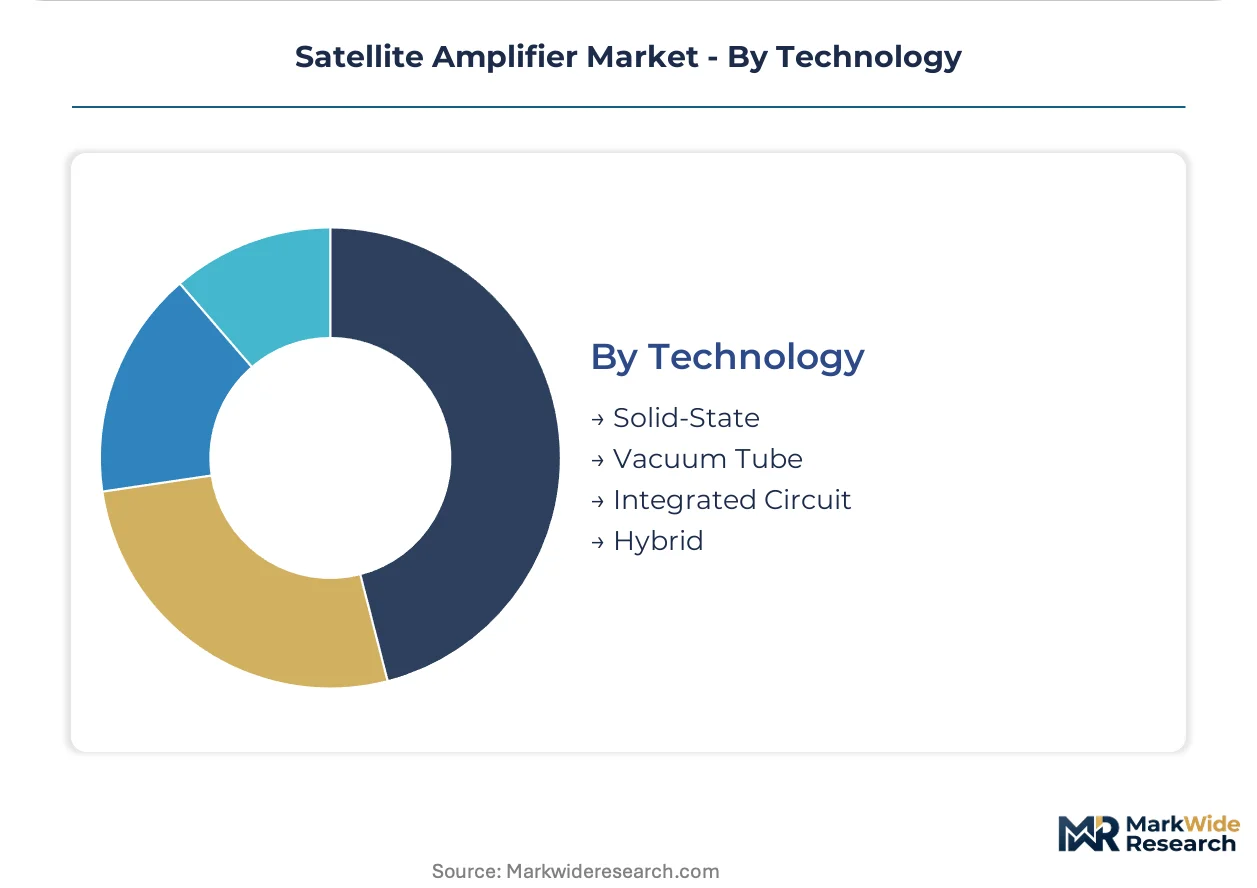
Technology:
Device physics selection trades efficiency, reliability, and raw power output against volume constraints and thermal budget limitations.
- Solid-State:GaN-on-diamond substrates collapse thermal resistance for space-qualified power amplifiers without liquid cooling. Decade-plus operational lifespans in geostationary orbit drive qualification investment.
- Vacuum Tube:Traveling-wave tube amplifiers retain efficiency and cost advantages in broadcast uplinks above 500 watts where size constraints relax. Legacy military platforms sustain residual demand.
- Integrated Circuit:Monolithic microwave integrated circuits enable multi-function integration for small-satellite payloads. Silicon germanium and silicon CMOS processes serve lower-frequency S-band applications.
- Hybrid:Solid-state driver stages paired with vacuum tube power sections optimize efficiency across variable output power requirements. Specialized military and scientific missions employ these architectures.
Solid-State technology commands the dominant share. Integrated Circuit implementations are expanding most quickly with constellation miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's satellite manufacturing corridor anchors the Satellite Amplifier Market's geographic concentration, with Colorado's ground station cluster and scattered defense procurement nodes across allied nations completing the demand map.
United States
US Space Force contracts for radiation-hardened GaN amplifiers and FCC spectrum efficiency mandates drive procurement volumes. The Department of Defense's MIL-STD-883 qualification requirements filter supplier access for domestic foundries. California's manufacturing corridor hosts small-satellite builders pursuing disintermediated procurement from compound semiconductor foundries.
Germany
REACH substance restrictions on hexavalent chromium plating and ESA-qualified program requirements shape amplifier housing manufacturing transitions. The EU Green Deal's extended producer responsibility frameworks compress compliance timelines for Ka-band block upconverters. Bavaria's precision engineering clusters adapt coating alternatives for satellite ground segment equipment.
France
Secure connectivity objectives under the EU Space Programme Agency's IRIS² constellation specifications tighten electromagnetic compatibility thresholds for qualified suppliers. ETSI standards govern spectrum allocation and hardware certification requirements. Toulouse's aerospace cluster concentrates prime contractor activity for geostationary orbit missions.
United Kingdom
Post-Brexit regulatory alignment with ETSI frameworks and national space strategy funding redirect amplifier procurement toward domestic qualification capabilities. The UK Space Agency's launch site development in Scotland creates localized demand for ground segment amplification. Harwell's space cluster houses emerging compound semiconductor research facilities.
Japan
METI industrial policy targets wide-bandgap semiconductor manufacturing equipment and gallium substrate supply chain resilience. JIS standards govern electromagnetic compatibility for satellite communication hardware. Tokyo's electronics corridor maintains legacy vacuum tube amplifier production for broadcast uplink applications above 500 watts.
Satellite Amplifier Market Vendor Landscape
Capacity expansion dominates the current landscape as compound semiconductor foundries race to meet defense and constellation procurement timelines. The supplier base fragments between defense-captive production lines with 24-month qualification cycles and commercial-flexible operations serving disintermediated small-satellite builders. Three archetypes occupy distinct positions: legacy defense contractors with radiation-hardening expertise, commercial foundries offering standardized module platforms, and specialist suppliers optimizing for thermal efficiency in compact form factors. Foundry partnerships and technology licensing arrangements represent the dominant competitive moves, with vertical integration into gallium nitride epitaxial wafer production emerging as a secondary priority.
Within the defense-captive archetype, Qorvo occupies a position anchored by compound semiconductor foundry capacity. Almagest Space and AmpliTech Group exemplify contrasting specialization vectors—small-satellite form factor optimization and precision low-noise block design respectively. These three represent the tiered structure separating radiation-hardened qualification capabilities from commercial constellation agility.
| Leading Market Players |
|---|
| mmTron |
| Almagest Space |
| AmpliTech Group |
| Astranis |
| Morpheus Space |
| Qorvo |
| Astrome Technologies |
| Impulse Space |
| Akash Systems |
| Others |
Supply Flow & Price Mechanics
Radiation-hardened qualification tiers split the Satellite Amplifier Market into divergent cost structures, with MIL-STD-883 certified GaN modules commanding substantial premiums over commercial-grade alternatives while gallium substrate scarcity compresses margins across both tiers. This bifurcation concentrates pricing power with domestic foundries serving US Space Force contracts, even as small-satellite builders in California negotiate volume-driven discounts that reshape procurement flows.
Pricing Analysis
Input-cost pass-through from gallium nitride epitaxial wafer pricing dominates amplifier cost structures, with wide-bandgap semiconductor feedstock volatility translating directly into module quotations. Three-tier pricing structure across radiation-hardened, industrial-grade, and commercial-off-the-shelf levels reflects qualification burden differentials rather than performance gaps alone. Cost compression in commercial tiers is intensifying because constellation operators disintermediate traditional aerospace supply chains and negotiate direct foundry relationships. Telecom operators exhibit highest price sensitivity, while defense procurement remains least elastic due to mission-critical reliability requirements.
Supply Chain Analysis
Reverse-logistics flows for amplifier refurbishment remain underdeveloped, with end-of-life traveling-wave tube units typically scrapped rather than remanufactured due to vacuum sealing complexity. Gallium substrate refining concentrates in China and Japan, while compound semiconductor foundry capacity clusters in the United States and Taiwan. Raw material dependencies span high-purity gallium metal, synthetic diamond thermal substrates, and specialized ceramic packaging. Single-source vulnerability in East Asian gallium refining creates supply chain risk. Distribution runs through defense prime contractor networks for qualified hardware, with direct foundry relationships emerging for commercial constellation volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Satellite Amplifier Market functions as a geographic-arbitrage play, with US-based foundries capturing premium pricing from domestic content requirements while European suppliers absorb REACH compliance costs that inflate housing manufacturing expenses.
For Market Incumbents: Acquire compound semiconductor foundry capacity to secure gallium nitride epitaxial wafer supply. Consolidation around radiation-hardening expertise defends against emerging commercial foundries encroaching on defense-adjacent segments. Capacity addition in Colorado's ground station corridor captures localized demand for precision low-noise block downconverters. For New Entrants and Emerging Players: Direct-to-constellation digital procurement platforms bypass traditional aerospace distributor markups. Small-satellite optimized form factors in California's manufacturing corridor represent the most penetrable segment, with standardized S-band and X-band modules enabling rapid customer acquisition. Go-to-market execution should emphasize thermal efficiency benchmarking against legacy aerospace suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with commercial-flexible foundries possessing GaN-on-diamond thermal management capabilities. Long-term viability hinges on constellation deployment sustaining volume demand beyond initial constellation buildout phases. Acquisition targets should display backward integration into gallium substrate sourcing or captive diamond heat spreader production. Practitioners should monitor US Department of Commerce export control expansions on wide-bandgap semiconductor manufacturing equipment for early signals of supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Diamond Thermal Integration | Collapses thermal resistance for decade-plus geostationary missions without liquid cooling architectures. |
| Direct Foundry Procurement Relationships | Disintermediates traditional aerospace supply chain markups for California small-satellite builders. |
| REACH-Compliant Housing Transition | Phases out hexavalent chromium plating for ESA-qualified European constellation programs. |
| Q/V-Band Frequency Expansion | Captures emerging spectrum allocations above 40 GHz for next-generation inter-satellite relay links. |
| Domestic Gallium Substrate Sourcing | Mitigates single-source vulnerability in East Asian wide-bandgap semiconductor feedstock refining. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RF device physicists, defense procurement officers at the US Space Force, constellation program managers, compound semiconductor foundry operations directors, and satellite prime contractor supply chain executives with secondary validation. Regulatory filings from the FCC and ESA, MIL-STD-883 qualification databases, customs records for gallium nitride epitaxial wafer trade flows, and ETSI electromagnetic compatibility certification registries anchored the secondary layer. Bottom-up amplifier shipment estimates triangulated against top-down defense budget allocation analysis.
Historical reference periods anchored the projection horizon through trend extrapolation and technology adoption curve modeling. Segmentation dimensions spanned signal chain position, end-user mission profile, environmental mounting requirements, and underlying device physics. CAGRs derived from volume-weighted average growth across product tiers. Forecast inputs incorporated constellation deployment schedules and spectrum allocation timelines from US and European regulators.
The model assumes a particular technology adoption path; alternative pathways for gallium nitride displacement of gallium arsenide would alter the outlook if thermal management breakthroughs accelerate or substrate costs collapse faster than projected. Forecasts reflect assumptions about defense procurement continuity and export control stability. Practitioners should monitor gallium substrate price volatility and FCC orbital debris rule enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Nano and Microsatellite Market
Satellite
Africa Satellite Connectivity Market
Satellite
Satellite Payload Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Satellite Gateway Market
Satellite
France Satellite Connectivity Market
Satellite
Global Broadband Satellite Services Market
Satellite
Commercial Satellite Launch Service Market
Satellite
EMEA Satellite Antenna Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
UAE Satellite Communication Market
Satellite
Japan Satellite Imagery Services Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Asia-Pacific Satellite Connectivity Market