
 North America Satellite Manufacturing and Launch Systems Market | 2026-2036
North America Satellite Manufacturing and Launch Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Satellite Manufacturing and Launch Systems Market Analytics
Multi-source procurement for propulsion subsystems is broadening across the North American supplier base. Lockheed Martin Corporation sustains long-cycle government satellite programs through captive manufacturing and classified payload integration. Space Exploration Technologies Corp dominates commercial launch cadence with reusable first-stage recovery and vertical integration into engine production.
Satellite manufacturing and launch systems encompass the design, fabrication, testing, and orbital deployment of spacecraft and their associated boost vehicles, typically involving aluminum-lithium alloy structures, composite payload fairings, and liquid oxygen-kerosene or liquid hydrogen-oxygen propulsion cycles rated for specific impulse above 300 seconds. These systems serve telecommunications, Earth observation, navigation, and national security missions requiring precise orbital insertion and operational longevity. Small satellites and Low Earth Orbit configurations lead volume growth as constellation operators prioritize rapid replenishment and distributed architecture over single large-platform geostationary assets. Launch services capture premium margins where dedicated rideshare flexibility and responsive spacelift timelines command price escalation against standardized manifest pooling.
The Federal Aviation Administration licenses commercial launch operations under 51 U.S.C. Chapter 509, while the Federal Communications Commission coordinates spectrum allocation and orbital debris mitigation for communications payloads. NASA and the Space Force impose mission assurance tiers that bifurcate supplier qualification pathways between commercial risk-tolerant and national security rigor categories. Stakeholders must track how export control revisions under the International Traffic in Arms Regulations affect component sourcing from Canadian and Mexican tier-two suppliers.
Market Dynamics
Reusable first-stage recovery is compressing launch economics and forcing satellite manufacturers to redesign for higher launch cadence tolerance, altering procurement timelines and qualification protocols across the supply chain.
Growth Catalysts
- FCC spectrum licensing reforms:Streamlined payload review timelines compress development cycles from 18 months to under 12 months for commercial broadband constellations, accelerating procurement volumes.
- Texas launch facilities:Brownsville and McGregor sites anchor responsive spacelift capacity, drawing propulsion subsystem suppliers and ground infrastructure investment into the Gulf Coast corridor.
- Aluminum-lithium alloy structures:Advanced metallurgy cuts bus mass by 15-20% versus conventional aluminum, enabling larger payload stacks per launch and reducing per-satellite orbital insertion costs.
Market Restraints
- Engine turbopump supply concentration:Domestic casting capacity for superalloy components concentrates in three specialized foundries, creating single-source vulnerability for liquid oxygen-kerosene propulsion cycles.
- ITAR component sourcing friction:Export control revisions complicate procurement from Canadian and Mexican tier-two suppliers, extending lead times for avionics and thermal management subsystems.
- Specific impulse ceiling:Chemical propulsion cycles plateau near 450 seconds for liquid hydrogen-oxygen configurations, limiting payload mass to higher orbits without staging penalties.
Strategic Opportunities
- Quebec satellite manufacturing:Underpenetrated Canadian capacity in Montreal's aerospace cluster offers nearshoring alternatives to California's congested supplier base for composite payload fairings.
- Responsive spacelift procurement:Space Force tactically responsive launch mandates create dedicated rideshare demand separate from commercial manifest pooling, commanding premium pricing for 24-hour call-up capability.
- Dual-use Earth observation convergence:Synthetic aperture radar and hyperspectral imaging fusion enables single-platform service to both defense intelligence and agricultural insurance verticals.
Industry Challenges
- Additive manufacturing technician scarcity:Qualified personnel for superalloy powder-bed fusion of combustion chamber components remain concentrated at three training pipelines, constraining throughput scaling.
- Mission assurance tier bifurcation:NASA Class A versus commercial risk-tolerant qualification pathways force suppliers to maintain dual process documentation, inflating overhead without volume guarantees.
- Orbital debris mitigation certification:FCC post-mission disposal and collision avoidance mandates extend design validation timelines, particularly for Low Earth Orbit constellations requiring automated deorbit reliability demonstration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Satellite Manufacturing and Launch Systems Market |
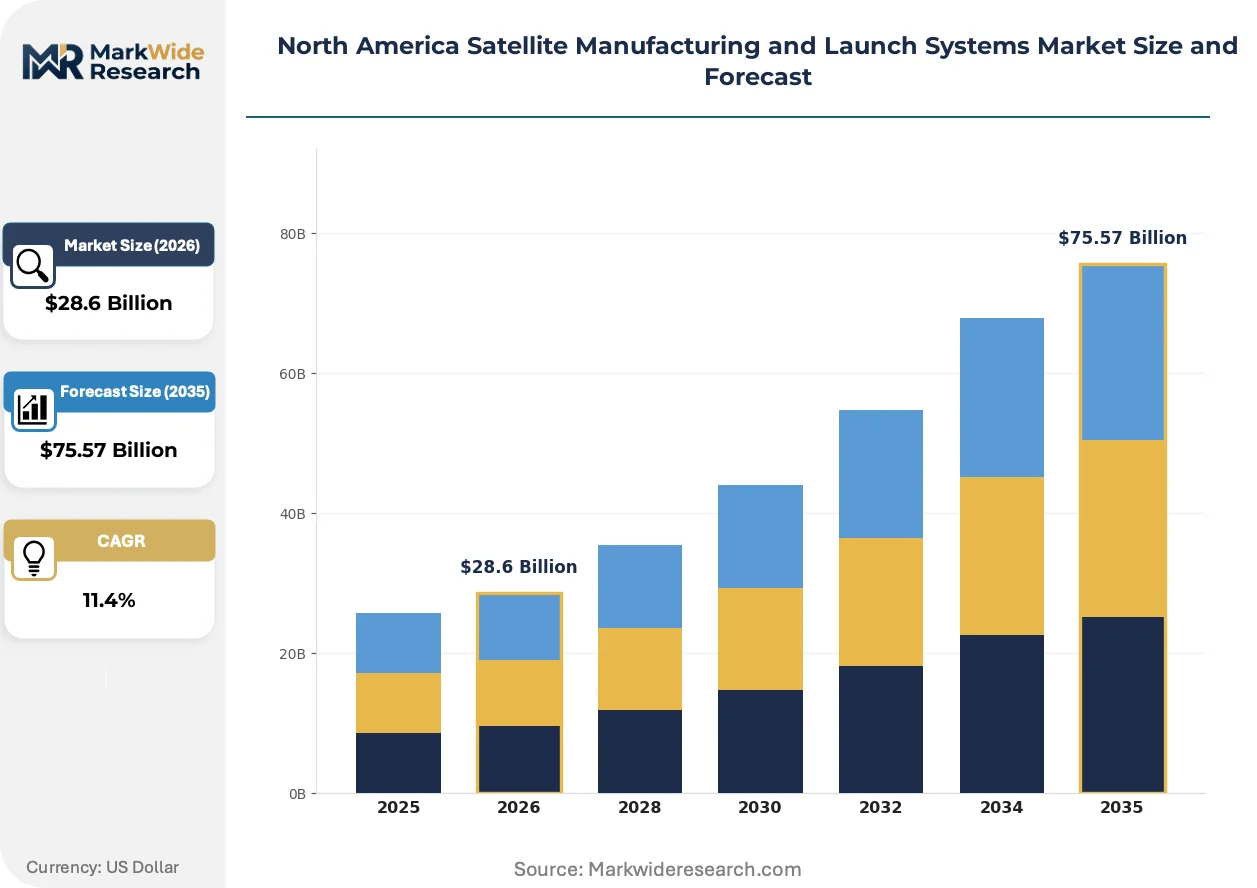
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Satellites, Medium Satellites, Large Satellites, Launch Vehicles Technology: CubeSat, NanoSat, Geostationary, Low Earth Orbit End User: Government, Commercial, Military, Research Institutions Service Type: Launch Services, Manufacturing Services, Ground Services, Integration Services |
| Companies Covered | Space Exploration Technologies Corp, Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, Sierra Nevada Corporation, Thales Group, ArianeGroup, Dynetics Inc, SpaceQuest Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Satellite Manufacturing and Launch Systems Market Evolving Landscape
Additive manufacturing of propulsion hardware is collapsing lead times for combustion devices, while spectrum coordination algorithms and modular payload architectures are rewriting how constellations achieve orbital deployment resilience.
Stainless-steel propellant tanks with welded stringer reinforcement are rewriting structural mass fractions for reusable launch vehicles. SpaceX and emerging competitors adopt this metallurgy for its cryogenic toughness and rapid fabrication versus carbon fiber composites. The shift enables daily flight rates by eliminating autoclave curing bottlenecks and simplifying field repair protocols.
The FAA's streamlined Part 450 launch licensing framework replaces prescriptive requirements with performance-based safety cases. This regulatory architecture reduces application review periods from years to months for experienced operators. California and Texas applicants now pursue site-specific operational authorizations rather than vehicle-class waivers, accelerating manifest flexibility.
Constellation operators now procure satellites through milestone-based payment schedules tied to orbital acceptance rather than manufacturing completion. This performance-risk transfer compresses supplier working capital cycles and aligns contract structures with insurance underwriting timelines. The model dominates commercial broadband deployments, particularly where rapid replenishment requirements demand 50-plus annual deliveries from single vendors.
North America Satellite Manufacturing and Launch Systems Market Segmentation
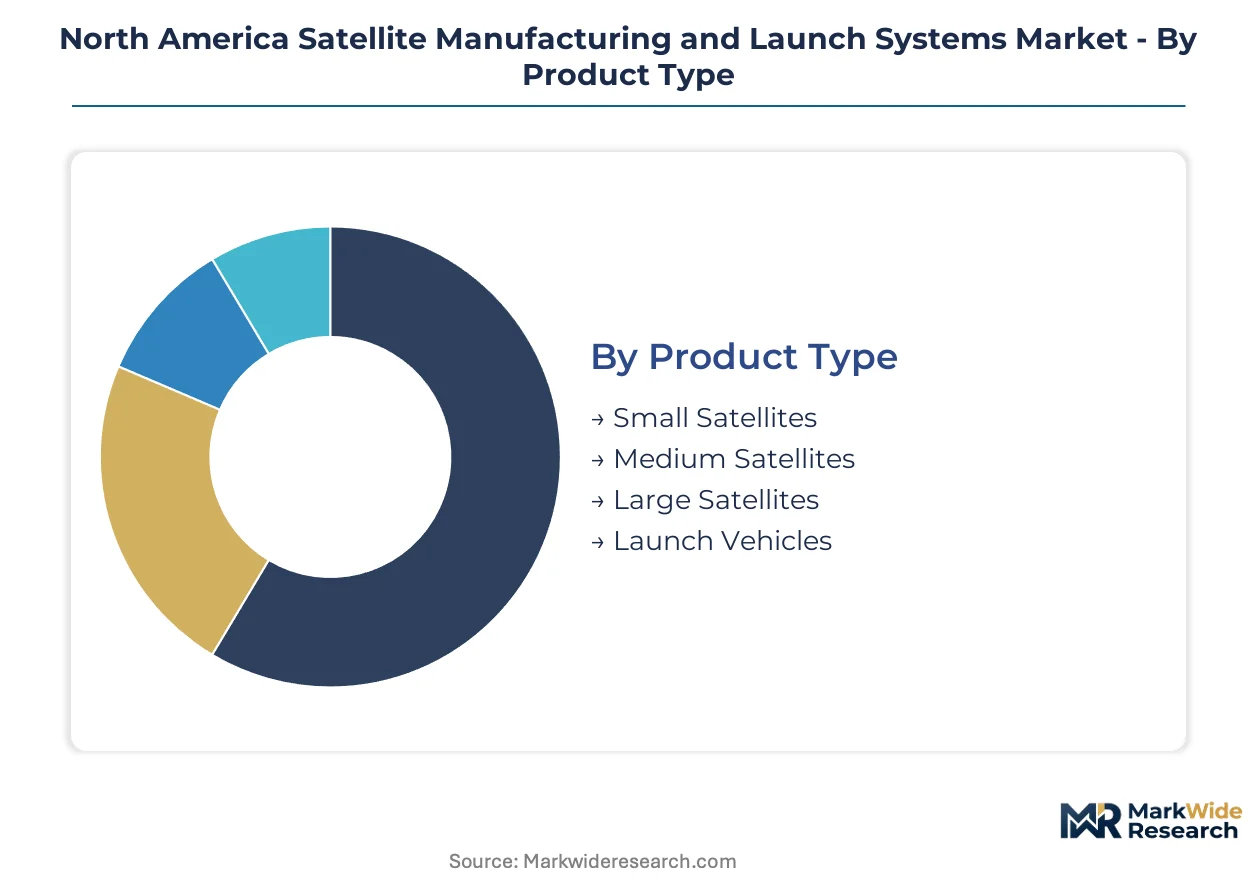
Satellite manufacturing and launch systems fragment across four distinct dimensions that govern procurement patterns and margin structures. Each category reveals how capital deployment, technical risk, and customer mission profiles shape supplier specialization and contract economics across the North American supply base.
Product Type:
Capital intensity peaks with launch vehicles and large geostationary platforms, where development cycles stretch across multiple years and qualification costs dominate program economics.
- Small Satellites:Mass-produced units under 500 kg employ standardized bus architectures and commercial off-the-shelf avionics. Demand concentrates in California's aerospace corridor for broadband constellation replenishment, where FCC streamlined licensing accelerates procurement cadence.
- Launch Vehicles:Reusable first-stage systems demand the heaviest upfront investment in propulsion test infrastructure and recovery vessel fleets. Texas launch facilities anchor capacity expansion, drawing superalloy foundry suppliers into the Gulf Coast corridor to reduce logistics friction for engine components.
- Medium Satellites:500-2,500 kg platforms balance custom payload accommodation with production scale.
- Large Satellites:Geostationary and deep-space platforms require mission-assurance rigor and extended qualification protocols.
Most installed capacity flows through Launch Vehicles. Expansion is steepest in Small Satellites.
Technology:
Orbit selection dictates thermal management complexity, propulsion requirements, and ground infrastructure investment, creating divergent supplier capability clusters.
- Low Earth Orbit:Altitudes below 2,000 km enable low-latency communications and rapid revisit Earth observation. Commercial broadband operators in Texas and California drive volume procurement, with automated manufacturing lines achieving 50-plus annual unit deliveries from single vendors.
- Geostationary:Fixed orbital slots at 35,786 km demand precision station-keeping propulsion and radiation-hardened electronics. Government and military customers sustain procurement through classified payload integration programs requiring captive manufacturing at cleared facilities.
- CubeSat:Standardized 10 cm form factors lower university and research access barriers.
- NanoSat:1-10 kg platforms bridge educational missions and commercial technology demonstration.
Geostationary retains the highest revenue per unit. Low Earth Orbit is gaining share fastest.
End User:
Customer type bifurcates supplier qualification pathways between risk-tolerant commercial procurement and mission-assurance rigor for national security applications.
- Commercial:Constellation operators prioritize cost-per-kilogram and launch cadence over individual unit reliability. Milestone-based payment schedules tied to orbital acceptance now dominate contract structures, compressing supplier working capital cycles and aligning with insurance underwriting timelines.
- Military:Space Force tactically responsive launch mandates create dedicated rideshare demand separate from commercial manifest pooling. Premium pricing attaches to 24-hour call-up capability and hardened communication protocols.
- Government:NASA science missions impose Class A mission assurance tiers with extensive documentation requirements.
- Research Institutions:University and laboratory payloads emphasize rapid access and technology demonstration flexibility.
Commercial accounts for the highest procurement volume. Military spending is climbing the fastest.
Service Type:
Value capture varies sharply across the satellite lifecycle, with launch services commanding premium margins where dedicated manifest flexibility differentiates from commodity rideshare.
- Launch Services:Orbital insertion contracts bundle vehicle provision, range coordination, and payload integration. FCC spectrum licensing reforms compress development cycles, accelerating procurement volumes for commercial broadband constellations seeking responsive spacelift timelines.
- Manufacturing Services:Satellite bus and payload fabrication spans aluminum-lithium alloy structures through composite payload fairings. California's congested supplier base drives nearshoring exploration into Quebec's underpenetrated Montreal aerospace cluster.
- Ground Services:Telemetry, tracking, and command infrastructure supports post-launch operations.
- Integration Services:Payload-to-bus mating and environmental testing precede launch site delivery.
Launch Services captures the highest margin per contract. Manufacturing Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's aerospace corridor concentrates satellite manufacturing capacity, drawing composite fabrication and avionics suppliers into a tightly clustered supply chain. Texas launch facilities anchor orbital insertion services, while regulatory coordination between the FAA and FCC shapes deployment timelines across the continent.
United States
Commercial broadband constellations and Space Force tactically responsive launch mandates drive procurement volumes. The FAA licenses commercial launch operations under 51 U.S.C. Chapter 509, while the FCC coordinates spectrum allocation and orbital debris mitigation. California's congested supplier base in Los Angeles and the Bay Area forces nearshoring exploration for composite payload fairings.
Canada
Underpenetrated satellite manufacturing capacity in Montreal's aerospace cluster offers alternatives to California supplier congestion. Health Canada and the Canadian Space Agency coordinate payload review timelines with FCC reforms to compress development cycles. Quebec's composite fabrication facilities draw propulsion subsystem suppliers seeking reduced logistics friction.
Mexico
Tier-two avionics and thermal management component sourcing extends lead times due to ITAR export control complications. The country's national trade regulator coordinates with U.S. authorities on dual-use technology transfers. Baja California and Chihuahua manufacturing zones host satellite subsystem suppliers navigating cross-border qualification protocols.
North America Satellite Manufacturing and Launch Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue reusable launch vehicle economics and rapid constellation replenishment services. The supplier base concentrates around three capability clusters: captive government program integration, commercial launch cadence dominance, and specialized subsystem fabrication. Strategic differentiation hinges on vertical integration depth versus modular supplier networks, with competitive moves centering on propulsion test infrastructure expansion and milestone-based contract restructuring.
Within the integrated launch services tier, Space Exploration Technologies Corp exemplifies reusable first-stage recovery economics, while Lockheed Martin Corporation anchors long-cycle government satellite programs through classified payload integration. Northrop Grumman Corporation occupies a position bridging commercial and national security mission assurance tiers.
| Leading Market Players |
|---|
| Space Exploration Technologies Corp |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| Sierra Nevada Corporation |
| Thales Group |
| ArianeGroup |
| Dynetics Inc |
| SpaceQuest Ltd |
| Others |
Value Network & Pricing Analysis
FCC orbital debris mitigation mandates gate qualified supplier status and premium-tier pricing access for constellation operators seeking expedited licensing pathways. Buyers without certified end-of-life disposal systems face extended review timelines that compress their pricing power against vendors with pre-qualified mission assurance packages.
Pricing Analysis
Input-cost pass-through from superalloy foundry capacity constraints shapes contract structures across the propulsion subsystem tier. Launch services command three-tier pricing differentiation across dedicated rideshare, responsive spacelift, and commodity manifest pooling, with certification grade and volume scale as primary drivers. Pricing pressure stems from reusable first-stage recovery economics forcing margin compression in expendable vehicle segments. Commercial constellation operators exhibit highest price sensitivity, while Space Force tactically responsive launch mandates sustain premium tolerance for 24-hour call-up capability.
Supply Chain Analysis
Domestic-content mandates under ITAR revisions are reshaping sourcing patterns for avionics and thermal management subsystems across the North American supplier base. Manufacturing concentrates in the United States, Canada, and Mexico, with California's aerospace corridor and Texas launch facilities anchoring production gravity. The supply chain draws from aluminum-lithium alloy structures, composite payload fairings, and superalloy combustion components, with single-source vulnerability concentrated in domestic turbopump casting capacity. Distribution runs through vertically integrated prime contractors and specialized tier-two subsystem vendors serving dual commercial-military qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's underpenetrated Montreal aerospace cluster offers geographic-arbitrage advantages against California supplier congestion, with Health Canada payload review coordination reducing regulatory friction versus FCC timelines.
For Market Incumbents: Extend captive manufacturing capabilities into responsive spacelift segments where Space Force premium pricing offsets commercial margin erosion. Consolidate superalloy foundry relationships through long-term offtake agreements to defend against emerging entrant vertical integration into propulsion hardware. Lockheed Martin and Northrop Grumman should leverage classified payload integration clearance as a certification moat.
For New Entrants and Emerging Players: Capture milestone-based contract structures in small satellite manufacturing where automated production lines enable 50-plus annual unit deliveries. Quebec composite fabrication capacity represents the most penetrable white-space target, with Health Canada regulatory alignment offering faster qualification than California's congested supplier base. Pursue dual-use Earth observation convergence as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two propulsion subsystem suppliers lacking vertical integration into engine production but holding ITAR-compliant manufacturing infrastructure. Long-term viability hinges on positioning for tactically responsive launch procurement growth and additive manufacturing technician pipeline control. Watch FCC spectrum licensing backlog clearance as the inflection signal for constellation operator capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Responsive Spacelift Capacity Expansion | Space Force tactically responsive launch mandates create premium pricing tiers for 24-hour call-up capability. |
| Additive Manufacturing Infrastructure Buildout | Superalloy powder-bed fusion of combustion chambers collapses lead times for reusable engine components. |
| Quebec Nearshoring Partnership | Montreal's aerospace cluster offers reduced logistics friction versus California's congested supplier base. |
| Dual-Use Payload Architecture Development | Synthetic aperture radar fusion serves both defense intelligence and agricultural insurance verticals simultaneously. |
| Milestone-Based Contract Restructuring | Orbital acceptance payment schedules align supplier working capital with insurance underwriting timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with satellite program managers, propulsion subsystem procurement leads, FCC licensing officers, Space Force tactically responsive launch coordinators, and additive manufacturing technicians with secondary validation against FAA launch licensing databases, FCC spectrum allocation records, NASA mission assurance documentation, SEC contractor filings, and customs trade data for aluminum-lithium alloy and superalloy inputs. Bottom-up vendor capacity assessments and top-down constellation deployment forecasts were triangulated to anchor volume projections.
Segment-weighting approaches distributed value across small satellite, launch vehicle, medium satellite, and large satellite product types, with Low Earth Orbit and Geostationary technology tiers, Commercial and Military end-user categories, and Launch Services versus Manufacturing Services value capture models modeled explicitly across the projection horizon. CAGRs were derived from deployment trajectory analysis and procurement cadence normalization, with FCC streamlined licensing timeline compression and reusable first-stage recovery economics as primary forecast inputs.
ITAR regulatory revision timing, superalloy foundry capacity expansion velocity, and Space Force budget authorization volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding constellation operator replenishment rates and additive manufacturing technician pipeline scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Small Satellite Service Market
Satellite
Satellite Gateway Market
Satellite
North America Military Satellite Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Broadband Satellite System Market
Satellite
Commercial LEO Satellite Market
Satellite
High-Throughput Satellite Market
Satellite
North America Satellite IoT Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Global Enterprise VSAT System Market
Satellite
France Satellite Imagery Services Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Canada Satellite Connectivity Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
All-Electric Propulsion Satellites Market