
 Global Dish Antennas Market | 2026-2036
Global Dish Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dish Antennas Market Foresight
Phased array integration with traditional parabolic architectures is reconfiguring manufacturing priorities across the supply base. Cobham Limited leverages its defense heritage to dominate military-grade precision installations. Mitsubishi Electric Corporation anchors Asia-Pacific production through vertically integrated ceramic feedhorn operations. Viasat, Inc. competes on Ka-band terminal density for mobility applications.
Dish antennas are directional parabolic reflectors engineered from aluminum, composite, or steel substrates, typically ranging from 0.6 to 30 meters in diameter, designed to focus electromagnetic energy onto a feed assembly for reception or transmission in satellite and terrestrial microwave links. Fixed dish antennas occupy the volume base in direct-to-home broadcasting, while Ka-band technology captures the fastest expansion trajectory driven by high-throughput satellite constellations. Motorized dish antennas command premium positioning in maritime and aeronautical mobility segments where continuous tracking is mission-critical.
The FCC enforces transmit power and out-of-band emission limits that dictate amplifier and feed system designs for U.S.-market equipment, while the EU Radio Equipment Directive mandates CE marking for electromagnetic compatibility across member states. India's WPC issues frequency authorization guidelines that constrain C-band deployment in dense urban corridors. Stakeholders must monitor spectrum auction outcomes and orbital slot filings to anticipate capacity deployment cycles and antenna specification shifts.
Market Dynamics
Spectrum reallocation mandates are compressing deployment timelines for C-band infrastructure while Ka-band constellations force feedhorn redesigns across the supply base. Military procurement cycles now prioritize electronically steered arrays over mechanically actuated systems.
Growth Catalysts
- High-throughput satellite constellations:Low Earth orbit deployments by SpaceX and Amazon's Project Kuiper are saturating orbital slots and mandating terminal density improvements for consumer broadband.
- India's BharatNet rural expansion:The Universal Service Obligation Fund is subsidizing satellite backhaul for village-level connectivity, creating concentrated demand for 2.4-meter and 3.8-meter fixed dishes.
- FCC 3.7-4.2 GHz reallocation:The mandate to clear C-band for 5G terrestrial use is forcing broadcasters and cable operators into accelerated antenna replacement programs.
Market Restraints
- Aluminum price volatility:Reflective surface substrates constitute 35-40% of bill-of-materials cost, and LME pricing swings compress margin predictability for mid-tier fabricators.
- Feedhorn ceramic supply concentration:High-purity alumina substrates for Ka-band waveguides concentrate in Japanese and German specialty ceramic houses, creating single-source vulnerability.
- Phased array substitution threat:Flat-panel electronically steered antennas are displacing parabolic architectures in maritime and aeronautical mobility segments above 10,000 units annually.
Strategic Opportunities
- Indonesia's Palapa Ring completion:The eastern islands segment remains underserved by fiber, creating white space for satellite backhaul terminals in Papua and Maluku provinces.
- EU Green Deal procurement criteria:Public sector tenders now embed embodied carbon scoring for aluminum and composite substrates, favoring recycled-content suppliers.
- 5G backhaul convergence:Integrated satellite-terrestrial terminals that combine dish antennas with millimeter-wave radio heads are opening mobile network operator procurement channels.
Industry Challenges
- Electromagnetic compatibility certification:CE marking under the EU Radio Equipment Directive requires anechoic chamber testing that adds 8-14 weeks to product launch timelines.
- Phased array integration complexity:Hybrid architectures combining parabolic reflectors with active phased array feeds demand RF engineering talent scarce outside defense contractor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dish Antennas Market |
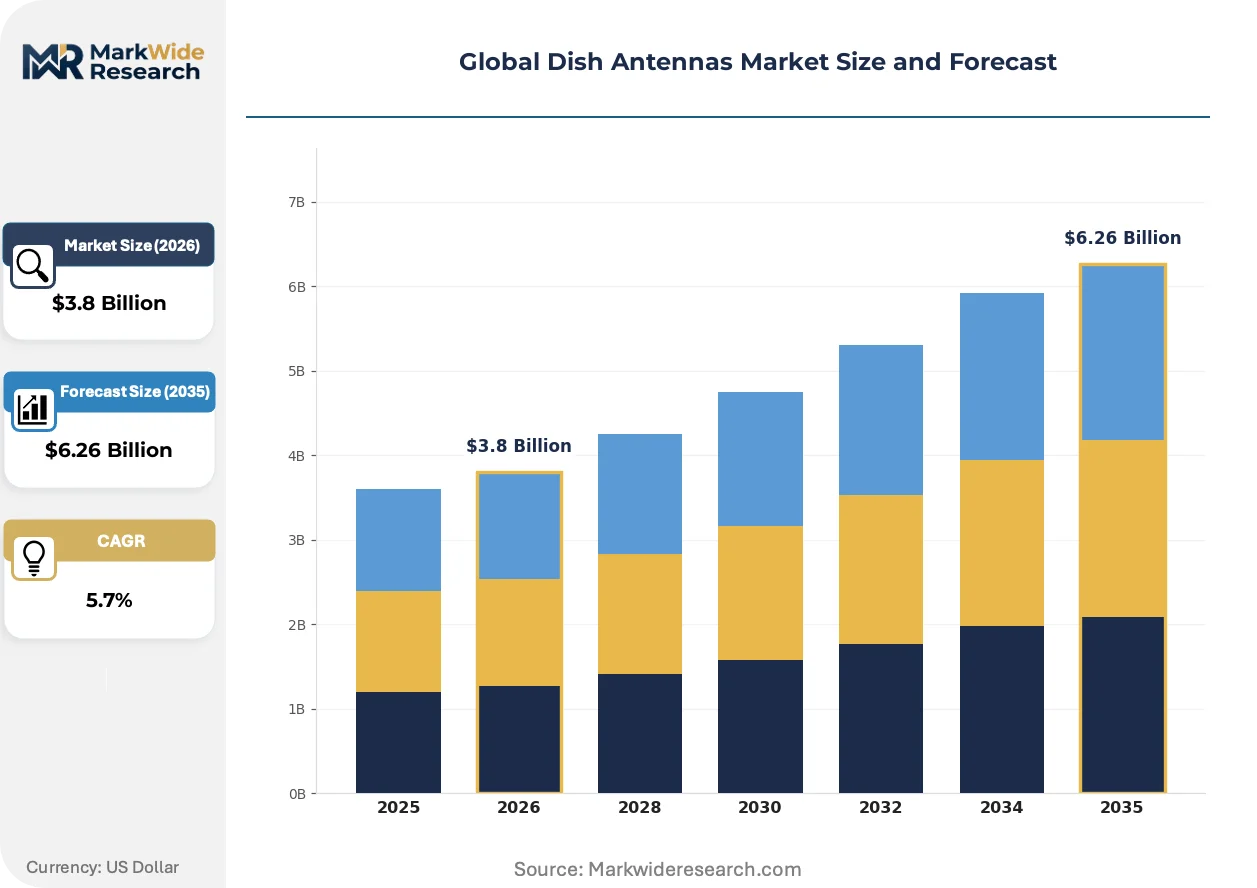
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Dish Antennas, Motorized Dish Antennas, Portable Dish Antennas, Offset Dish Antennas Technology: K_u Band, K_a Band, C Band, X Band, S Band Application: Direct-to-Home, Satellite Communication, Telemetry, Data Broadcasting, Military Communications End User: Telecommunication Operators, Broadcasting Companies, Defense Sector, Internet Service Providers, Maritime Industry |
| Companies Covered | Cobham Limited, Hughes Network Systems, Honeywell International Inc., CPI International, Airbus S.A.S., Mitsubishi Electric Corporation, Viasat, Inc., C-COM Satellite Systems Inc., L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dish Antennas Market Shifts & Advancements
Active antenna systems are compressing the boundary between traditional reflector physics and solid-state beamforming. Three concurrent developments are restructuring competitive positioning and procurement specifications.
Metamaterial-enabled flat reflectors are hybridizing electromagnetic performance with mechanical simplicity. These engineered surfaces manipulate wavefronts through subwavelength structures rather than parabolic curvature, enabling satellite TV reception from wall-mounted form factors. European direct-to-home operators are piloting these in multi-dwelling units where balcony dish placement is restricted, compressing installation costs by eliminating motorized pointing systems.
The EU Radio Equipment Directive's 2024 cybersecurity annex is mandating firmware integrity verification for all network-connected terminals. Dish antenna controllers with IP interfaces must now demonstrate secure boot capabilities and encrypted over-the-air update mechanisms. German and French satellite broadband providers are accelerating procurement of compliant terminals ahead of the enforcement deadline, shifting supplier qualification criteria toward embedded systems expertise.
Defense contractors are consolidating vendor relationships around dual-use qualification status. The US Department of Defense's Commercial Solutions for Classified program now permits satellite terminals originally developed for military applications to serve civilian federal agencies without redundant certification cycles. This channel consolidation favors suppliers with existing JITC interoperability listings, compressing qualification timelines for incumbents while extending barriers for new market entrants.
Global Dish Antennas Market Segmentation
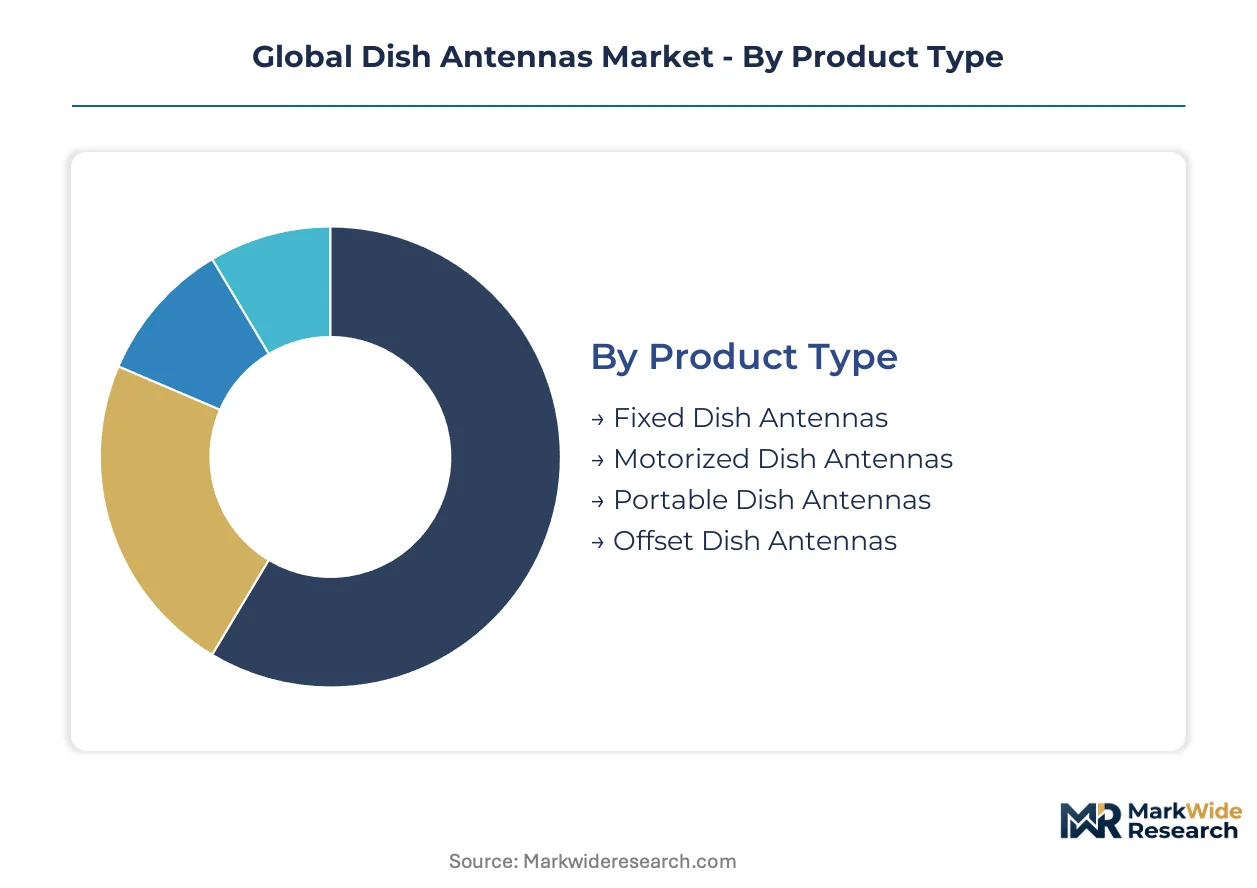
Dish antenna specifications diverge sharply across deployment contexts, from fixed rooftop installations to maritime tracking systems. Understanding these segment boundaries clarifies where component standardization ends and custom engineering begins.
Product Type:
Mechanical configuration determines installation complexity, maintenance schedules, and total cost of ownership across customer budgets.
- Fixed Dish Antennas:Stationary parabolic reflectors mounted on rooftops or ground pads dominate direct-to-home broadcasting volumes. India's BharatNet rural expansion is concentrating procurement of 2.4-meter and 3.8-meter fixed dishes for village-level satellite backhaul.
- Motorized Dish Antennas:Azimuth-elevation actuators enable continuous satellite tracking for mobile platforms. Maritime and aeronautical operators in Indonesia's eastern islands specify these for uninterrupted connectivity across Papua and Maluku provinces.
- Portable Dish Antennas:Rapid-deploy tripods and flyaway kits serve emergency response and military field operations. Defense contractors prioritize compact stowage dimensions for air-transportable communications nodes.
- Offset Dish Antennas:Asymmetric reflector geometry positions the feed assembly outside the primary signal path, reducing blockage. European multi-dwelling units deploy these where balcony mounting restrictions apply.
Fixed configurations command the established base. The steepest expansion runs through motorized architectures for mobility applications.
Technology:
Frequency band selection governs atmospheric attenuation characteristics, orbital slot availability, and regulatory licensing requirements in each operating territory.
- K_a Band:High-frequency operation above 26 GHz enables dense frequency reuse for high-throughput satellite constellations. SpaceX and Amazon's Project Kuiper deployments are mandating terminal density improvements for consumer broadband.
- K_u Band:The 12-18 GHz range balances rain fade resilience with antenna compactness for direct-to-home services. Broadcasters across Germany and France maintain established receiver ecosystems in this spectrum.
- C Band:Lower frequencies penetrate heavy precipitation but require larger reflector diameters. The FCC's 3.7-4.2 GHz reallocation is forcing accelerated replacement programs among U.S. cable operators.
- X Band:Military-allocated spectrum around 8 GHz supports secure communications with anti-jam characteristics. NATO interoperability specifications dominate procurement criteria for defense contractors.
- S Band:Mobile satellite services utilize this range for handheld and vehicular terminals. Maritime safety systems specify S-band links for global distress signaling compliance.
K_u Band retains the installed base. K_a Band frequencies are climbing the fastest as constellation operators saturate orbital slots.
Application:
Use-case differentiation separates consumer entertainment markets from mission-critical infrastructure where outage tolerance approaches zero.
- Direct-to-Home:Satellite television distribution to residential rooftops represents the volume foundation. India's rural broadband programs are subsidizing fixed-dish installations for village connectivity.
- Satellite Communication:Enterprise and government backhaul links demand higher availability tiers than consumer services. Indonesia's Palapa Ring completion gaps in Papua drive concentrated terminal procurement.
- Telemetry:Data collection from remote sensors and unmanned platforms requires low-latency uplink capability. Scientific research stations in Antarctica and Greenland specify ruggedized terminals for polar operations.
- Data Broadcasting:Multicast content distribution to edge caching nodes reduces terrestrial bandwidth requirements. Content delivery networks deploy receive-only dishes at regional headends.
- Military Communications:Anti-jam and low-probability-of-intercept modes distinguish defense specifications from commercial equivalents. The U.S. Department of Defense's Commercial Solutions for Classified program accelerates dual-use terminal qualification.
Direct-to-Home commands the established base. Military Communications is gaining share fastest as electronically steered arrays displace mechanical systems.
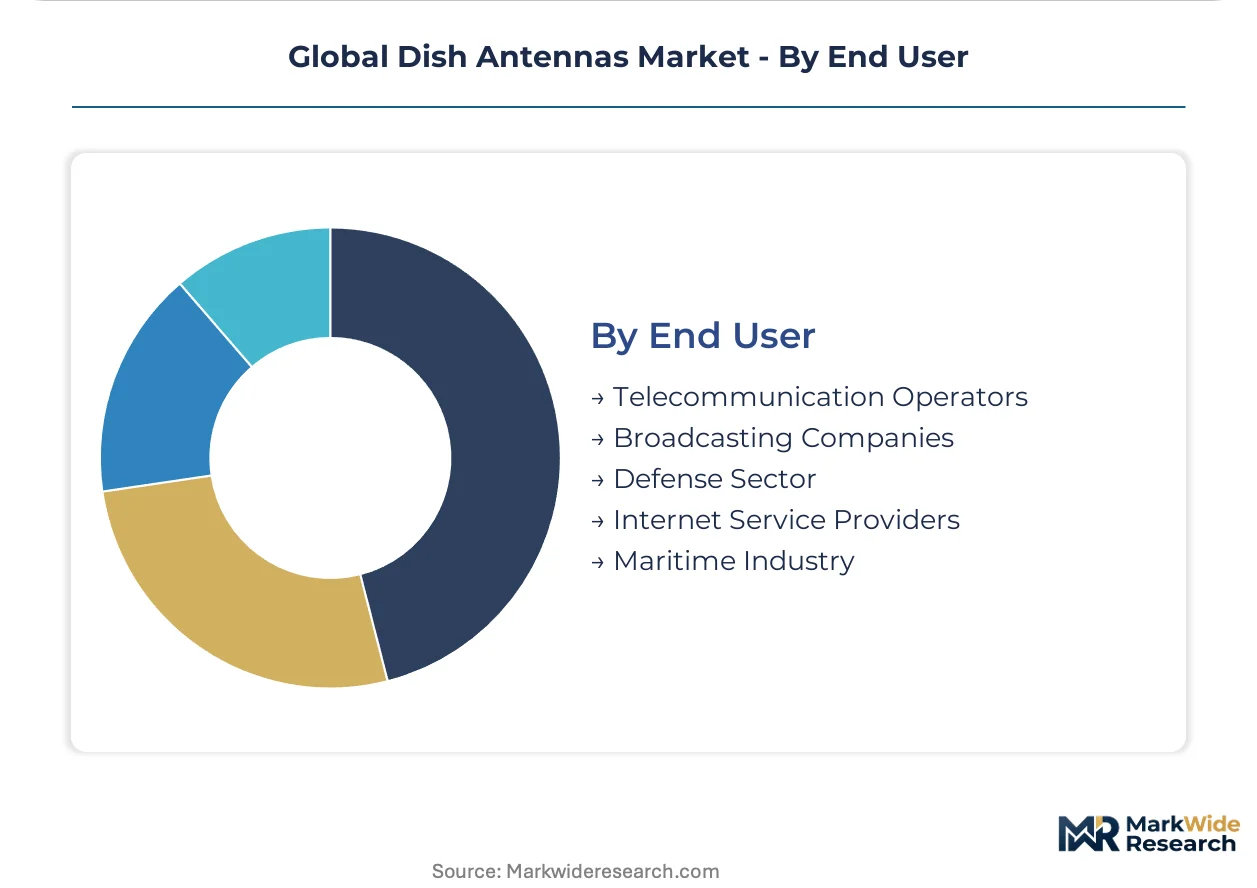
End User:
Customer organizational type shapes procurement channels, contract structures, and technical support expectations.
- Telecommunication Operators:Mobile network operators integrate satellite backhaul for rural cell site coverage. 5G millimeter-wave convergence is opening procurement channels for combined satellite-terrestrial terminals.
- Broadcasting Companies:Television networks and cable operators maintain receive facilities for content aggregation. FCC spectrum reallocation mandates are compressing C-band infrastructure replacement timelines.
- Defense Sector:Military procurement prioritizes JITC interoperability listings and dual-use qualification status. Cobham Limited leverages defense heritage for precision installation contracts.
- Internet Service Providers:Fixed wireless and satellite broadband retailers serve subscriber bases with varying data consumption profiles. India's Universal Service Obligation Fund concentrates demand among rural-focused ISPs.
- Maritime Industry:Commercial shipping and offshore platforms require continuous connectivity across oceanic routes. Phased array substitution threatens parabolic architectures above 10,000 annual units in this segment.
Telecommunication Operators command the established base. The Defense Sector is expanding most quickly through electronically steered array procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered feedhorn assemblies to satellite operators across the Middle East and Southeast Asia, establishing a critical trade corridor for Ka-band terminal components.
United States
The FCC's 3.7-4.2 GHz reallocation is compressing C-band infrastructure replacement timelines among broadcasters and cable operators. Military procurement through the Department of Defense's Commercial Solutions for Classified program accelerates dual-use terminal qualification. Defense contractors cluster around Huntsville, Alabama, where JITC interoperability testing facilities concentrate precision installation expertise.
Germany
The EU Radio Equipment Directive's 2024 cybersecurity annex mandates firmware integrity verification for network-connected terminals. German satellite broadband providers accelerate procurement of compliant terminals ahead of enforcement deadlines. Industrial fabricators concentrate in Bavaria, where anechoic chamber testing infrastructure supports CE marking certification cycles.
India
The Universal Service Obligation Fund subsidizes satellite backhaul for village-level connectivity under BharatNet rural expansion programs. The Wireless Planning and Coordination Wing issues frequency authorization guidelines constraining C-band deployment in dense urban corridors. Fabrication demand concentrates in Gujarat, where 2.4-meter and 3.8-meter fixed dish production scales for rural broadband installation.
Japan
High-purity alumina substrate supply for Ka-band waveguides concentrates in Japanese specialty ceramic houses, creating single-source vulnerability for feedhorn components. METI standards govern electromagnetic compatibility certification for satellite terminal exports. Manufacturing gravity centers on Nagoya, where vertically integrated ceramic feedhorn operations anchor Asia-Pacific production.
Indonesia
The Palapa Ring completion leaves eastern islands segments underserved by fiber, creating white space for satellite backhaul terminals. Maritime and aeronautical operators in Papua and Maluku provinces specify motorized dish antennas for uninterrupted connectivity. Installation activity concentrates in Jayapura, where terrain challenges prevent terrestrial infrastructure deployment.
Global Dish Antennas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. The vendor base separates into defense heritage contractors, commercial satellite terminal specialists, and vertically integrated electronics conglomerates. Three archetypes dominate: precision installation contractors serving military-grade specifications, Ka-band density specialists competing on terminal miniaturization, and composite substrate fabricators optimizing for embodied carbon scoring. Competitive moves concentrate on dual-use qualification status acquisition and strategic partnerships for phased array feed integration.
Within the defense heritage tier, Cobham Limited and L3Harris Technologies, Inc. exemplify precision installation contractors leveraging JITC interoperability listings. Mitsubishi Electric Corporation anchors Asia-Pacific production capabilities. Viasat, Inc. occupies a position among Ka-band terminal density specialists competing for mobility application procurement.
| Leading Market Players |
|---|
| Cobham Limited |
| Hughes Network Systems |
| Honeywell International Inc. |
| CPI International |
| Airbus S.A.S. |
| Mitsubishi Electric Corporation |
| Viasat, Inc. |
| C-COM Satellite Systems Inc. |
| L3Harris Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Nagoya's vertically integrated ceramic feedhorn operations anchor Asia-Pacific production capacity, concentrating supply-side leverage for Ka-band waveguide components and compressing margin flexibility for downstream terminal assemblers competing on consumer broadband density.
Pricing Analysis
Current-generation Ka-band terminals command premium positioning against legacy Ku-band installations and developmental phased-array alternatives. Three-tier pricing structure across premium, standard, and economy levels separates JITC-certified defense contractors from commercial satellite operators and rural broadband subsidized programs. Cost compression in aluminum reflector substrates is intensifying because LME pricing volatility erodes fabricator predictability. Broadcasting companies exhibit highest price sensitivity due to accelerated C-band replacement mandates, while defense contractors absorb premiums for dual-use qualification status.
Supply Chain Analysis
Export control regimes under ITAR and EAR classifications restrict high-purity alumina substrate flows for Ka-band waveguides, constraining feedhorn sourcing options. Manufacturing gravity centers on Japan, Germany, and India for ceramic components, aluminum reflector fabrication, and rural terminal assembly respectively. Raw material dependencies span LME-grade aluminum, high-purity alumina, and composite substrates. Single-source vulnerability in Japanese specialty ceramic houses creates supply chain risk. Distribution runs through defense contractor procurement channels, satellite operator direct agreements, and Universal Service Obligation Fund subsidized tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dish antenna market sits at a platform-economics inflection where JITC interoperability listings and dual-use qualification status create winner-take-most dynamics, reinforced by the U.S. Department of Defense's Commercial Solutions for Classified program collapsing redundant certification cycles.
For Market Incumbents: Insulate defense heritage advantages through accelerated dual-use qualification under CSfC protocols while deepening backward integration into ceramic feedhorn production to offset Japanese supply concentration. Phased array substitution in maritime mobility above 10,000 annual units threatens parabolic architectures. Certification investment in EU Radio Equipment Directive cybersecurity annex compliance secures procurement channel control ahead of enforcement deadlines. For New Entrants and Emerging Players: Indonesia's eastern islands fiber gaps in Papua and Maluku provinces represent the most penetrable entry point for satellite backhaul terminals, with motorized dish specifications dominating maritime and aeronautical procurement. India's BharatNet rural expansion concentrates subsidized demand for 2.4-meter and 3.8-meter fixed dishes among ISPs. Go-to-market execution through Universal Service Obligation Fund tender participation bypasses incumbent channel relationships. For Investors and Strategic Acquirers: Long-term, this sits as a defense-civilian convergence play because spectrum reallocation mandates and constellation deployment cycles create sustained replacement demand across dual-use applications. Acquisition targets with existing JITC interoperability listings and embedded systems firmware capabilities command structural scarcity premiums. The signal to watch is FCC spectrum auction outcomes and orbital slot filings as capacity deployment cycle indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Qualification Acceleration | CSfC program listings collapse certification timelines for defense and civilian federal procurement channels. |
| Ceramic Feedhorn Backward Integration | In-house alumina substrate production mitigates single-source vulnerability in Japanese specialty houses. |
| EU Cybersecurity Annex Compliance | Firmware integrity verification capabilities shift supplier qualification criteria toward embedded systems expertise. |
| Phased Array Feed Partnership | Hybrid parabolic-active antenna architectures address RF engineering talent scarcity outside defense ecosystems. |
| Recycled-Content Composite Sourcing | EU Green Deal embodied carbon scoring favors suppliers with circular aluminum and composite substrate supply. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, satellite operator network engineers, rural ISP deployment managers, and ceramic component sourcing leads, then refined through secondary validation against FCC spectrum allocation records, EU Radio Equipment Directive filings, customs trade data for aluminum and alumina flows, and satellite operator capex disclosures. Bottom-up installation volume estimates triangulated with top-down market value reconstruction across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling segmentation across product type, frequency band, application, and end user throughout the forecast period. CAGRs derived from installed base replacement cycles, constellation deployment timelines, and regulatory mandate compliance schedules. Industry-specific inputs incorporated BharatNet subsidy disbursement patterns and Palapa Ring completion status for eastern Indonesia connectivity gaps.
Practitioners should monitor FCC spectrum auction outcomes, EU cybersecurity annex enforcement timing, and SpaceX-Amazon constellation deployment velocity for early signals of specification shifts and procurement cycle acceleration. Forecasts reflect documented assumptions regarding aluminum price stability and orbital slot availability. Material shifts in ITAR/EAR export control scope or Japanese ceramic supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Backhaul Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
High-Throughput Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
North America Satellite Bus Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Satellite Communication Equipment Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Electric Propulsion Satellite Market
Satellite
Global LEO Satellite Market
Satellite
Satellite Signal Meter Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Mexico Satellite Connectivity Market