
 Asia-Pacific Remote Sensing Satellites Market | 2026-2036
Asia-Pacific Remote Sensing Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Remote Sensing Satellites Market Insights
Project finance through sovereign-backed satellite leasing is fragmenting competitive entry barriers across the Asia-Pacific. Chang Guang Satellite Technology leverages captive manufacturing of optical payloads to control unit economics at scale. ISRO sustains cost leadership through its Polar Satellite Launch Vehicle program and technology transfer to NewSpace ventures. Mitsubishi Heavy Industries anchors high-reliability radar platforms for Japanese defense and climate monitoring contracts.
Asia-Pacific remote sensing satellites orbit Earth to capture multispectral, radar, and hyperspectral data at resolutions reaching sub-meter ground sample distance for commercial and government analysis. Synthetic aperture radar penetrates cloud cover and darkness, enabling all-weather disaster response and maritime surveillance where optical sensors fail. Earth observation payloads command the largest revenue share as governments fund persistent coverage for territorial monitoring and climate tracking. Defense operations represent the fastest-growing application segment, with classified procurement shifting toward dual-use radar and hyperspectral systems that serve both military reconnaissance and environmental validation.
Japan's METI sets national space industrial policy through its Basic Plan on Space Policy, while China's MIIT and SAMR govern commercial remote sensing licensing and data security protocols that restrict cross-border imagery flows. India's BIS and ISRO jointly enforce technical standards for domestic satellite manufacturing and ground segment interoperability. Stakeholders must monitor how export control alignment between METI, India's DGFT, and China's SAMR reshapes component sourcing and constellation deployment timelines across the region.
Market Dynamics
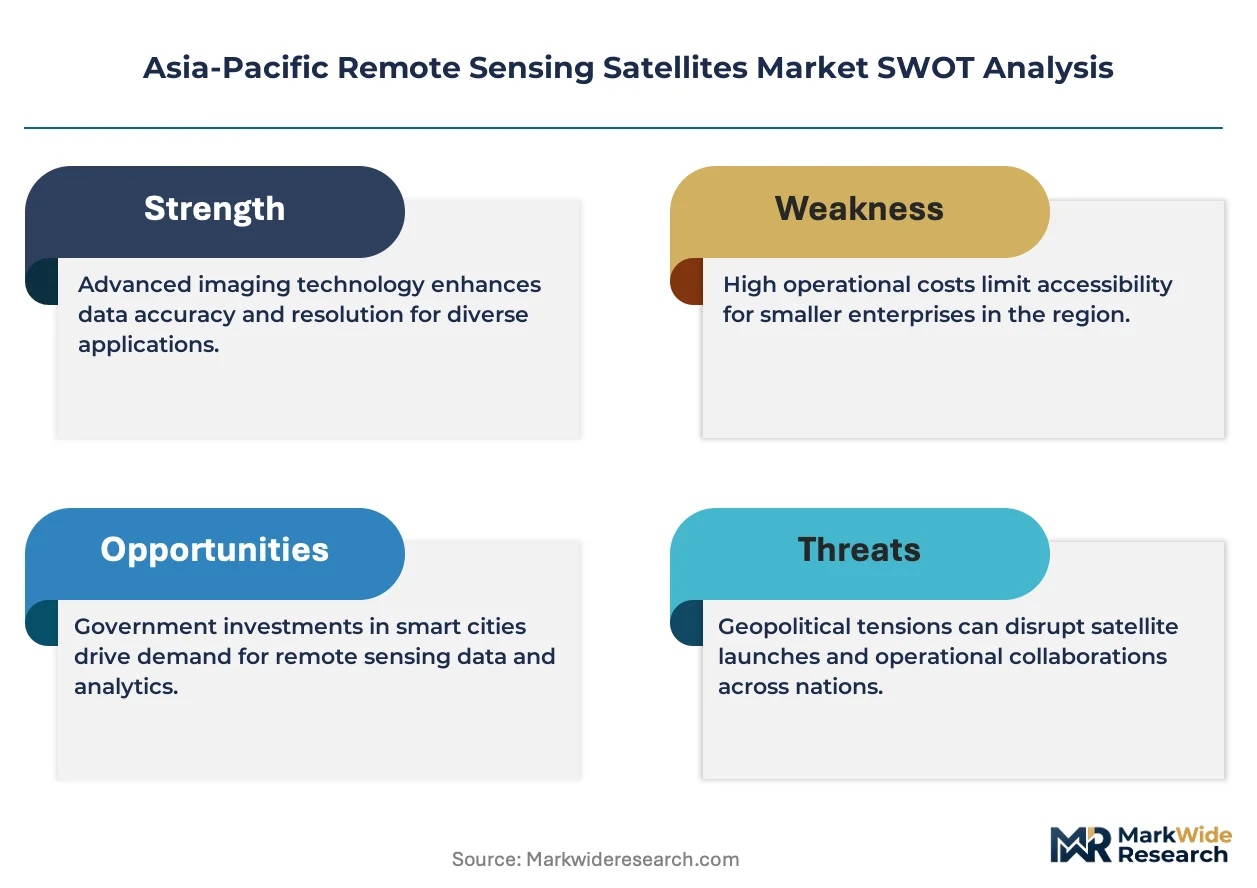
Sovereign-backed satellite leasing programs are fragmenting capital barriers across Southeast Asia, enabling defense agencies and commercial operators to access persistent Earth observation without full constellation ownership. This financing innovation is compressing procurement timelines and expanding the addressable operator base beyond traditional state-backed incumbents.
Growth Catalysts
- India's PLI scheme for space technology:Production-linked incentives for domestic satellite manufacturing are accelerating NewSpace venture formation and reducing import dependency for optical payloads and ground segment components.
- Maritime domain awareness mandates:Defense procurement across Indonesia, Vietnam, and the Philippines is driving demand for synthetic aperture radar constellations capable of all-weather territorial water monitoring.
- China's dual carbon goals:National emissions verification requirements are expanding government contracts for hyperspectral imaging to monitor industrial pollution, deforestation, and renewable energy deployment.
Market Restraints
- Export control misalignment:Divergent component licensing between Japan's METI, India's DGFT, and China's SAMR is fragmenting supply chains and extending procurement timelines for multinational constellation operators.
- Launch capacity concentration:Dependence on ISRO's Polar Satellite Launch Vehicle and China's Long March series creates bottleneck risk for commercial operators without dedicated ride-share agreements.
- Data sovereignty protocols:China's cross-border imagery flow restrictions under MIIT and SAMR licensing are limiting foreign operator market access and complicating regional data product distribution.
Strategic Opportunities
- Emerging Pacific Island demand:Climate vulnerability in Fiji, Papua New Guinea, and the Solomon Islands is creating sovereign financing opportunities for disaster response-focused small satellite constellations.
- AI-enabled analytics convergence:Integration of onboard edge computing with multispectral sensors is enabling real-time feature extraction for defense and agricultural monitoring applications.
- Australian defense modernization:The country's sovereign satellite capability program under Defense Space Command is opening procurement channels for radar and signals intelligence payload providers.
Industry Challenges
- RF engineer scarcity:Specialized talent for synthetic aperture radar payload design and phased array antenna integration remains concentrated in Japan, India, and China, constraining regional expansion for newer entrants.
- Ground segment interoperability:BIS and ISRO technical standards for Indian domestic manufacturing are creating certification complexity for foreign operators seeking market access.
- Capex intensity of radar platforms:High-power synthetic aperture radar satellites require substantially greater investment in solar arrays and thermal management than optical equivalents, limiting private capital participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Remote Sensing Satellites Market |
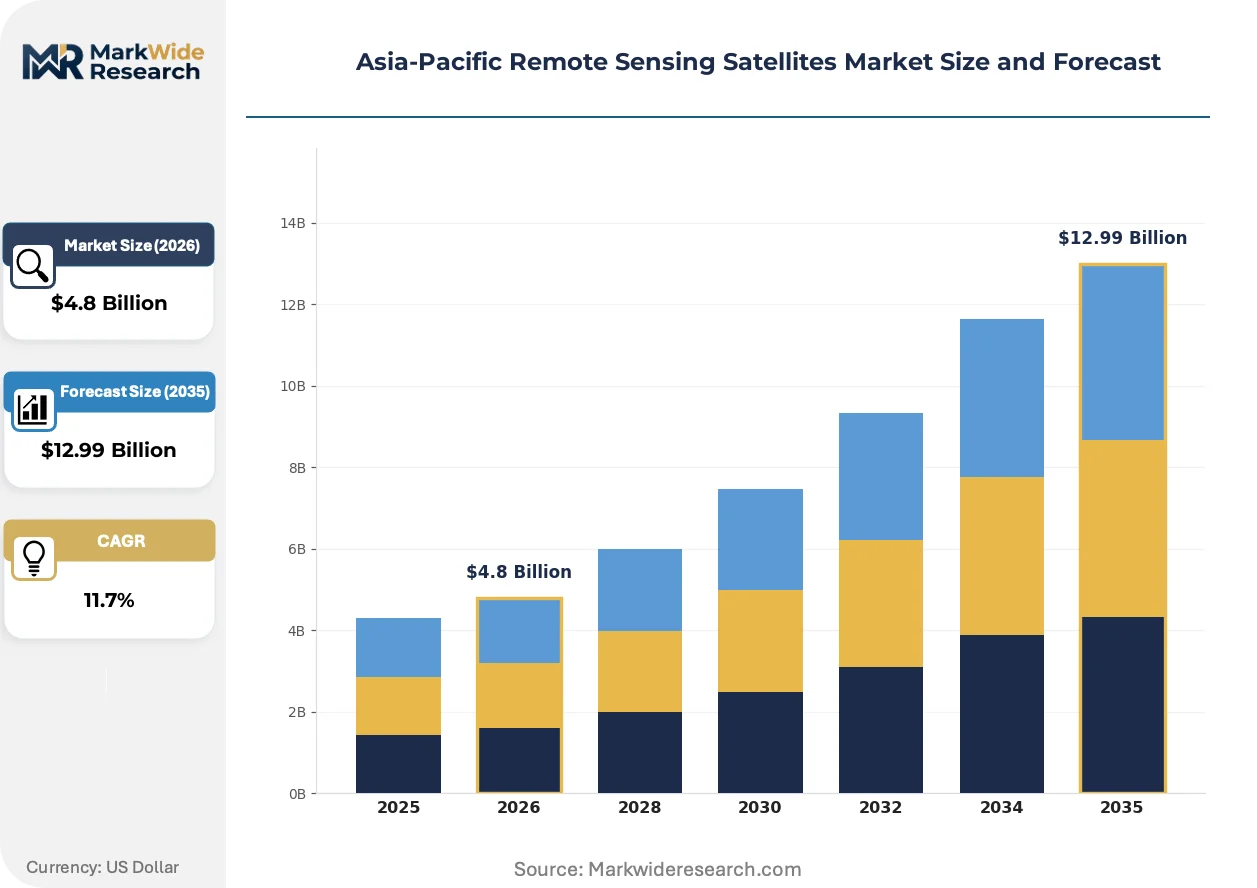
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earth Observation, Weather Monitoring, Environmental Management, Agricultural Surveillance Application: Urban Planning, Disaster Management, Natural Resources Monitoring, Defense Operations Technology: Optical Imaging, Radar Imaging, Hyperspectral Imaging, Lidar Technology End User: Government Agencies, Research Institutions, Commercial Enterprises, Non-Governmental Organizations |
| Companies Covered | Japan Aerospace Exploration Agency (JAXA), Indian Space Research Organisation (ISRO), China Aerospace Science and Technology Corporation (CASC), IHI Corp, Mitsubishi Heavy Industries, Chang Guang Satellite Technology Co. Ltd, Korea Aerospace Research Institute (KARI), Spacety, Axelspace Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Remote Sensing Satellites Market Trends and Innovations
Constellation architectures are shifting from large government platforms to distributed small satellite networks, compressing revisit times and enabling persistent coverage models. This structural change is redistributing value capture from prime contractors to payload specialists and launch service providers.
Commercial small satellite buses paired with synthetic aperture radar payloads are collapsing the cost floor for all-weather Earth observation. Maritime surveillance agencies across Southeast Asia are adopting these platforms to monitor exclusive economic zones without optical weather dependency. The technology is collapsing the historical trade-off between coverage frequency and unit economics that favored large government platforms.
China's MIIT and SAMR have tightened commercial remote sensing licensing requirements and data security protocols governing cross-border imagery flows. Foreign operators must now establish domestic ground stations and data processing facilities to serve Chinese government contracts. The policy is compressing foreign market share in China's commercial Earth observation sector while accelerating domestic constellation deployment.
Defense procurement across the region is migrating from single-mission satellites to dual-use radar and hyperspectral systems serving both military reconnaissance and environmental validation. Japanese climate monitoring contracts and Philippine maritime security programs now specify identical payload specifications, enabling vendors to amortize development across civilian and classified revenue streams. This convergence is most visible in Australia's integrated investment approach under its National Space Mission for Earth Observation.
Asia-Pacific Remote Sensing Satellites Market Segmentation
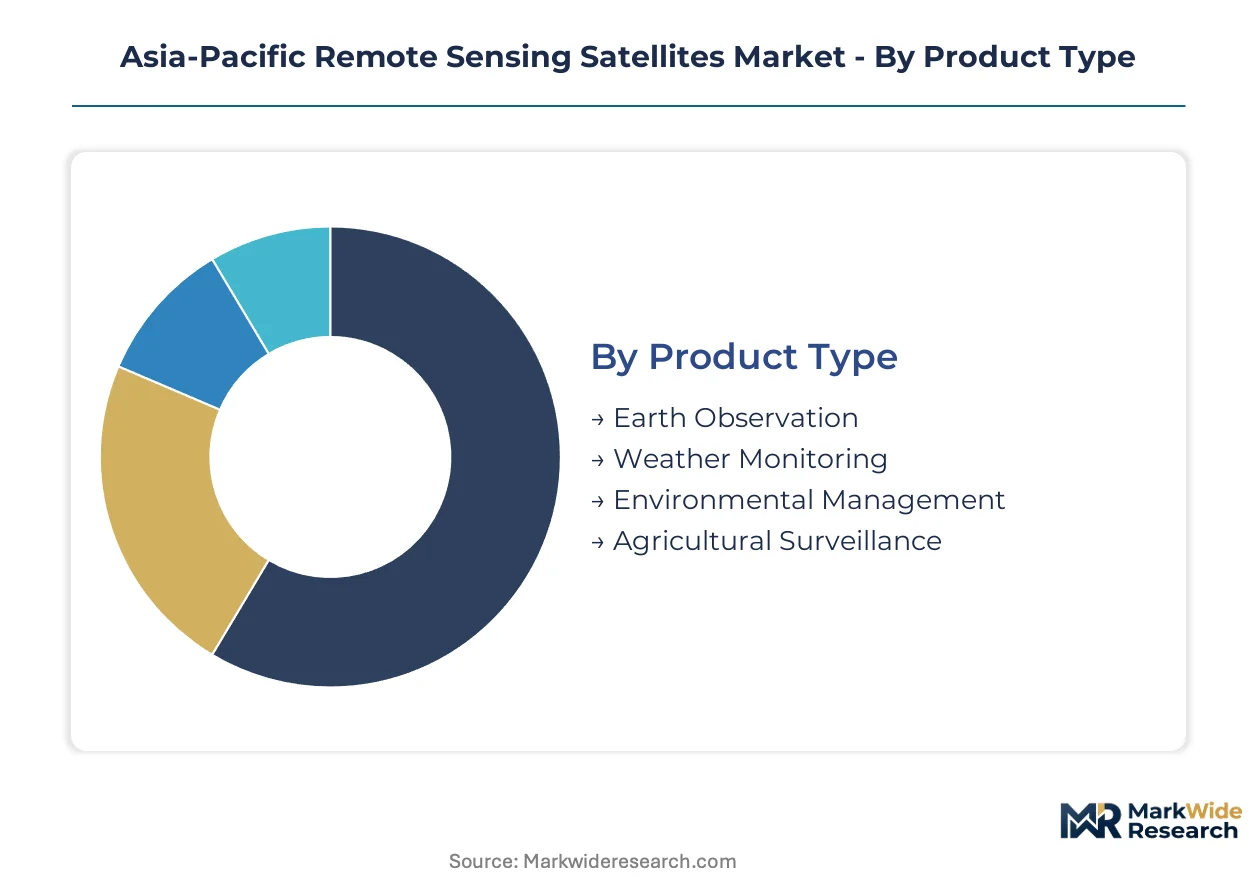
Segmentation of the Asia-Pacific remote sensing satellites market reveals how payload specifications, procurement authority, and data processing requirements reshape competitive positioning across national space programs. Understanding these divides clarifies where sovereign budgets concentrate versus where private capital can penetrate.
Product Type:
Mature government platforms now coexist with emerging small satellite architectures, redistributing value capture between prime contractors and component specialists.
- Earth Observation:Multispectral and panchromatic payloads capture sub-meter resolution imagery for territorial monitoring and infrastructure mapping. China's commercial operators and India's NewSpace ventures drive procurement volume as domestic constellation deployment accelerates under Beijing's dual carbon goals and New Delhi's PLI scheme.
- Weather Monitoring:Geostationary and polar-orbiting meteorological satellites carry infrared sounders and microwave imagers for atmospheric profiling. Japan's Meteorological Agency and India's ISRO sustain demand through regional climate modeling mandates and cyclone early warning systems.
- Environmental Management:Hyperspectral sensors track industrial emissions, deforestation, and marine ecosystem health for regulatory compliance.
- Agricultural Surveillance:Normalized difference vegetation index mapping supports precision farming across Australia's wheat belt and Southeast Asian rice paddies.
Earth Observation handles the majority of throughput; Agricultural Surveillance is gaining share fastest as food security programs expand across Indonesia and Vietnam.
Application:
Cost tier segmentation separates classified defense procurement from commercially funded civilian programs, with dual-use systems bridging the gap.
- Defense Operations:Synthetic aperture radar and signals intelligence payloads enable all-weather maritime surveillance and electronic reconnaissance. Australia's Defense Space Command and Southeast Asian navies drive specification requirements for exclusive economic zone monitoring.
- Disaster Management:Rapid-revisit small satellite constellations deliver post-event imagery for flood, earthquake, and wildfire response. Pacific Island nations under climate vulnerability pressure are emerging as sovereign financing customers for dedicated coverage.
- Urban Planning:High-resolution stereo imaging supports cadastral mapping and informal settlement monitoring in megacities.
- Natural Resources Monitoring:Mineral exploration and forestry compliance applications concentrate in Australia's mining corridors and Indonesia's pulp concessions.
Defense Operations commands the premium pricing tier; Disaster Management is expanding most quickly as climate adaptation funding flows through multilateral development banks.
Technology:
Supply concentration for radio frequency engineering talent shapes which technology pathways achieve commercial scale across the region.
- Radar Imaging:Active microwave systems penetrate cloud cover and darkness for persistent maritime and agricultural monitoring. Japan's METI-funded climate programs and Philippine naval procurement specify identical phased array requirements, enabling vendor development cost amortization.
- Optical Imaging:Passive sensors across visible and near-infrared bands deliver the highest spatial resolution for mapping and urban analysis. Chang Guang Satellite Technology and ISRO's technology transfer programs dominate cost-efficient manufacturing at scale.
- Hyperspectral Imaging:Narrow contiguous bands enable material identification for mineralogy and vegetation stress detection.
- Lidar Technology:Laser altimetry supports topographic mapping and forest biomass quantification for carbon accounting.
Optical Imaging retains volume leadership; Radar Imaging shows the steepest expansion trajectory as all-weather requirements displace weather-dependent alternatives.
End User:
Customer type segmentation determines procurement timeline urgency, budget cycle predictability, and data security classification requirements.
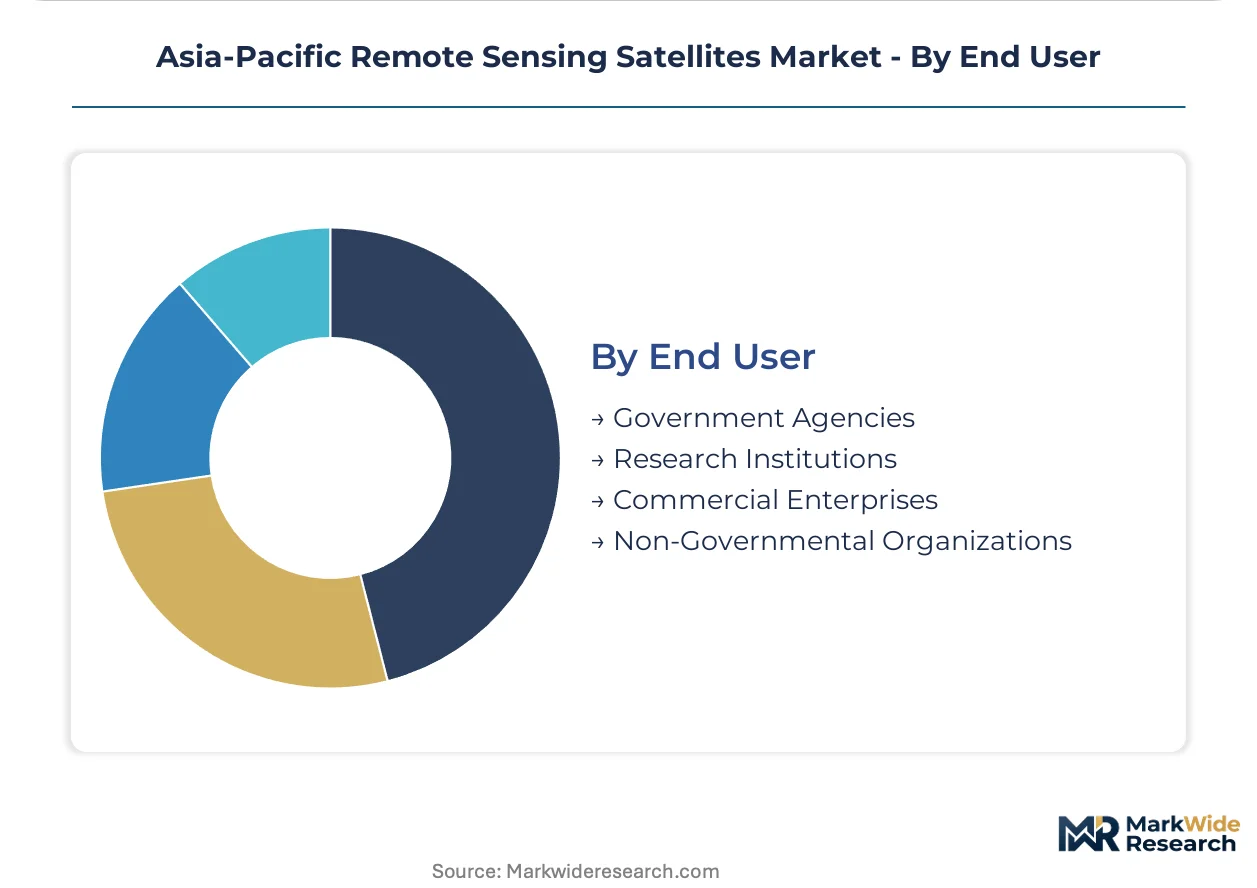
- Government Agencies:National space programs, defense ministries, and environmental regulators commission dedicated satellites or sovereign leasing arrangements. China's MIIT and SAMR licensing restrictions channel foreign operator access through domestic ground station mandates.
- Commercial Enterprises:Agriculture, insurance, and mining corporations purchase analytics-ready data products rather than raw imagery. Australian mining majors and Southeast Asian plantation operators represent the addressable base.
- Research Institutions:Universities and national laboratories access subsidized data archives for climate and geophysical science.
- Non-Governmental Organizations:Conservation and humanitarian groups leverage small grants and open data policies for targeted monitoring campaigns.
Government Agencies anchor procurement volume; Commercial Enterprises are climbing fastest as private analytics platforms aggregate satellite feeds for sector-specific decision tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries and commercial operators across Asia-Pacific concentrate procurement authority in sovereign space agencies and state-backed industrial groups. National security mandates and climate monitoring obligations channel budget commitments through established institutional pathways. Geographic dispersion of manufacturing competence creates distinct competitive clusters around launch infrastructure and payload engineering centers.
China
MIIT and SAMR licensing frameworks restrict cross-border imagery flows while accelerating domestic constellation deployment. Chang Guang Satellite Technology exemplifies private operator emergence challenging state-backed incumbents in commercial Earth observation. Beijing-Tianjin-Hebei anchors manufacturing concentration for optical payload production serving dual carbon verification mandates.
Japan
METI's Basic Plan on Space Policy channels industrial policy toward high-reliability radar platforms for defense and climate contracts. Mitsubishi Heavy Industries occupies the prime contractor position for phased array systems specified identically across naval and meteorological programs. Nagoya's Chubu region concentrates RF engineering talent for synthetic aperture radar development.
India
ISRO's Polar Satellite Launch Vehicle program sustains cost leadership while PLI scheme incentives accelerate NewSpace venture formation. BIS technical standards enforce domestic manufacturing requirements for satellite buses and ground segment components. Bangalore's aerospace corridor hosts technology transfer partnerships between ISRO and emerging private operators.
Australia
Defense Space Command's sovereign satellite capability program opens procurement channels for radar and signals intelligence payload providers. National Space Mission for Earth Observation integrates civilian climate monitoring with classified defense requirements through unified investment frameworks. Adelaide's space industry hub concentrates small satellite bus manufacturing for regional export.
South Korea
KARI anchors national Earth observation infrastructure while commercial operators pursue agricultural and maritime analytics contracts. MFDS regulatory alignment with international space debris mitigation standards shapes component sourcing decisions for constellation operators. Daejeon's research complex hosts hyperspectral instrument development for environmental management applications.
Asia-Pacific Remote Sensing Satellites Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where sovereign agencies anchor procurement volume and private operators capture commercial analytics value. State-backed prime contractors dominate large platform manufacturing while NewSpace ventures fragment the small satellite bus segment. Two strategic archetypes prevail: vertically integrated national champions with captive launch infrastructure, and payload-focused specialists leveraging ride-share access. Competitive moves concentrate on sovereign partnership formation and manufacturing cost compression through technology transfer programs.
Within the national champion tier, China Aerospace Science and Technology Corporation and Indian Space Research Organisation exemplify vertically integrated operators controlling launch, satellite manufacturing, and ground segment deployment. Mitsubishi Heavy Industries occupies a position bridging defense prime contracting with commercial climate monitoring platforms. Spacety represents the emerging specialist archetype, leveraging small satellite architectures and ride-share launch access to serve commercial analytics demand without capital-intensive infrastructure ownership.
| Leading Market Players |
|---|
| Japan Aerospace Exploration Agency (JAXA) |
| Indian Space Research Organisation (ISRO) |
| China Aerospace Science and Technology Corporation (CASC) |
| IHI Corp |
| Mitsubishi Heavy Industries |
| Chang Guang Satellite Technology Co. Ltd |
| Korea Aerospace Research Institute (KARI) |
| Spacety |
| Axelspace Corporation |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor's freight cost volatility compresses margins for optical payload importers while amplifying price differentiation between ISRO's PSLV ride-share tiers and dedicated Long March launches. This logistics tension concentrates procurement power with operators maintaining captive manufacturing in Beijing-Tianjin-Hebei or technology transfer partnerships in Bangalore.
Pricing Analysis
Cost-plus contracts with aluminum and gallium arsenide indexation dominate satellite manufacturing procurement from China's state-backed primes. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened defense specifications from commercial small satellite buses. Pricing pressure stems from Chang Guang Satellite Technology's vertical manufacturing integration. Commercial analytics providers exhibit highest price sensitivity; defense ministries accept premium positioning for classified radar platforms.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor component procurement for NewSpace ventures lacking sovereign balance sheet backing. Manufacturing concentrates in China, India, and Japan for solar arrays, reaction wheels, and phased array antennas. Raw material dependencies span gallium arsenide substrates, pyrolytic graphite, and radiation-hardened semiconductors. Single-source vulnerability persists for synthetic aperture radar transmit-receive modules from Nagoya's Chubu cluster. Distribution runs through ISRO's commercial arm, CASC's international division, and specialist brokers serving Southeast Asian defense agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs value capture as ground segment interoperability standards from India's BIS and data sovereignty protocols from China's SAMR reshape competitive boundaries. The shift toward sovereign leasing models fragments traditional prime contractor control.
For Market Incumbents: Insulate radar platform margins through captive phased array manufacturing in Nagoya's Chubu corridor and technology transfer restrictions to emerging NewSpace ventures. Lock in exclusive launch allocation agreements with ISRO's commercial arm before PSLV capacity saturates. Secure dual-use certification pathways under Japan's METI and Australia's Defense Space Command to amortize development across civilian and classified revenue streams. For New Entrants and Emerging Players: Build out sovereign leasing partnerships with Pacific Island nations facing climate vulnerability pressure in Fiji, Papua New Guinea, and the Solomon Islands. Target disaster response analytics as the most penetrable application segment given multilateral development bank funding flows. Pursue AI-enabled edge computing integration as the primary go-to-market angle for real-time agricultural monitoring contracts. For Investors and Strategic Acquirers: Payload-integrated small satellite specialists with proven ride-share launch relationships represent the most defensible acquisition archetype for the medium-term horizon. Long-term viability hinges on constellation operators achieving persistent coverage economics before regulatory fragmentation hardens. Monitor BIS-ISRO technical standard harmonization progress as the critical inflection signal for foreign operator market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Leasing Partnership Formation | Enables Southeast Asian defense agencies to access persistent coverage without constellation ownership capital burden. |
| Technology Transfer Program Expansion | ISRO's PLI-aligned partnerships accelerate NewSpace venture formation in Bangalore's aerospace corridor. |
| Dual-Use Payload Certification Investment | METI and Australia's Defense Space Command specifications enable cost amortization across military and climate contracts. |
| Ground Segment Interoperability Compliance | BIS standards enforcement creates certification moats for domestic Indian operators against foreign entrants. |
| AI-Enabled Edge Computing Integration | Real-time feature extraction capabilities differentiate analytics offerings for defense and agricultural monitoring applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with satellite program directors, defense procurement officers, NewSpace venture founders, and ground segment engineers; and secondary validation through ISRO annual reports, JAXA mission disclosures, MIIT licensing registries, and customs trade data for optical payload components. Bottom-up unit economics modeling triangulated against top-down sovereign budget allocation analysis.
Forecast inputs span payload type segmentation, procurement authority classification, and technology pathway adoption curves across the projection horizon. Modeled dimensions include Earth observation versus weather monitoring product types, defense versus commercial application tiers, radar versus optical versus hyperspectral technology categories, and government agency versus commercial enterprise end-user archetypes. CAGRs derive from satellite deployment pipeline analysis and sovereign financing commitment trajectories. Industry-specific inputs incorporate PSLV and Long March launch cadence projections and dual-use contract specification convergence patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by China's commercial operators or accelerated PLI scheme disbursements from India's DGFT would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Reconnaissance Satellite Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
United States Satellite Communications Market
Satellite
Small Satellite Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
France Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Earth Observation Satellite Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Satellite Data Service Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Global Enterprise VSAT System Market
Satellite
Germany Satellite Connectivity Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Europe Small Satellite Market
Satellite
Global Commercial Satellite Imagery Market