
 United States Satellite Communications Market | 2026-2036
United States Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
United States Satellite Communications Market Insights
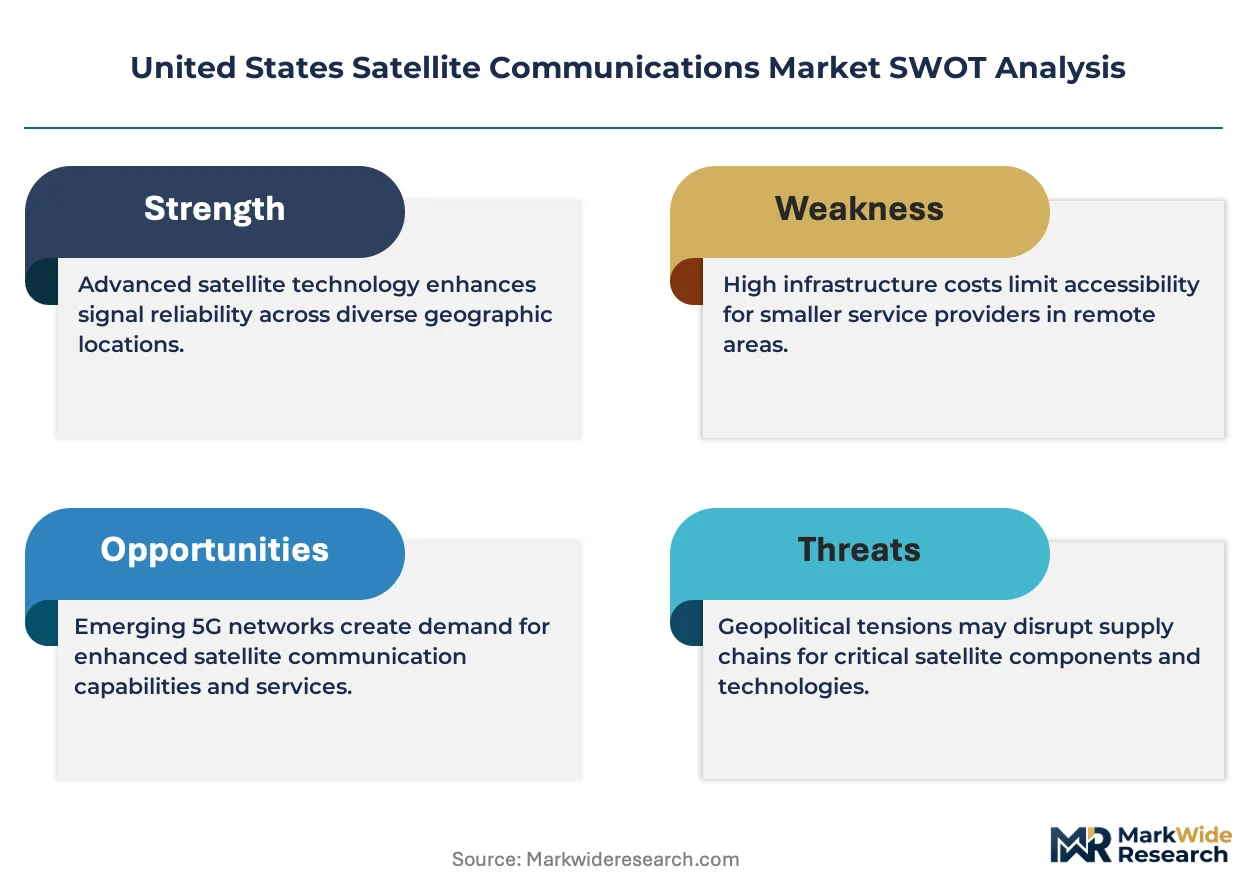
A shortage of radio-frequency engineers and orbital mechanics specialists is unwinding project timelines across the industry. Viasat Inc. leverages vertical integration from chipset design to ground infrastructure to control delivery schedules. L3Harris Technologies Inc. anchors defense contracting relationships that sustain classified payload programs. Iridium Communications Inc. dominates mobile satellite services through its completed LEO constellation replacement.
United States satellite communications encompasses the transmission, relay, and reception of data via artificial Earth-orbiting platforms operating across L-band through Ka-band frequencies, with signal latencies ranging from under 50 milliseconds for low Earth orbit systems to 500+ milliseconds for geostationary configurations. The primary commercial purpose is to provide connectivity in locations where terrestrial fiber or cellular infrastructure is uneconomical or impossible to deploy. Broadband service type captures the largest revenue pool as rural internet subsidy programs expand addressable households. LEO technology is displacing GEO dominance in latency-sensitive applications including defense command networks and maritime fleet management. Enterprise service type concentrates margin in managed network contracts for energy sector remote operations.
The FCC governs spectrum licensing and orbital slot coordination, while the FAA regulates commercial launch activities and spaceport operations; together these agencies shape market entry costs and operational boundaries for new constellation deployments. The National Telecommunications and Information Administration controls federal spectrum use, creating priority access tiers that commercial operators must navigate. Stakeholders must monitor emerging FCC rules on in-orbit servicing and debris mitigation, as these will determine which legacy operators can extend asset lifetimes versus face accelerated replacement cycles.
Market Dynamics
The FCC's C-band spectrum reallocation is compressing legacy geostationary operations while LEO constellations capture latency-sensitive defense and maritime contracts. This regulatory-engineering collision is restructuring competitive positioning across orbital regimes and forcing accelerated capital redeployment.
Growth Catalysts
- Rural Broadband Subsidies:Federal connectivity programs expand addressable households in unserved census blocks, pulling fiber-infeasible regions into the commercial satellite footprint.
- LEO Constellation Deployment:Low Earth orbit architectures deliver sub-50 millisecond latency that GEO systems cannot match, unlocking defense command networks and autonomous maritime operations.
- Defense Bandwidth Procurement:Pentagon classified payload programs sustain secure satellite demand through multi-year indefinite-delivery contracts with integrated prime contractors.
Market Restraints
- Radio-Frequency Engineering Scarcity:Orbital mechanics and RF design talent shortages unwind project timelines and inflate compensation costs across the aerospace corridor.
- Spectrum Coordination Friction:NTIA priority access tiers for federal users create licensing delays that commercial operators must navigate before constellation activation.
- Launch Infrastructure Bottlenecks:Eastern Range and Cape Canaveral capacity constraints limit deployment velocity for new market entrants.
Strategic Opportunities
- In-Orbit Servicing Rules:Emerging FCC debris mitigation and satellite servicing frameworks will determine which legacy operators extend asset lifetimes versus face accelerated replacement cycles.
- California Aerospace Cluster:Launch infrastructure and ground station network concentration in the state's corridor creates ecosystem advantages for co-located operators.
- Managed Energy Networks:Enterprise service contracts for remote oilfield and mining operations concentrate margin in vertically integrated network management offerings.
Industry Challenges
- Legacy System Integration:Defense agencies require backward compatibility with existing GEO terminals while migrating to LEO architectures, complicating procurement specifications.
- Debris Mitigation Compliance:FCC rules on post-mission disposal and collision avoidance impose operational constraints that increase design complexity and insurance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Satellite Communications Market |
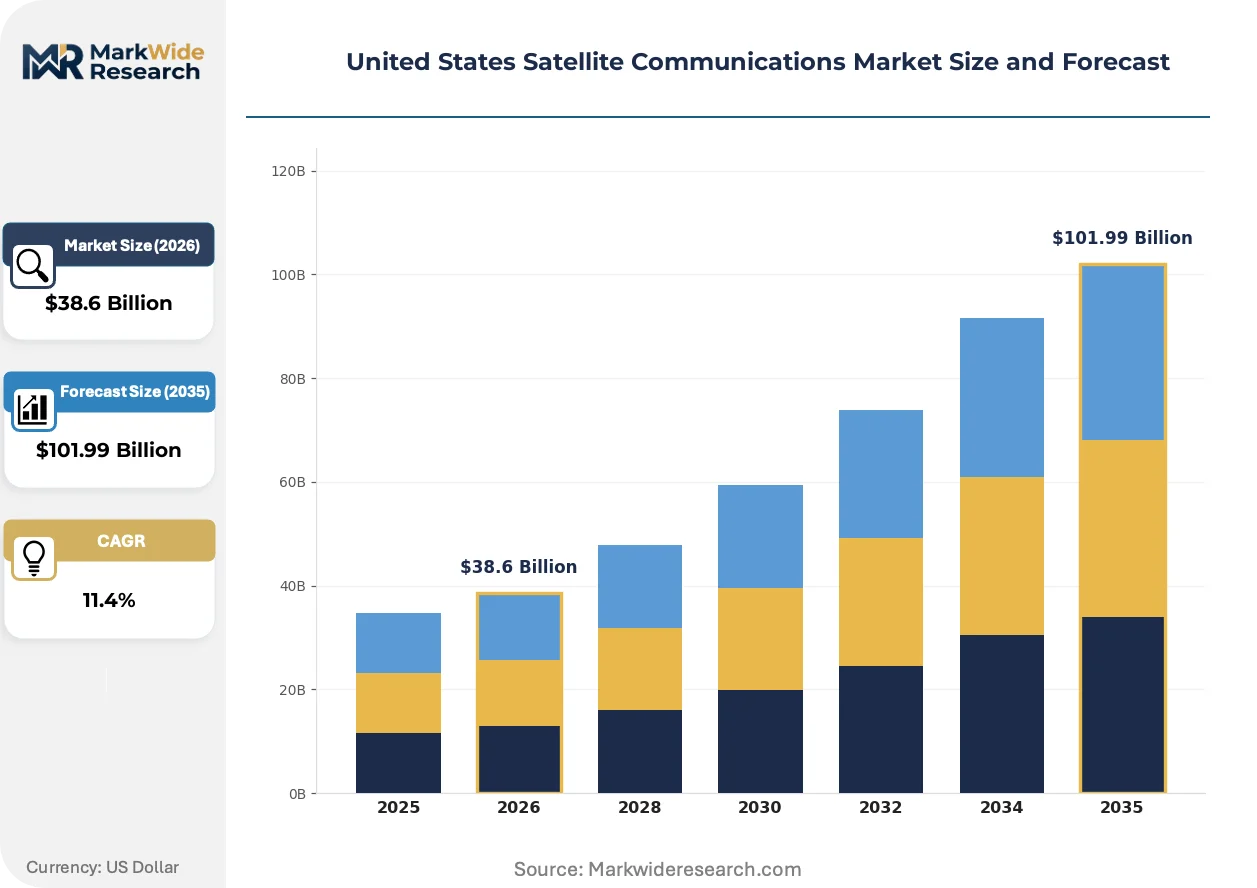
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Direct-To-Home, Mobile, Enterprise Application: Aerospace, Maritime, Government, Energy Technology: LEO, MEO, GEO, HTS End User: Telecommunications, Defense, Broadcasting, Oil & Gas |
| Companies Covered | Iridium Communications Inc., Telesat Corporation, Viasat Inc., Intelsat, Gilat Satellite Networks Ltd., L3Harris Technologies Inc., EchoStar Corporation, Thales Group, Inmarsat Global Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Satellite Communications Market Trends and Innovations
Active phased array terminals and software-defined payloads are compressing hardware refresh cycles. The market is bifurcating between standardized consumer broadband and hardened military-grade systems with diverging certification requirements.
Electronically steered flat-panel antennas are supplanting parabolic dishes for mobile and maritime applications. Defense contractors and commercial airlines are adopting these systems for phased fleet retrofits. This hardware transition is supplanting legacy installation infrastructure and opening volume manufacturing economies that GEO-era equipment never achieved.
FCC orbital debris mitigation rules now mandate post-mission disposal timelines and collision probability thresholds. Commercial operators must redesign propulsion reserves and end-of-life protocols to maintain licensing eligibility. Small-satellite constellations face the steepest compliance burden due to higher object counts and shorter design lives.
Enterprise buyers are consolidating vendor relationships around integrated managed-service contracts rather than bandwidth-only procurement. Energy sector remote operations lead this shift, demanding guaranteed latency and uptime with single-source accountability. This purchasing evolution is most visible in Permian Basin and Gulf of Mexico operations where terrestrial redundancy is unavailable.
United States Satellite Communications Market Segmentation
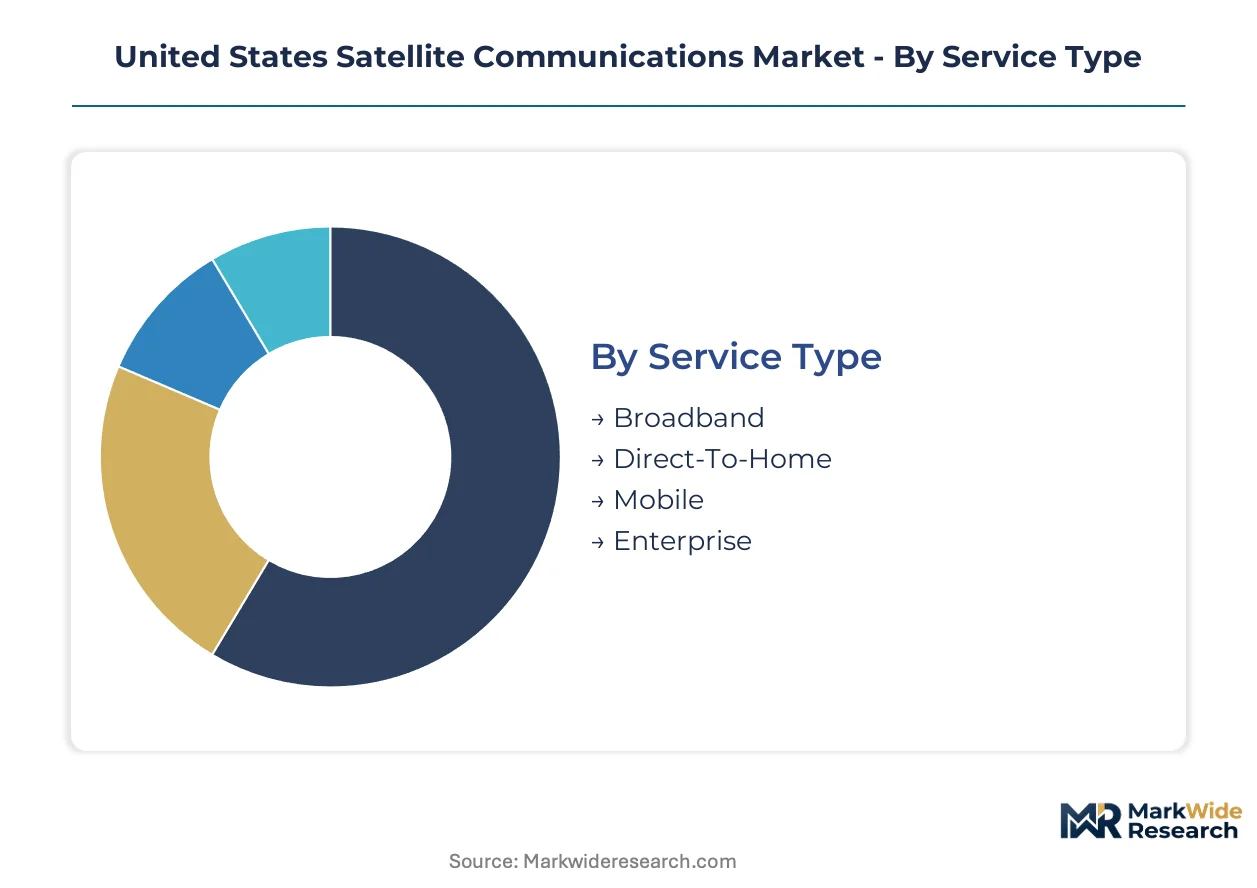
Satellite communications segmentation reveals how orbital architecture and service delivery models align with distinct customer procurement patterns. Each dimension captures different competitive dynamics, from spectrum licensing constraints to latency requirements that dictate technology selection.
Service Type:
Broadband and Enterprise services concentrate procurement within domestic federal subsidy programs and defense contracting channels, while Direct-To-Home and Mobile segments serve more geographically dispersed consumer and commercial maritime demand.
- Broadband:Fixed satellite services delivering high-throughput data to residential and small business subscribers. Rural internet subsidy programs in unserved census blocks across the Mountain West and Great Plains are pulling fiber-infeasible households into commercial satellite footprints.
- Enterprise:Managed network contracts with guaranteed service-level agreements for mission-critical operations. Energy sector remote operations in the Permian Basin and Gulf of Mexico concentrate margin in vertically integrated offerings with single-source accountability.
- Direct-To-Home:Satellite television broadcasting to consumer premises. Subscriber bases in Alaska and rural Montana sustain this segment despite cord-cutting pressures in urban markets.
- Mobile:Voice and data services to aircraft, vessels, and land vehicles. Maritime fleet operators along Pacific and Atlantic shipping lanes drive renewal demand as legacy L-band systems reach end-of-life.
Broadband holds the largest share; momentum sits with Enterprise as procurement shifts toward managed-service accountability.
Application:
Defense and Energy applications command premium pricing through specialized terminal requirements, while Maritime and Aerospace segments scale through standardized hardware platforms.
- Government:Classified and unclassified communications for federal agencies and military branches. Pentagon indefinite-delivery contracts sustain multi-year procurement relationships with primes capable of secure payload integration.
- Energy:Exploration, production, and pipeline monitoring for oilfield and mining operations. Remote drilling sites in North Dakota's Bakken formation and offshore platforms demand guaranteed uptime where terrestrial redundancy is unavailable.
- Aerospace:In-flight connectivity for commercial and business aviation. Airlines operating transcontinental routes from hubs in Atlanta, Dallas-Fort Worth, and Los Angeles are retrofitting fleets with electronically steered flat-panel antennas.
- Maritime:Fleet management and crew welfare communications for commercial shipping. Container operators traversing Pacific trade corridors require low-latency links for autonomous navigation systems.
Government captures the steepest expansion trajectory; Energy offers the most stable contract visibility.
Technology:
LEO architectures are displacing GEO dominance in latency-sensitive defense and maritime contracts, while HTS payloads extend geostationary competitiveness in broadcast applications.
- LEO:Low Earth orbit constellations operating below 2,000 kilometers altitude with sub-50 millisecond latency. Defense command networks and autonomous maritime operations in California's aerospace corridor are accelerating deployment timelines.
- GEO:Geostationary satellites at 35,786 kilometers altitude with fixed earth-pointing coverage. Legacy C-band operations face compression from FCC spectrum reallocation for 5G backhaul.
- MEO:Medium Earth orbit systems bridging latency and coverage tradeoffs. O3b mPOWER deployments serve equatorial regions with performance between LEO responsiveness and GEO reach.
- HTS:High-throughput satellite platforms using frequency reuse and spot beams. Ka-band HTS payloads maximize spectral efficiency for consumer broadband beams over the continental United States.
GEO retains installed base dominance; LEO is gaining share fastest through defense procurement migration.
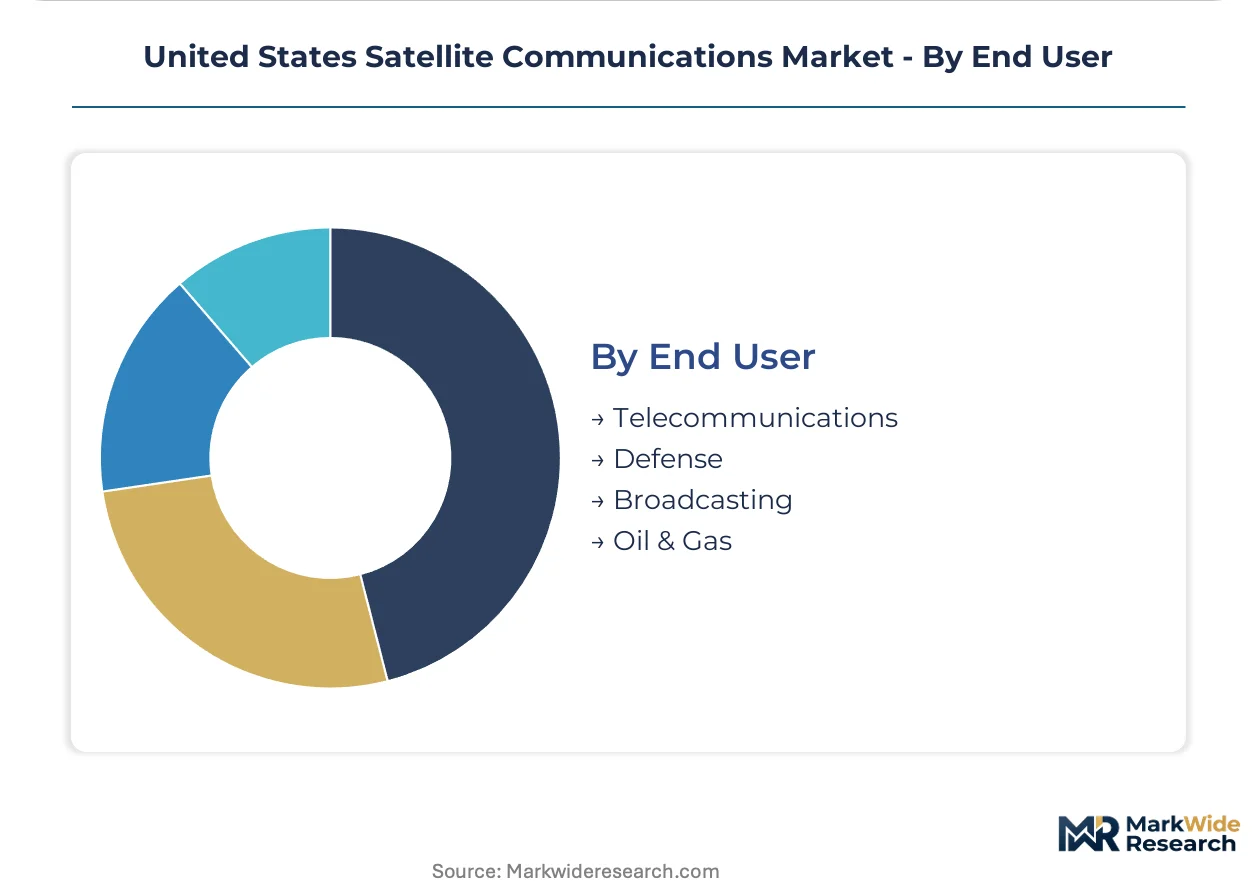
End User:
Defense and Telecommunications end users drive infrastructure investment cycles, while Broadcasting and Oil & Gas operate on extended replacement timelines.
- Defense:Secure communications for military operations and intelligence community requirements. Classified payload programs sustain demand through NTIA priority spectrum access and hardened terminal specifications.
- Telecommunications:Backhaul and trunking services for rural carriers and emergency response networks. FCC Connect America Fund disbursements expand addressable infrastructure for tribal lands and remote communities.
- Broadcasting:Content distribution to affiliate stations and cable headends. Network television groups maintain GEO capacity for simultaneous nationwide program delivery.
- Oil & Gas:Exploration data transmission and production facility monitoring. Supermajors operating in the Gulf of Mexico consolidate vendor relationships around integrated managed-service contracts.
Defense anchors procurement volume; Telecommunications offers the broadest subsidy-supported expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC anchors spectrum licensing and orbital coordination across the United States, while the FAA governs commercial launch operations. State-level aerospace clusters concentrate manufacturing and ground infrastructure in distinct corridors.
California
Defense command networks and autonomous maritime operations drive LEO constellation deployment timelines in the state's aerospace corridor. The California Air Resources Board coordinates environmental review for spaceport expansion alongside federal regulators. Los Angeles and San Diego anchor satellite manufacturing, with Hawthorne and El Segundo hosting vertically integrated production facilities for spacecraft and ground terminals.
Texas
Launch infrastructure bottlenecks at Cape Canaveral are redirecting deployment velocity toward Boca Chica and Houston spaceport facilities. The Texas Space Commission allocates state incentives for launch site development and propulsion testing. The Gulf Coast corridor from Brownsville to Houston clusters engine manufacturing and mission control operations for commercial constellation operators.
Colorado
Secure payload integration and classified ground station networks concentrate demand in the Denver-Aurora metropolitan zone. The state's aerospace tax credit program sustains engineering workforce recruitment against coastal compensation pressures. Boulder and Colorado Springs host satellite operations centers and military space command facilities that coordinate federal spectrum access.
Florida
Eastern Range capacity constraints at Cape Canaveral limit deployment schedules for new market entrants seeking equatorial launch trajectories. Space Florida administers infrastructure bonds for launch pad modernization and payload processing facilities. The Space Coast maintains its position through heritage relationships with NASA and Department of Defense launch procurement.
Virginia
Wallops Flight Facility and the Mid-Atlantic Regional Spaceport capture polar orbit launches for reconnaissance and weather satellite deployments. The Virginia Commercial Space Flight Authority coordinates FAA licensing for coastal launch operations. Hampton Roads clusters small-satellite manufacturing and university research partnerships that feed engineering pipelines for constellation operators.
United States Satellite Communications Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with defense contractors and commercial operators occupying distinct competitive vectors. The market structure reflects bifurcation between classified payload programs and consumer broadband scale plays. Prime contractors anchor multi-year indefinite-delivery relationships with Pentagon procurement offices, while constellation operators compete for rural connectivity subsidies. Competitive moves concentrate on vertical integration into chipset design and strategic partnerships for launch capacity allocation.
Within the integrated prime tier, L3Harris Technologies Inc. and Viasat Inc. exemplify divergent strategic positions—one anchoring defense contracting channels, the other controlling delivery schedules through captive manufacturing. Iridium Communications Inc. occupies a distinct position as a completed LEO constellation operator with established mobile satellite service relationships. These three companies represent the spectrum from hardware-integrated primes to service-focused constellation owners.
| Leading Market Players |
|---|
| Iridium Communications Inc. |
| Telesat Corporation |
| Viasat Inc. |
| Intelsat |
| Gilat Satellite Networks Ltd. |
| L3Harris Technologies Inc. |
| EchoStar Corporation |
| Thales Group |
| Inmarsat Global Limited |
| Others |
Pricing and Supply Chain Analysis
Multi-year indefinite-delivery contracts with Pentagon procurement offices lock in both secure payload access and price visibility for prime contractors, while commercial broadband operators face spot-market volatility in launch capacity allocation. This bifurcation concentrates pricing power with defense-anchored integrators and fragments margin capture across consumer-facing constellation builders.
Pricing Analysis
California's aerospace corridor commands premium pricing over Gulf Coast manufacturing zones due to co-located engineering talent and ground station density. Three-tier pricing structure across hardened military-grade, enterprise managed-service, and consumer broadband levels separates procurement by certification complexity and latency guarantees. Cost compression in consumer broadband tiers intensifies because LEO constellation overcapacity and rural subsidy rate caps limit ARPU expansion. Energy sector remote operations show least price sensitivity due to single-source accountability requirements and guaranteed uptime SLAs.
Supply Chain Analysis
Propulsion system lead times now stretch eighteen to twenty-four months for domestic engine manufacturers, compressing constellation deployment schedules. Manufacturing concentrates in the United States, with payload integration in Colorado and terminal production in California drawing from gallium arsenide substrate suppliers and radiation-hardened semiconductor foundries. Single-source vulnerability in solid rocket motor propellant supply creates bottlenecks for small-satellite launch providers. Distribution runs through vertically integrated primes for defense contracts and direct-to-constellation-operator procurement for commercial bandwidth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed wireless access and low-orbit optical inter-satellite links threaten to displace radio-frequency satellite bandwidth in latency-tolerant applications, forcing incumbents to defend substitution risk through performance differentiation and vertical integration depth.
For Market Incumbents: Shield classified payload relationships through NTIA spectrum priority access and backward integration into radiation-hardened chipset design. Accelerate in-orbit servicing capability development before FCC debris mitigation rules force premature asset retirement. Defense contracting channels remain the priority lever against Starlink-led consumer broadband commoditization. For New Entrants and Emerging Players: Anchor in maritime fleet management retrofits where legacy L-band systems reach end-of-life and electronically steered flat-panel antenna demand outstrips supply. Target Permian Basin energy operators with managed-service accountability models that incumbent GEO operators cannot match on latency. Pursue channel partnerships with California ground station networks to bypass Eastern Range launch bottlenecks. For Investors and Strategic Acquirers: RF engineering boutiques with captive orbital mechanics talent represent the most defensible acquisition archetype as talent scarcity inflames project timeline risk. Long-term viability hinges on regulatory capture through FCC licensing relationships rather than constellation scale alone. Watch for Pentagon indefinite-delivery contract award velocity as the signal distinguishing sustainable prime contractors from speculative infrastructure plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chipset Design | Viasat's captive semiconductor production shields delivery schedules from foundry allocation constraints. |
| In-Orbit Servicing Capability Buildout | FCC debris mitigation rules will reward operators capable of extending asset lifetimes through on-orbit refueling. |
| Managed Service Contract Consolidation | Energy sector buyers in the Gulf of Mexico demand single-source accountability that bandwidth-only vendors cannot meet. |
| California Ground Station Network Expansion | Co-located launch infrastructure and mission control operations compress latency for defense command networks. |
| Electronically Steered Flat-Panel Antenna Scale-Up | Maritime and aviation retrofit demand enables volume manufacturing economies unavailable to parabolic dish incumbents. |
Research Methodology
A spread of perspectives from constellation operations directors, Pentagon procurement officers, FCC regulatory counsel, and ground station network engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, NTIA spectrum allocation databases, and FAA commercial launch licensing records. Bottom-up triangulation across service type demand curves and top-down reconciliation against federal subsidy disbursement schedules anchored volume estimates.
Segmentation dimensions modeled include orbital regime architecture, service delivery model, end-use application, and state-level aerospace cluster concentration across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves for defense bandwidth procurement and rural broadband subsidy expansion. Forecast inputs incorporated Eastern Range launch capacity constraints and radio-frequency engineering workforce pipeline data from Bureau of Labor Statistics occupational projections.
Decision-makers should treat outputs as directional under assumptions of sustained Pentagon classified payload spending and FCC spectrum reallocation timelines; material deviation in federal connectivity program authorization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite Imagery Services Market
Satellite
Middle East Satellite Communications Market
Satellite
Indonesia Satellite Communications Market
Satellite
Satellite Gateway Market
Satellite
Satellite Data Service Market
Satellite
UK Satellite Connectivity Market
Satellite
Satellite Communications Service Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Japan Satellite Communication Market
Satellite
Satellite Services Market
Satellite
Japan Satellite Connectivity Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Israel Satellite Communications Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
North America Remote Sensing Services Market
Satellite
China Satellite Imagery Services Market