
 Asia-Pacific Satellite Manufacturing and Launch Systems Market | 2026-2036
Asia-Pacific Satellite Manufacturing and Launch Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Manufacturing and Launch Systems Market Outlook
Government procurement channels across the Asia-Pacific are tilting toward dual-use satellite architectures that blend civilian broadband with sovereign sensing capabilities. China Aerospace Science and Technology Corporation leverages its Long March vehicle family to anchor domestic launch cadence and secure geostationary slots. Mitsubishi Heavy Industries Ltd competes through H3 rocket reliability and precision payload delivery for Japanese institutional clients. Antrix Corporation Limited extends ISRO's launch services to commercial customers across Southeast Asia and Africa.
Asia-Pacific satellite manufacturing and launch systems encompass the design, fabrication, testing, and orbital deployment of spacecraft ranging from sub-100 kg CubeSats to 6,000+ kg geostationary platforms, with launch vehicles employing liquid hydrogen/oxygen or solid-propellant stages to achieve Low Earth Orbit or geosynchronous transfer trajectories. Small Satellites lead volume demand as constellation operators in Australia and Southeast Asia pursue rapid replenishment cycles. Launch Services capture disproportionate margin pools where ride-share configurations and dedicated missions command premium pricing. Ground Systems represent a maturing segment where established vendors face pressure from software-defined radio architectures.
India's Department of Space and ISRO shape market access through technology transfer policies and foreign launch clearance requirements for domestically registered spacecraft. Japan's Cabinet Office and METI coordinate spectrum allocation and export control alignment with U.S. International Traffic in Arms Regulations. China's SAMR and MIIT enforce indigenous standards for satellite components and launch vehicle subsystems that constrain foreign supplier participation. Stakeholders must weigh sovereign capacity investments against commercial partnership models as national space legislation proliferates across the region.
Market Dynamics
Dual-use satellite architectures are compressing procurement cycles across Asia-Pacific defense and civilian agencies, forcing manufacturers to reconcile sovereign payload requirements with commercial cost structures in single platform designs.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for space-grade component manufacturing are accelerating indigenization of satellite subsystems and reducing import dependency for domestic constellation operators.
- LEO broadband constellations:Commercial telecom operators in Indonesia and the Philippines are expanding fleet procurement to address archipelagic connectivity gaps underserved by terrestrial infrastructure.
- Sriharikota-Bengaluru corridor:Concentrated launch infrastructure and testing facilities are creating supplier clustering effects that shorten integration timelines for regional spacecraft builders.
Market Restraints
- Solid-propellant supply concentration:Ammonium perchlorate sourcing remains concentrated among a limited supplier base, creating input cost volatility for launch vehicle manufacturers.
- Geostationary slot scarcity:ITU coordination procedures and orbital congestion around 110-120°E longitude constrain fleet expansion timelines for new market entrants.
- Foreign launch clearance requirements:India's technology transfer policies and domestic launch mandates create regulatory friction for spacecraft operators seeking cost-optimized deployment options.
Strategic Opportunities
- Vietnam and Thailand:Underpenetrated markets for Earth observation services present first-mover advantages for synthetic aperture radar constellation operators.
- Quantum key distribution payloads:Convergence of photonic integrated circuits with satellite platforms is opening sovereign secure communications contracts across defense agencies.
- Australia's space agency funding:Regulatory tailwinds from civil space program expansion are creating anchor tenancy opportunities for small satellite manufacturers.
Industry Challenges
- Propulsion systems integration:Talent scarcity in electric thruster calibration and hall-effect propulsion engineering is extending spacecraft qualification timelines.
- ITAR-EAR alignment:Japanese and Australian manufacturers face certification complexity when sourcing U.S.-controlled components for dual-use platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Manufacturing and Launch Systems Market |
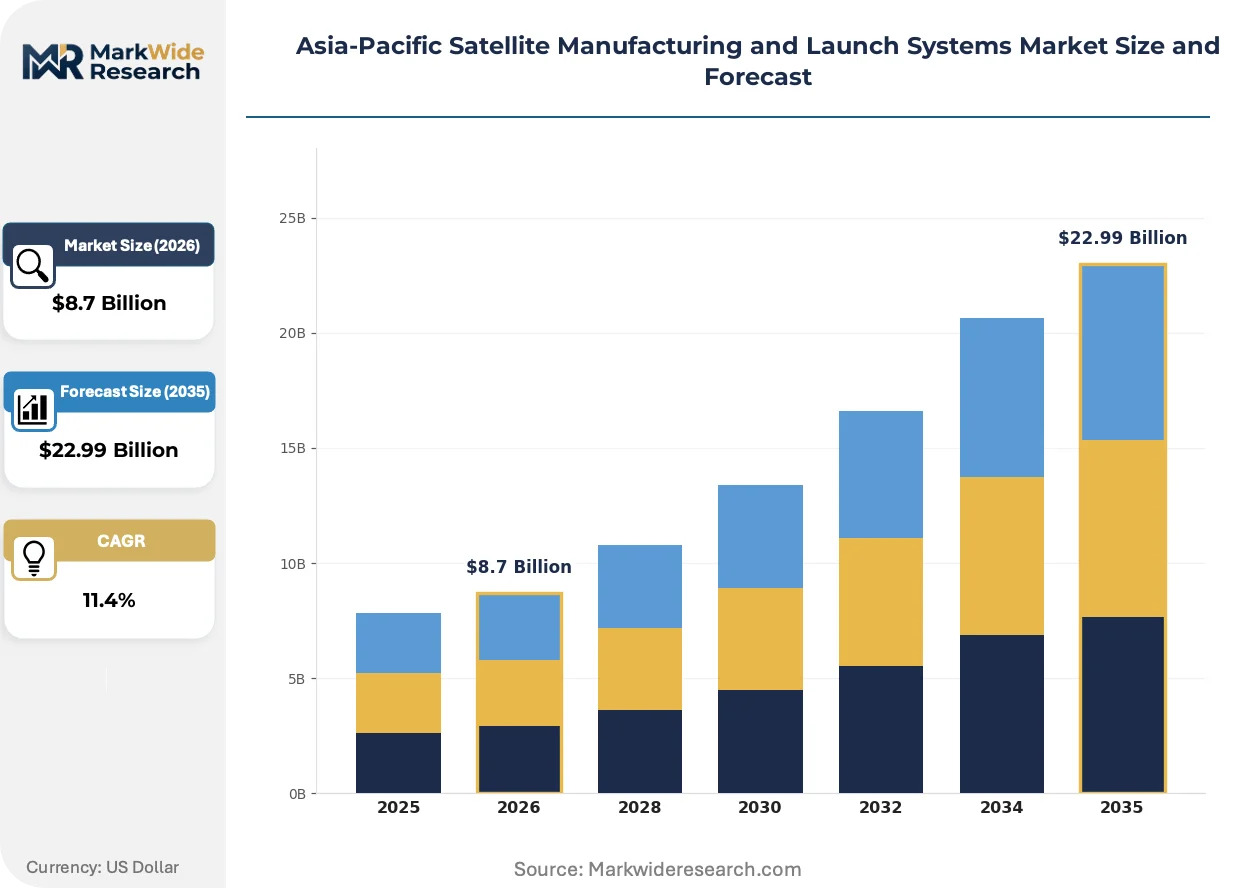
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Satellites, Medium Satellites, Large Satellites, CubeSats Service Type: Launch Services, Assembly Services, Testing Services, Integration Services End User: Government Agencies, Commercial Operators, Research Institutions, Military Organizations Technology: Launch Vehicles, Payload Technologies, Satellite Components, Ground Systems |
| Companies Covered | Mitsubishi Heavy Industries Ltd, IHI Corporation, China Aerospace Science and Technology Corporation, Transpace Technologies Pvt Ltd, Dhruva Space Private Limited, China Satellite Communications Co Ltd, Satrec Initiative Co Ltd, Radio Amateur Satellite Corporation, Antrix Corporation Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Manufacturing and Launch Systems Market Strategic Shifts
Propulsion technology and sovereign data policies are actively reconfiguring competitive positioning across Asia-Pacific satellite manufacturing, compressing legacy platform lifecycles while opening niche specialization pathways.
Additive manufacturing of titanium alloy thrust chambers is hybridizing traditional subtractive machining workflows with powder-bed fusion techniques. ISRO and private Indian launch vehicle developers are adopting these processes for engine component batches under 50 units annually. This hybridizing production model is collapsing lead times for cryogenic engine manifolds from 18 months to under 6 months.
China's MIIT indigenous standards enforcement for satellite components and launch vehicle subsystems is constraining foreign supplier participation in domestic programs. Manufacturers must now certify to GB standards for power conditioning units and onboard computers. European and Japanese component vendors are responding by establishing joint ventures with state-designated partners or exiting mainland procurement channels entirely.
Constellation operators are unbundling spacecraft procurement from launch service contracts, fragmenting what were previously vertically integrated 10-year agreements. Australian and Southeast Asian buyers now separately tender for satellite buses, payload integration, and orbital deployment. This disaggregation is most visible in the Philippines, where domestic telecom groups source platforms from Korean manufacturers while contracting launch services through Antrix or emerging Chinese providers.
Asia-Pacific Satellite Manufacturing and Launch Systems Market Segmentation
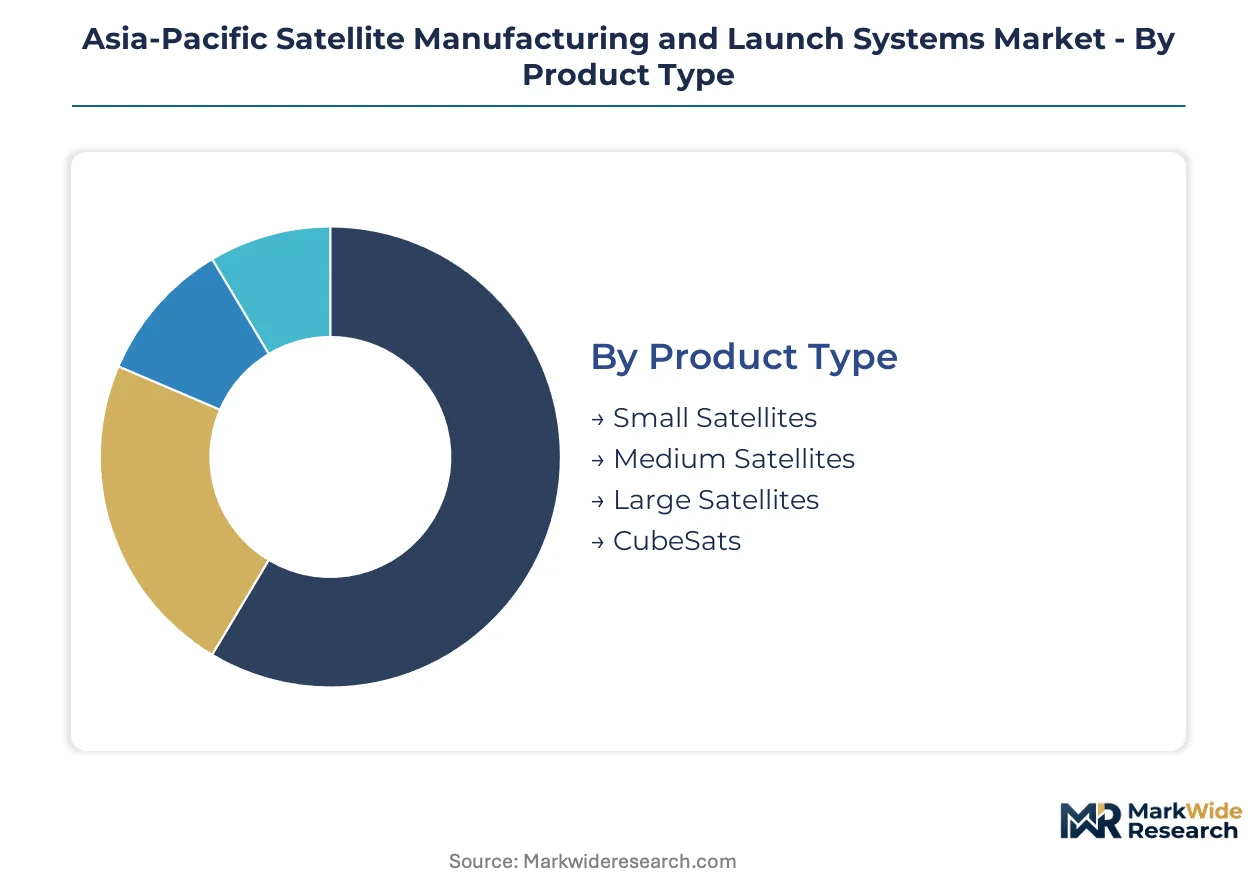
Segmentation in Asia-Pacific satellite manufacturing and launch systems reveals how procurement patterns fragment across platform scale, service unbundling, and sovereign versus commercial demand. Understanding these divisions exposes where margin pools concentrate and where new entrants face structural barriers.
Product Type:
Cost tier stratification across satellite mass classes determines integration complexity, launch vehicle matching, and replenishment cycle economics for constellation operators.
- Small Satellites:Platforms under 500 kg dominate procurement volumes across Australian and Southeast Asian constellation operators seeking rapid deployment timelines. Demand concentrates in Earth observation constellations where operators trade orbital lifespan for unit cost reduction and launch flexibility.
- Medium Satellites:500-2,500 kg platforms balance payload capacity with ride-share compatibility, capturing procurement from Indonesian and Philippine telecom operators bridging archipelagic coverage gaps. These spacecraft accommodate dual-use payloads blending civilian broadband with sovereign sensing capabilities.
- Large Satellites:Geostationary platforms exceeding 2,500 kg serve established broadcast and fixed satellite services with 15-year design lives.
- CubeSats:Standardized 1U-12U form factors enable university and research institution access to orbital deployment through piggyback launch arrangements.
Large satellites command the established base. The steepest expansion runs through small satellites.
Service Type:
Application-specific service unbundling is fragmenting what were previously decade-long vertically integrated contracts across the Asia-Pacific procurement landscape.
- Launch Services:Orbital deployment commands premium pricing where dedicated missions and ride-share configurations serve distinct customer risk tolerances. ISRO's Antrix Corporation and emerging Chinese providers compete for Southeast Asian commercial contracts previously captive to European launch systems.
- Assembly Services:Satellite bus construction and payload integration represent margin-intensive activities where Indian manufacturers leverage PLI scheme subsidies to capture regional demand from domestic and export customers.
- Testing Services:Environmental qualification and vibration testing facilities cluster around Sriharikota and Bengaluru, shortening logistics chains for Indian spacecraft builders.
- Integration Services:Final payload-to-bus mating and launch adapter configuration require specialized cleanroom infrastructure concentrated among established national space agencies.
Assembly services anchor the revenue base. Launch services are climbing the fastest as procurement unbundling accelerates.
End User:
Customer type segmentation captures divergent procurement timelines, specification rigor, and sovereign content requirements across Asia-Pacific demand pools.
- Government Agencies:Civilian space programs in India, Japan, and Australia drive sustained procurement for Earth observation and telecommunications infrastructure with multi-year budget cycles and technology transfer mandates.
- Commercial Operators:Telecom and remote sensing ventures in Indonesia, Philippines, and Vietnam pursue fleet expansion with shorter decision horizons and price-sensitive tendering.
- Research Institutions:University and laboratory demand concentrates in CubeSat and technology demonstration missions with limited payload budgets.
- Military Organizations:Defense procurement channels across the region favor dual-use architectures and classified payload integration with stringent supply chain security requirements.
Government agencies hold the incumbent position. Commercial operators are gaining share fastest as constellation deployment scales.
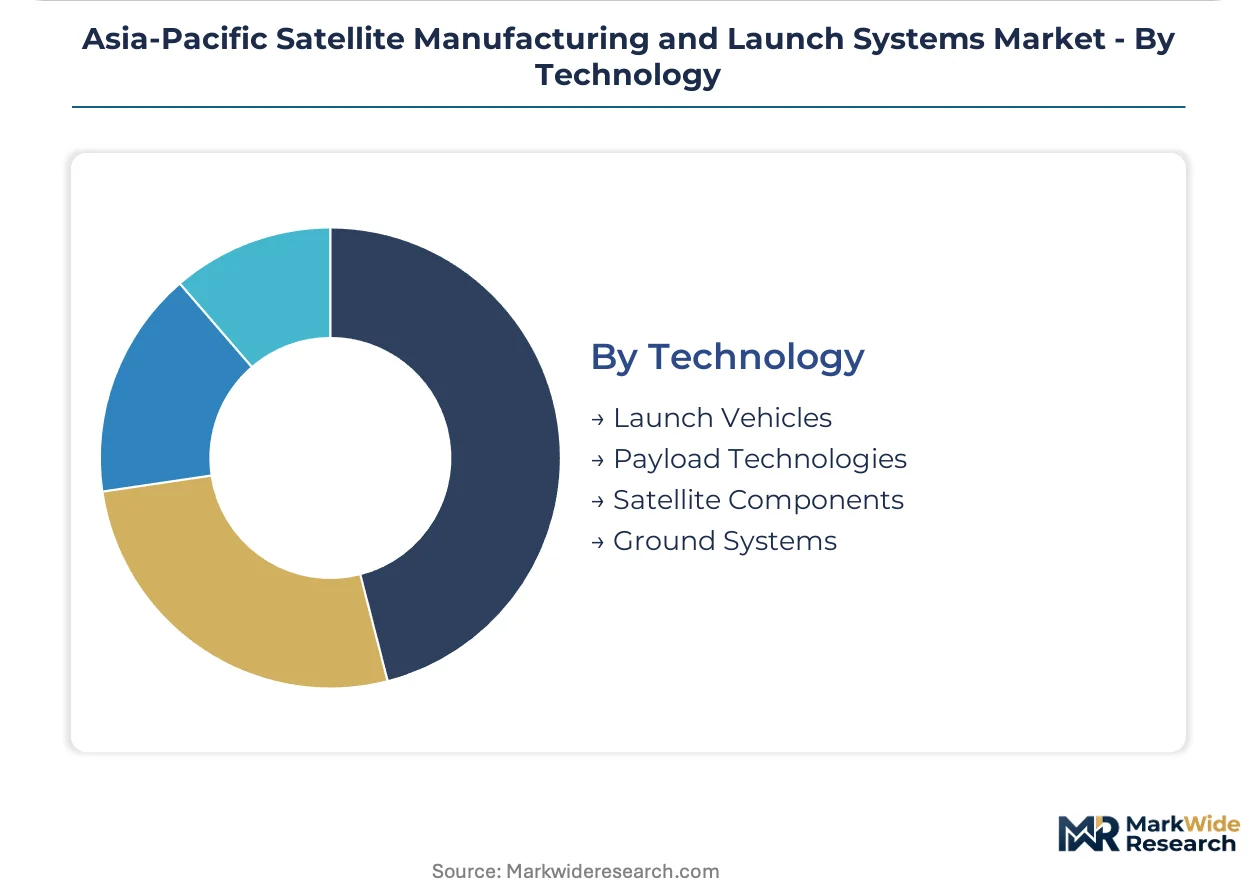
Technology:
Supply concentration across technology layers determines where foreign vendor participation faces regulatory friction versus open procurement competition.
- Launch Vehicles:Propulsion systems and stage integration represent the highest capital barrier to entry, with China's Long March and Japan's H3 families anchoring domestic launch cadence while ISRO's SSLV targets small satellite cost reduction.
- Payload Technologies:Synthetic aperture radar and photonic integrated circuits for quantum key distribution attract defense and commercial investment as sovereign secure communications capabilities mature.
- Satellite Components:Power conditioning units, onboard computers, and attitude control systems face China's GB standards enforcement, constraining European and Japanese supplier access to mainland procurement channels.
- Ground Systems:Software-defined radio architectures are displacing legacy hardware-defined ground segment vendors across Australian and Southeast Asian control facilities.
Launch vehicles capture the technology investment base. Payload technologies are expanding most quickly as sovereign sensing requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands premium pricing for commercial launch services across Southeast Asia, while Indian providers undercut costs through PLI-subsidized component sourcing. This asymmetry reshapes procurement decisions for Indonesian and Philippine constellation operators.
India
ISRO's SSLV program and Antrix commercial services anchor demand from African and Southeast Asian satellite operators seeking cost-efficient deployment. The Department of Space mandates domestic launch preference for spacecraft registered under Indian flag, tightening market access for foreign providers. The Sriharikota-Bengaluru corridor clusters environmental testing facilities, bus manufacturers, and propulsion subsystem suppliers within 350 kilometers.
China
Long March vehicle families sustain domestic cadence while securing geostationary slots across 110-120°E longitude for Belt and Road communications infrastructure. MIIT and SAMR enforce GB standards for satellite components, constraining European and Japanese supplier participation in mainland programs. Xichang and Jiuquan launch centers anchor state-directed capacity expansion with dedicated commercial pads under construction.
Japan
METI coordinates spectrum allocation and export control alignment with U.S. ITAR-EAR frameworks for dual-use platform manufacturers. H3 rocket reliability targets precision payload delivery for institutional clients including JAXA and defense agencies. Tanegashima and Uchinoura space centers concentrate launch infrastructure with Mitsubishi Heavy Industries anchoring vehicle integration.
South Korea
Nuri rocket development and KARI satellite programs drive indigenous capability investment with Naro Space Center supporting orbital access. The Ministry of Science and ICT channels funding toward small satellite constellation demonstration missions. Daejeon-Sejong corridor hosts satellite bus manufacturers and ground systems integrators serving domestic and export markets.
Australia
The Australian Space Agency's civil program expansion creates anchor tenancy demand for Earth observation and communications platform builders. Regulatory frameworks for launch site licensing at Whalers Way and Bowen attract foreign vehicle operators seeking equatorial access. New South Wales and Victoria concentrate satellite services startups and ground segment software vendors.
Asia-Pacific Satellite Manufacturing and Launch Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower margins but faster inventory turns. The vendor base stratifies across three tiers: state-owned enterprises with captive launch infrastructure, mid-scale commercial bus manufacturers, and specialized subsystem suppliers. Strategic moves center on backward integration into propulsion components and geographic expansion through technology licensing arrangements rather than asset-heavy facility builds.
Within the state-enterprise tier, China Aerospace Science and Technology Corporation and Mitsubishi Heavy Industries Ltd occupy positions defined by sovereign launch infrastructure access and institutional customer relationships. Antrix Corporation Limited exemplifies the hybrid model combining government mission assurance with commercial pricing flexibility for export customers. These entities represent how national space legislation and technology transfer policies shape competitive boundaries more than pure technical differentiation.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| IHI Corporation |
| China Aerospace Science and Technology Corporation |
| Transpace Technologies Pvt Ltd |
| Dhruva Space Private Limited |
| China Satellite Communications Co Ltd |
| Satrec Initiative Co Ltd |
| Radio Amateur Satellite Corporation |
| Antrix Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
The Sriharikota-Bengaluru corridor concentrates environmental testing facilities, propulsion subsystem suppliers, and satellite bus manufacturers within 350 kilometers, compressing logistics costs for Indian spacecraft builders and amplifying their pricing power against Southeast Asian constellation operators seeking cost-efficient deployment.
Pricing Analysis
Configured-to-order pricing for custom geostationary platforms commands spreads of 40-60 percent above standard small satellite bus configurations. Pricing stratifies across premium, standard, and economy tiers based on payload integration complexity and launch vehicle matching requirements. Cost compression in the small satellite tier is intensifying because Antrix Corporation and emerging Chinese providers compete aggressively for Southeast Asian commercial contracts. Commercial telecom operators in Indonesia and the Philippines exhibit the highest price sensitivity, while defense agencies across Japan and Australia prioritize sovereign payload assurance over unit cost.
Supply Chain Analysis
U.S. ITAR-EAR frameworks and China's GB standards enforcement constrain technology flows for power conditioning units, onboard computers, and cryogenic engine components. Supply concentration rests on China for solid-propellant precursors and titanium alloy powder-bed fusion feedstock, Japan for precision payload delivery systems, and India for space-grade component manufacturing under PLI scheme subsidies. Single-source vulnerability persists in ammonium perchlorate sourcing for launch vehicle manufacturers. Distribution runs through national space agency procurement channels with technology transfer mandates, supplemented by direct commercial contracting for unbundled launch services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric thruster calibration and hall-effect propulsion engineering talent pools remain critically thin across the Asia-Pacific, forcing manufacturers to extend spacecraft qualification timelines or import specialized labor at premium cost.
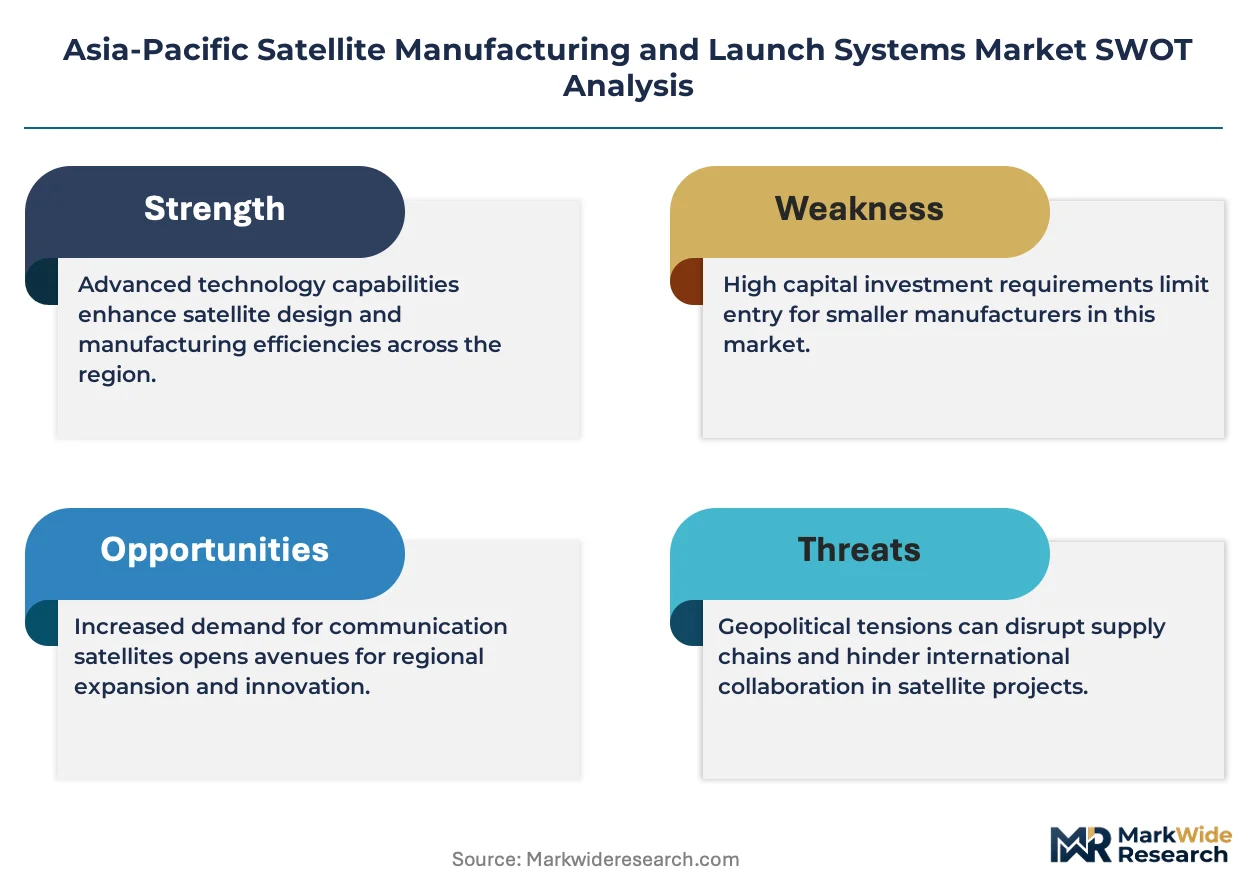
For Market Incumbents: Pre-empt talent poaching by captive training programs at Sriharikota and Tanegashima facilities, locking in propulsion engineering pipelines before Chinese launch vehicle developers expand recruitment. Defend margin position through backward integration into titanium alloy additive manufacturing for cryogenic engine manifolds, collapsing supplier lead times from 18 months to under 6 months. Monitor Antrix Corporation's pricing flexibility for export customers as the primary margin compression threat. For New Entrants and Emerging Players: Pursue synthetic aperture radar constellation opportunities in Vietnam and Thailand, where Earth observation services remain underpenetrated and first-mover advantages persist for operators offering sub-meter resolution. Target Australia's civil space program expansion as anchor tenancy demand materializes for small satellite manufacturers. Lead with software-defined radio ground systems architectures to displace legacy hardware-defined vendors across Southeast Asian control facilities. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign infrastructure play because national space legislation and technology transfer policies shape competitive boundaries more than pure technical differentiation, embedding durable procurement relationships with defense and civilian agencies. Acquisition focus should center on mid-scale commercial bus manufacturers with demonstrated PLI scheme compliance and export licensing track records. Watch India's foreign launch clearance requirement enforcement as the signal indicating whether cost-optimized deployment options open or close for regional operators.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Compliance Investment | Qualifies Indian manufacturers for space-grade component subsidies that undercut Southeast Asian import costs. |
| Dual-Use Platform Certification | Opens procurement channels with Japan's defense agencies and METI-coordinated institutional clients. |
| Ride-Share Configuration Development | Captures premium pricing from Australian constellation operators seeking rapid replenishment cycles. |
| Quantum Key Distribution Payload Integration | Secures sovereign secure communications contracts as photonic integrated circuits mature. |
| Software-Defined Radio Ground Systems | Displaces legacy hardware vendors across Philippine and Indonesian control facilities. |
Study Parameters
Initial hypotheses were tested against primary input from satellite program directors, launch vehicle procurement officers, ground systems engineers, and defense agency technology transfer leads, and refined through secondary validation against ISRO annual reports, JAXA mission disclosures, MIIT standards filings, and customs data for space-grade component trade flows. Bottom-up demand modeling from constellation operator fleet expansion plans was triangulated with top-down capacity assessments across Sriharikota, Tanegashima, and Xichang launch infrastructure.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling satellite mass class segments, service unbundling patterns, end-user procurement timelines, and technology layer supply concentration. CAGRs were derived from weighted scenario analysis incorporating sovereign capacity investment trajectories and commercial partnership proliferation rates. Industry-specific inputs included ITU geostationary slot coordination timelines and PLI scheme subsidy absorption curves for Indian manufacturers.
Sensitivities concentrate around foreign launch clearance requirement enforcement in India, GB standards compliance cost escalation in China, and ITAR-EAR alignment complexity for Japanese dual-use platforms. Forecasts reflect documented assumptions regarding constellation deployment cadence and national space legislation proliferation. Material shifts in solid-propellant supply concentration or quantum key distribution payload maturation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Transponder Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Russia Satellite Connectivity Market
Satellite
Commercial LEO Satellite Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Mexico Satellite Connectivity Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Europe Small Satellite Market
Satellite
South Korea Satellite Connectivity Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Japan Satellite Imagery Services Market
Satellite
North America Satellite Manufacturing Market
Satellite
France Satellite Connectivity Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Bus Market