
 Medium and Large Satellite Market | 2026-2036
Medium and Large Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Medium and Large Satellite Market Intelligence
Defense procurement is decoupling from telecom as the primary demand anchor for medium and large satellite platforms. Lockheed Martin Corporation dominates military geostationary programs through classified payload integration. Airbus SAS competes across dual-use Earth observation missions with European government backing. Boeing leverages its commercial satellite heritage while sustaining classified manufacturing lines in El Segundo.
Medium and large satellites encompass spacecraft with launch masses exceeding 500 kilograms, typically employing chemical or electric propulsion for orbital insertion and station-keeping over fifteen-year design lives. Their primary purpose spans persistent communications relay, strategic surveillance, and planetary science data collection. Communication Satellites generate the dominant revenue pool through transponder leasing and managed bandwidth services. Low Earth Orbit deployments represent the fastest-expanding segment as constellations demand larger individual bus architectures. Government Agencies anchor procurement volume through classified and civilian programs with multi-year appropriation cycles.
The Federal Aviation Administration governs U.S. launch licensing while the FCC regulates spectrum coordination and orbital debris mitigation rules. ESA member states operate under EU Space Surveillance and Tracking consortium guidelines plus national export control regimes. China's MIIT and SAMR administer frequency allocation and spacecraft manufacturing standards through state-owned enterprise channels. Stakeholders must monitor evolving debris remediation mandates and sovereign launcher availability before committing to bus platform investments.
Market Dynamics
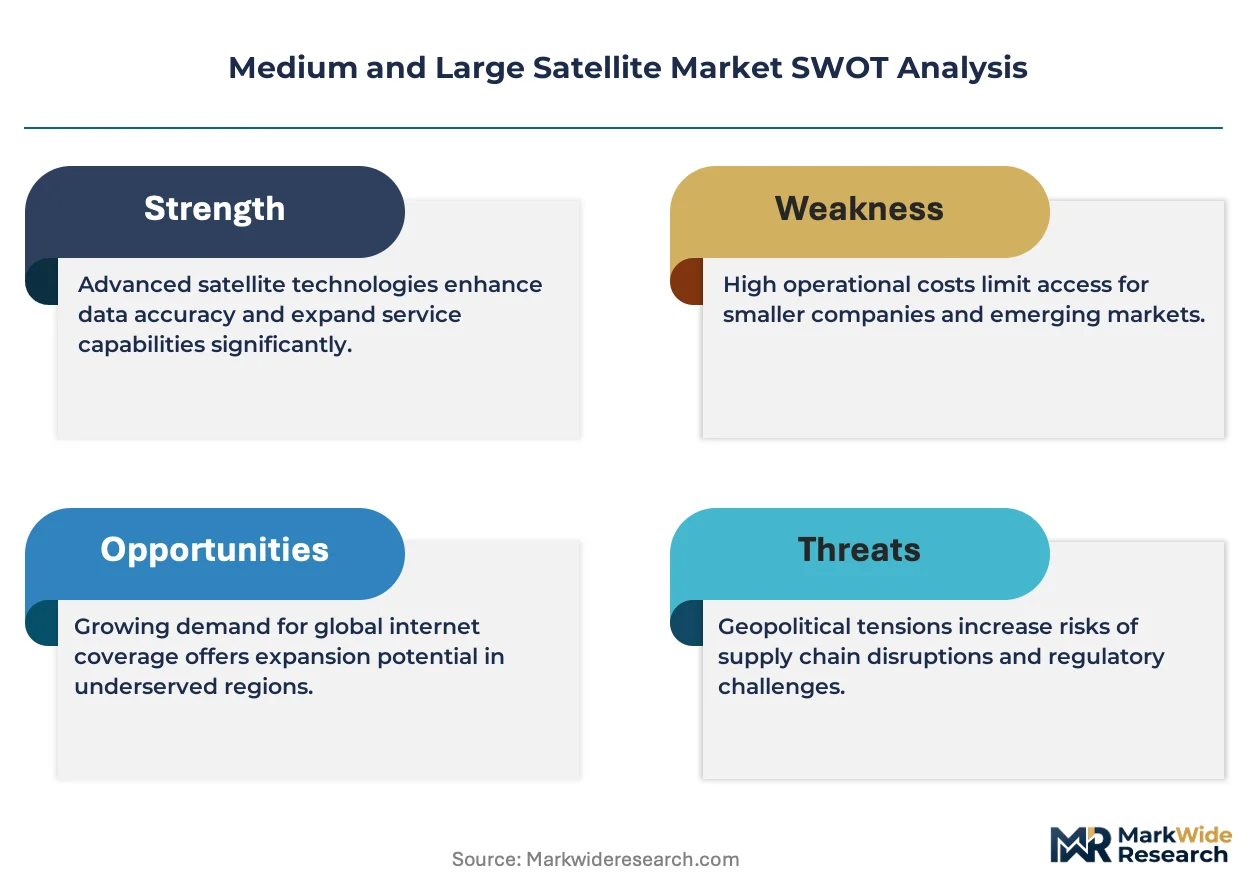
Defense procurement decoupling from telecom anchor tenants is restructuring medium and large satellite demand, as sovereign buyers prioritize classified payload integration over commercial transponder leasing. This shift compresses design cycles and elevates security-cleared manufacturing capabilities above cost efficiency.
Growth Catalysts
- REACH compliance timelines:European thermal control system manufacturers are accelerating fluorinated gas phase-outs ahead of regulatory deadlines, creating replacement demand for compliant spacecraft materials.
- National security budgets:Sovereign launcher availability in the United States, China, and France is expanding dedicated procurement channels outside commercial ride-share manifests.
- Electric propulsion maturation:Hall-effect thrusters are reducing station-keeping fuel mass fractions, enabling heavier payload allocations on fixed launch mass budgets.
Market Restraints
- Launch capacity concentration:Sovereign launcher backlogs in the United States and China extend delivery timelines for medium and large platforms beyond traditional eighteen-month procurement windows.
- Thermal control material scarcity:F-Gas Regulation compliance is constraining qualified supplier pools for European satellite programs, elevating input costs for two-phase heat transport systems.
- Orbital debris mitigation rules:FCC passive disposal requirements are adding structural mass for drag sails or propulsion reserves, compressing payload budgets on fixed-cost contracts.
Strategic Opportunities
- Dual-use Earth observation:European government backing for civilian-military sensor fusion is opening procurement channels for bus architectures with modular payload interfaces.
- Managed bandwidth services:Military end-users are migrating from transponder leases to end-to-end network management contracts, elevating service revenue above hardware margins.
- Low Earth Orbit constellations:Individual bus architectures exceeding 500 kilograms are penetrating commercial communications deployments previously served by smallsat dispensers.
Industry Challenges
- Security-cleared workforce scarcity:Classified payload integration requires personnel with active government clearances, constraining manufacturing throughput at specialized facilities.
- Multi-year appropriation cycle misalignment:Government procurement schedules desynchronize from commercial satellite production rhythms, forcing contractors to maintain dual planning systems.
- Cross-border technology transfer controls:National export control regimes fragment supply chains for propulsion subsystems and encryption modules, complicating multinational program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium and Large Satellite Market |
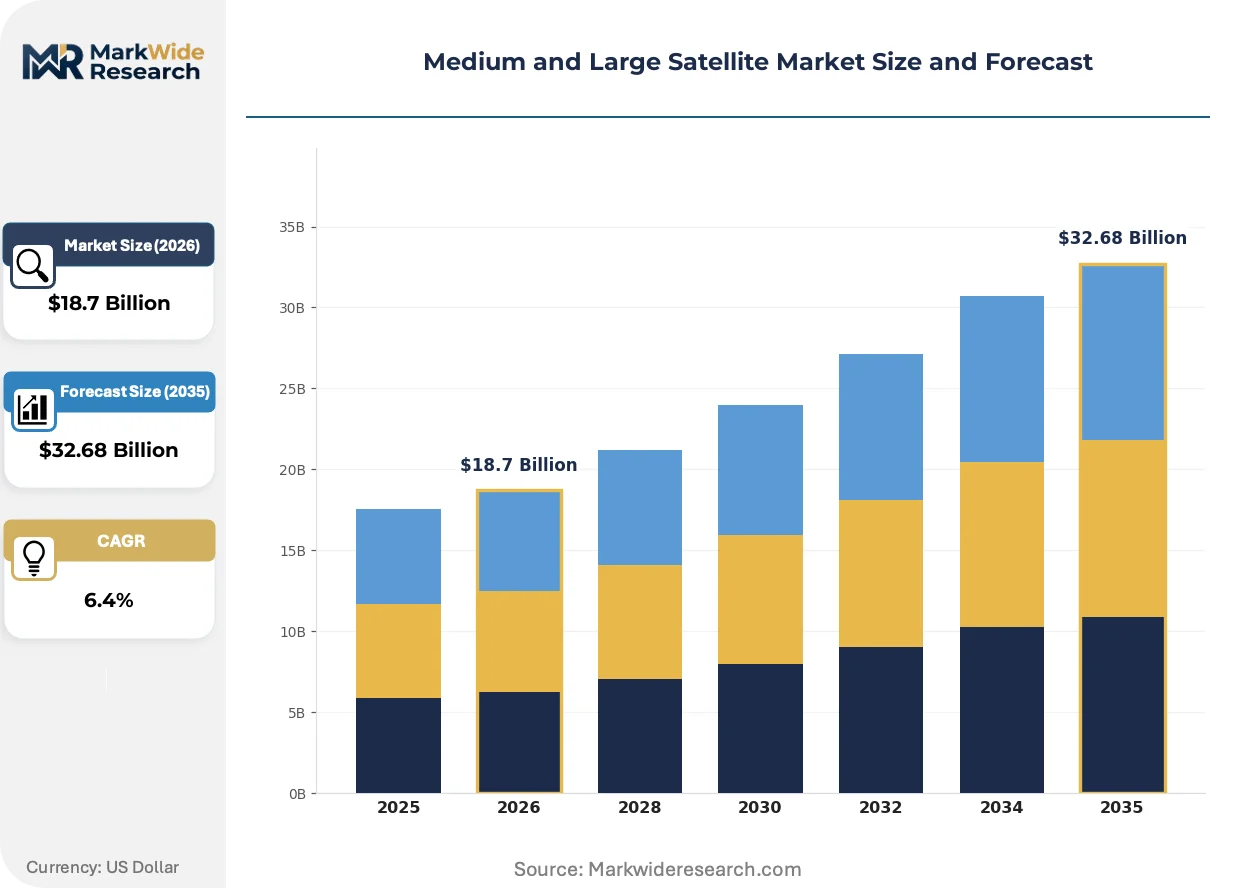
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Satellites, Surveillance Satellites, Earth Observation Satellites, Scientific Satellites Deployment: Geostationary Orbit, Low Earth Orbit, Medium Earth Orbit, Polar Orbit Application: Telecommunication, Weather Monitoring, Navigation, Environmental Monitoring End User: Government Agencies, Commercial Operators, Research Institutions, Defense |
| Companies Covered | The Boeing Company, Lockheed Martin Corporation, Airbus SAS, Northrop Grumman Corporation, L3Harris Technologies Inc., China Aerospace Science and Technology Corporation, Thales Alenia Space, Maxar Technologies, OHB SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium and Large Satellite Market Strategic Shifts & Innovations
Propulsion technology maturation and regulatory material phase-outs are compressing traditional satellite design paradigms. Sovereign procurement channels are diverging from commercial manufacturing standards, while orbital sustainability mandates reshape platform architecture requirements.
Hall-effect electric propulsion is overtaking chemical bipropellant systems for station-keeping on geostationary platforms. Military and commercial operators are adopting this technology to extend service lives beyond fifteen years while reducing launch mass. The shift is overtaking legacy fuel tank sizing methodologies and enabling heavier sensor payloads on fixed bus structures.
Europe's F-Gas Regulation is accelerating thermal control system material substitutions ahead of 2027 compliance deadlines. Satellite manufacturers must qualify alternative working fluids for loop heat pipes and cryocoolers under compressed timelines. European Earth observation programs face the steepest requalification burdens as national space agencies enforce REACH-aligned procurement specifications.
Sovereign buyers are consolidating procurement through classified manufacturing lines rather than commercial satellite production facilities. This channel migration displaces cost-optimized commercial bus architectures from defense programs. The United States exhibits the most pronounced bifurcation, with security-cleared facilities in California and Colorado capturing national security volume while commercial lines serve residual telecom demand.
Medium and Large Satellite Market Segmentation
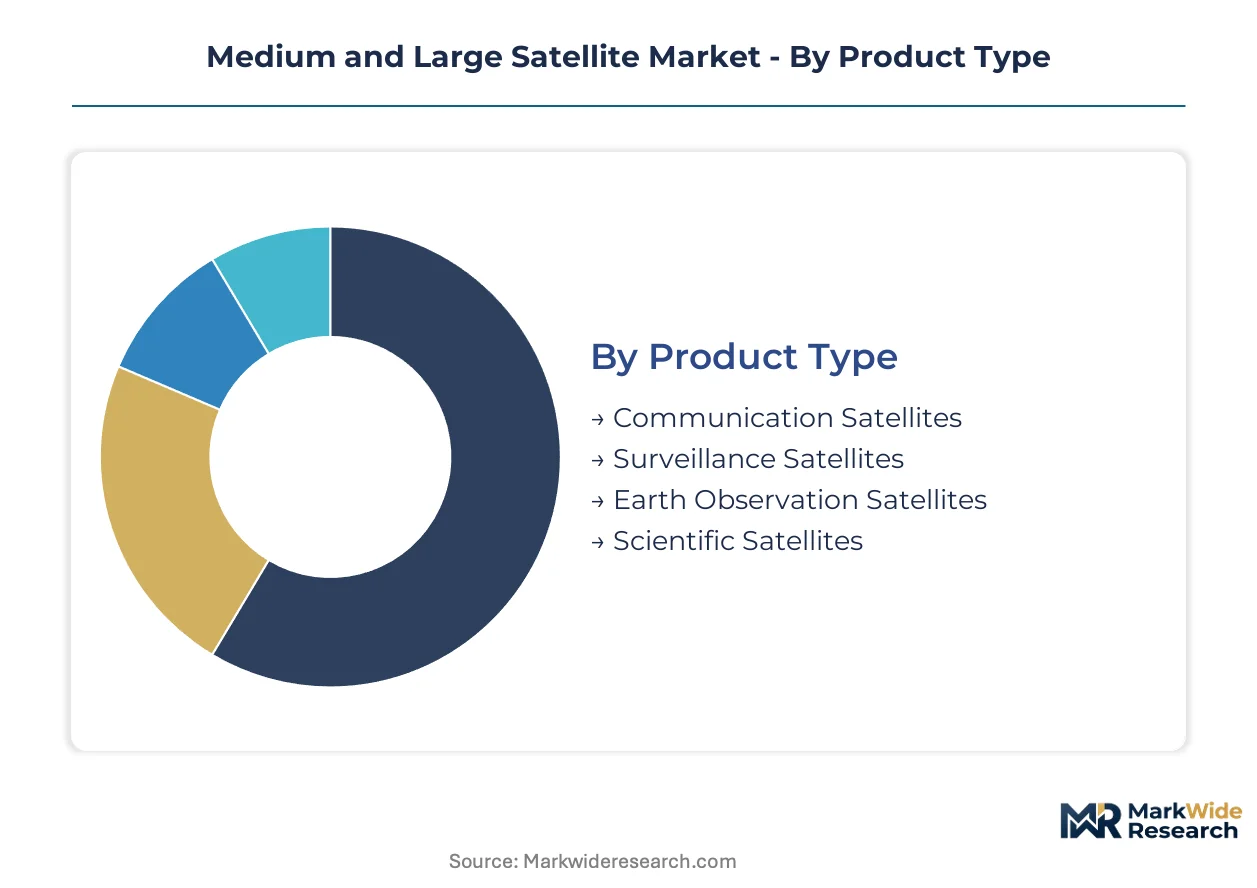
Segmentation in the medium and large satellite market reveals divergent procurement rhythms across sovereign and commercial buyers. Platform specifications vary sharply between persistent geostationary relay missions and proliferating low-altitude constellations. Understanding these divides exposes where design cycles compress and where margins concentrate.
Product Type:
Upgrade cycles for communication platforms are shortening as electric propulsion enables payload mass reallocation without bus redesign.
- Communication Satellites:Geostationary platforms with transponder payloads dominate revenue through bandwidth leasing and managed services. Sovereign buyers in the United States and China are consolidating procurement through classified manufacturing lines rather than commercial channels.
- Surveillance Satellites:Electro-optical and synthetic aperture radar payloads require stabilized bus architectures with precise pointing accuracy. Defense agencies prioritize security-cleared integration facilities over cost-optimized production.
- Earth Observation Satellites:Dual-use sensor fusion is expanding procurement under European government backing.
- Scientific Satellites:Planetary and heliophysics missions command extended development timelines with deep space-qualified subsystems.
Volume placements concentrate in Communication Satellites; the faster expansion belongs to Surveillance Satellites.
Deployment:
Cost tiers separate legacy geostationary platforms from proliferating low-altitude architectures with shortened design lives.
- Geostationary Orbit:Station-keeping demands dominate fuel budgets across fifteen-year service lives. Hall-effect thrusters are displacing chemical bipropellant systems to preserve mass for payload expansion.
- Low Earth Orbit:Constellation deployments are driving individual bus masses above 500 kilograms as dispenser limitations ease. Commercial operators in the United States are commissioning larger platforms than smallsat alternatives permit.
- Medium Earth Orbit:Navigation constellations occupy this altitude band with atomic clock payloads requiring radiation-hardened electronics.
- Polar Orbit:Sun-synchronous trajectories serve Earth observation with consistent illumination geometry.
Revenue gravity centers on Geostationary Orbit; the steepest expansion trajectory belongs to Low Earth Orbit.
Application:
Customer type divides between sovereign bandwidth consumers and commercial service providers with diverging technical specifications.
- Telecommunication:Transponder leasing yields to end-to-end network management contracts as military end-users demand integrated service delivery. This shift elevates recurring revenue above hardware margins.
- Weather Monitoring:Geostationary imagers and polar-orbiting sounders require radiometric calibration stability across decade-long missions. NOAA and EUMETSAT anchor procurement through multi-year appropriations.
- Navigation:Precise timing payloads demand redundant atomic frequency standards with autonomous integrity monitoring.
- Environmental Monitoring:Synthetic aperture radar penetrates cloud cover for all-weather surface observation.
Procurement volume clusters in Telecommunication; Weather Monitoring is climbing the fastest.
End User:
Supply concentration differs sharply between security-cleared defense channels and commercially accessible production lines.
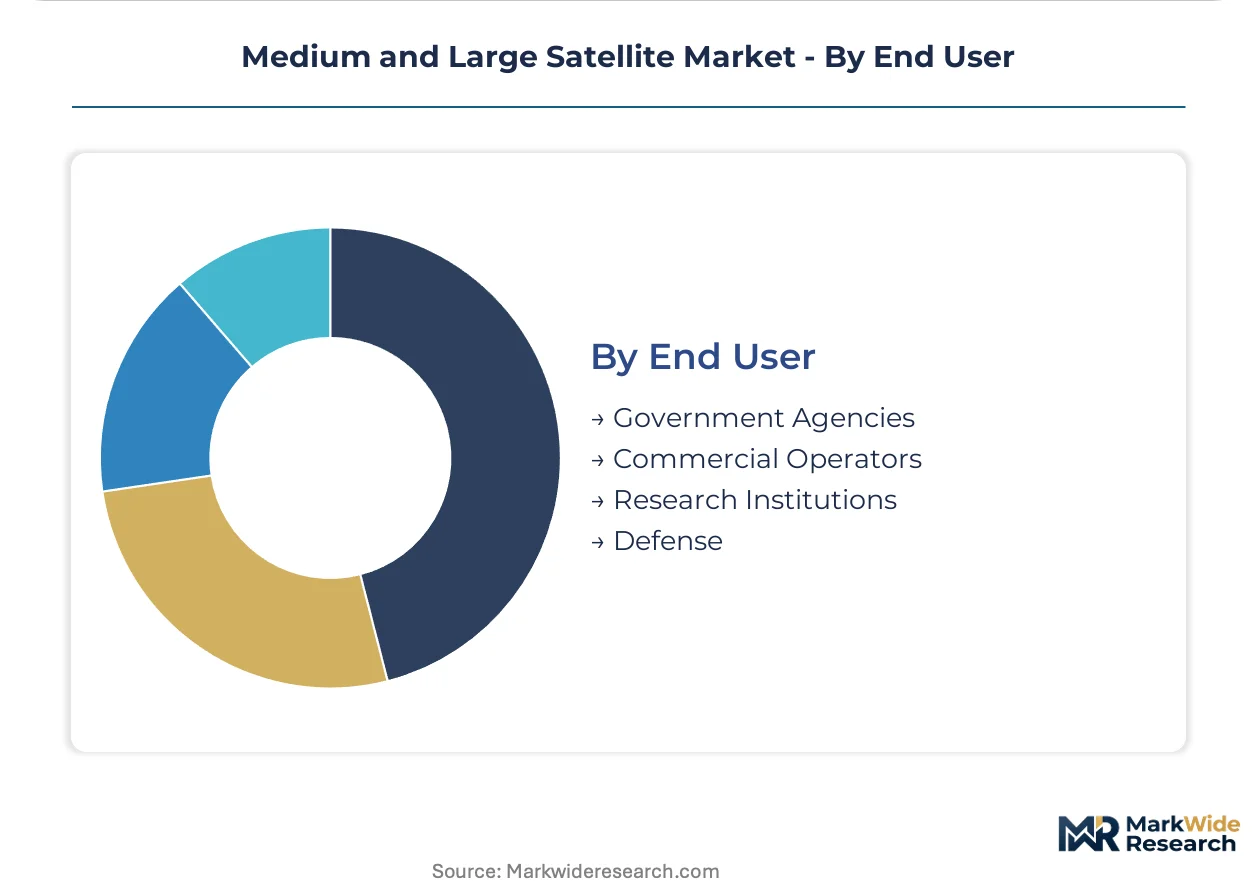
- Government Agencies:Civilian programs operate through civilian space agencies with published technical specifications. NASA and ESA procurement cycles extend across multiple fiscal years with milestone-based payments.
- Defense:Classified payload integration demands cleared personnel and isolated manufacturing facilities. The United States maintains the most pronounced bifurcation between security-cleared and commercial production.
- Commercial Operators:Constellation deployers prioritize bus modularity for rapid replenishment.
- Research Institutions:University-led missions access standardized platforms through national space agency programs.
Contract value concentrates with Government Agencies; Defense is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spaceport America in New Mexico and similar designated aerospace zones concentrate testing infrastructure and manufacturing incentives for satellite producers across multiple sovereign territories.
United States
Classified defense procurement and commercial constellation deployments drive platform demand. The FCC enforces orbital debris mitigation rules requiring passive disposal systems. El Segundo, California hosts security-cleared manufacturing lines serving national security programs.
China
State-owned enterprise channels anchor spacecraft production for navigation and communications constellations. MIIT and SAMR administer frequency allocation and manufacturing standards through centralized procurement. Beijing-Tianjin-Hebei corridor concentrates final assembly facilities for government missions.
France
Dual-use Earth observation missions receive government backing for civilian-military sensor integration. ESA member states operate under EU Space Surveillance and Tracking consortium guidelines plus national export controls. Toulouse anchors Airbus SAS satellite manufacturing with REACH-compliant supply chains.
Germany
Electric propulsion subsystem suppliers serve European geostationary programs. ECHA REACH compliance timelines constrain qualified thermal control material suppliers. Bremen concentrates OHB SE bus integration facilities with F-Gas Regulation-aligned component sourcing.
Japan
Quasi-zenith navigation augmentation and commercial communications sustain platform procurement. METI coordinates space industry policy through public-private partnership frameworks. Tanegashima Space Center supports domestic launch integration for medium-class missions.
Medium and Large Satellite Market Key Industry Players
Top-tier vendors anchor classified defense contracts, while mid-tier specialists compete for commercial Earth observation and science missions. The vendor base separates sharply between security-cleared facilities and commercially accessible production lines. Two archetypes dominate: integrated prime contractors with sovereign backing, and subsystem specialists with propulsion or payload expertise. Competitive moves center on manufacturing capacity expansion in designated aerospace zones and strategic partnerships for electric propulsion technology access.
Among U.S.-based defense primes, Lockheed Martin Corporation and The Boeing Company occupy positions within the classified manufacturing tier, exemplifying the bifurcation between security-cleared and commercial satellite production. Airbus SAS represents the European integrated model with dual-use program backing.
| Leading Market Players |
|---|
| The Boeing Company |
| Lockheed Martin Corporation |
| Airbus SAS |
| Northrop Grumman Corporation |
| L3Harris Technologies Inc. |
| China Aerospace Science and Technology Corporation |
| Thales Alenia Space |
| Maxar Technologies |
| OHB SE |
| Others |
Cost & Logistics Intelligence
Xenon propellant spot prices and heritage component scarcity indices cascade through medium and large satellite supply chains, compressing margins on fixed-price government contracts while elevating premiums for security-cleared manufacturing slots. Sovereign buyers in the United States, China, and France absorb these cost pass-throughs through multi-year appropriations, leaving commercial operators exposed to spot-market volatility in electric propulsion subsystems.
Pricing Analysis
Lead-time premiums dominate pricing architecture, with eighteen-month delivery slots commanding standard rates and sub-twelve-month expedited schedules extracting surcharges above baseline. Three-tier pricing structure across security-cleared, dual-use, and commercial manufacturing tiers reflects certification overhead differentials, with FCC debris-mitigation compliance adding structural mass costs that compress payload budgets. Price erosion runs through commercial geostationary programs as electric propulsion commoditizes, while defense channels exhibit pricing inelasticity due to active clearance requirements. Commercial constellation deployers demonstrate highest price sensitivity, whereas classified program offices prioritize schedule assurance over unit cost.
Supply Chain Analysis
ITAR and EAR qualification gating restricts qualified supplier pools for propulsion subsystems and encryption modules to United States, France, and Germany manufacturing corridors. Hall-effect thruster anode assemblies, heritage bipropellant valves, and radiation-hardened FPGA units draw from single-source or dual-source vendor arrangements with limited second-source qualification. Single-source vulnerability in electric propulsion subsystem supply concentrates risk around xenon feed system manufacturers. Distribution runs through prime contractor integration facilities rather than component spot markets, with ESA and NASA acting as gatekeepers for qualified vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over electric propulsion subsystem supply and security-cleared manufacturing capacity determines competitive survival. Players are pursuing backward integration into Hall-effect thruster production and heritage component captive supply to defend margin position against input cost volatility.
For Market Incumbents: Cement security-cleared workforce pipelines through cleared facility expansion in Colorado and California aerospace clusters. Deepen upstream control over electric propulsion anode manufacturing to offset xenon propellant price volatility, while maintaining dual-use Earth observation bus architectures to capture European government procurement migrating from pure commercial channels.
For New Entrants and Emerging Players: Launch via modular bus platform partnerships with established prime contractors lacking nimble commercial lines. Target commercial Low Earth Orbit constellation deployers in the United States seeking alternatives to legacy geostationary suppliers, with go-to-market positioning centered on rapid requalification timelines for REACH-compliant thermal control materials.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric propulsion specialists with ESA qualification credentials in Germany and France. Long-term viability hinges on sovereign launcher availability alignment and debris-mitigation rule compliance capability across the analysis window. The signal to monitor is FCC orbital debris enforcement intensity against fixed-cost contract portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Security-Cleared Facility Expansion | Captures U.S. defense procurement volume migrating from commercial manufacturing lines. |
| Electric Propulsion Backward Integration | Reduces xenon thruster supply vulnerability and preserves payload mass allocation flexibility. |
| REACH-Compliant Material Requalification | Preserves European Earth observation program access ahead of F-Gas Regulation deadlines. |
| Dual-Use Bus Architecture Development | Opens civilian-military sensor fusion procurement channels under government-backed programs. |
| Sovereign Launcher Partnership | Secures dedicated launch manifest access outside commercial ride-share backlogs. |
Research Approach
Document review covered FCC orbital debris rulings, ESA procurement databases, and MIIT spacecraft manufacturing standards, complemented by interviews with satellite bus integration directors, electric propulsion subsystem engineers, defense procurement officers, and thermal control material suppliers. Secondary validation drew from FAA launch licensing records, ECHA REACH compliance filings, and national space agency appropriation documents. Bottom-up platform unit economics triangulated against top-down sovereign budget allocation analysis.
Segment-level demand outputs across product type, deployment orbit, application, and end-user categories were generated through driver elasticity modeling over the projection horizon. CAGRs were derived from regression against historical procurement cycle timing, launcher manifest availability, and regulatory compliance cost trajectories. Forecast inputs incorporated electric propulsion adoption curves and F-Gas Regulation material substitution timelines.
Sovereign budget reallocation, launcher failure events, and debris-mitigation rule enforcement intensity are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in classified procurement channel volume or REACH compliance timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Earth Observation Satellite Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Satellite Communications Service Market
Satellite
M2M Satellite Communication Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Canada Satellite Connectivity Market
Satellite
Europe Satellite Manufacturing Market
Satellite
South Korea Satellite Communication Market
Satellite
Satellite Operation Service Market
Satellite
Small Satellite Launch Market
Satellite
EMEA Satellite Antenna Market
Satellite
Satellite Data Service Market
Satellite
Satellite Payload Market