
 Asia-Pacific Satellite Manufacturing Market | 2026-2036
Asia-Pacific Satellite Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Manufacturing Market Insights
Commercial telecom operators and Earth observation service providers is redrawing procurement patterns across the Asia-Pacific Satellite Manufacturing Market. China Aerospace Science and Technology Corporation anchors production of large geostationary platforms through vertically integrated facilities in Beijing and Shanghai. Mitsubishi Heavy Industries leverages its H3 launch vehicle integration to sustain captive demand for precision-manufactured satellite buses. Satrec Initiative specializes in compact Earth observation systems, competing aggressively for Southeast Asian government contracts.
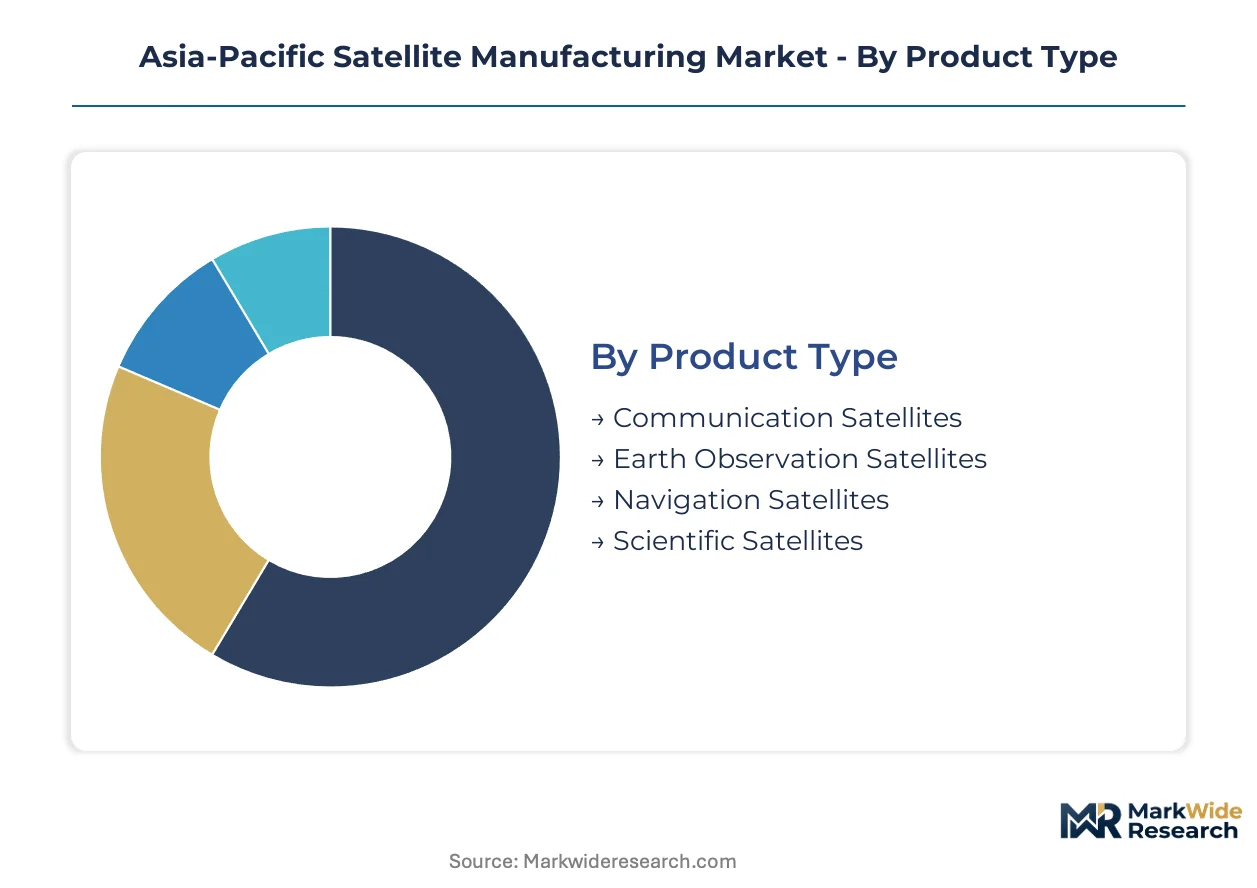
Asia-Pacific satellite manufacturing encompasses the design, fabrication, assembly, and testing of spacecraft platforms, payloads, and subsystems for orbital deployment, typically involving aluminum-lithium alloy structures, gallium arsenide solar cells, and hydrazine or electric propulsion systems rated for fifteen-year operational lifespans in geostationary orbit or five-to-seven-year cycles in low Earth orbit. These systems serve telecommunications relay, remote sensing, precision navigation, and climate monitoring functions for government and commercial clients. Communication Satellites retain the largest revenue share due to sustained transponder leasing demand, though Low Earth Orbit Satellites represent the fastest-expanding technology segment as constellation operators pursue broadband coverage. Earth Observation Satellites command premium margins in the product type category, driven by defense and agricultural analytics procurement.
China's MIIT enforces GB standards for satellite electromagnetic compatibility and frequency coordination, while India's ISRO and IN-SPACe regulate private sector participation through licensing frameworks and shared test facilities. Japan's METI coordinates export control alignment with Wassenaar Arrangement provisions, constraining component trade for certain orbital classes. Stakeholders must monitor evolving spectrum allocation rules and domestic content requirements as national security classifications tighten across the region.
Market Dynamics
The Asia-Pacific Satellite Manufacturing Market is being restructured by the migration from bespoke geostationary platforms to standardized smallsat constellations, compressing production cycles and forcing facility retooling across China's Yangtze River Delta and India's Bengaluru-Hyderabad corridor.
Growth Catalysts
- India's PLI scheme for space manufacturing:Production-linked incentives are redirecting public investment toward domestic satellite production, accelerating private sector participation through shared ISRO test facilities.
- Earth observation constellations:Defense and agricultural analytics procurement is expanding for compact remote sensing systems across Southeast Asian government agencies.
- Dual carbon goals:China's MEE and MIIT are enforcing emissions benchmarks that favor electric propulsion and gallium arsenide solar cell adoption in new spacecraft designs.
Market Restraints
- Aluminum-lithium alloy supply concentration:Structural material sourcing remains captive to a limited supplier base in East Asian metallurgy clusters, exposing manufacturers to input cost volatility.
- GB standards electromagnetic compatibility:China's MIIT enforcement creates certification friction for foreign component vendors seeking frequency coordination approvals.
- Launch capacity bottlenecks:Integration delays with H3 and indigenous launch vehicles are extending satellite delivery timelines for commercial telecom operators.
Strategic Opportunities
- Vietnam and Indonesia government contracts:Underpenetrated Southeast Asian markets present white space for compact Earth observation system vendors competing against established suppliers.
- 5G backhaul integration:Low Earth orbit broadband constellations are converging with terrestrial telecom infrastructure, creating new payload specifications for inter-satellite laser links.
- IN-SPACe licensing frameworks:India's streamlined private sector participation rules are enabling foreign satellite bus manufacturers to establish local assembly partnerships.
Industry Challenges
- Propulsion system integration:Hydrazine-to-electric propulsion transitions require specialized technician training that outpaces current vocational pipeline output in regional manufacturing hubs.
- Wassenaar Arrangement alignment:Japan's METI export control provisions are complicating component trade for certain orbital classes, delaying procurement cycles for dual-use satellite subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Manufacturing Market |
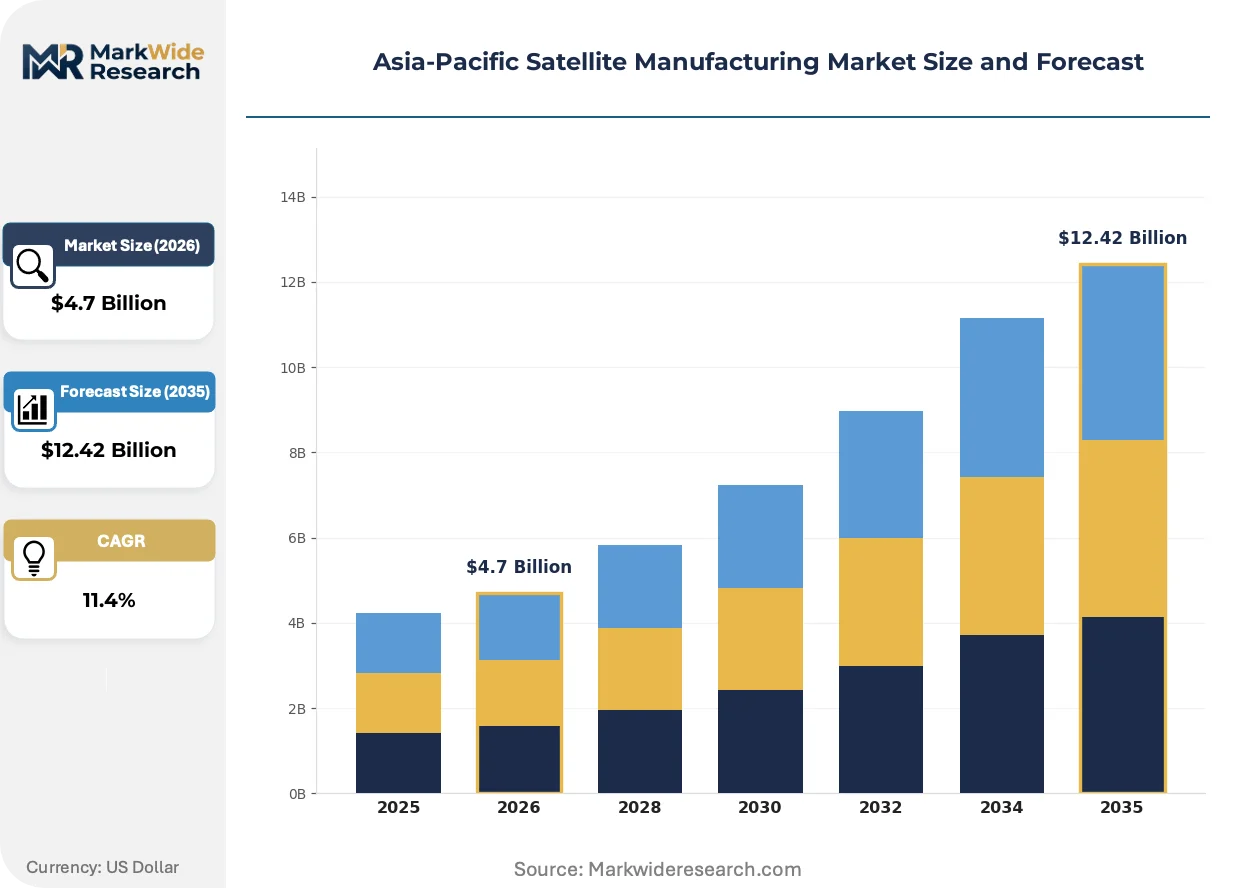
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Satellites, Earth Observation Satellites, Navigation Satellites, Scientific Satellites Technology: Geostationary Satellites, Low Earth Orbit Satellites, Medium Earth Orbit Satellites, CubeSats End User: Government, Commercial, Aerospace, Educational Institutions Service Type: Launch Services, Design & Development, Testing Services, Integration Services |
| Companies Covered | China Aerospace Science and Technology Corporation, Antrix Corporation, Axelspace Corporation, Mitsubishi Heavy Industries, Chang Guang Satellite Technology, Satrec Initiative, Japan Aerospace Exploration Agency, Transpace Technologies, Guodian Gaoke, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Manufacturing Market Trends and Innovations
Standardization of satellite bus architectures is compressing development timelines while opening procurement to non-traditional vendors. Three developments are reshaping competitive positioning.
CubeSat and nanosatellite form factors are miniaturizing Earth observation payloads without sacrificing optical resolution. Agricultural analytics providers and defense agencies across Southeast Asia are adopting these platforms for rapid constellation deployment. The technology is miniaturizing the addressable market for traditional large-platform manufacturers.
China's MIIT is tightening GB standards for satellite electromagnetic compatibility and frequency coordination. The industrial consequence is mandatory redesign of power distribution subsystems for spacecraft operating in shared spectrum bands. Low Earth orbit constellation operators are responding by pre-certifying buses against domestic content requirements before contract bidding.
Telecom operators are unbundling satellite manufacturing from launch procurement, previously purchased as integrated packages. This disintermediation is disrupting captive demand models at major launch providers and opening satellite bus contracts to specialized manufacturers. The shift is most visible in Australia's emerging LEO broadband market, where operators now source spacecraft and launch services through separate tenders.
Asia-Pacific Satellite Manufacturing Market Segmentation
Segmentation in satellite manufacturing determines facility configuration, certification pathways, and procurement timelines. Product type and technology choices dictate aluminum-lithium alloy specifications, propulsion system ratings, and solar cell configurations. End user and service type classifications shape contract structures, risk allocation, and regulatory compliance obligations across the Asia-Pacific production corridor.
Product Type:
Margin pools concentrate in Earth observation platforms where defense and agricultural analytics procurement commands premium pricing for compact remote sensing systems.
- Communication Satellites:Aluminum-lithium alloy structures support fifteen-year operational lifespans in geostationary orbit with gallium arsenide solar arrays and hydrazine propulsion. Telecom operators in China's Yangtze River Delta cluster sustain transponder leasing demand through vertically integrated procurement from Beijing and Shanghai facilities.
- Earth Observation Satellites:Compact optical and synthetic aperture radar payloads serve five-to-seven-year low Earth orbit cycles with electric propulsion adoption accelerating under China's dual carbon goals. Southeast Asian defense agencies and agricultural analytics providers are expanding constellation procurement, compressing production timelines for standardized bus architectures.
- Navigation Satellites:Precision timing payloads require radiation-hardened components and atomic clock integration for regional augmentation systems.
- Scientific Satellites:Specialized instrumentation for space weather and astronomy missions demands custom thermal control and pointing accuracy specifications.
Communication Satellites holds installed capacity. Earth Observation Satellites is rotating up the share rankings.
Technology:
Volume production has shifted toward standardized smallsat form factors that compress assembly timelines and reduce per-unit qualification costs.
- Geostationary Satellites:Large-platform manufacturing with three-axis stabilization and chemical propulsion dominates legacy procurement from established operators. China's MIIT enforces GB standards for electromagnetic compatibility that extend certification cycles for foreign component vendors seeking frequency coordination approvals.
- Low Earth Orbit Satellites:Constellation-scale production of broadband relay platforms with inter-satellite laser links and electric propulsion is displacing bespoke geostationary procurement. Australia's emerging operators now unbundle spacecraft and launch services through separate tender processes, disrupting captive demand models.
- Medium Earth Orbit Satellites:Navigation and specialized communications platforms occupy intermediate orbital regimes with moderate radiation exposure and propulsion requirements.
- CubeSats:Miniaturized form factors enable rapid constellation deployment for technology demonstration and limited-duration missions without full qualification overhead.
Geostationary Satellites retains legacy infrastructure. Low Earth Orbit Satellites is climbing the fastest in new capacity investment.
End User:
Customer type determines contract risk profiles, with government procurement requiring domestic content compliance and commercial operators prioritizing schedule certainty.
- Government:Defense and civilian space agencies specify fifteen-year operational lifespans with full redundancy and ITAR-aligned component sourcing. India's ISRO and IN-SPACe regulate private sector participation through licensing frameworks and shared test facilities that accelerate domestic production qualification.
- Commercial:Telecom operators and Earth observation service providers pursue constellation-scale procurement with standardized buses and compressed delivery schedules. Japan's METI export control alignment with Wassenaar Arrangement provisions constrains component trade for certain orbital classes, extending procurement timelines.
- Aerospace:Launch vehicle manufacturers and space station operators procure specialized platforms with crew-rated safety margins.
- Educational Institutions:Technology demonstration missions and training programs drive demand for simplified interfaces and reduced qualification pathways.
Government holds installed capacity. Commercial is gaining share fastest in new contract awards.
Service Type:
Supply chain configuration separates integrated full-service providers from specialized component and subsystem vendors competing on technical differentiation.
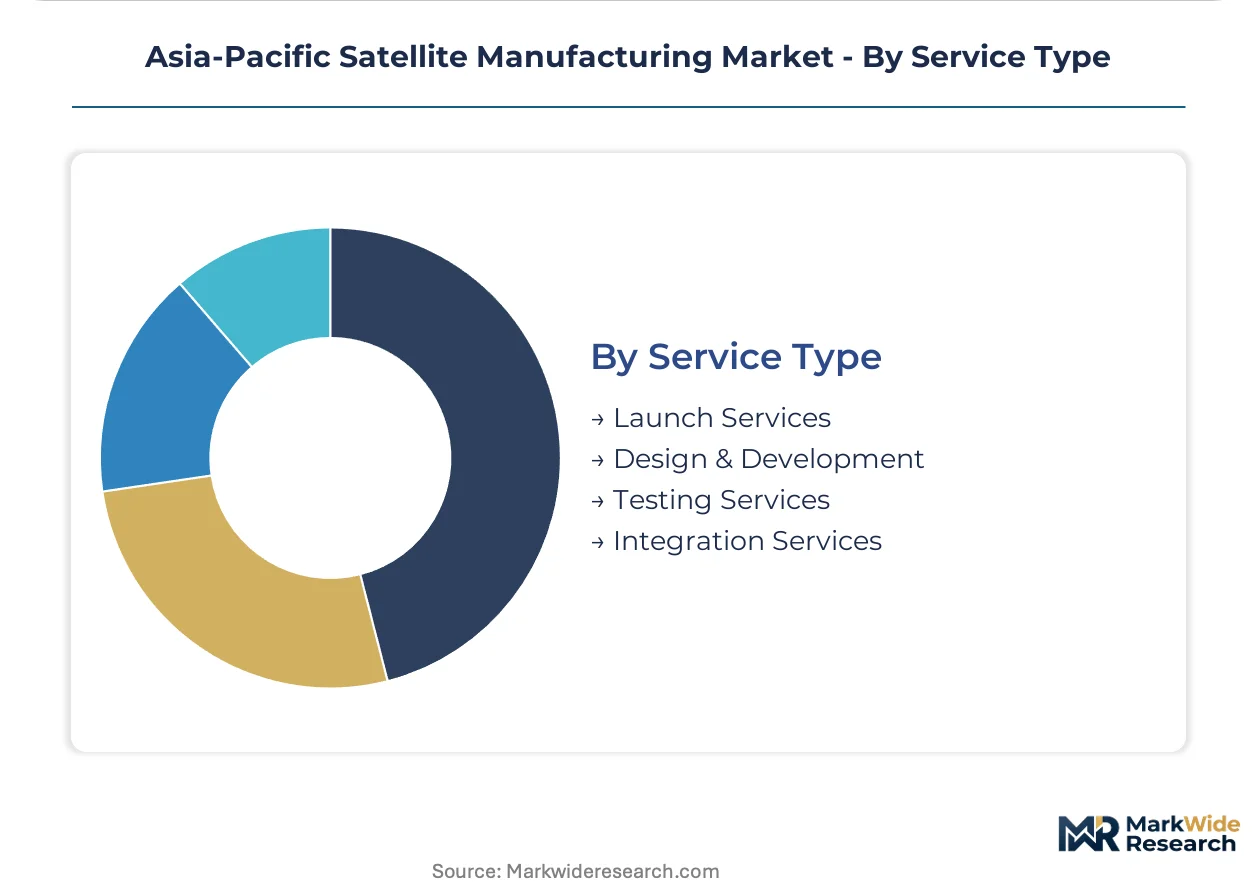
- Launch Services:Integration with H3 and indigenous launch vehicles extends satellite delivery timelines for operators seeking schedule certainty. Mitsubishi Heavy Industries leverages captive launch capacity to sustain demand for precision-manufactured satellite buses.
- Design & Development:Bus architecture standardization and payload integration engineering command premium margins for platforms with electric propulsion transitions requiring specialized technician training.
- Testing Services:Thermal vacuum, vibration, and electromagnetic compatibility qualification facilities represent capacity bottlenecks in India's Bengaluru-Hyderabad corridor.
- Integration Services:Final assembly and system-level verification concentrate in China's Yangtze River Delta cluster with vertically integrated supply chains.
Launch Services holds installed capacity. Design & Development is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in China's Yangtze River Delta and India's Bengaluru-Hyderabad corridor, where vertically integrated facilities and shared test infrastructure compress production cycles for standardized smallsat constellations. Domestic content requirements and dual carbon mandates are redirecting public investment toward localized manufacturing across the region.
China
MIIT enforces GB standards for electromagnetic compatibility and frequency coordination, extending certification cycles for foreign component vendors. The Yangtze River Delta cluster anchors production of large geostationary platforms with vertically integrated facilities in Beijing and Shanghai. MEE emissions benchmarks favor electric propulsion adoption in new spacecraft designs.
India
ISRO and IN-SPACe regulate private sector participation through licensing frameworks and shared test facilities. The Bengaluru-Hyderabad corridor concentrates thermal vacuum and vibration qualification capacity. PLI scheme incentives accelerate domestic satellite production qualification for defense and agricultural analytics procurement.
Japan
METI coordinates export control alignment with Wassenaar Arrangement provisions, constraining component trade for certain orbital classes. Mitsubishi Heavy Industries leverages H3 launch vehicle integration to sustain captive demand for precision-manufactured satellite buses. Kanto region facilities specialize in radiation-hardened component sourcing for government missions.
Australia
Emerging LEO broadband operators unbundle spacecraft and launch services through separate tender processes, disrupting captive demand models. The national space agency coordinates spectrum allocation rules with regional neighbors. Domestic procurement concentrates on inter-satellite laser link payloads for 5G backhaul integration.
South Korea
Seoul Capital Area facilities specialize in compact optical payloads for Earth observation constellations targeting Southeast Asian defense contracts. The national regulator enforces domestic content thresholds for government satellite procurement. Satrec Initiative competes aggressively for regional remote sensing system contracts from Korean manufacturing bases.
Asia-Pacific Satellite Manufacturing Market Competitive Landscape
Concentration sits with state-affiliated aerospace conglomerates and vertically integrated launch providers. The market structure tiers across captive production units, commercial spin-offs, and specialized component vendors. Two archetypes dominate: sovereign champions with guaranteed government offtake, and agile platform specialists winning commercial constellation contracts. Competitive moves center on facility retooling for standardized smallsat production and strategic partnerships for shared test infrastructure access.
Among state-affiliated conglomerates, China Aerospace Science and Technology Corporation anchors sovereign production capacity with vertically integrated supply chains. Mitsubishi Heavy Industries occupies a position bridging launch services and precision-manufactured satellite buses. Satrec Initiative exemplifies the specialist archetype, competing for Southeast Asian government contracts with compact Earth observation platforms. These three represent the spectrum from captive state demand to commercial export orientation.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| Antrix Corporation |
| Axelspace Corporation |
| Mitsubishi Heavy Industries |
| Chang Guang Satellite Technology |
| Satrec Initiative |
| Japan Aerospace Exploration Agency |
| Transpace Technologies |
| Guodian Gaoke |
| Others |
Pricing and Supply Chain Analysis
China's MIIT GB standards for electromagnetic compatibility and frequency coordination gate both supplier qualification and price differentiation simultaneously, extending certification cycles for foreign component vendors while compressing margins for domestic manufacturers unable to absorb compliance overhead. This regulatory architecture stratifies the market into certified premium tiers and uncertified economy alternatives.
Pricing Analysis
China's MIIT GB standards dictate the pricing tier structure across the Asia-Pacific Satellite Manufacturing Market. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened government platforms from commercial constellation buses and unqualified technology demonstrators. Price differentiation rests on certification grade and volume scale, with constellation operators commanding batch discounts unavailable to bespoke geostationary procurement. Cost compression in economy tiers is intensifying because aluminum-lithium alloy supply concentration exposes manufacturers to input volatility. Defense agencies exhibit least price sensitivity due to mission-critical redundancy requirements, while educational institutions and technology demonstrators drive economy tier demand.
Supply Chain Analysis
Extended lead times for gallium arsenide solar cells and hydrazine propulsion subsystems compress manufacturing windows for constellation-scale orders. Supply concentrates in China's Yangtze River Delta, India's Bengaluru-Hyderabad corridor, and Japan's Kanto region, with each cluster specializing in distinct qualification tiers. Raw material dependencies draw from East Asian aluminum-lithium alloy metallurgy, South Korean semiconductor foundries, and domestic electric propulsion development. Single-source vulnerability in structural material sourcing exposes manufacturers to procurement disruption. Distribution runs through vertically integrated state-affiliated conglomerates and specialized component vendors serving commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Satellite Manufacturing Market represents an early-cycle expansion story, with LEO constellation deployment accelerating faster than legacy geostationary replacement cycles. Electric propulsion adoption and standardized bus architectures are compressing development timelines and opening procurement to non-traditional vendors.
For Market Incumbents: Shield sovereign production capacity by deepening backward integration into aluminum-lithium alloy sourcing and gallium arsenide solar cell manufacturing. Acquire specialized electric propulsion developers before constellation operators bring that capability in-house. China's MIIT tightening of GB standards for electromagnetic compatibility presents both defensive moat-building opportunity and compliance cost pressure requiring absorption. For New Entrants and Emerging Players: Shared test infrastructure gaps in India's Bengaluru-Hyderabad corridor present white-space entry points for qualification-as-a-service providers. Vietnam and Indonesia government contracts for compact Earth observation systems remain underpenetrated by established suppliers. Pursue IN-SPACe licensing partnerships to access ISRO thermal vacuum and vibration facilities without capital-intensive facility construction. For Investors and Strategic Acquirers: India's PLI scheme for space manufacturing reshapes the acquisition landscape by subsidizing domestic production qualification and accelerating private sector participation timelines. Target satellite bus specialists with electric propulsion integration capabilities and established Southeast Asian government relationships. Watch for MIIT pre-certification announcements as inflection indicators for contract award probability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Integration | China's MEE emissions benchmarks favor hydrazine-to-electric transitions in new spacecraft designs. |
| Standardized Bus Architecture Development | Constellation operators in Australia's LEO broadband market unbundle spacecraft from launch procurement. |
| Shared Test Infrastructure Partnership | IN-SPACe licensing frameworks enable foreign manufacturers to access ISRO Bengaluru-Hyderabad facilities. |
| Southeast Asian Government Contract Pursuit | Vietnam and Indonesia defense agencies expand procurement for compact Earth observation systems. |
| Aluminum-Lithium Alloy Supply Securement | East Asian metallurgy cluster concentration creates input cost volatility for structural material sourcing. |
Research Methodology
Desk research of satellite manufacturing trade databases, launch manifest records, and national space agency procurement disclosures preceded structured interviews with satellite bus engineering directors, constellation program managers, launch vehicle integration leads, and defense procurement officers across the Asia-Pacific production corridor. Primary fieldwork with ISRO licensing officials and IN-SPACe regulatory staff validated secondary estimates of private sector participation timelines. Bottom-up assembly cost modeling triangulated against top-down national space budget allocations.
Variance decomposition across product type, technology, end user, and service type segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity expansion curves and replacement cycle analysis for geostationary versus low Earth orbit platforms. Forecast inputs incorporated electric propulsion adoption rates, aluminum-lithium alloy price indices, and MIIT certification queue lengths.
Underlying assumptions cover sustained government space agency procurement, stable launch vehicle integration timelines, and unchanged Wassenaar Arrangement export control alignment, with deviation risk concentrated in spectrum allocation rule changes and domestic content requirement escalations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Manufacturing Market
Satellite
Satellite Signal Meter Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Commercial Satellite Launch Service Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Europe Satellite IoT Market
Satellite
Military Satellite Market
Satellite
North America Mobile Satellite Services Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Europe Small Satellite Market
Satellite
South Korea Satellite Communication Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
China Satellite Connectivity Market
Satellite
Saudi Arabia Satellite Communications Market