
 Canada Satellite Connectivity Market | 2026-2036
Canada Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Satellite Connectivity Market Insights
The Canada satellite connectivity landscape is recalibrating around a widening performance gap between premium low-Earth-orbit constellations and legacy geostationary commodity offerings. Starlink leverages its dense LEO architecture to dominate latency-sensitive applications in remote mining and defense corridors. Telesat anchors its position through Lightspeed constellation investments targeting sovereign Arctic coverage obligations. Xplornet competes aggressively on price across rural residential broadband markets where fiber deployment remains uneconomical.
Canada satellite connectivity encompasses orbital and ground-based systems transmitting voice, video, and data signals across C-band, Ku-band, Ka-band, and emerging Q/V-band frequencies, with LEO constellations operating at altitudes below 2,000 kilometers to achieve sub-50 millisecond round-trip latency. Geostationary satellites still occupy the majority of installed broadcasting capacity, though LEO satellites are capturing the fastest expansion in internet services as constellation operators deploy inter-satellite laser links. Military communications represents a concentrated margin pool given Department of National Defence requirements for sovereign-controlled, jam-resistant Arctic pathways.
Health Canada and the PMRA govern radiofrequency exposure limits for ground station installations, while the CRTC's Broadband Fund and ISED's spectrum licensing frameworks directly shape market access timelines for new orbital entrants. The CRTC's mandatory wholesale access rules for satellite-dependent communities influence pricing structures and service obligations across incumbent and new-entrant providers. Stakeholders must monitor Telesat's Lightspeed deployment cadence against Starlink's expanding Canadian subscriber base to assess competitive equilibrium in Arctic coverage.
Market Dynamics
The Canada satellite connectivity market is recalibrating around the sovereign coverage mandate for Arctic communications corridors, where Department of National Defence requirements for jam-resistant, low-latency pathways are forcing constellation operators to prioritize polar orbital planes over equatorial density.
Growth Catalysts
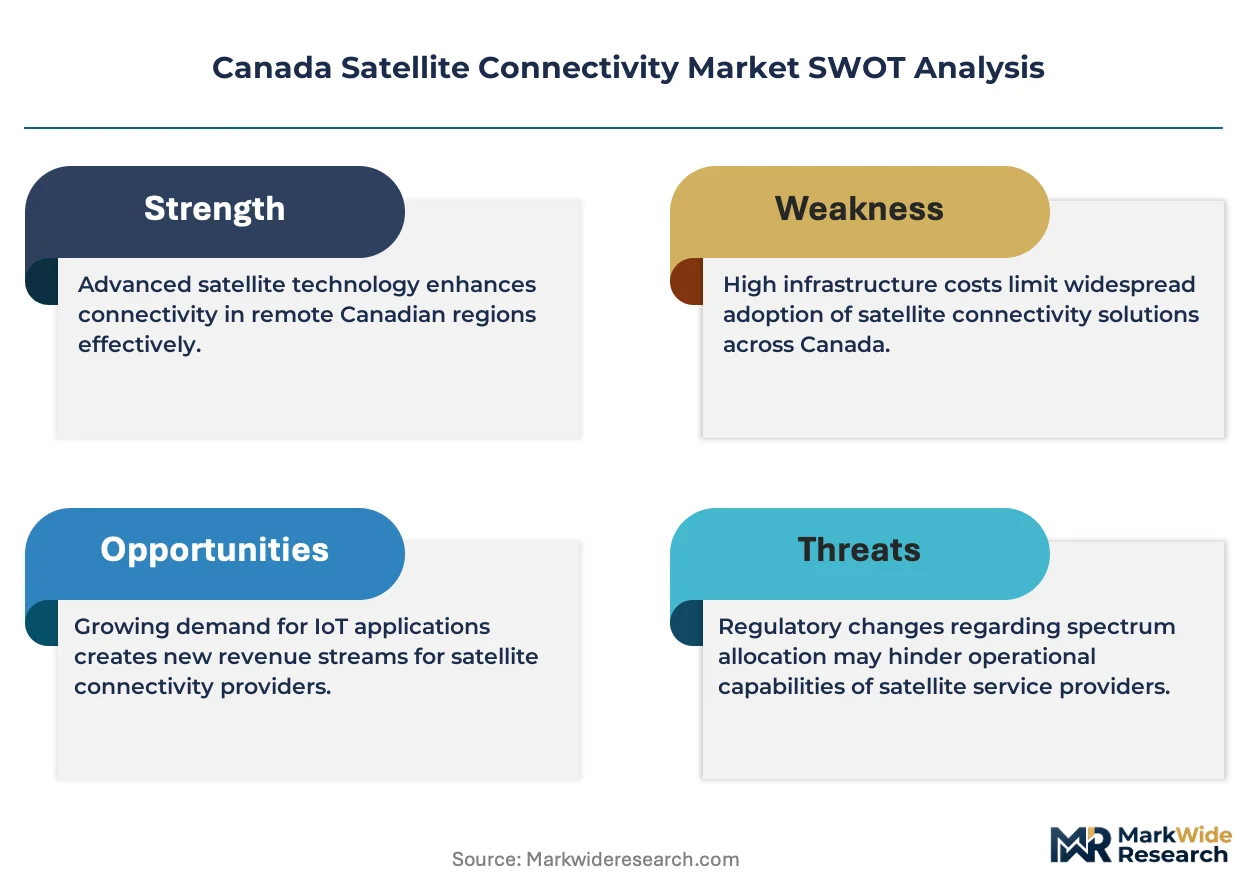
- ISED Spectrum Licensing Framework:Accelerated Ka-band and Q/V-band allocations for non-geostationary orbit systems compress deployment timelines for LEO constellation operators seeking Canadian market entry.
- Remote Mining Operations:Autonomous haulage systems and real-time environmental monitoring in Alberta's oil sands and northern mining districts generate insatiable demand for sub-50 millisecond satellite links where fiber cannot reach.
- CRTC Broadband Fund Mandates:Subsidy pools directed at satellite-dependent communities in Yukon, Northwest Territories, and Nunavut reduce subscriber acquisition costs for orbital service providers targeting residential connectivity gaps.
Market Restraints
- Launch Capacity Concentration:Dependence on a limited number of foreign launch providers creates schedule risk for Canadian-registered constellation deployment, particularly for Telesat's Lightspeed program.
- Ground Station Real Estate Costs:Prime polar gateway locations in Inuvik and Iqaluit command premium lease rates, inflating capital intensity for operators seeking redundant Arctic coverage.
- Health Canada RF Exposure Limits:Stringent electromagnetic field thresholds for terrestrial gateway installations extend site approval timelines and restrict urban co-location options.
Strategic Opportunities
- Nunavut Residential Penetration:Less than one-third of territory households have broadband-quality connectivity, representing a captive subscriber base for price-competitive LEO offerings.
- Defense-Commercial Convergence:NATO Arctic exercises and NORAD modernization programs create dual-use infrastructure opportunities where civilian satellite capacity can serve sovereign military requirements.
- Inter-Satellite Laser Link Integration:Optical mesh networking between orbital assets eliminates ground gateway dependency for trans-polar traffic, reducing latency to European and Asian endpoints.
Industry Challenges
- Arctic-Qualified Technician Scarcity:Ground station maintenance and installation in extreme cold climates requires specialized certifications that Canadian technical colleges currently underproduce.
- Legacy GEO System Integration:Mining and broadcast incumbents with sunk investments in geostationary terminals resist forklift upgrades to LEO architectures, complicating hybrid service provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Satellite Connectivity Market |
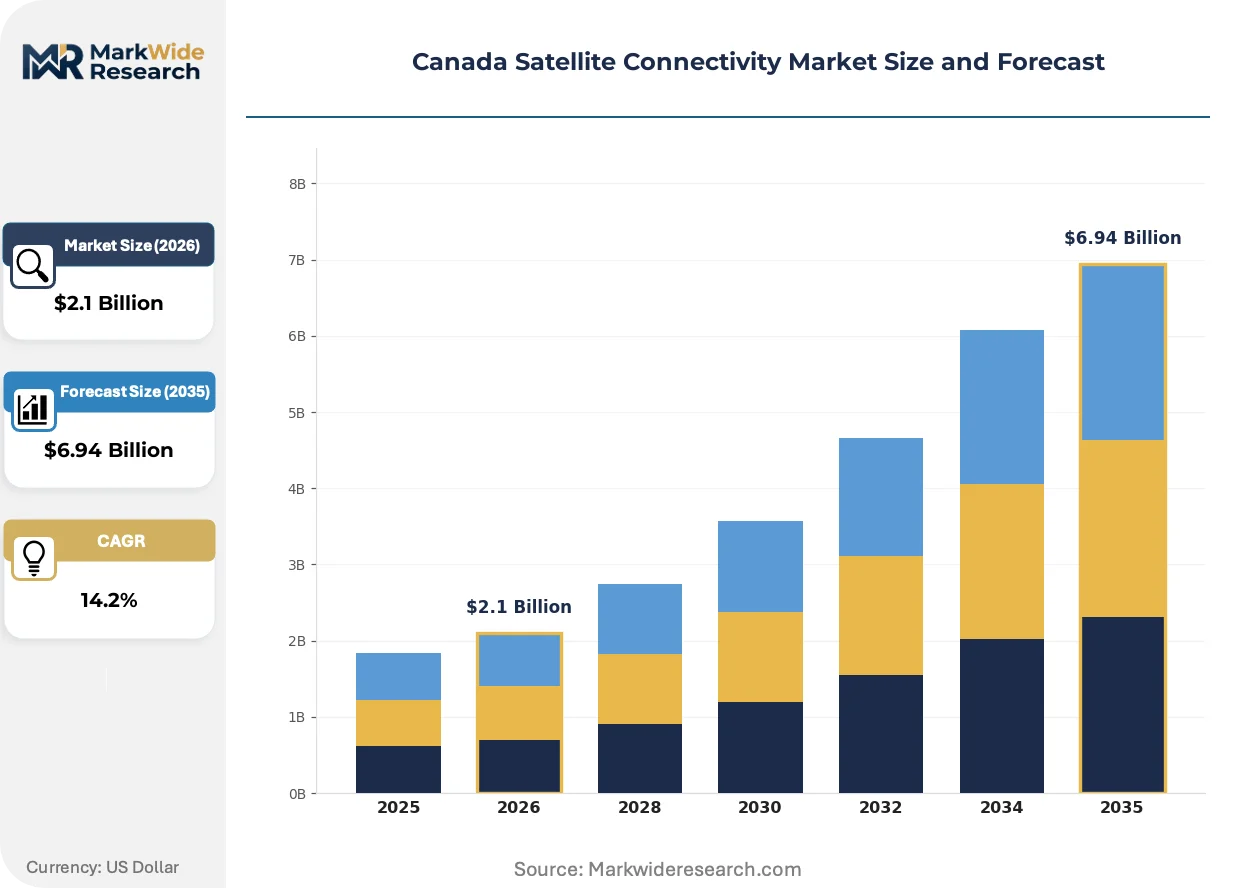
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.94 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geostationary Satellites, LEO Satellites, MEO Satellites, Hybrid Satellites Service Type: Internet Services, Broadcasting Services, Data Services, Military Communications End User: Aerospace, Maritime, Government, Telecommunication Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | HughesNet, Xplornet, Starlink, EchoStar, Rogers, Telesat, Eutelsat OneWeb, Thuraya Telecommunications, Viasat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Satellite Connectivity Market Trends and Innovations
Orbital architectures are fragmenting into performance-tiered service layers, with laser-linked LEO constellations capturing latency-sensitive workloads while geostationary platforms retreat to bulk video distribution and backup connectivity roles.
Software-defined radio payloads aboard next-generation Canadian-registered satellites are unifying multiple frequency bands onto single orbital assets. Resource extraction operators in the Northwest Territories are adopting these flexible terminals to switch between C-band resilience and Ka-band throughput without hardware swaps. This capability is unifying what were previously separate backup and primary link procurement decisions into single-vendor relationships.
Innovation Canada's Strategic Innovation Fund has expanded eligibility to include domestic satellite manufacturing and ground system component production. The fund's repayable contribution structure now covers up to 50% of eligible R&D costs for orbital hardware developed within Canada. Arctic constellation operators and their supply chain partners are restructuring project financing to access these non-dilutive capital pools ahead of commercial service launch.
Enterprise buyers in remote resource sectors are consolidating vendor relationships around integrated managed-service contracts that bundle terminal hardware, bandwidth, and field maintenance into single per-site fees. This procurement compression displaces the historical pattern of separate negotiations with dish installers, bandwidth resellers, and repair contractors. The shift is most visible in Alberta's oil sands camps, where facility operators now prioritize uptime guarantees over raw throughput metrics in supplier selection.
Canada Satellite Connectivity Market Segmentation
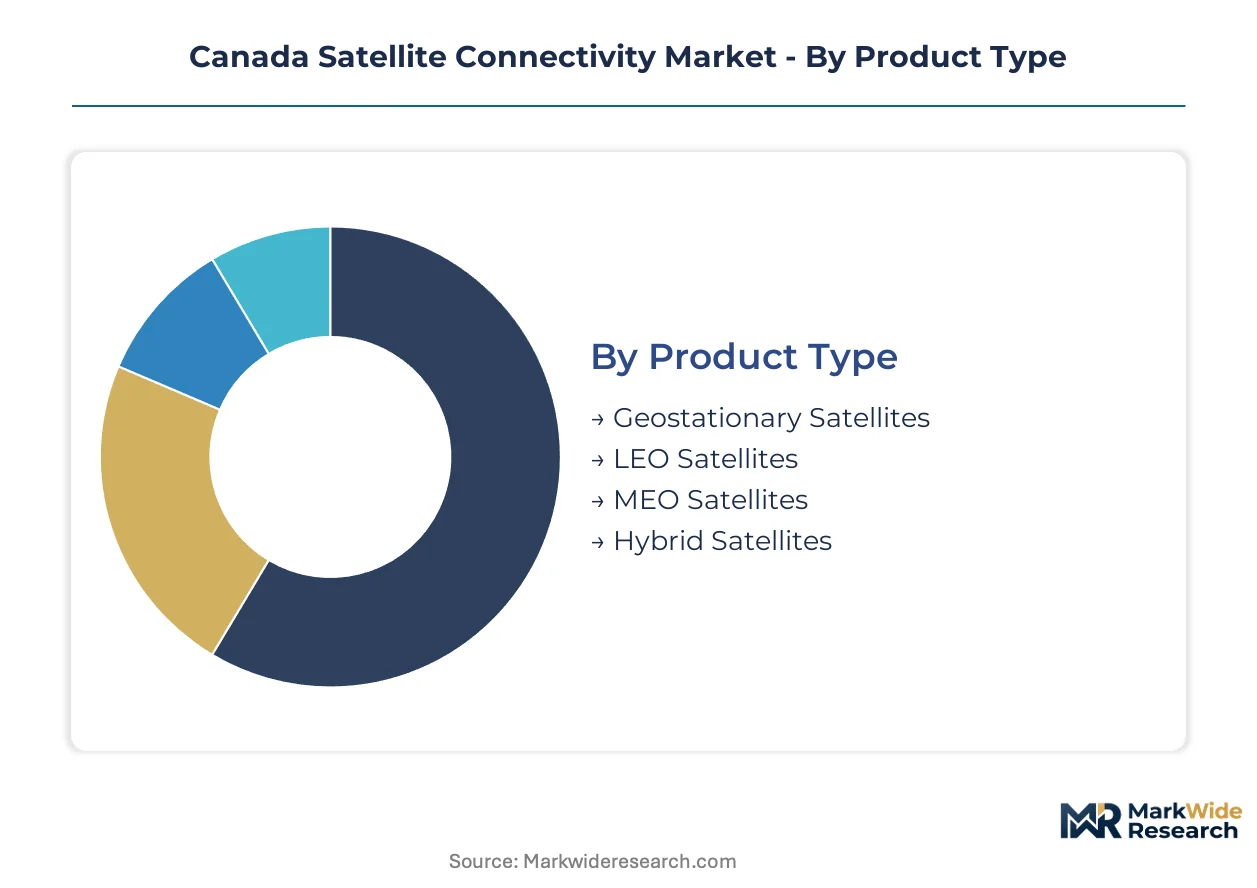
Canada's satellite connectivity market fragments across orbital architectures, service layers, and deployment models that reflect the country's unique geography. Arctic sovereignty requirements and northern resource extraction patterns create concentrated demand profiles that diverge from temperate-zone markets.
Product Type:
Orbital altitude and constellation architecture determine latency performance, coverage footprint, and capital intensity for Canadian operators.
- Geostationary Satellites:Positioned at 35,786 kilometers above the equator, these assets deliver persistent single-point coverage across Canadian latitudes. Broadcasting incumbents and remote mining camps with legacy terminals rely on GEO platforms for video distribution and backup connectivity where millisecond latency is non-critical.
- LEO Satellites:Operating below 2,000 kilometers, these constellations achieve sub-50 millisecond round-trip latency through dense orbital planes. Real-time autonomous haulage systems in Alberta's oil sands and NORAD Arctic corridors drive procurement of these low-latency links.
- MEO Satellites:Medium-Earth-orbit assets at 8,000-12,000 kilometers balance latency and coverage economics for maritime and aeronautical mobility applications.
- Hybrid Satellites:Multi-orbit terminals switch between GEO resilience and LEO throughput based on application priority and link conditions.
Mature deployment sits with Geostationary Satellites. Newer deployment is concentrated in LEO Satellites.
Service Type:
Revenue concentration aligns with sovereign mandates and resource sector digitization timelines across Canadian territories.
- Internet Services:Residential and enterprise broadband delivered via LEO constellations captures the steepest expansion trajectory as CRTC Broadband Fund subsidies reduce subscriber acquisition costs in Yukon, Northwest Territories, and Nunavut.
- Broadcasting Services:Direct-to-home television and radio distribution remains anchored in GEO capacity, with northern communities dependent on satellite-delivered content where fiber backhaul cannot reach.
- Data Services:Enterprise-grade private networks and cloud connectivity for remote industrial sites.
- Military Communications:Department of National Defence requirements for sovereign-controlled, jam-resistant Arctic pathways concentrate margin in this segment.
Commercial volume concentrates in Internet Services. Defense margin pools in Military Communications.
End User:
Customer procurement authority and uptime requirements shape contract structures and vendor selection criteria.
- Government:Federal and territorial agencies procure sovereign-controlled connectivity for Arctic operations, emergency response, and indigenous community services. CRTC mandates and Innovation Canada funding frameworks directly shape acquisition timelines.
- Telecommunication:Incumbent carriers and regional ISPs lease satellite capacity to extend service footprints beyond fiber economics.
- Aerospace:Commercial aviation and unmanned systems require mobility-optimized links.
- Maritime:Coastal shipping and Arctic vessel operations demand continuous connectivity across Canadian waters.
Procurement scale favors Government. Growth velocity sits with Telecommunication.
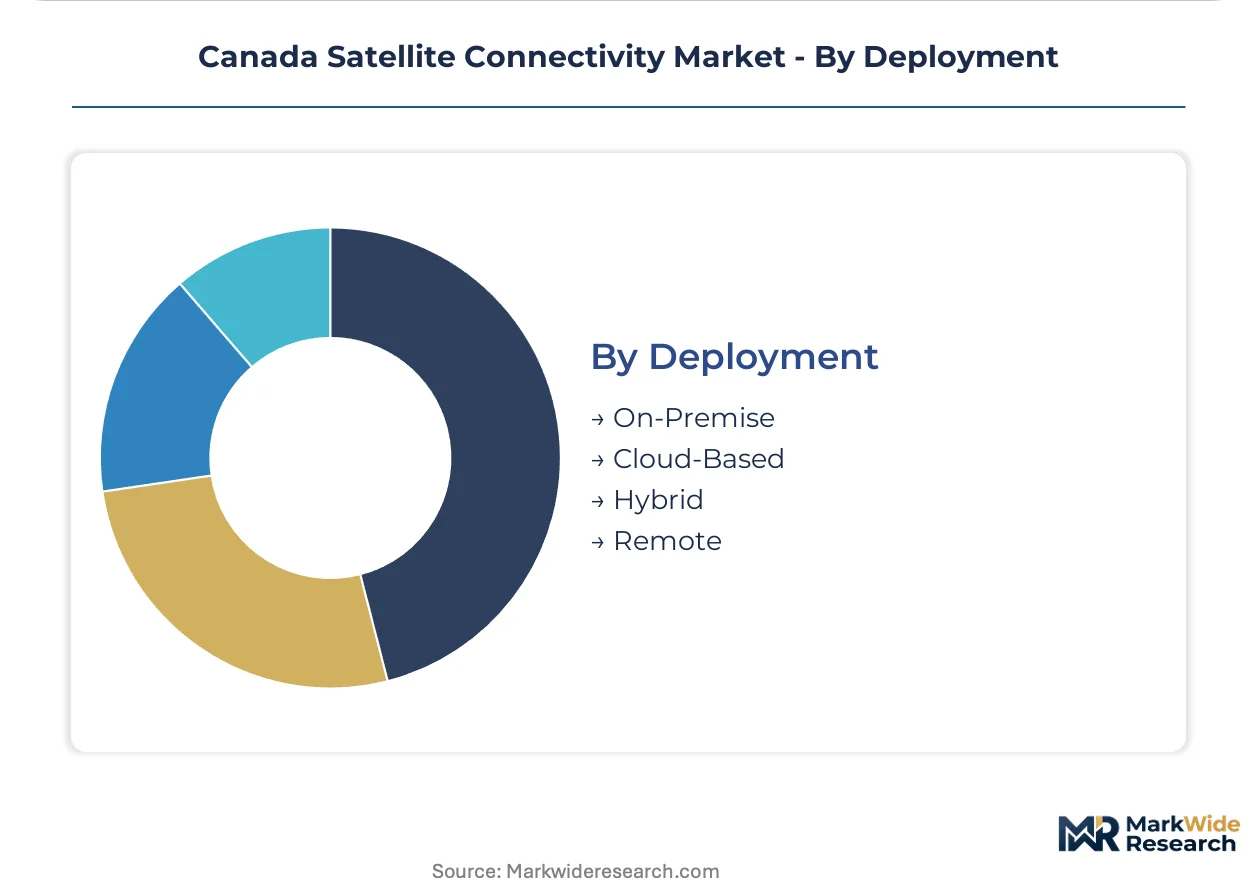
Deployment:
Infrastructure location relative to terrestrial network availability determines operational complexity and total cost of ownership.
- Remote:Standalone installations in Canada's three northern territories operate without fiber or cellular fallback. Ground station maintenance in Inuvik and Iqaluit requires Arctic-qualified technicians that Canadian technical colleges underproduce.
- Hybrid:Combined satellite-terrestrial configurations prioritize satellite for backup and overflow capacity.
- On-Premise:Enterprise-owned gateway equipment for mining camps and defense facilities with security requirements.
- Cloud-Based:Virtualized network functions and managed service delivery reduce capital burden for mid-market customers.
Capital intensity peaks in Remote deployment. Operational flexibility expands in Cloud-Based configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inuvik anchors Canada's satellite gateway infrastructure, hosting polar ground stations that serve Arctic orbital corridors where fiber cannot reach.
Ontario
Ottawa's technology corridor concentrates satellite R&D and ground system manufacturing, with Kanata-based firms supplying antenna components to constellation operators. Innovation Canada's Strategic Innovation Fund channels repayable contributions toward domestic orbital hardware development. Toronto's financial district structures project financing for LEO deployments, while Waterloo's engineering cluster feeds specialized software talent into network management systems.
Quebec
Montreal hosts Telesat's corporate headquarters and satellite control operations, anchoring sovereign constellation management for Arctic coverage mandates. The CRTC's broadband connectivity rulings directly shape provincial deployment priorities for remote communities. Saguenay-Lac-Saint-Jean's industrial base supplies precision machined components for ground station installations, with local technical colleges expanding RF technician certification programs.
Alberta
Fort McMurray's oil sands camps generate concentrated demand for low-latency links powering autonomous haulage and real-time environmental monitoring systems. The province's energy regulator mandates continuous emissions monitoring that satellite backhaul enables at remote extraction sites. Calgary's corporate headquarters cluster hosts procurement teams for major resource operators consolidating vendor relationships around managed-service contracts.
British Columbia
Vancouver's port and coastal shipping lanes drive maritime connectivity requirements for vessel tracking and crew welfare communications. The province's mountainous terrain leaves persistent cellular gaps along highway corridors and interior mining districts where hybrid satellite-terrestrial configurations prevail. Prince Rupert's expanding container terminal operations require dedicated bandwidth for logistics coordination with Asian trade partners.
Northern Territories
Iqaluit, Yellowknife, and Whitehorse represent captive subscriber bases where less than one-third of households access broadband-quality connectivity through terrestrial means. The CRTC Broadband Fund directs subsidy pools specifically at satellite-dependent communities across Nunavut, Northwest Territories, and Yukon. Arctic sovereignty operations by the Department of National Defence concentrate procurement authority for jam-resistant, sovereign-controlled pathways in these jurisdictions.
Canada Satellite Connectivity Market Competitive Landscape
Premium-margin players sit above commodity-margin players across latency performance and sovereign control dimensions, with low-Earth-orbit constellation operators capturing latency-sensitive applications while geostationary incumbents defend broadcasting and backup connectivity roles. The vendor base stratifies into three archetypes: vertically integrated constellation owners, terrestrial network extenders leasing orbital capacity, and specialized managed-service integrators bundling hardware, bandwidth, and field maintenance. Capacity expansion through polar orbital plane deployment and strategic partnerships for gateway infrastructure represent the dominant competitive moves as operators race to satisfy Arctic coverage obligations.
Within the constellation-owner tier, Starlink and Telesat occupy distinct positioning vectors, with the former leveraging dense LEO architecture for consumer and enterprise penetration while the latter anchors sovereign Arctic coverage through Lightspeed investments. Xplornet represents the network-extender archetype, competing aggressively on price across rural residential markets where fiber deployment remains uneconomical. Among geostationary incumbents, HughesNet exemplifies the commodity-margin defender, maintaining installed broadcasting capacity and backup link relationships with mining camps resistant to terminal hardware upgrades.
| Leading Market Players |
|---|
| HughesNet |
| Xplornet |
| Starlink |
| EchoStar |
| Rogers |
| Telesat |
| Eutelsat OneWeb |
| Thuraya Telecommunications |
| Viasat |
| Others |
Pricing and Supply Chain Analysis
Inter-satellite laser link deployment is compressing gateway infrastructure requirements while simultaneously concentrating manufacturing leverage among optical component specialists in Canada and the United States. This dual shift reduces per-bit transmission costs for constellation operators but amplifies dependency on precision photonics suppliers with limited surge capacity.
Pricing Analysis
Uptime guarantees anchor value-based pricing for remote mining camps and defense facilities where connectivity failures halt operations. Three-tier pricing structure across premium low-latency LEO, standard hybrid GEO-LEO bundles, and economy GEO backup tiers reflects latency sensitivity and sovereign control requirements. Cost compression in economy GEO tiers is intensifying because Starlink's consumer pricing sets a ceiling for residential satellite broadband. Government procurement teams show least price sensitivity due to Arctic sovereignty mandates, while rural residential subscribers exhibit highest elasticity.
Supply Chain Analysis
Terminal refurbishment flows from northern mining camps to Calgary and Montreal service centers extend hardware lifecycles and reduce gateway equipment procurement cycles. Satellite manufacturing concentrates in the United States, France, and Canada, with ground station components sourced from specialized RF equipment producers in Germany and Japan. Supply chain risk centers on single-source vulnerability for radiation-hardened chipsets from qualified foundries. Distribution runs through Telesat and Starlink direct sales teams for enterprise accounts, with Xplornet channel partners handling rural residential subscriber acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation operators are racing to secure backward integration into domestic satellite manufacturing and captive polar gateway real estate. Control over these upstream assets determines margin defense against launch cost volatility and Arctic coverage mandates.
For Market Incumbents: Anticipate Starlink's subscriber scale advantages by accelerating Telesat Lightspeed deployment cadence and securing long-term leaseholds in Inuvik and Iqaluit gateway sites. Defensive consolidation through exclusive managed-service contracts with Alberta oil sands operators locks out emerging LEO competitors. Certification investment in Health Canada RF compliance streamlines site approvals and accelerates time-to-revenue for new ground stations.
For New Entrants and Emerging Players: The CRTC Broadband Fund in Canada opens a window for specialized integrators targeting Nunavut residential penetration where less than one-third of households have broadband-quality connectivity. White-space targets include Arctic-qualified technician training partnerships with Saguenay-Lac-Saint-Jean technical colleges and software-defined radio terminal development for hybrid GEO-LEO switching. Go-to-market leverage rests on per-site managed-service bundling that displaces fragmented procurement patterns in remote mining camps.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated constellation operators seeking sovereign Arctic coverage credentials and established government procurement relationships. Long-term viability favors assets with secured spectrum allocations, polar orbital plane licenses, and exclusive gateway leaseholds in Canada's northern territories. Monitor Telesat Lightspeed launch schedules and CRTC subsidy disbursement rates as inflection indicators for competitive equilibrium timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Polar Gateway Expansion | Secures redundant Arctic coverage for NORAD modernization and NATO exercise requirements. |
| Domestic Manufacturing Scale-Up | Accesses Innovation Canada Strategic Innovation Fund repayable contributions for orbital hardware R&D. |
| Inter-Satellite Laser Link Integration | Eliminates trans-polar ground gateway dependency and reduces latency to European endpoints. |
| Managed-Service Contract Consolidation | Captures oil sands procurement authority by bundling terminal, bandwidth, and field maintenance. |
| Spectrum Licensing Acceleration | Compresses ISED Ka-band and Q/V-band allocation timelines for LEO constellation market entry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with constellation program directors, CRTC policy officers, mining camp procurement managers, and Arctic gateway technicians combined with secondary validation from ISED spectrum allocation databases, Innovation Canada contribution agreements, and CRTC Broadband Fund disbursement records. Bottom-up subscriber projections across Yukon, Northwest Territories, and Nunavut triangulated against top-down orbital capacity estimates from Telesat and Starlink technical specifications.
Segmentation granularity modeled orbital architecture, service layer, and deployment mode dimensions across the projection horizon. CAGRs derived from installed base growth curves adjusted for CRTC subsidy pool expansion and autonomous haulage system adoption timelines in Alberta's oil sands. Industry-specific inputs included polar orbital plane deployment schedules, Health Canada RF exposure compliance timelines, and Arctic-qualified technician graduation rates from Canadian technical colleges.
The model assumes a particular technology adoption path; alternative pathways for inter-satellite laser link maturation would alter the outlook for ground gateway infrastructure investment. Forecasts reflect assumptions about CRTC mandate continuity and Innovation Canada funding availability. Practitioners should monitor ISED spectrum auction timing and Telesat launch contract execution for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Payload Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
GEO Satellite Market
Satellite
UAE Satellite Communication Market
Satellite
Satellite Communication System Market
Satellite
Satellite Signal Meter Market
Satellite
Europe Military Satellite Market
Satellite
Satellite Antenna Market
Satellite
Optical Satellite Communication Market
Satellite
Nanosatellite Market
Satellite
Nano and Microsatellite Market
Satellite
High-Throughput Satellite Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Israel Satellite Imagery Services Market
Satellite
US Remote Sensing Technology Market
Satellite
Italy Satellite Communication Market