
 Communication Satellite Launch Services Market | 2026-2036
Communication Satellite Launch Services Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Satellite Launch Services Market Insights
The FCC's streamlined licensing framework for large constellations is restructuring cost-of-entry calculus for new orbital ventures. SpaceX leverages reusable Falcon 9 architecture to dominate commercial rideshare missions. Rocket Lab sustains dedicated small-launch capacity from its New Zealand and Virginia facilities. United Launch Alliance anchors national security demand through Atlas V and Vulcan Centaur reliability.
Communication satellite launch services encompass the end-to-end delivery of orbital payloads from integration through deployment, typically involving launch vehicles with thrust exceeding 200 kN for geostationary missions or sub-500 kg dedicated capacity for constellation batches. Expendable vehicles still carry the majority of geostationary telecom payloads where mass-to-orbit requirements exceed reusable margins. Low Earth Orbit rideshare services represent the fastest-expanding segment as Starlink-style constellations demand frequent, standardized injection schedules. Dedicated launch contracts for military organizations command premium pricing due to mission assurance protocols and vertical integration requirements.
NASA, the FAA Office of Commercial Space Transportation, and the US Space Force collectively shape US market access through launch licensing, range safety, and national security payload allocation. ESA's Ariane 6 qualification and India's IN-SPACe liberalization are creating parallel regulatory ecosystems that fragment vendor certification pathways. Stakeholders must monitor how spectrum coordination rules and debris mitigation standards reshape manifest priority and insurance underwriting before committing to multi-launch procurement strategies.
Market Dynamics
Reusable launch vehicle technology is compressing per-kilogram payload economics while fragmenting vendor competitive positions around flight-proven reliability versus dedicated mission assurance. This structural force is redrawing procurement criteria for constellation operators and national security buyers alike.
Growth Catalysts
- LEO broadband constellations:Telecom operators are pulling launch demand through standardized, high-frequency injection schedules that favor rideshare architectures and compress procurement cycles.
- FCC streamlined licensing:The US regulator's large-constellation framework is lowering cost-of-entry calculus for new orbital ventures and accelerating manifest commitments.
- Reusable first-stage recovery:Propulsive landing technology is extending vehicle life and enabling price competition that expands addressable customer segments.
Market Restraints
- Launch site congestion:Range capacity at Cape Canaveral and Vandenberg is creating manifest bottlenecks that extend lead times for commercial customers.
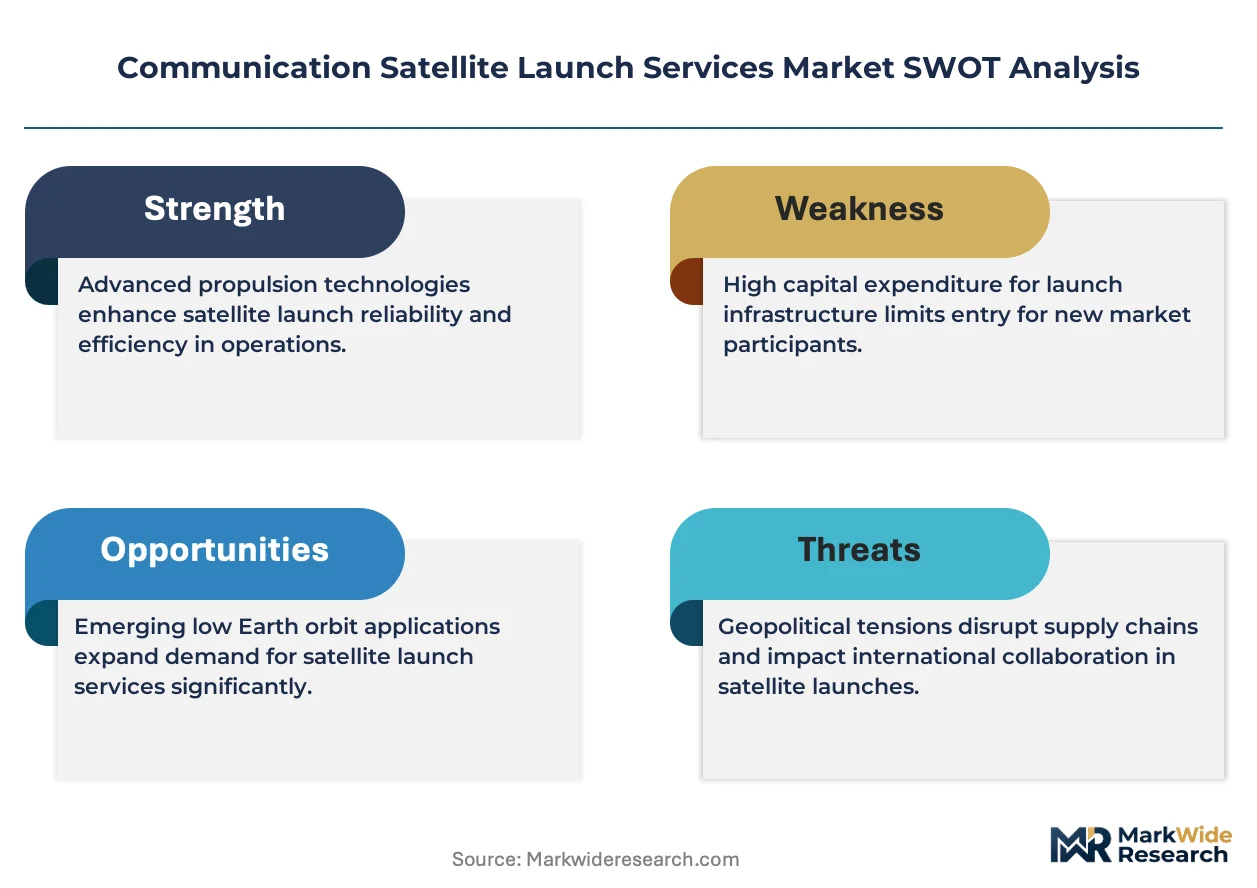
- Propellant supply concentration:Hydrocarbon fuel and liquid oxygen production clusters in Gulf Coast refining corridors expose operators to weather and logistics disruptions.
- Insurance underwriting rigidity:Traditional space liability frameworks have not adapted to reusable vehicle risk profiles, inflating premium structures for early-flight customers.
Strategic Opportunities
- India's IN-SPACe liberalization:The national spaceport opening to private launch providers creates an alternative Eastern Hemisphere launch corridor with polar and equatorial access.
- On-orbit servicing integration:Convergence of rendezvous-docking protocols with refueling infrastructure is enabling extended satellite lifecycles and deferred replacement launches.
- Military assured-access mandates:US Space Force multi-year procurement commitments are creating predictable revenue streams for vehicles meeting mission-unique vertical integration requirements.
Industry Challenges
- Debris mitigation compliance:Post-mission disposal regulations from FCC and emerging ISO standards are forcing design changes that reduce payload fraction and complicate mission planning.
- Propulsion engineering talent scarcity:Liquid oxygen-methane turbopump specialists and avionics integration engineers command premium compensation that inflates fixed cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Satellite Launch Services Market |
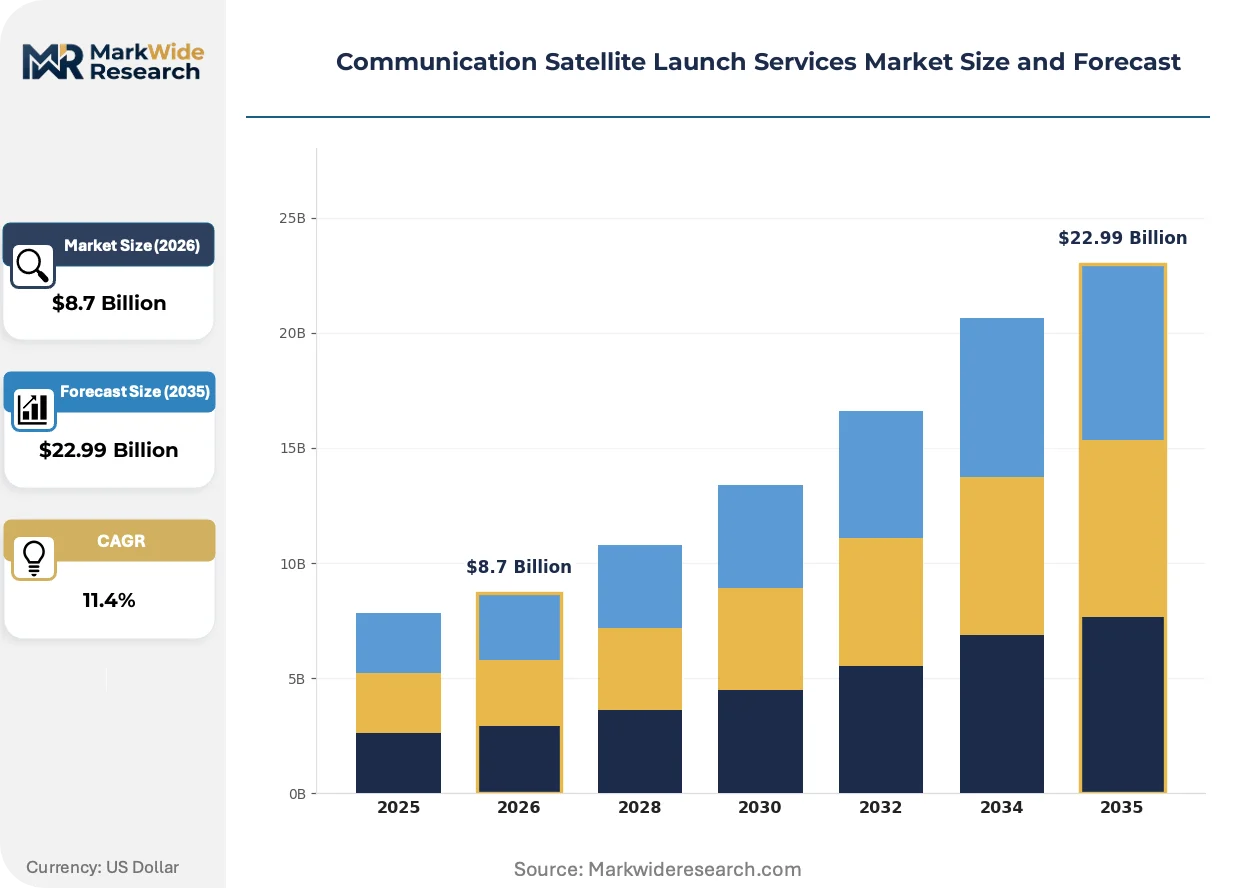
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Launch Vehicle Type: Expendable, Reusable, Solid Propellant, Liquid Propellant, Hybrid Propellant Orbit Type: Geostationary, Low Earth Orbit, Medium Earth Orbit, Sun-Synchronous, Highly Elliptical Orbit Customer Type: Telecom Operators, Government Agencies, Broadcasting Companies, Military Organizations, Research Institutions Service Model: Dedicated Launch, Rideshare Launch, Secondary Payload, Virtual Launch, Commercial Contract |
| Companies Covered | SpaceX, United Launch Alliance, Arianespace, Northrop Grumman, Blue Origin, Rocket Lab, ISRO, China Great Wall Industry Corporation, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Satellite Launch Services Market Trends and Innovations
Launch service architecture is bifurcating between mass-manufactured reusable systems and specialized heavy-lift vehicles, with downstream effects on payload integration workflows and customer contracting terms.
Staged-combustion liquid oxygen-methane engines are rewriting thermal efficiency benchmarks for orbital insertion. Small-constellation operators are adopting these propulsion systems for dedicated missions that require precise inclination control. The technology is rewriting the trade-off between payload mass and mission flexibility that previously favored kerosene architectures.
EU debris mitigation standards under the Space Surveillance and Tracking framework are mandating post-mission disposal timelines and collision-avoidance system certification. Commercial operators are reconfiguring satellite bus designs to meet these requirements. The regulation is reshaping manifest priority for rideshare missions where non-compliant payloads face exclusion.
Telecom procurement teams are consolidating multi-launch contracts into annual block buys with performance guarantees replacing per-mission payments. Satellite operators in North America and Europe are driving this shift to secure capacity commitments and stabilize unit economics. The model is compressing vendor sales cycles while elevating technical service requirements for mission assurance documentation.
Communication Satellite Launch Services Market Segmentation
Launch service procurement varies sharply by payload mass, orbital destination, and mission assurance requirements. Segment-specific capital intensity determines vendor specialization and contract pricing structures across the value chain.
Launch Vehicle Type:
Propulsion architecture dictates upfront development costs and per-flight economics. Liquid oxygen-methane systems require the heaviest R&D investment but offer the steepest cost reduction curves.
- Expendable:Single-use vehicles with heritage kerosene or hydrogen-oxygen stages carry the majority of geostationary telecom payloads where mass-to-orbit requirements exceed reusable margins. Demand concentrates among operators launching heavy broadcast satellites from Cape Canaveral and Kourou, constrained by insurance underwriting rigidity for unproven alternatives.
- Reusable:Propulsive first-stage recovery extends vehicle life and enables price competition that expands addressable customer segments. SpaceX Falcon 9 dominates commercial rideshare missions from Florida and California, though refurbishment cycles create manifest bottlenecks during high-tempo launch windows.
- Solid Propellant:Cast grain motors offer launch-on-demand responsiveness for national security payloads. India's PSLV and Japan's Epsilon serve polar orbit insertion with minimal pad turnaround.
- Liquid Propellant:Staged-combustion engines deliver precise orbital insertion for constellation deployment. Blue Origin BE-4 and SpaceX Raptor rewrite thermal efficiency benchmarks.
- Hybrid Propellant:Combined solid-liquid systems reduce ground handling complexity. Virgin Orbit's air-launch architecture targeted responsive small-satellite markets before restructuring.
Most installed capacity flows through Expendable vehicles. Expansion is steepest in Reusable systems.
Orbit Type:
Altitude and inclination requirements segment addressable demand by payload mass, radiation tolerance, and ground station architecture.
- Geostationary:Fixed orbital position at 35,786 kilometers enables continuous regional coverage for direct-to-home broadcasting. SES and Intelsat procurement teams anchor demand from French Guiana and Florida launch complexes, though slot coordination with the ITU extends lead times.
- Low Earth Orbit:Constellation operators demand frequent, standardized injection schedules for broadband internet coverage. Starlink and OneWeb drive rideshare manifest priority from Vandenberg and New Zealand, compressing procurement cycles through annual block buys.
- Medium Earth Orbit:Intermediate altitude balances coverage footprint with latency for navigation augmentation. O3b mPOWER satellites launch on Ariane 6 and Falcon Heavy.
- Sun-Synchronous:Polar inclination enables consistent solar illumination for Earth observation payloads. ISRO's Satish Dhawan Space Centre serves this orbit from Sriharikota.
- Highly Elliptical Orbit:Extended apogee dwell time supports high-latitude communications. Russian Molniya heritage informs current military applications.
Geostationary missions retain the highest per-launch revenue. Low Earth Orbit deployment volumes are climbing the fastest.
Customer Type:
End-user risk tolerance and mission assurance protocols fragment pricing structures and vertical integration requirements.
- Telecom Operators:Constellation builders and geostationary incumbents prioritize unit cost reduction through multi-launch procurement. Eutelsat and Telesat consolidate annual capacity commitments to stabilize satellite replacement schedules.
- Government Agencies:Civil space programs anchor demand for heavy-lift capability and deep-space trajectories. NASA Artemis and ESA science missions require human-rating certification that commercial providers cannot yet match.
- Broadcasting Companies:Regional media groups purchase dedicated slots for direct-to-home television distribution. Latin American and Southeast Asian broadcasters drive demand for customized coverage footprints.
- Military Organizations:Assured access mandates command premium pricing due to encryption requirements and launch site security protocols. US Space Force multi-year procurement commitments create predictable revenue streams for certified vehicles.
- Research Institutions:University and laboratory payloads rideshare on commercial missions with relaxed schedule constraints. CubeSat deployers from Caltech and TU Berlin access orbit through standardized dispensers.
Military Organizations generate the highest margin per launch. Telecom Operators drive the steepest expansion trajectory through constellation deployment.
Service Model:
Contract structure determines revenue recognition timing, technical service obligations, and customer switching costs.
- Dedicated Launch:Exclusive vehicle allocation for single-payload missions with precise orbital requirements. National security and interplanetary probes demand this model from United Launch Alliance and Arianespace.
- Rideshare Launch:Standardized dispenser systems aggregate multiple small satellites on common orbital planes. SpaceX Transporter missions and ISRO PSLV commercial flights dominate this segment through manifest flexibility.
- Secondary Payload:Unused capacity on primary missions offers cost reduction for schedule-tolerant operators. Adapter rings from Spaceflight Industries and Exolaunch broker these opportunities.
- Virtual Launch:Software-defined manifest coordination matches payload requirements with available capacity across provider networks. Momentus and other in-space transportation companies intermediate these transactions.
- Commercial Contract:Multi-mission framework agreements with performance guarantees replace per-flight payments. Amazon Kuiper procurement teams negotiated this structure with Blue Origin and Arianespace for constellation deployment.
Commercial Contracts capture the largest committed revenue. Rideshare Launch volumes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized propulsion engineering talent concentrates in Southern California, Alabama, and Texas, anchoring United States launch capacity. French Guiana's equatorial position and Sriharikota's Eastern Hemisphere access complete a three-pole geography.
United States
Space Force procurement commitments and Starlink constellation deployment anchor demand from Cape Canaveral and Vandenberg. FAA Office of Commercial Space Transportation streamlines licensing for large constellations. Hawthorne, California hosts vertical integration of reusable vehicle manufacturing alongside McGregor, Texas test facilities.
France
Ariane 6 qualification and Kourou's equatorial launch site sustain European heavy-lift capacity for geostationary telecom payloads. ESA's Space Surveillance and Tracking framework mandates debris mitigation compliance timelines. Toulouse and Paris-Saclay clusters concentrate avionics and propulsion engineering expertise.
India
IN-SPACe liberalization opens Satish Dhawan Space Centre to private launch providers for polar and equatorial missions. ISRO's commercial arm Antrix brokers rideshare capacity on PSLV and GSLV vehicles. Sriharikota's Eastern coastline enables cost-effective launches to Sun-synchronous orbits for Earth observation constellations.
China
China Great Wall Industry Corporation markets Long March vehicles for commercial telecom satellite deployment. MIIT coordinates spectrum allocation and launch licensing through national space planning frameworks. Xichang and Jiuquan launch centers support domestic constellation programs with standardized injection schedules.
New Zealand
Rocket Lab's Mahia Peninsula facility anchors dedicated small-launch capacity for constellation operators requiring precise orbital insertion. New Zealand's geographic isolation enables flexible launch azimuths without populated area overflight constraints. Auckland and Christchurch clusters support avionics integration and payload processing workflows.
Communication Satellite Launch Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across launch service procurement. The vendor base stratifies around three archetypes: vertically integrated aerospace conglomerates with defense heritage, commercial pure-plays built on reusable architectures, and state-affiliated providers with national security mandates. Consolidation pressure intensifies as constellation operators demand multi-year capacity commitments. Strategic moves center on reusable vehicle certification and Eastern Hemisphere launch site acquisition.
Among United States-based providers, SpaceX exemplifies the commercial pure-play archetype through Falcon 9 rideshare dominance. United Launch Alliance occupies the mission-assurance tier serving national security payloads. Arianespace represents European state-affiliated consolidation with Ariane 6 heavy-lift positioning.
| Leading Market Players |
|---|
| SpaceX |
| United Launch Alliance |
| Arianespace |
| Northrop Grumman |
| Blue Origin |
| Rocket Lab |
| ISRO |
| China Great Wall Industry Corporation |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
FCC debris mitigation mandates gate qualified supply access and premium-tier pricing eligibility for launch service procurement. Operators demonstrating compliant post-mission disposal capabilities command mission assurance premiums from military and interplanetary customers, while non-certified providers compete on price for commercial rideshare manifests.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes dedicated launch contracts from rideshare offerings. Pricing stratifies across mission assurance tiers, with encryption requirements and vertical integration protocols differentiating military premiums from commercial economy rates. Cost compression in commercial rideshare segments is intensifying because SpaceX Transporter missions standardize dispenser interfaces. Telecom constellation builders exhibit highest price sensitivity, while national security buyers prioritize reliability over unit cost.
Supply Chain Analysis
Regional distribution centers for liquid oxygen and RP-1 propellant concentrate along Gulf Coast refining corridors. Engine turbopump manufacturing draws from Southern California, Alabama, and Texas engineering clusters. Raw material dependencies include aerospace-grade aluminum-lithium alloys, Inconel superalloys, and high-purity cryogenic fluids. Single-source vulnerability for staged-combustion engine castings from specialized foundries poses structural risk. Distribution runs through captive vertical integration at Hawthorne and Decatur production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Communication satellite launch services constitute a late-cycle quality story as constellation operators shift procurement toward flight-proven reliability and debris compliance certification. Premium specifications now dominate multi-year block buy negotiations.
For Market Incumbents: To counter reusable vehicle price erosion from SpaceX Falcon 9 dominance, United Launch Alliance and Arianespace should deepen backward integration into solid rocket motor production and secure Eastern Hemisphere launch site access through partnership with India's IN-SPACe framework. Certification investment in liquid oxygen-methane architectures preserves optionality for next-generation competition. For New Entrants and Emerging Players: Capture underserved demand from small constellation operators requiring precise inclination control outside SpaceX's standardized orbital planes. Rocket Lab's dedicated Electron capacity demonstrates penetrability in responsive launch segments. Go-to-market positioning should emphasize polar orbit insertion capabilities and accelerated manifest flexibility versus rideshare schedule constraints. For Investors and Strategic Acquirers: Roll-up economics work for specialized propulsion engineering firms because liquid oxygen-methane turbopump talent scarcity concentrates in geographically clustered labor markets. Long-term viability favors acquisition targets with demonstrated reusable vehicle recovery and refurbishment workflows. Watch FCC licensing backlog clearance as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Vehicle Certification | Flight-proven recovery protocols unlock military assured-access contracts and premium pricing tiers. |
| Eastern Hemisphere Launch Site Acquisition | India's IN-SPACe liberalization creates alternative polar and equatorial access corridors for constellation deployment. |
| Debris Mitigation Compliance Investment | Post-mission disposal certification gates manifest priority under FCC streamlined licensing frameworks. |
| Liquid Oxygen-Methane Engine Development | Staged-combustion architectures rewrite thermal efficiency benchmarks and reduce per-kilogram payload economics. |
| Multi-Year Block Buy Contracting | Annual capacity commitments from Amazon Kuiper and Starlink stabilize vendor revenue recognition and unit economics. |
Research Methodology
Bottom-up constellation operator demand modeling reconciled against top-down launch vehicle supply tracking forms the analytical core of this study. Primary interviews with launch procurement directors at telecom operators, mission assurance officers at military organizations, and range safety coordinators at FAA-licensed spaceports combined with secondary validation from FCC licensing databases, ESA launch manifests, and ISRO commercial deployment records. Triangulation across stakeholder inputs and regulatory filings ensures coverage of classified national security demand and transparent commercial procurement.
Historical trendline analysis of launch frequency, payload mass distribution, and per-kilogram pricing trajectories established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include orbit type, vehicle propulsion architecture, customer risk tolerance tier, and service model structure. CAGRs derive from curve-fitting observed deployment schedules against constellation completion targets. Forecast inputs incorporate FCC spectrum coordination timelines and Ariane 6 qualification milestones.
Launch site congestion, propellant supply disruption, and debris regulation stringency are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding reusable vehicle refurbishment cycle efficiency and insurance underwriting adaptation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
UAE Satellite Communication Market
Satellite
France Satellite Imagery Services Market
Satellite
Africa Satellite Connectivity Market
Satellite
Germany Satellite Communications Market
Satellite
China Satellite Imagery Services Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
North America Satellite Manufacturing Market
Satellite
Russia Satellite Communications Market
Satellite
Satellite Connectivity Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
United States Satellite Communications Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Satellite Transponder Market
Satellite
Israel Satellite Imagery Services Market