
 North America Satellite Attitude and Orbit Control System Market | 2026-2036
North America Satellite Attitude and Orbit Control System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Satellite Attitude and Orbit Control System Market Insights
Electro-optical hybrid sensing is reshaping how satellite attitude determination architectures integrate star trackers with MEMS gyroscopes. The Boeing Company leverages vertical integration across spacecraft bus manufacturing to capture downstream AOCS value. Honeywell International Inc. sustains technology leadership in precision inertial reference units for geostationary missions. Moog Inc. specializes in propulsion-integrated control systems that dominate smallsat reaction control segments.
Satellite attitude and orbit control systems comprise sensor suites, actuators, and control algorithms that maintain spacecraft orientation and orbital position through closed-loop feedback, typically achieving pointing accuracy within arc-seconds for Earth observation payloads. Their primary commercial purpose is to stabilize platforms for uninterrupted payload operations across varying orbital regimes. Reaction control systems and star trackers anchor the product mix, with reaction control systems commanding the largest revenue share due to recurring propellant and thruster replacement cycles. Autonomous systems represent the fastest-expanding technology segment as operators seek to reduce ground-segment dependency and latency in constellation management.
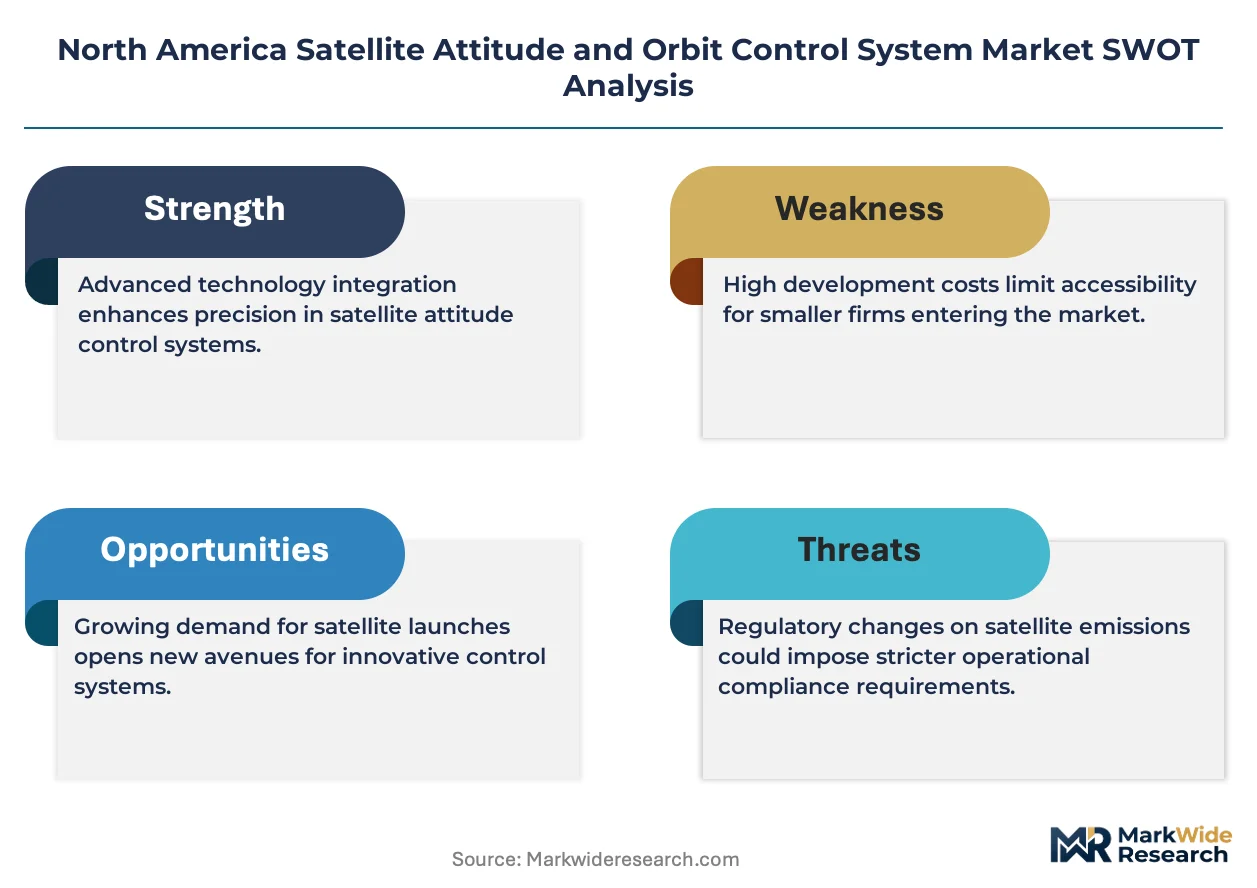
The FAA's updated orbital debris mitigation requirements and NASA's technical standards for spacecraft reliability are tightening qualification thresholds for AOCS components, particularly for commercial launch licensing. The U.S. Space Force's emphasis on rapid reconstitution and responsive space architectures is redirecting procurement toward modular, software-defined control systems with shorter development cycles. Stakeholders must weigh the trade-off between heritage component qualification and the agility of newer autonomous architectures when positioning for upcoming constellation replenishment contracts.
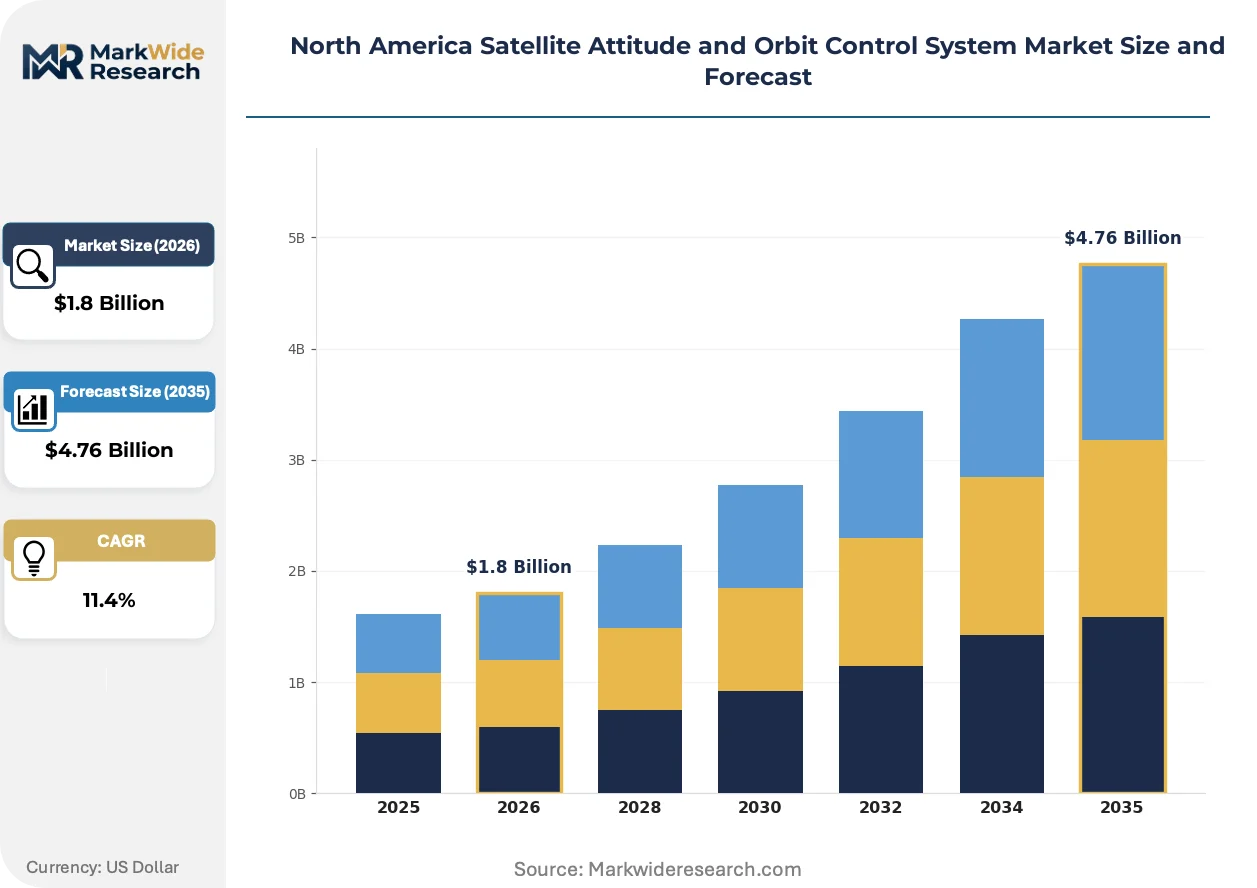
Market Dynamics
LEO constellation operators are compressing procurement cycles for miniaturized attitude control systems, forcing incumbent vendors to abandon heritage qualification timelines in favor of modular, software-defined architectures that match Space Force responsive space mandates.
Growth Catalysts
- LEO Constellation Deployment:Commercial operators are fielding hundreds of small satellites requiring mass-producible AOCS components, creating sustained demand for reaction control systems and star tracker miniaturization.
- FAA Orbital Debris Mitigation Standards:Updated licensing requirements mandate autonomous collision-avoidance capabilities, compelling vendors to integrate predictive maneuvering algorithms into standard product offerings.
- California Aerospace Cluster Concentration:Prime contractors co-located with Space Force and NASA facilities in Los Angeles and Silicon Valley accelerate technology transfer and joint development programs.
Market Restraints
- Rare Earth Magnet Supply Concentration:Torque rod and reaction wheel manufacturers face input cost volatility due to dependence on Chinese-processed neodymium and dysprosium for precision magnetic actuators.
- Heritage Component Lock-In:Geostationary satellite operators demand flight-proven inertial reference units with 15-plus-year operational histories, freezing out newer MEMS-based alternatives regardless of performance metrics.
- NASA Technical Standard Rigor:Reliability qualification protocols for commercial crew and cargo missions impose 18-to-24-month certification timelines that mismatch constellation deployment schedules.
Strategic Opportunities
- Software-Defined Control Architectures:Modular AOCS designs enabling in-orbit algorithm updates via ground uplink are capturing interest from operators seeking to extend satellite operational lifespans without hardware replacement.
- Mexican Manufacturing Expansion:Lower-cost precision machining capabilities in Baja California and Querétaro offer nearshoring alternatives for reaction wheel housings and sensor mounting structures serving U.S. prime contractors.
- Space Force Rapid Reconstitution Mandates:Responsive space procurement frameworks prioritize vendors with sub-12-month delivery capabilities, rewarding domestic suppliers with accelerated qualification pathways.
Industry Challenges
- GNC Software Talent Scarcity:Guidance, navigation, and control firmware developers with spacecraft-specific expertise command premium compensation in California and Colorado, constraining vendor scaling.
- Propulsion-AOCS Integration Complexity:Small satellite operators demand combined attitude and orbital maneuvering systems, forcing hardware suppliers to master chemical thruster, electric propulsion, and cold gas architectures simultaneously.
- ITAR Compliance Burden:Export control classification for precision gyroscopes and star trackers creates documentation overhead that delays international sales cycles and diverts engineering resources from product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Satellite Attitude and Orbit Control System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reaction Control System, Gyroscopes, Star Trackers, Sensors Application: Earth Observation, Communication, Scientific Research, Navigation End User: Government Agencies, Commercial Operators, Defense Entities, Research Institutions Technology: Active Control, Passive Control, Hybrid Control, Autonomous Systems |
| Companies Covered | The Boeing Company, The Lockheed Martin Corporation, Honeywell International Inc., Maxar Technologies Inc., Moog Inc., Northrop Grumman Corporation, Blue Canyon Technologies LLC, Millennium Space Systems Inc., L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Satellite Attitude and Orbit Control System Market Trends and Innovations
Electro-optical hybrid sensing architectures are compressing the boundary between star tracker precision and MEMS gyroscope affordability, reshaping how attitude determination systems are specified across orbital regimes.
Star tracker technology is migrating from discrete, high-cost units toward fused electro-optical systems that combine CMOS imagers with compact fiber-optic gyroscopes. Small satellite constellation operators are adopting these integrated packages at volume scale for LEO missions. This convergence is migrating from premium geostationary platforms toward commodity smallsat buses, collapsing the traditional price-performance hierarchy between mission classes.
The FAA's updated Part 450 commercial space licensing framework imposes explicit orbital debris mitigation obligations on launch vehicle and spacecraft operators alike. These rules require demonstrated post-mission disposal and collision avoidance maneuvering capability as conditions for license issuance. Commercial remote sensing constellations are responding by embedding autonomous conjunction assessment modules directly into AOCS flight software rather than relying on ground-segment processing.
Constellation operators are unbundling traditional integrated AOCS procurement into component-level sourcing with separate algorithm development contracts. This disaggregation permits mixing heritage sensor hardware from established vendors with internally developed control laws and third-party flight software. The practice is most visible among Earth observation startups in California and Washington state seeking to preserve engineering control over pointing accuracy specifications while outsourcing manufacturing risk.
North America Satellite Attitude and Orbit Control System Market Segmentation
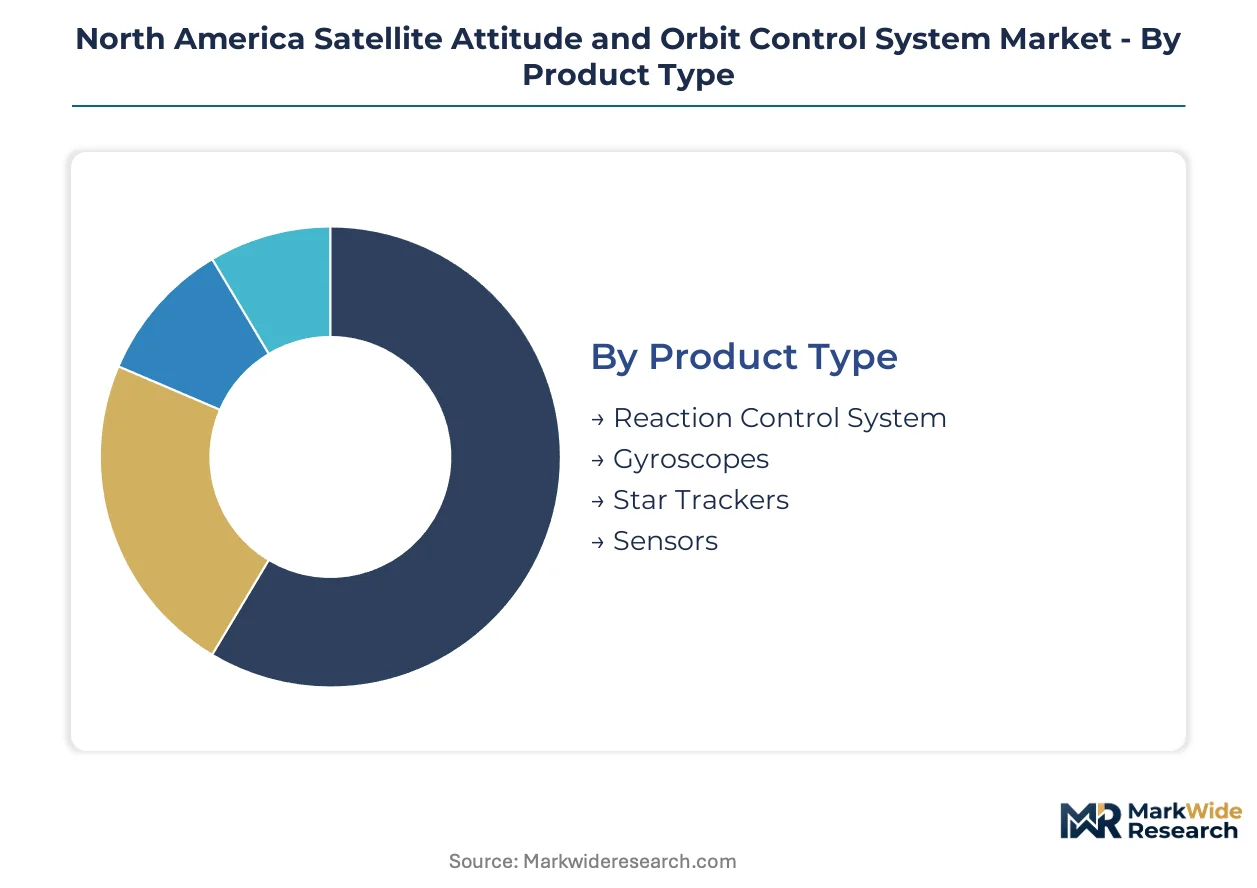
AOCS procurement patterns diverge sharply across mission profiles, with constellation operators prioritizing miniaturized reaction control systems while geostationary platforms demand precision inertial units. Understanding these segment boundaries reveals where technology substitution is accelerating versus where heritage qualification still governs purchasing decisions.
Product Type:
Use-case spectrum spans disposable smallsat thrusters to precision stellar reference units for decade-long geostationary missions.
- Reaction Control System:Thruster clusters and propellant management hardware dominate procurement volumes for LEO constellations requiring frequent station-keeping and deorbit maneuvers. California-based commercial operators are compressing supplier lead times for these systems to match rapid constellation deployment schedules.
- Star Trackers:Electro-optical attitude reference units achieve arc-second pointing accuracy for Earth observation payloads. Demand concentrates in Colorado and California aerospace corridors where prime contractors integrate these with onboard processing for autonomous navigation.
- Gyroscopes:MEMS-based rate sensors serve small satellite buses; fiber-optic variants anchor geostationary missions.
- Sensors:Magnetometers, sun sensors, and Earth horizon detectors provide redundant attitude data for fault-tolerant architectures.
Established volume favors reaction control systems; emerging adoption favors star tracker miniaturization for smallsat platforms.
Application:
Cost tier differentiation separates premium geostationary communication payloads from commodity Earth observation buses.
- Earth Observation:Commercial remote sensing constellations in LEO drive demand for compact, low-power AOCS with rapid revisit pointing agility. FAA orbital debris rules are mandating autonomous collision-avoidance capabilities in flight software for these missions.
- Communication:Geostationary relay satellites and emerging LEO broadband constellations require ultra-stable pointing for uninterrupted link budgets. Space Force rapid reconstitution mandates are pushing vendors toward modular designs with shortened qualification cycles.
- Scientific Research:Precision pointing for astrophysics and heliophysics missions demands heritage-proven inertial reference units.
- Navigation:GPS augmentation and alternative PNT satellites prioritize timing synchronization alongside attitude control.
Revenue concentration sits with communication; steepest expansion trajectory belongs to Earth observation constellations.
End User:
Customer type determines procurement rigor, from NASA technical standards to commercial operator cost optimization.
- Government Agencies:NASA and NOAA missions impose 18-to-24-month qualification timelines for crew-rated reliability. These programs sustain demand for flight-proven component architectures with extensive on-orbit heritage.
- Commercial Operators:LEO constellation ventures prioritize software-defined AOCS with in-orbit update capability over hardware redundancy. Space Force responsive space frameworks are accelerating vendor qualification for domestic suppliers meeting sub-12-month delivery windows.
- Defense Entities:Classified missions drive demand for radiation-hardened components with ITAR-controlled supply chains.
- Research Institutions:University and nonprofit CubeSat programs seek commercial off-the-shelf AOCS at minimized cost points.
Procurement volume centers on commercial operators; technology innovation investment concentrates in government agency programs.
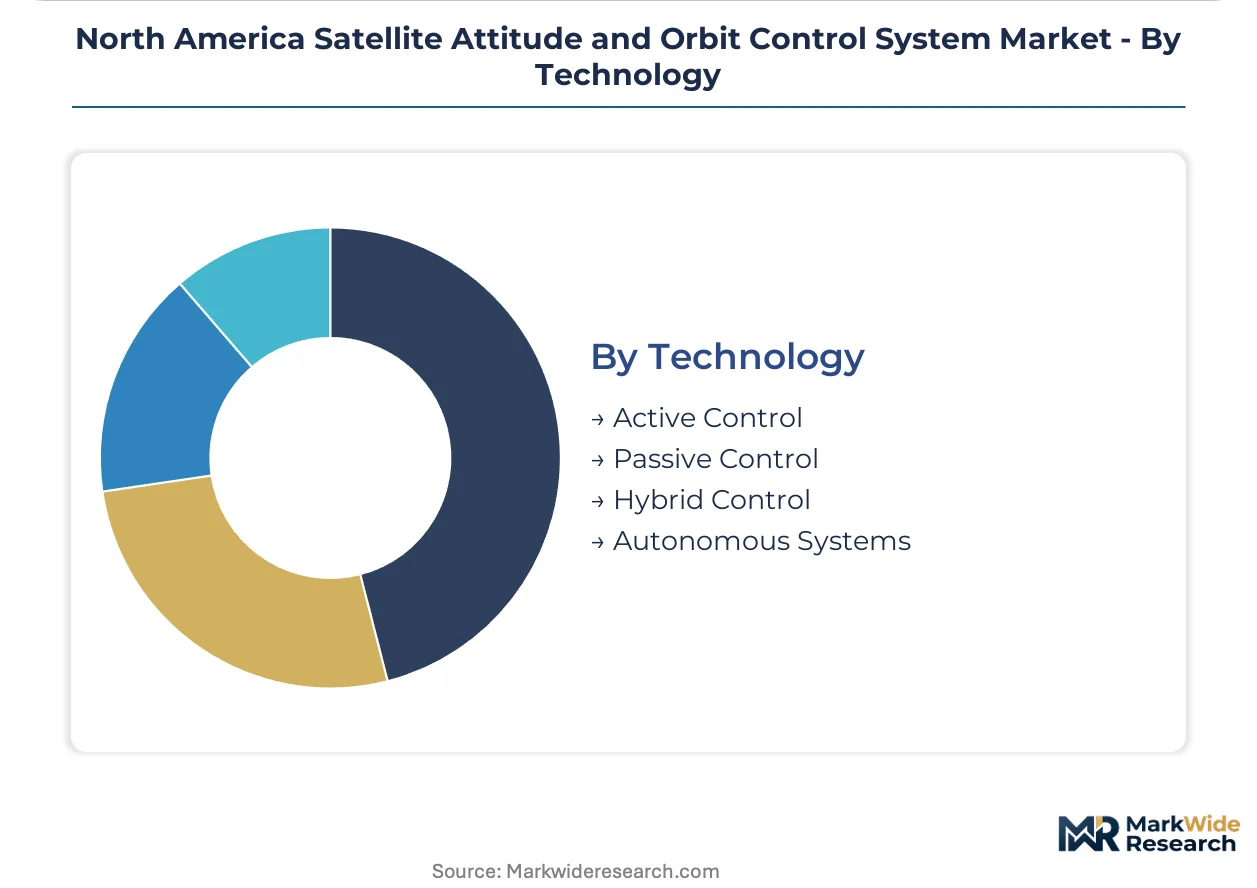
Technology:
Maturity gradient separates heritage passive damping from emerging autonomous maneuvering architectures.
- Autonomous Systems:Self-directed conjunction assessment and collision-avoidance maneuvering embed directly into flight software, eliminating ground-segment latency. FAA Part 450 licensing requirements are making these capabilities standard for commercial remote sensing constellations.
- Hybrid Control:Fused electro-optical and inertial sensing architectures combine MEMS gyroscope affordability with star tracker precision. These systems are gaining share fastest among small satellite operators seeking to collapse the traditional price-performance hierarchy between mission classes.
- Active Control:Closed-loop feedback with reaction wheels and torque rods remains standard for three-axis stabilized platforms.
- Passive Control:Gravity-gradient booms and magnetic hysteresis dampers serve simplest CubeSat missions with minimal pointing requirements.
Heritage deployment favors active control; capability expansion favors autonomous systems with predictive maneuvering algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prime contractors and constellation operators concentrate procurement decisions in three distinct North American jurisdictions, each shaped by defense spending patterns, commercial launch density, and cross-border manufacturing integration.
United States
California's aerospace corridor generates concentrated demand for miniaturized AOCS components as Space Force and NASA facilities drive rapid technology transfer. FAA Part 450 licensing mandates autonomous collision-avoidance capabilities for commercial remote sensing missions. Los Angeles and Silicon Valley host prime contractor clusters where Boeing, Lockheed Martin, and Northrop Grumman co-locate engineering teams with government customers.
Canada
Robotic space systems and satellite servicing missions anchor Canadian demand for precision pointing and proximity operations control. The Canadian Space Agency funds technology development through its Space Technology Development Program. Ontario and Quebec host specialized suppliers serving U.S. prime contractors under ITAR-compliant supply agreements.
Mexico
Nearshoring momentum builds in Baja California and Querétaro as U.S. manufacturers seek lower-cost precision machining for reaction wheel housings and sensor structures. Mexican aerospace clusters benefit from proximity to California's integration facilities without full ITAR transfer requirements. The federal government's Proyecto México Espacial initiative supports supplier capability development for satellite component manufacturing.
North America Satellite Attitude and Orbit Control System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure consolidates around vertically integrated spacecraft bus manufacturers and specialized component suppliers serving constellation operators. Three archetypes dominate: prime contractors capturing downstream AOCS value through captive production, precision inertial specialists defending heritage positions in geostationary missions, and emerging smallsat-focused vendors exploiting modular software-defined architectures. Competitive moves center on strategic partnerships for rapid qualification pathways and geographic expansion into Mexican nearshoring zones.
Among U.S.-based prime contractors, The Boeing Company and The Lockheed Martin Corporation occupy positions as channel-controlling integrators with captive AOCS development capabilities. Honeywell International Inc. exemplifies the heritage specialist archetype, while Moog Inc. anchors the propulsion-integrated control segment for small satellite applications.
| Leading Market Players |
|---|
| The Boeing Company |
| The Lockheed Martin Corporation |
| Honeywell International Inc. |
| Maxar Technologies Inc. |
| Moog Inc. |
| Northrop Grumman Corporation |
| Blue Canyon Technologies LLC |
| Millennium Space Systems Inc. |
| L3Harris Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Chinese-processed neodymium and dysprosium concentration anchors input cost volatility for torque rod and reaction wheel manufacturers, compressing margin pools at the precision magnetic actuator tier while downstream system integrators capture value through software-defined control architectures.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate procurement for heritage inertial reference units, while fixed-price agreements govern volume reaction control system orders from constellation operators. Price differentiation rests on flight heritage certification tier and ITAR compliance status. Cost compression in MEMS-based alternatives is intensifying because commercial operators prioritize software-defined architectures over hardware redundancy. LEO constellation ventures exhibit highest price sensitivity; geostationary communication satellite operators demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Contract manufacturing for sensor housings and reaction wheel structures concentrates in Baja California and Querétaro, with secondary capacity in Ontario and Colorado. The supply chain draws from Chinese-processed rare earth magnets, U.S.-fabricated fiber-optic gyroscope coils, and Canadian-precision machined aluminum housings. Single-source vulnerability in neodymium supply creates tariff exposure risk. Distribution runs through prime contractor integration facilities in California's aerospace corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as constellation operators unbundle integrated AOCS procurement into component-level sourcing with interoperable software interfaces, creating ecosystem lock-in opportunities for vendors mastering modular control architectures.
For Market Incumbents: Build switching-cost moats through software-defined control architectures with in-orbit update capability. Honeywell International Inc. and Moog Inc. should deepen backward integration into radiation-hardened processor supply to defend against emerging smallsat-focused vendors exploiting modular open standards. FAA Part 450 compliance investment serves as the priority lever for maintaining prime contractor channel control. For New Entrants and Emerging Players: Establish a beachhead in Mexican nearshoring corridors for precision machining of reaction wheel housings and sensor structures. Blue Canyon Technologies LLC and Millennium Space Systems Inc. demonstrate viable paths through Space Force rapid reconstitution procurement frameworks rewarding sub-12-month delivery capabilities. White-space concentration sits with autonomous collision-avoidance flight software for commercial remote sensing constellations. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined AOCS specialists with demonstrated in-orbit algorithm update capabilities and ITAR-compliant supply chains. Long-term viability favors vendors bridging heritage component qualification with responsive space delivery mandates. The signal to monitor is Space Force accelerated qualification pathway awards as inflection indicator for contract flow timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Development | Enables in-orbit algorithm updates extending satellite operational lifespans without hardware replacement. |
| Mexican Manufacturing Footprint Expansion | Captures lower-cost precision machining capacity in Baja California serving U.S. prime contractor integration. |
| Autonomous Collision-Avoidance Integration | Addresses FAA Part 450 licensing mandates for commercial remote sensing constellation operators. |
| Rare Earth Supply Chain Diversification | Mitigates input cost volatility from Chinese-processed neodymium and dysprosium dependencies. |
| Space Force Rapid Qualification Pathway | Accelerates vendor certification for responsive space procurement frameworks prioritizing sub-12-month delivery. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with AOCS engineering directors, constellation program managers, Space Force procurement officers, and FAA licensing specialists; and secondary validation against NASA technical standards documentation, SEC filings from prime contractors, and Space Force budget justification materials. Bottom-up triangulation across component-level procurement data and top-down validation through spacecraft bus production forecasts anchored volume estimates.
Forecast inputs span orbital regime segmentation, mission class differentiation, and technology maturity curves across autonomous, hybrid, and active control architectures. Modeled dimensions include product type, application, end user, and technology tier. CAGRs were derived through regression analysis of historical procurement patterns and projected constellation deployment schedules. Industry-specific inputs incorporate FAA regulatory timeline assumptions and Space Force responsive space funding trajectories.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations, rare earth commodity prices, or commercial launch cadence would shift the trajectory. Forecasts reflect documented assumptions regarding constellation deployment rates and regulatory implementation timing. Quarterly review of Space Force procurement awards and FAA licensing issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Remote Sensing Services Market
Satellite
Nanosatellite Market
Satellite
Global Dish Antennas Market
Satellite
Satellite Antenna Market
Satellite
Communication Satellite Launch Services Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Global Satellite Modem Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Earth Observation Satellite Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Commercial LEO Satellite Market
Satellite
Satellite Market
Satellite
Satellite Broadband Market
Satellite
Israel Satellite Communications Market
Satellite
Satellite Communication System Market
Satellite
South Korea Satellite Connectivity Market