
 Satellite Communication System Market | 2026-2036
Satellite Communication System Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication System Market Analytics
The performance gap between radiation-hardened military-grade transponders and commercial off-the-shelf broadband payloads is broadening, splitting procurement budgets into two distinct supply chains with diverging qualification standards and vendor pools. Intelsat leverages its geostationary fleet heritage to anchor premium enterprise and government contracts requiring guaranteed service-level agreements. SpaceX competes on manufacturing scale, driving unit economics down through vertically integrated Starship production and in-house semiconductor fabrication for user terminals. Iridium Communications specializes in narrowband mobility services, sustaining its pole position in cross-linked LEO constellations for aviation and maritime safety applications.
A satellite communication system comprises ground stations, space-based relay platforms, and user terminals engineered to operate across allocated frequency bands—typically C-band, Ku-band, Ka-band, and emerging Q/V bands—employing modulation schemes and antenna architectures matched to orbital altitude and link budget constraints. These systems enable long-haul data transmission where terrestrial infrastructure proves uneconomical or physically impossible, serving defense coordination, commercial broadband extension, and environmental monitoring missions. Low Earth Orbit satellites now command the fastest expansion trajectory as operators deploy dense constellations for low-latency consumer broadband, while geostationary platforms retain margin concentration in video distribution and enterprise trunking where dwell time and coverage stability justify premium pricing. Military end users represent a structurally distinct demand pool with classified procurement channels and hardened specification requirements that insulate incumbent suppliers from commercial price erosion.
The FCC governs spectrum licensing and orbital debris mitigation rules for U.S.-registered operators, directly conditioning market access and constellation deployment timelines. EASA and national aviation regulators in France, Germany, and the United Kingdom impose terminal certification standards for in-flight connectivity, shaping supplier qualification burdens across European airframes. ITU coordination procedures for frequency filings create first-mover advantages that incumbent geostationary operators exploit to defend orbital slots against LEO newcomers. Stakeholders must track how national security designations for space infrastructure redirect procurement toward domestic supply chains and away from foreign-owned constellation services.
Market Dynamics
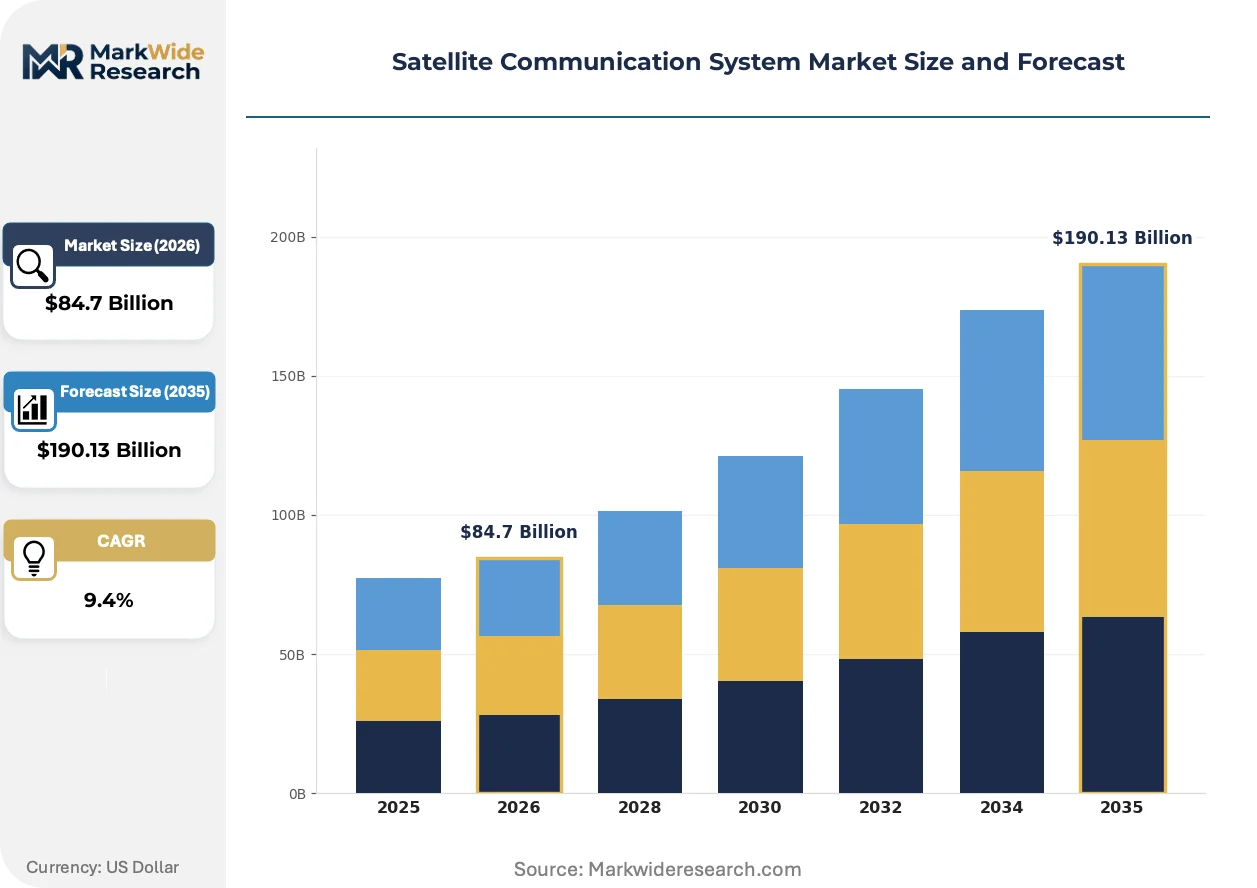
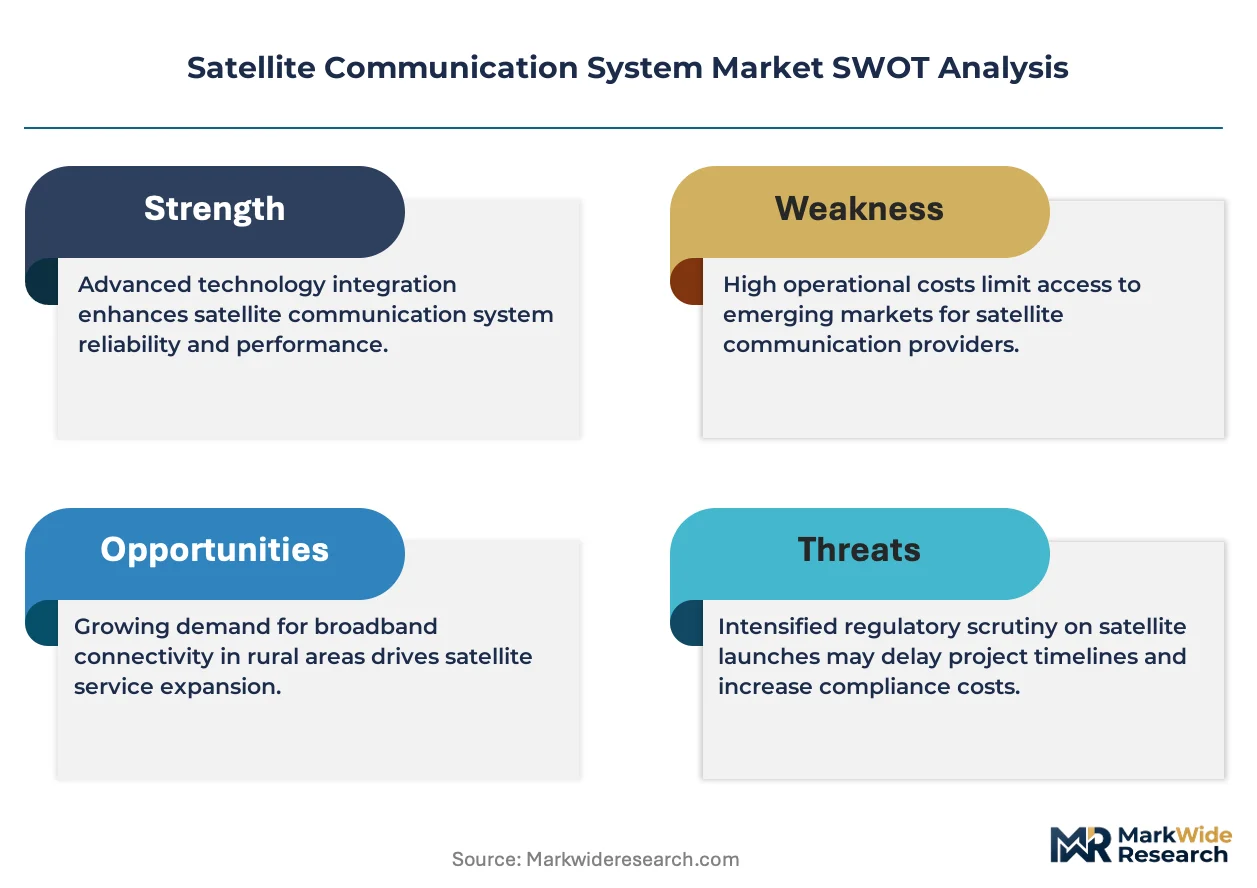
The split between radiation-hardened military transponders and commercial broadband payloads is bifurcating procurement channels, creating parallel supply chains with incompatible qualification standards and vendor ecosystems.
Growth Catalysts
- LEO Constellation Density:Dense orbital deployments for low-latency consumer broadband are pulling demand for phased-array user terminals and ground station infrastructure.
- NATO Secure Terminal Procurement:Military procurement acceleration across member states is generating dedicated funding streams for classified satcom programs with hardened specification requirements.
- FCC Spectrum Reallocation:Updated allocation rules for non-geostationary orbit systems are redrawing competitive boundaries and accelerating deployment timelines for new entrants.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet dependencies for Hall-effect thrusters concentrate in limited supplier geographies, creating propulsion system bottlenecks.
- ITU Coordination Backlogs:International Telecommunication Union frequency filing procedures create multi-year delays that incumbent geostationary operators exploit to defend orbital slots.
- Launch Cost Stickiness:Despite reusability advances, per-kilogram launch economics remain prohibitive for small operators without dedicated ride-share agreements.
Strategic Opportunities
- Aviation Safety Mandates:EASA and national aviation regulators in France, Germany, and the United Kingdom are imposing terminal certification standards that favor qualified narrowband providers for cockpit connectivity.
- Q/V Band Spectrum:Emerging frequency allocations above Ka-band offer terabit-scale throughput potential for next-generation high-throughput satellites.
- Maritime Regulatory Compliance:International Maritime Organization safety mandates are expanding addressable demand for cross-linked LEO constellations in commercial shipping lanes.
Industry Challenges
- Radiation-Hardened Semiconductor Talent:Design expertise for space-grade integrated circuits concentrates at a handful of defense contractors and national laboratories, constraining payload development velocity.
- Orbital Debris Mitigation Compliance:Post-mission disposal and collision avoidance system requirements are extending development cycles and inflating non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication System Market |
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $190.13 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Geostationary Satellites, Low Earth Orbit Satellites, Medium Earth Orbit Satellites, Active Relay Satellites Service Type: Broadband Services, Broadcasting Services, Mobile Services, Data Services Application: Aerospace Communication, Maritime Communication, Remote Sensing, Disaster Management End User: Government, Commercial, Military, Telecommunications |
| Companies Covered | Intelsat, SES S.A., Viasat Inc., SpaceX, Eutelsat Communications, Telesat, Iridium Communications, Inmarsat Global Limited, Hughes Network Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication System Market Evolving Landscape
Electronically steered antenna architectures are compressing terminal form factors while software-defined payloads are decoupling hardware from service flexibility, enabling operators to reconfigure coverage patterns without launching replacement spacecraft.
Optical inter-satellite links are electrifying constellation mesh architectures by replacing radio-frequency crosslinks with laser-based data pipes. Maritime and aviation operators are adopting these terminals fastest, driven by latency-sensitive command-and-control requirements. The technology is electrifying competitive positioning among LEO operators by eliminating ground gateway dependencies for polar coverage.
The FCC's updated orbital debris mitigation rules are tightening post-mission disposal timelines and collision avoidance system mandates. Operators must now demonstrate passivation capabilities and tracking transparency before license grant. Small satellite constellations registered in the United States face the steepest compliance cost escalations, prompting some to consider foreign flag registries.
Defense procurement patterns are consolidating around indefinite-delivery indefinite-quantity vehicles with multi-year performance periods. Prime contractors are displacing fragmented subsystem vendors by integrating payload, bus, and ground segment capabilities under single award mechanisms. This concentration is most visible in classified programs near Washington D.C. and Redmond, Washington manufacturing corridors.
Satellite Communication System Market Segmentation
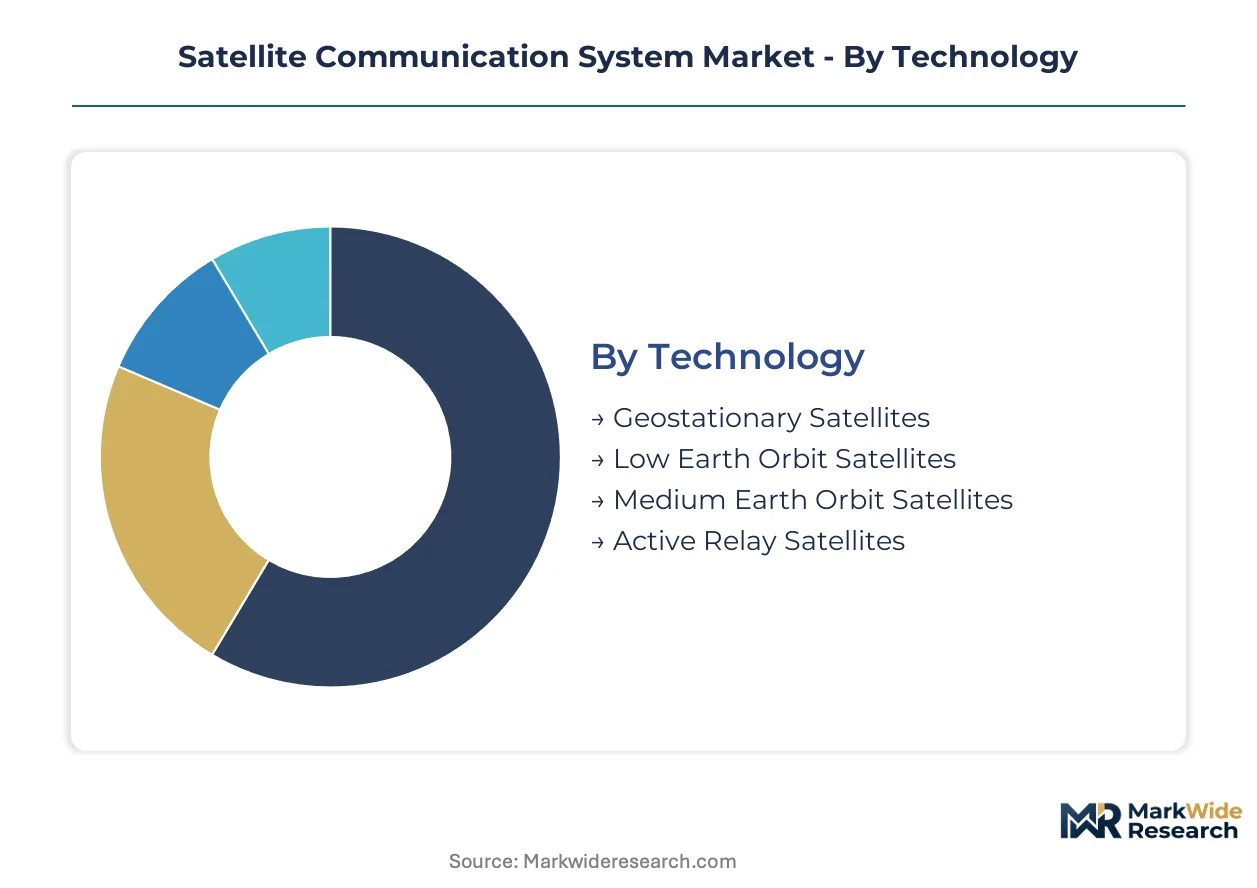
Satellite communication systems fragment across orbital architectures, service modalities, and procurement channels that dictate entirely different vendor ecosystems and qualification standards. Each segmentation axis reveals distinct margin structures, regulatory exposures, and technology roadmaps that shape competitive positioning.
Technology:
Orbital altitude determines latency budgets, coverage footprints, and manufacturing scale economics that separate incumbent suppliers from emerging constellation operators.
- Geostationary Satellites:Stationary orbital slots at 35,786 kilometers enable continuous regional coverage with single-satellite architectures. Demand concentrates with broadcasters and enterprise trunking customers in the United States and Europe where dwell-time stability justifies premium transponder leases.
- Low Earth Orbit Satellites:Dense constellations below 2,000 kilometers deliver sub-50 millisecond latency for consumer broadband and mobility applications. Procurement is accelerating near Redmond, Washington and government contracting corridors around Washington D.C. as operators scale manufacturing.
- Medium Earth Orbit Satellites:Intermediate altitude platforms balance coverage swath with latency performance for navigation augmentation and specialized broadband.
- Active Relay Satellites:Regenerative payload architectures with onboard processing enable flexible routing independent of ground gateway availability.
Volume sits with geostationary platforms; growth tilts toward low earth orbit constellations.
Service Type:
Service modality separates high-volume consumer subscriptions from mission-critical contracts with hardened performance guarantees and classified procurement channels.
- Broadband Services:High-throughput data delivery for consumer, enterprise, and government subscribers via dedicated spot beams. Demand is climbing fastest in aviation and maritime mobility segments where terrestrial alternatives remain unavailable.
- Broadcasting Services:Video distribution and content relay with guaranteed availability for media networks. Procurement concentrates with legacy geostationary operators anchoring premium enterprise contracts.
- Mobile Services:Narrowband voice and data for handheld terminals in remote terrain.
- Data Services:Machine-to-machine telemetry and backhaul for IoT and industrial monitoring.
Revenue concentrates in broadband; expansion tilts toward mobile services as aviation safety mandates proliferate.
Application:
Application context determines terminal specification, regulatory certification burden, and whether procurement flows through commercial or classified channels.
- Aerospace Communication:In-flight connectivity and cockpit safety communications for commercial and military aircraft. EASA and national aviation regulators in France, Germany, and the United Kingdom impose terminal certification standards that favor qualified narrowband providers.
- Maritime Communication:Ship-to-shore data and safety compliance for commercial shipping and naval fleets. International Maritime Organization mandates are expanding addressable demand for cross-linked LEO constellations in major shipping lanes.
- Remote Sensing:Earth observation data relay and command uplink for imaging constellations.
- Disaster Management:Emergency communications restoration and coordination for humanitarian and government response agencies.
Procurement volume sits with aerospace; steepest expansion trajectory belongs to maritime as regulatory compliance deadlines approach.
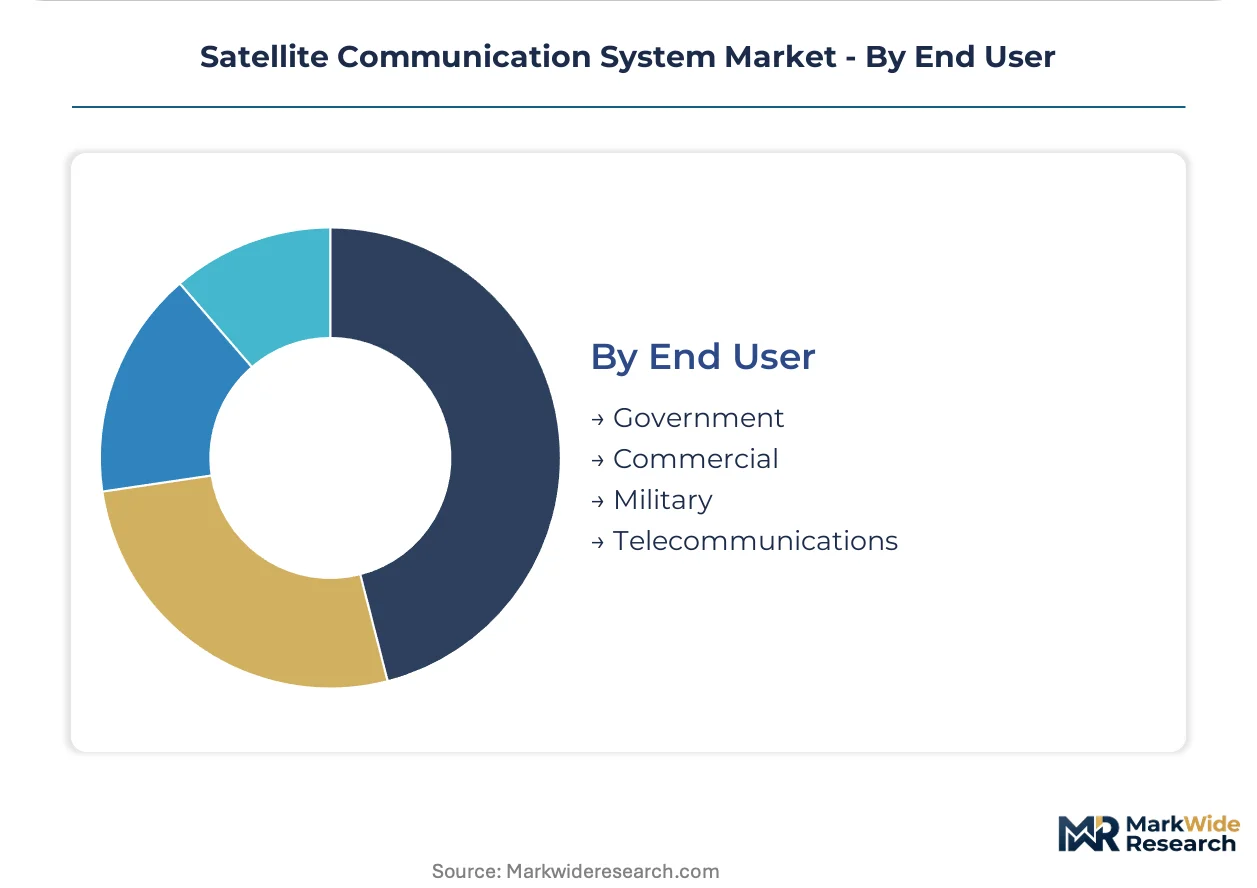
End User:
End-user classification splits the market between price-sensitive commercial subscribers and procurement channels insulated from cost competition by national security designation.
- Government:Civilian agency communications, environmental monitoring, and diplomatic secure networks. FCC spectrum licensing and orbital debris mitigation rules condition deployment timelines for U.S.-registered operators serving federal contracts.
- Military:Classified satcom programs with radiation-hardened specification requirements and indefinite-delivery indefinite-quantity procurement vehicles. NATO member states are accelerating secure terminal procurement with dedicated funding streams.
- Commercial:Enterprise broadband, media distribution, and consumer internet services.
- Telecommunications:Carrier backhaul and network extension for mobile operators.
Spending scale sits with commercial subscribers; margin concentration tilts toward military as procurement consolidates around integrated prime contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Redmond, Washington anchors the most concentrated satellite manufacturing corridor in North America, with vertically integrated production facilities feeding both commercial broadband constellations and classified government programs. Washington D.C. and its surrounding Virginia and Maryland suburbs host the densest cluster of defense procurement offices and satellite services contractors. Demand patterns diverge sharply between these commercial manufacturing hubs and the security-cleared contracting corridors that handle military satcom procurement.
United States
The FCC governs spectrum licensing and orbital debris mitigation rules that directly condition constellation deployment timelines for U.S.-registered operators. Washington D.C., northern Virginia, and suburban Maryland corridors concentrate defense procurement offices awarding indefinite-delivery indefinite-quantity contracts for secure terminals. SpaceX operates its Starlink manufacturing hub in Redmond, Washington, scaling phased-array terminal production through in-house semiconductor fabrication.
France
Eutelsat maintains its geostationary fleet operations from Paris while EASA imposes terminal certification standards for in-flight connectivity across European airframes. The country's national space agency, CNES, coordinates with ITU filing procedures that incumbent operators exploit to defend orbital slots. Toulouse and Paris host the primary satellite manufacturing and services clusters serving both broadcast and enterprise trunking customers.
Germany
The KBA and national aviation regulators impose equipment certification burdens that shape supplier qualification for cockpit connectivity systems. Munich and Stuttgart concentrate precision manufacturing capabilities for ground station components and user terminal subsystems. German automotive and industrial conglomerates are expanding demand for machine-to-machine satellite backhaul in remote manufacturing facilities.
United Kingdom
Inmarsat operates its global maritime safety services from London while the UK Space Agency coordinates national frequency filings with ITU coordination procedures. Harwell and the Westcott Space Cluster in Buckinghamshire host emerging satellite manufacturing and propulsion testing facilities. British defense procurement is accelerating secure terminal programs through NATO-aligned funding mechanisms.
Japan
METI oversees national space industrial policy while the country's national telecommunications regulator manages spectrum allocation for non-geostationary systems. Tokyo and Tsukuba concentrate satellite services headquarters and space technology research institutes. Japanese shipping conglomerates are expanding fleet-wide adoption of cross-linked LEO constellation terminals to meet International Maritime Organization safety compliance deadlines.
Satellite Communication System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification-tier boundaries, with radiation-hardened military specification vendors commanding structurally insulated pricing while commercial broadband operators compete on manufacturing scale. The vendor base separates into heritage geostationary operators defending orbital slots, vertically integrated LEO constellation builders, and narrowband mobility specialists. Three archetypes dominate: integrated prime contractors capturing classified procurement, scale manufacturers driving unit economics down, and specialized narrowband providers anchoring safety-critical applications. Competitive moves concentrate on strategic partnerships for launch access and backward integration into semiconductor fabrication for terminal cost reduction.
Within the heritage geostationary tier, Intelsat and SES S.A. exemplify operators leveraging fleet continuity to anchor premium enterprise contracts requiring guaranteed service-level agreements. SpaceX occupies a distinct position as a vertically integrated constellation builder combining Starship production with captive terminal manufacturing. Iridium Communications represents the narrowband mobility archetype, sustaining competitive positioning through cross-linked LEO architecture specialization for aviation and maritime safety applications.
| Leading Market Players |
|---|
| Intelsat |
| SES S.A. |
| Viasat Inc. |
| SpaceX |
| Eutelsat Communications |
| Telesat |
| Iridium Communications |
| Inmarsat Global Limited |
| Hughes Network Systems |
| Others |
Value Network & Pricing Analysis
Electronically steered antenna architectures and software-defined payloads are compressing manufacturing costs while concentrating production in vertically integrated facilities near Redmond, Washington and government contracting corridors around Washington D.C. This dual-track production geography simultaneously enables scale economies for commercial broadband terminals and insulates premium military-grade supply chains from price erosion.
Pricing Analysis
Service-level agreement guarantees anchor value-based pricing for geostationary operators serving enterprise and government contracts, while subscription-tiered models dominate consumer broadband from LEO constellations. Price differentiation hinges on certification grade—radiation-hardened military specifications command structural premiums versus commercial off-the-shelf payloads—and volume scale from dense constellation deployments. Cost compression in consumer broadband terminals is intensifying because SpaceX's captive semiconductor fabrication and Starship production integration undercut legacy supplier cost structures. Commercial subscribers exhibit highest price sensitivity; military procurement channels remain least sensitive due to classified specification requirements and indefinite-delivery indefinite-quantity contract vehicles.
Supply Chain Analysis
Domestic-content mandates in U.S. defense procurement are reshaping sourcing toward American-flagged operators and away from foreign-owned constellation services. Manufacturing concentrates in the United States, France, and Germany—Redmond anchors terminal production, Toulouse hosts geostationary fleet operations, and Munich concentrates ground station components. Raw material dependencies center on rare earth magnets for Hall-effect thrusters, compound semiconductors for phased-array antennas, and radiation-hardened integrated circuits. Single-source vulnerability in permanent magnet supply creates propulsion system bottlenecks. Distribution runs through prime contractor integration for military programs and direct-to-consumer channels for broadband subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FCC orbital debris mitigation compliance is forcing smaller constellation operators toward foreign flag registries or acquisition exits as non-recurring engineering costs escalate.
For Market Incumbents: Anchor premium positioning through guaranteed service-level agreements for geostationary enterprise contracts while accelerating backward integration into semiconductor fabrication for terminal cost control. Defend against SpaceX's manufacturing scale by deepening certification barriers for aviation and maritime safety applications where EASA and IMO mandates favor qualified incumbents. For New Entrants and Emerging Players: Narrowband mobility specialists serving cockpit connectivity and maritime safety compliance represent the most penetrable buyer archetype underserved by broadband-focused LEO operators. Target aviation terminals in European airframes and commercial shipping fleets facing International Maritime Organization mandate deadlines. Pursue qualification-first go-to-market strategies that front-load regulatory certification investment before manufacturing scale. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of specialized narrowband providers and cross-linked LEO constellation operators with aviation-maritime certification moats. Long-term viability favors vertically integrated players with captive launch access and in-house terminal production. Watch ITU frequency filing resolution timelines as inflection indicator for competitive positioning shifts between incumbent geostationary defenders and LEO newcomers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive phased-array chip production enables SpaceX to undercut legacy terminal suppliers on unit economics. |
| Aviation Terminal Certification Investment | EASA mandates in France, Germany, and the United Kingdom favor qualified providers for cockpit connectivity contracts. |
| Prime Contractor Consolidation | Defense procurement near Washington D.C. displaces fragmented subsystem vendors through integrated award mechanisms. |
| Optical Inter-Satellite Link Deployment | Laser-based crosslinks eliminate ground gateway dependencies for polar coverage in maritime and aviation segments. |
| Foreign Flag Registry Migration | Small satellite operators facing FCC debris compliance costs seek alternative national licensing jurisdictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this satellite communication system market assessment. Primary interviews with constellation program directors, defense procurement officers, ground station engineers, and aviation certification specialists combined with FCC licensing databases, ITU frequency coordination filings, EASA airworthiness directives, and SEC contractor disclosures. Bottom-up unit economics from terminal manufacturing and top-down addressable market sizing were triangulated for convergence validation.
Segmentation granularity modeled orbital altitude, service modality, application context, and end-user classification across the projection horizon. CAGRs derived from deployment timeline trajectories for LEO constellation density, military procurement acceleration patterns, and regulatory compliance cost escalations. Forecast inputs incorporated Starship production ramp assumptions, rare earth magnet supply constraints, and ITU coordination backlog resolution scenarios.
Revisions become necessary when FCC orbital debris rule amendments, NATO procurement funding reallocations, or launch cost discontinuities materialize outside modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Operation Service Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
GEO Satellite Market
Satellite
Satellite Payload Market
Satellite
Medium and Large Satellite Market
Satellite
Earth Observation Satellite Market
Satellite
Global Small Satellite Service Market
Satellite
Canada Satellite Connectivity Market
Satellite
Europe Satellite Connectivity Market
Satellite
Satellite Internet Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Commercial LEO Satellite Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
France Satellite-Based Earth Observation Market